




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


PC Magazine | By Rob Marvin | May 19, 2016

In Part One of our explainer on the government-regulated crowdfunding investment space, we talked about how businesses and investors should navigate the now-regulated crowdfunding landscape.
Entrepreneurs and start-ups that have never had access to traditional venture capital funding can now raise up to $1 million through online Regulation Crowdfunding (Reg CF) portals, and middle-class non-accredited investors can contribute 5-10 percent of their income per year in Reg CF offerings, depending on their net worth.
But Reg CF is only one side of the equity crowdfunding coin, which also includes something known as Regulation A+ (Reg A+).
To start, equity crowdfunding means online investors actually get a stake in the start-up or SMB as opposed to traditional nonprofit crowdfunding platforms like Kickstarter and Indiegogo, which are easy ways to lose your money.
Reg CF and Reg A+ are part of the 2012 Jumpstart Our Business Startups (JOBS) Act, which has been reworked and updated over the past several years to address the crowdfunding economy and encourage new forms of protected, regulated start-up and SMB funding and investment. Reg CF is Title III and Reg A+, which went into effect in 2015, is Title IV.
"The entire purpose of Regulation Crowdfunding is to allow emerging companies to raise capital faster, cheaper, and more efficiently than ever before, and we are optimistic that over time, this will be prove to be the case," said Darren Marble, CEO of digital marketing agency CrowdfundX.
PCMag has a detailed explanation on how Reg A+ works and how accredited Reg A+ portals operate, but the gist is that compared to Reg CF, Reg A+ deals in higher funding amounts that are more tightly regulated.
Both regulations deal with unaccredited investors as opposed to traditional VC investors, private equity firms, and hedge funds. But Reg A+ requires full SEC approval of each offering (as opposed to formally notifying the SEC of a Reg CF offering), and two years' worth of audited financial data. Investors also have to self-certify their net worth before they can start putting money down.
Reg A+ has two funding tiers: Tier 1 caps the maximum amount a business can raise per year at $20 million and Tier 2 at $50 million. Funding portals must register separately with the SEC and FINRA as expressly Reg CF or Reg A+ marketplaces (though you can be both). There are no limits on how much individuals can invest in Tier 1 offerings, but Tier 2 investments are limited to a maximum of either 10 percent of the investor's net worth or net income, whichever is higher.
Rod Turner, founder and CEO of approved Reg A+ crowdfunding portal Manhattan Street Capital (MSC) said Reg CF is more like a traditional seed round, while Reg A+ fills the role of a much heftier Series A, B, or C funding round. There are no restrictions stating a company can't raise a Reg CF round this year, and a Reg A+ round a year or two later.
"Title III is essentially seed financing; you don't need wealthy friends and relatives, you don't need access to angel investors," said Turner. "[The regulation] is filling a great need both from companies that had no real chance because of their geography, and for smaller businesses looking to raise an amount too small for VCs or angel investors to consider. With Title III you can be in podunk nowhere and as long as you market your product well and it's appealing to consumers, you can raise capital."
MSC measures Reg A+ statistics monthly. Its latest report found that the number of mid-stage companies and mature start-ups adopting Regulation A+ funding is currently at approximately 116, with the aggregate capital of all those intended raises adding up to $1.9 billion, up from $1.2 billion in January.
To get a sense of the vast difference in scale between Reg CF and Reg A+, look no further than Mark Cuban. Speaking recently at the Salt Conference, the entrepreneur, investor, and Shark Tank host told attendees at the hedge fund summit that Reg A+ is a huge opportunity to counter Silicon Valley VC culture with a new way for businesses to raise significant capital.
"The SEC has Reg A+, which simplifies the paperwork for [a] $25 million or $50 million offering. These rules with Reg A+ have just been crystallized recently and there is a huge opportunity and I've been talking to folks about creating a fund that says the goal is to invest in [a] start-up, but part of the effort is we're going to try to take them public within four to five years," Cuban said, according to The Street.
Most coverage of the new crowdfunding regulations has focused on start-ups and entrepreneurs, but in a way that misses the point. A hot new start-up with innovative tech or a great-looking growth forecast can always court traditional VC investment. The companies that can really benefit from the comparatively small investment limits of Reg CF are under-the-radar small businesses that have been around a while, have a stable business plan, and just need that extra push
Jeff Koeppel, Of Counsel with the Law Offices of Kirk Halpin & Associates, P.A, advises public and private companies on private equity and debt issuances, corporate governance, contracts, deal structuring, joint ventures, and other corporate and securities matters. He said as this space matures, Regulation Crowdfunding will be particularly helpful to mature small businesses with a financial track record and a solid local presence seeking to raise a small amount of capital. Maybe it's hiring new employees or expanding to new local retail locations, or maybe a manufacturer wants to expand the factory floor or buy new equipment.
"These are the folks whose bank line of credit was cancelled in the last financial downturn or who don't want to pay the rate being charged. It may be a local music store, dry cleaner, or even an auto repair shop that just needs a few hundred thousand dollars to open a store in another neighborhood," said Koeppel, who also spent three years at the SEC as a Senior Attorney-Advisor in the Division of Corporation Finance.
Koeppel pointed to a British crowdfunding site called Crowdcube as a good example of how this kind of equity crowdfunding should work. Crowdcube took advantage of UK crowdfunding regulations to introduce something called The Burrito Bond, which helped Mexican restaurant chain Chilango expand to more locations in London. The Reg CF-like offering paid investors 8 percent interest over four years, and raised more than £2 million.
Crowdcheck CEO Sara Hanks agreed that local small businesses have the most to gain. Crowdcheck is a due diligence, disclosure, and compliance firm for online funding and investment, and Hanks is also a corporate and securities attorney with experience at several law firms as well as the SEC. The firm does due diligence and compliance filing for both Reg CF and Reg A+ offerings.
As laid out in Part One, established SMBs may also be in a better position to handle the upfront costs and recurring fees arising from accounting and legal due diligence and financial reviews. "I see Regulation CF as being helpful for 'Main Street' type businesses that find it very hard to get funding, and yet could provide meaningful job growth and economic activity if only they could grow," said Hanks.

The National Crowdfunding Association of Canada (NCFA Canada) is a cross-Canada non-profit actively engaged with both social and investment crowdfunding stakeholders across the country. NCFA Canada provides education, research, leadership, support and networking opportunities to over 1300+ members and works closely with industry, government, academia, community and eco-system partners and affiliates to create a strong and vibrant crowdfunding industry in Canada. Learn more at ncfacanada.org.
Competition Bureau | May 19, 2016

Crowdfund Insider | | May 17, 2016
 Monday, May 16, 2016 is the first day that ordinary people—not just the super rich—will be able to invest in the next Uber or Snapchat. That’s because Title III of the JOBS Act, otherwise known as Regulation Crowdfunding or Reg CF, legalizes retail investment crowdfunding that day. This new regulation will open up the investor pool to over 300 million potential investors and aims to spur the growth of small businesses.
In April 2012, President Barack Obama signed into law the Jumpstart Our Business Startups Act, or JOBS Act. The JOBS Act was so called because it aimed to facilitate access to capital for startups and small businesses, give more people the ability to participate in investment opportunities, and ultimately, create more jobs and stimulate economic growth. While other crowdfunding regulations from the JOBS Act, such as Title II and IV, were implemented more quickly, Title III is the third but most anticipated piece of crowdfunding regulation to become effective.
For the first time, Title III will allow issuers to raise funds online from ordinary people for investment purposes. The regulation creates a new exemption to the Securities Act of 1933. This essentially means that, for the first time since being written 80 years ago, our securities laws will be updated to recognize modern modes of online capital raising.
Previously, generally only accredited investors could invest in early stage startups. Accredited investors are those who earn an annual income of at least $200,000 (or $300,000 if married), or those with a net worth of at least $1M (excluding one’s primary residence).
You might argue that crowdfunding has been around for years now, which is true. Crowdfunding is essentially the act of raising capital from others via the Internet. Platforms like Kickstarter, IndieGogo, and GoFundMe have been around since at least 2008 and have given us the Pebble Watch, Veronica Mars, and every gadget imaginable. However, these portals practice rewards-based crowdfunding, or in the case of GoFundMe, donation-based crowdfunding. When backers give a crowdfunding campaign money, they either make a donation or get back a “reward”—maybe a thank you note, or the first edition of said widget.
Title III expands the possibilities to include investment crowdfunding, or the ability to buy equity in an early stage company and hopefully reap a monetary return on investment. On May 16, ordinary Americans don’t need to settle for just a Pebble watch (though that would be a great additional perk); instead, they can own a piece of the company that makes the Pebble watch. Title III democratizes access to startup investment opportunities, while greatly expanding the pool of available capital to small businesses and startups. And while the crowd may not replace angel investors and venture capital, they may now invest alongside them.
Issuers, or those looking to raise funds, should know the following basics about Title III:
Title III is historic in that it specifically recognizes a new type of intermediary for crowdfunding transactions, called a funding portal. At least 30 applications for funding portals have been received as of April, with likely many more to come. Funding portals are essentially modern online connectors between issuer companies and investors and amongst investors, and these platforms will be regulated by the SEC and FINRA.
Despite high hopes around a vibrant Title III crowdfunding industry, Title III may encounter some turbulence at takeoff following its May 16 debut. Although it took the SEC three and a half years to issue the final rules on Title III, regulators were said to be scrambling in the final days of the regulatory process to get the final rules out. And in doing so, the final rules came out short of optimal and, in the opinion of some, not workable.
Critics point out that the SEC’s final rules on Title III do just the opposite of its regulatory intent. That is, instead of creating a mechanism that would allow attractive startups to include retail investors, the SEC’s zealous concerns over small investor protection resulted in unrealistically high regulatory burdens that would disincentivize any company from using the regulation, except as a last resort. And that’s the opposite of what small investors should want to invest in—the companies otherwise rejected by accredited investors.
One of the major concerns around Title III is the high transaction costs required to raise $1M. Issuers will find themselves with bills in the tens of thousands of dollars right out of the gate to pay for legal and accounting services—and will then have to spend at least a couple thousand dollars after fundraising to comply with ongoing reporting requirements. Several industry experts have publicly criticized the final rules, including OneVest/1000 Angels co-founder and Chairman Alejandro Cremades who issued an open letter condemning Title III and publicly stating that his company would stay “far away” from utilizing the regulation.
Even with low cost solutions like iDisclose and Crowdcheck, the upfront costs to conduct financial audits—before an issuer may even determine whether it will be able to raise financing at all—is a gamble.
And issuers must all the while acknowledge the likelihood that its campaign will fail. If we take lessons from analogous models, Kickstarter has a 36% success rate for fully funded campaigns, while AngelList has testified that less than 10% of companies that list on its platform succeed in a raise. Some platforms that lean towards “listing” rather than “curating” may find that very few campaigns overall will reach their funding goal. Issuers will want to ensure that they surround themselves with good advisors and counsel, and to associate themselves with well-performing funding portals, or else they may find themselves in the red if they’ve raised less money than needed to even cover transaction costs.
 Currently, Congressman McHenry has introduced proposed legislation called the Fix Crowdfunding Act (HR 4855) that has yet to be voted on by the House or Senate. The amendment fixes a number of issues with Title III to make it more workable, if approved and implemented. HR 4855 makes the following changes:
Testing the Waters
Issuers would be able to solicit interest prior to actually spending money on lawyers and accountants. Given that companies must brace themselves for the scenario in which they cannot cover transaction costs or loss money as a result of not having raised enough funds, the ability to gauge investor interest up front may save a number of issuers from being in the red on day one (and may encourage other companies to boldly steam forward).
Raising the Funding Cap From $1M to $5M
In his open letter, Cremades wrote “Nowadays startups on average raise, at a Seed stage, in the neighborhood of $2M+. The fact that startups will have a limit of $1M per year will either force them to be under capitalized or conduct another type of offering in parallel to raise the remaining capital from accredited investors, which means more costs from a legal perspective.” Raising the funding cap to $5M would make the transaction costs more justifiable and allow companies to raise the capital they need.
The National Crowdfunding Association of Canada (NCFA Canada) is a cross-Canada non-profit actively engaged with both social and investment crowdfunding stakeholders across the country. NCFA Canada provides education, research, leadership, support and networking opportunities to over 1300+ members and works closely with industry, government, academia, community and eco-system partners and affiliates to create a strong and vibrant crowdfunding industry in Canada. Learn more at ncfacanada.org.
BCSC |BC Notice 2016/03 | May 6, 2016
 Adoption of BC Instrument 72-505 Exemption from prospectus requirement for crowdfunding distributions to purchasers outside British Columbia
Today, the British Columbia Securities Commission adopted BC Instrument 72-505 Exemption from prospectus requirement for crowdfunding distributions to purchasers outside British Columbia (BCI 72-505). This instrument provides an exemption from the prospectus requirement to allow issuers located in British Columbia to distribute securities to purchasers outside British Columbia using Multilateral Instrument 45-108 Crowdfunding (MI 45-108), which has been adopted in a number of Canadian jurisdictions.
The key conditions of BCI 72-505 are:
BCI 72-505 expires on May 5, 2017. BCI 72-505 is a temporary exemption while Commission staff consider ways to more easily facilitate multi-jurisdictional crowdfunding.
You may refer questions to:
Elliott Mak
British Columbia Securities Commission
(604) 899-6501
(800) 373-6393 (toll-free across Canada)
May 6, 2016
Brenda M. Leong
Chair
Source: BCSC 72-505 May 6, 2016
The National Crowdfunding Association of Canada (NCFA Canada) is a cross-Canada non-profit actively engaged with both social and investment crowdfunding stakeholders across the country. NCFA Canada provides education, research, leadership, support and networking opportunities to over 1300+ members and works closely with industry, government, academia, community and eco-system partners and affiliates to create a strong and vibrant crowdfunding industry in Canada. Learn more at ncfacanada.org.


Crowdfunding for Business and IP Seminar
Investment Crowdfunding markets are rapidly evolving and democratizing the ability for startups and SMEs to access capital online with the US alternative finance market surging to $36 billion in 2015. On Jan 25-2016, the integrated crowdfunding exemption (multilateral 45-108) was enacted in 5 provinces (+SK pending) including Ontario. Boost your knowledge of the Crowdfunding industry and your ability to protect and advocate for your clients who are considering becoming a Crowdfunding investor, creating a business startup, or commencing a crowdfunding raise or portal. In this 2-hour seminar, you will gain a greater understanding of the crowdfunding rules and legislation implemented by the Ontario Securities Commission, along with information on available financing options, and a range of key business and intellectual property considerations.
Learn from the experts! Register now to take advantage of relevant and timely information that will help you and your clients navigate the quickly emerging and lucrative crowdfunding industry.
AGENDA
8:00 am Registration & Coffee and Refreshments
8:30 am Welcome and Opening Remarks
8:35 am Crowdfunding Financing Options
8:55 am Regulatory Perspectives
9:15 am Protecting Your Business, Investment and Portal
9:30 am Trademarks, Patents, Copyright and Privacy Rights
9:45 am Question and Answer Session
10:00 am Program Ends
Questions you can expect to be answered?
Speakers

RUBSUN HO, Chief Crowdpleaser, Crowdmatrix Inc.
Rubsun Ho is the Chief Crowdpleaser at Crowdmatrix Inc., an equity crowdfunding platform that will bring efficiency and transparency to the capital raising process for Canadian growth companies. A portfolio company of Extreme Venture Partners, Crowdmatrix plans to launch in late spring, 2015. Rubsun is also a co-founder and partner of Cognition LLP, a virtual law firm that was created to address the rising costs and inefficiencies of corporate legal services from traditional law firms. Cognition now has over 50 lawyers operating in Toronto, Ottawa and Calgary, and its clients range from growing startups through to some of Canada’s largest companies.

ZULF KARIM, Regional Head of Business Development, TSX Private Markets
Zulf Karim is the Head of Business Development at TSX Private Markets, a platform that provides access to the Canadian exempt market. It facilitates the raising of capital through brokered, private placement financings for both private and public companies and secondary trading of private company securities and public company "hold period" securities.
 ELIZABETH TOPP, Senior Legal Counsel, Compliance and Registration, OSC
GLORIA TSANG, Legal Counsel, Compliance and Registrant Regulation Branch, Ontario Securities Commission.
In her role as legal counsel, Gloria is responsible for advising on the registration regime in Ontario (National Instrument 31-103 Registration Requirements, Exemptions and Ongoing Registrant Obligations and related instruments) and for reviewing and making recommendations in response to applications for exemptions from registration requirements under the Securities Act (Ontario) and the Commodity Futures Act. Gloria also participates in reviews of registration applications and registrants to determine if they are in compliance with securities laws and acts as a legal resource on registration and compliance issues to other staff and industry participants. Gloria was part of the OSC team that worked with the other jurisdictions in the development of Multilateral Instrument 45-108 Crowdfunding. Gloria holds a law degree from the Queen’s University and is a member of CPA Ontario.
 JASON SALTZMAN, Partner, Dentons Canada LLP
Jason Saltzman practices corporate finance and securities law, with an emphasis on securities offerings, mergers and acquisitions, private equity and venture capital transactions, as well as all other aspects of corporate and securities law.Jason works with both established and emerging companies world-wide, primarily in the mining, technology, life science, cleantech (including renewable energy, water tech and ag tech), industrial, mid-tech and digital media and entertainment sectors. He assists issuers, investment dealers, and institutional and private investors on complex equity and debt financing transactions, ranging from start-up investments, venture capital and private equity investments, to larger public offerings and project finance.
 ANDREW CURRIER, Partner, PKCIP
Andrew is a recognized leader in intellectual property, combining experience in industry, law and academia before co-founding PCK. Andrew’s industry experience includes General Counsel for a publicly-traded flat-panel display company, IP counsel for a Silicon Valley start-up, and engineer for the automotive industry. In law, Andrew practised for several years with three of Canada’s national firms. In academia, Andrew held a teaching appointment as Adjunct Professor at Western University in London Ontario, teaching patent law from 2000-2007. Cited by the Supreme Court of Canada, he is also co-author (with Stephen Perry) of Canadian Patent Law (2nd ed. Butterworths, 2014) the first text on Canadian patent law by practitioners in over thirty years.
Why attend this seminar?
Who should attend this seminar?
Exclusive deal with purchase (bonus)
Attend this CPD Seminar and GET 25% Discount off our annual NCFA-EVP Rooftop Summer Kickoff Networking Event that takes place a week before the CPD course on Jun 1st from 5:30-9:00pm.
Network in style with investors and entrepreneurs passionate about crowdfunding, fintech, and alternative finance. It's an event you don't want to miss!
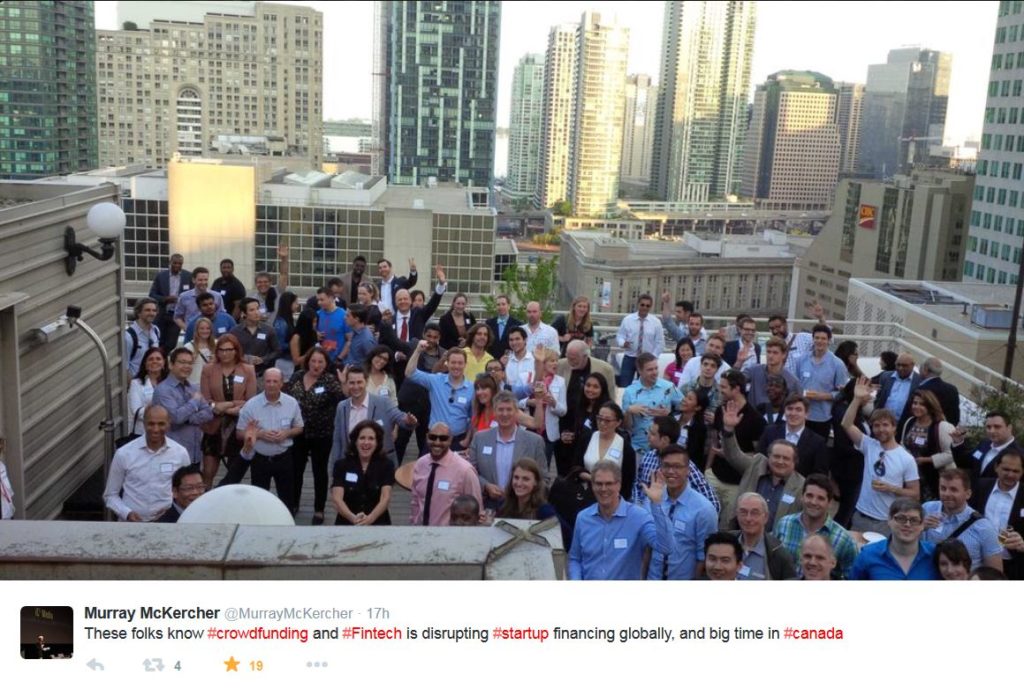
Early bird tickets available now...
The National Crowdfunding Association of Canada (NCFA Canada) is a cross-Canada non-profit actively engaged with both social and investment crowdfunding stakeholders across the country. NCFA Canada provides education, research, leadership, support and networking opportunities to over 1300+ members and works closely with industry, government, academia, community and eco-system partners and affiliates to create a strong and vibrant crowdfunding industry in Canada. Learn more at ncfacanada.org.
Crowdfund Insider | | May 3, 2016
 Two years after Title II of the JOBS Act, known as 506(c), went into effect well over one billion dollars of financings have been closed through online funding portals under this provision and 506(b).
The year over year growth has been substantial. Entrepreneurs and real estate professionals have benefited and so have investors. Even with all that activity so far, there has been very limited reported fraud- one maybe two at most, representing significantly less than 1% of the capital raised. This is not to suggest that there won’t be more and no doubt other legitimate investor losses as well, but online 506(b) and (c) has thus far delivered on the promise of an alternative way for entrepreneurs to raise capital, for investors to participate in opportunities not previously available to them, and equally importantly, for this not to become a regulatory burden.
The data suggests that nearly two thousand such entrepreneurs have received such funding, which inevitably creates jobs. The key being that the balance of interests between capital formation and investor protection (from fraud, not losses) has been more than satisfied so far. The voiced concern of overwhelming fraud has not materialized and regulators generally acknowledge this reality.
All crowdfunding constituents continue to need to remain vigilant and keep the problems limited. We all share this responsibility if we want to benefit from this considerable departure from old securities law conventions. Building on the strength of this new approach to permitting capital formation, May 16 of this year marks the date upon which the third provision relating to crowdfunding under the JOBS Act, Regulation CF, makes available unregistered investment opportunities to all Americans. This isn’t open to debate, it’s the law. You might be surprised at how many events that I attend where panelists and attendees continue to debate the issues as if we were still in a time warp prior to the JOBS Act enactment in 2012.
For all of the genuine concern, many of these folks have neither read the Regulation CF rules, don’t fully appreciate the construct of the statute and rules, nor care to recognize that these rules came to be after a bi-partisan congressional action, signed by the President and extensively considered and refined by both the SEC and FINRA after four years of comment letters by both supporters and detractors of the legislation have had full opportunity to share their comments.
As a participant and observer, I am proud of what Titles III Regulation III Crowdfunding represents, how thoughtful the final rules are, the care and consideration that the staff members of both the SEC and FINRA have put into making the final approved rules viable and the institutional restraint from being inflexible. Moreover, tremendous credit must be given to the perseverance of the industry and the individuals that stayed the course and engaged in the process- this truly was a crowdsourced effort.
- Doug Ellenoff is Managing Partner of Ellenoff Grossman & Schole LLP,
We are well aware that there are investor protection concerns and believe that the current rules are quite respectful of those interests. We are also aware that some market participants must make a more concerted effort to fully recognize that this is a highly regulated industry for good reason and their business processes must become more compliant in order to protect investors even better. Certainly, we also support continuing efforts to address aspects of the final rules which would make the final rules more commercially viable. If the securities activity that gets transacted after May 16 under Regulation CF is as responsibly undertaken by the online 506(b) and (c) community, then legislators will have the necessary momentum to take additional positive action beneficial to the industry.
The National Crowdfunding Association of Canada (NCFA Canada) is a cross-Canada non-profit actively engaged with both social and investment crowdfunding stakeholders across the country. NCFA Canada provides education, research, leadership, support and networking opportunities to over 1300+ members and works closely with industry, government, academia, community and eco-system partners and affiliates to create a strong and vibrant crowdfunding industry in Canada. Learn more at ncfacanada.org.
WSJ | Louise Lee | May 1, 2016

Equity crowdfunding promises to be a major new source of funding for small businesses. But some critics say it lacks a crucial element: a secondary market for most participating investors.
Under the Jumpstart Our Business Startups Act, startups can sell equity stakes online to small investors with limited resources. It’s a potentially huge opportunity for businesses that might fly under the radar of bigger backers.
Many observers, though, have pointed out a possible flaw in the setup: There isn’t an easy way for those equity investors to sell their shares to somebody else. Without a secondary market, the critics say, equity crowdfunding won’t take off and small businesses won’t be able to tap all that capital.
So far, the Securities and Exchange Commission hasn’t given the green light to a secondary market. Now Seth C. Oranburg, a visiting professor at Chicago-Kent College of Law, is pushing what he says is a way to jump-start the process: have crowdfunding portals hire analysts who would provide potential buyers with information about companies’ prospects and valuations. That way, he argues, a secondary market will be a much safer environment for unsophisticated small investors—and much more attractive for regulators to approve.
“The independent analyst is going to help people know what something is worth and make sure they’re selling it for the right price and buying it for the right price,” says Mr. Oranburg. “The SEC would hopefully permit a resale market to exist if they felt comfortable the private independent analyst would protect the resale investors.”
Although initial buyers also could benefit from analyst research, secondary buyers need that information even more, says Mr. Oranburg, whose paper on the topic will be published in a forthcoming issue of the Rutgers Law Journal. Under current laws, he says, secondary buyers don’t have as much protection from fraud as do initial investors.
He adds that although secondary buyers would have access to the public disclosures that startups are required to make, those filings aren’t enough and are likely to be too complicated for unsophisticated investors to understand.
Mr. Oranburg sees each analyst covering as many as 30 startups listed with the portal, and protecting and advocating for shareholders by attending company board meetings and voting on certain matters such as acquisitions and management salaries. Ultimately, Mr. Oranburg says, these layers of protection provided by analysts should allow regulators to feel more comfortable with allowing secondary markets for crowdfunded shares.
In an email, an SEC spokeswoman said the commission wouldn’t comment. At a March 2015 meeting of the SEC’s Advisory Committee on Small and Emerging Companies, Commissioner Luis A. Aguilar said in a statement that didn’t speak for the agency, “The lack of a fair, liquid, and transparent secondary market for these securities is a long-standing problem that needs an effective solution.”
The National Crowdfunding Association of Canada (NCFA Canada) is a cross-Canada non-profit actively engaged with both social and investment crowdfunding stakeholders across the country. NCFA Canada provides education, research, leadership, support and networking opportunities to over 1300+ members and works closely with industry, government, academia, community and eco-system partners and affiliates to create a strong and vibrant crowdfunding industry in Canada. Learn more About Us or visit ncfacanada.org.


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016