





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 12, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, Lending Consumer Credit And BNPL
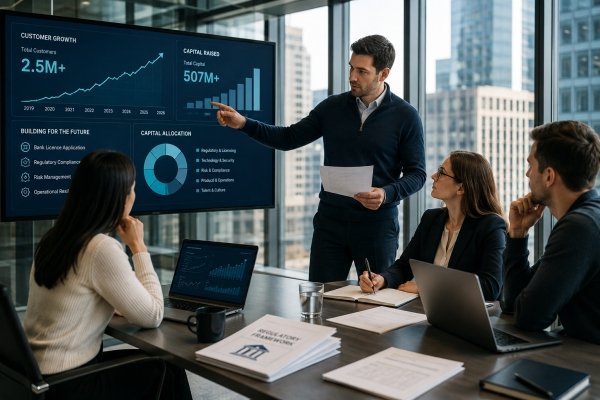
On June 11, 2026, KOHO announced a $130 million CAD financing at a $1.33 billion CAD valuation. KOHO says the capital will support growth and provide the initial capital base for a federally regulated bank, subject to ministerial approval. The round includes new investors Mubadala, Savano Capital, Shopify founder Tobi Lütke, and Affirm COO Michael Linford, with participation from Portage Ventures, Drive Capital, BDC Capital, HOOPP, and Eldridge. KOHO says it has raised $507 million CAD since launch and lists more than 2.5 million customers.
KOHO previously said it entered the second phase of acquiring a Canadian banking licence in January 2024, after raising an $86 million extension at an $800 million valuation and surpassing 1 million users.
The numbers have changed since that earlier milestone, but approval remains a federal decision. KOHO has added customer reach, capital base, and product depth behind its application. A bank licence requires proof of customer demand, not just capital strength, governance, risk controls, compliance systems, consumer protection, and trust. KOHO is trying to cross that line while still competing as a consumer fintech.
KOHO's round lands as OSFI prepares to launch a more defined path for targeted new entrants in June 2026. OSFI fast track approval framework analysis explains why the change is important for fintechs, challenger banks, and other firms with innovative banking models.
While the framework doesn't make approval easy, it offers eligible applicants a clearer route through the federal process while preserving prudential oversight. For fintechs, that is useful because demand for a product is not enough. A bank licence requires capital, governance, risk controls, compliance systems, consumer protection, and trust.
Questbank gives the KOHO story a recent Canadian benchmark. In November 2025, Questbank received approval to operate as a Schedule I bank after a six year approval process. KOHO is pursuing a different strategy, but the approval highlights that new federally regulated banking entrants can still emerge in Canada. That goes for international banking groups too like Santander who was approved by OSFI for a Canadian Banking License in 2025, after waiting for 6 years.
KOHO's financing follows two other large Canadian fintech disclosures. Wealthsimple raised C$750 million at a C$10 billion valuation in October 2025. nesto announced a C$302 million Series E at a C$1.47 billion valuation on June 10, 2026. KOHO followed one day later with a C$1.33 billion valuation.
Wealthsimple is pushing further into personal finance and banking style products. nesto is scaling mortgage and lending infrastructure. KOHO is putting new capital behind a federal bank licence effort. The same funding cycle is reaching different parts of financial services.
Customer growth and venture funding helped create Canada's latest generation of fintech firms. The next evolutionary question is whether firms that already have users and capital can obtain the regulatory permissions needed to participate more directly in deposits, lending, payments, and other core financial services.
KOHO has more than 2.5 million customers, a $1.33 billion valuation, and fresh capital earmarked for its bank licence effort. If customer scale and funding are no longer the hardest milestones, is regulated banking capacity now the real test for Canadian fintech competition?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply