





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 9, 2026
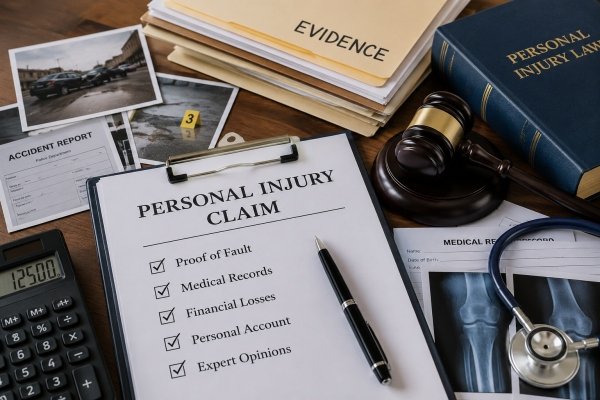
Most people think personal injury claims are won or lost in court. That's not how it works. The outcome gets decided long before trial, during the evidence-gathering phase. Strong documentation is what separates a settlement that actually covers your losses from a rejection letter sitting in your mailbox.
This article walks through exactly what evidence matters, how to collect it, and why insurers and courts in Halifax and across Nova Scotia weigh each type the way they do. Let's break down the main categories of evidence you'll need to build a winning claim.
Fault is everything. Without evidence that someone else caused your injury, no stack of medical records will get you a single dollar. What the insurer or court is really asking: did another party act carelessly, and did that carelessness directly cause your harm?
https://www.preszlerlaw-ns.com/ is where many injured Nova Scotians start once they realize how critical the liability question becomes. Fault evidence includes photos of the accident scene, dashcam or security camera footage, police reports from collisions, and witness statements gathered immediately after the incident. Each piece strengthens the picture that the defendant's conduct fell below a reasonable standard of care. And here's the catch: you need to move fast. Surveillance footage gets overwritten within 24 to 72 hours; witnesses' memories blur within days. In slip-and-fall cases, document that hazardous condition before the property owner fixes it. In car accidents, get the police collision report number at the scene so you can pull the full report later. A solid chain of fault evidence? That's your legal foundation.
Medical evidence pulls double duty. It connects your injuries to the accident, and it shows how serious those injuries really are. Insurance adjusters challenge both points routinely.
Your medical records should include:
Here's what catches people off guard: gaps in treatment. Insurers see missed appointments or delayed care and assume your injuries weren't that bad. Attend every appointment, follow your doctor's advice, and ask your providers to write down your symptoms at each visit. When a provider notes your condition matches a specific type of accident, that connection becomes extremely powerful. A written opinion from a specialist, an orthopaedic surgeon, neurologist, or similar, carries far more weight than a general note and is often requested in cases involving lasting or permanent damage. Keep every document, every referral letter, every test result in one organized place.
Compensation isn't just pain and suffering. You're entitled to claim actual financial losses, and you'll need documentation to back up every amount you ask for.
The most common financial loss categories:
Collect pay stubs, letters from your employer confirming missed time, recent tax returns, and receipts for everything related to recovery. Self-employed claimants get extra scrutiny, income is harder to prove, so bank statements, client invoices, and accountant letters all help. But here's the truth: don't assume the insurer will calculate your losses fairly. They won't. You have to present a clear, documented picture of exactly what this injury has cost you, both from day one and looking forward.
Your own story is evidence. Courts and insurers listen closely to how consistently and credibly you describe what the injury does to your daily life.
Start a pain journal right after the accident. Write entries daily or several times a week, capturing:
A journal kept faithfully over months beats a general statement made years later. Document conversations with your doctor about how you feel, and make sure those match what's in your medical file. When your journal, your medical records, and what you say all line up, adjusters and judges take notice. Any inconsistency gets used against you; consistency builds credibility. Personal accounts matter most in soft-tissue claims, chronic pain cases, or trauma cases where objective test results might be sparse.
Complex claims almost always need expert evidence. No matter how thorough your own documentation is, certain aspects require professional credentials to carry weight in court.
Common experts in Nova Scotia personal injury claims include:
Expert reports cost money, but they're often essential for serious injuries or significant wage loss claims. And when the defence hires its own expert, you get a battle of credentials and methods, which is why report quality matters enormously. Talk to your lawyer early about which experts will strengthen your particular case. In Nova Scotia, expert reports must be shared with the other side before trial, so getting them done early gives you time to shore up any weak points before a formal hearing happens.
Winning a personal injury claim in Halifax comes down to the strength and completeness of your evidence across five areas: proof of fault, medical documentation, financial loss records, your personal account, and expert opinions. Each one supports the others. Gaps in any single area give the insurer a reason to reduce or reject your claim. Start collecting evidence from day one, keep it all organized, and work with a lawyer who knows how to prepare and present that evidence inside Nova Scotia's legal system.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply