





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 2, 2026 | NCFA Insight | Artificial Intelligence And Data, Capital Markets And Market Infrastructure, Risk Compliance And Regtech
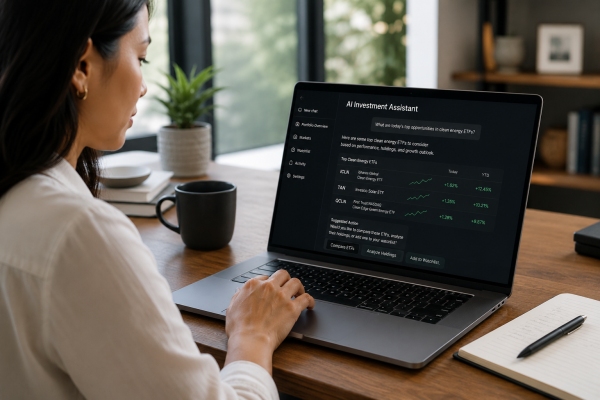
On May 26, 2026, Liquid launched Co Invest for ChatGPT and Claude, allowing users to research markets, construct portfolios, fund accounts, and execute trades from inside an AI conversation. The platform supports more than 500 markets across stocks, ETFs, commodities, crypto, FX, prediction markets, and pre IPO opportunities. Every trade still requires user confirmation before execution.
The launch is testing a new distribution model for financial services. For two decades, brokers competed to convince customers to visit websites and download apps. Liquid is testing a different idea. This is already happening in commerce. Agent driven checkout and payments are moving purchase decisions closer to AI assistants.
What happens if the customer never leaves the AI assistant?
Traditional brokerage growth follows a familiar formula. Acquire the customer. Get them into the platform. Keep them engaged. Generate more activity inside the platform.
Co Invest reverses that process. The customer already lives inside ChatGPT or Claude. Research happens there. Portfolio construction happens there. Market comparisons happen there. The trade happens there. The broker becomes the infrastructure underneath the conversation.
The launch announcement describes Co Invest as a way to move from market question to live execution inside a single workflow. If customers increasingly begin their financial decisions inside AI assistants, brokers may need to compete for agent connectivity as aggressively as they once competed for app downloads.
Much of the discussion around AI and investing focuses on autonomous trading. Liquid's current product doesn't do that. Users must still approve all trades before execution (at least for now). The assistant can research, compare, explain, size positions, and prepare orders, but it cannot freely move money or trade without permission (aka the agentic trading model).
Perhaps before markets and regulators reach fully autonomous investing, there will be a type of 'permissioned investing' that gets iterated before then. The goal isn't unrestricted authority. It's a type of controlled automation with clear limits, permissions, and accountability.
Example: A customer could authorize an agent to purchase a specific ETF under preset conditions, apply position limits, avoid leverage, stop trading after a certain loss threshold, and require additional approval for larger transactions.
This approach may appeal to regulators, brokers, and investors because it preserves accountability while reducing friction.
The benefits are easy to understand. AI agents can monitor markets continuously, enforce risk rules consistently, compare opportunities quickly, and reduce emotional decision making.
The risks are less obvious. If millions of investors eventually rely on similar models, data sources, prompts, and optimization goals, market behaviour could become more concentrated. Markets already experience crowding through index investing, quantitative strategies, and algorithmic trading. Agentic investing could introduce a new version of the same challenge if many systems begin reaching similar conclusions at the same time.
The concern is that a large number of investors could end up acting through similar decision frameworks without fully realizing it. A model that works well for one investor may create new market risks when millions of investors use similar prompts, data sources, and optimization rules. The result could be more crowded trades, sharper reversals, and less diversity in market decision making.
If AI assistants become the place where investors start financial decisions, brokers lose some control over the customer interface and relationship.
Distribution changes and brokers may need to prove itself to the AI systems that sit between customers and financial products.
That creates a different kind of competition. Brokers may be forced to compete on permission controls, API reliability, execution quality, and audit records as much as interface design.
The broker with the most reliable AI integrations may win more order flow than the broker with the best looking app.
Canada's discussions around consumer driven banking, digital identity, AI governance, retail payment oversight, and securities regulation all intersect here. If AI assistants become a gateway to investing, accountability becomes more important than automation.
Who approved the instruction? What permissions were granted? What limits were applied? What records were created? Who supervised the activity? Those questions are more important than whether the interaction started in a brokerage app or a chatbot.
Current securities rules already apply to firms using AI, and AI is creating new audit and authorization questions for financial firms. The harder challenge is determining how responsibility should be shared when AI systems increasingly participate in financial decisions and transaction workflows.
Liquid's launch doesn't answer those questions, but it provides an early look at where the industry may be heading.
If AI assistants become the primary place where investors research markets, compare opportunities, and initiate transactions, will brokers compete for customers or compete for connectivity to the agents representing those customers?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply