





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 18, 2026 | NCFA Fintech Market Insight | Payments And Consumer Finance And Tax
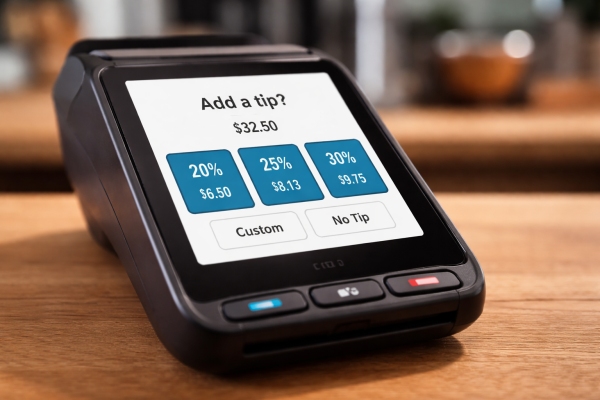
On Mar 17 2026, H&R Block Canada revealed tipping survey results putting new numbers behind a growing consumer reaction to tip prompts at checkout. Two thirds of Canadians or 67% say Canada should abolish tipping culture. Another 93% say they feel annoyed when a card machine prompts for a tip in places where tipping was not previously expected, and 89% say tipping is out of hand and is applied to goods and services they do not think warrant tipping.
This backlash isn't just frustration. It's now changing behaviour and pushing customers away.
The survey also connects tipping culture to tax and compliance.
H&R Block’s 2025 survey found 84% of Canadians know tips are taxable income, but 47% assume people are not declaring all tips. The evolution from paying/receiving cash tips to digital tips changes how income shows up for tax purposes, especially when tips flow through employers and platform operators.
Digital tipping changes the paper trail. When tips move through a card terminal or POS system and the business pays them out through payroll, the tip can show up like other income on a paycheque, with deductions such as tax, EI, or CPP applied before the employee receives it and then reflected on tax slips. That is different from cash tips left on a table, where the worker has to track and report them. Gig work is different again. Even when an app collects tips and passes them on, gig workers are often treated as self employed, so they still have to report the full amount themselves at tax time.
This is a payments design problem that's now hitting brand trust. The tip prompt is part of the checkout experience, and the checkout experience is increasingly built and configured through payment processors, point of sale providers, and embedded finance stacks. When consumers feel pressured, they blame the merchant, but they also blame the payment flow. The numbers show that tip prompts can create real revenue risk for merchants if 41% of customers are willing to avoid tip pushing businesses.
For fintechs selling point of sale and payment tools, this is an opening to compete on trust and customer experience. Firms that give merchants better controls, clearer disclosure, and safer defaults can reduce backlash while still supporting gratuities where they make sense.
Fintechs that serve gig platforms (or merchants) can help by making tip reporting clearer in worker dashboards and by separating tip flows in a way that matches how income is treated.
Merchants will tune tip prompts more carefully because customer resentment is measurable. Payment platforms will face more pressure to treat tip design as a trust issue, not a digital cash lever. Regulators and tax authorities will face more questions about consistency and clarity as tipping moves further into digital rails.
If 67% of Canadians want tipping abolished and 41% avoid tip pushing businesses, do payment platforms start competing on tip prompt design the same way they compete on fees and checkout conversion?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply