





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mar 3, 2026 | NCFA Fintech Market Insight | Small Business Performance And Payments
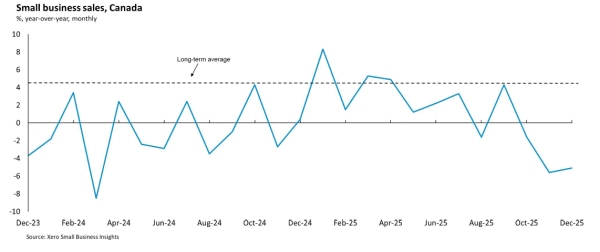
Image: Small Business Sales, Canada (Xero Small Business Insights, Canada Oct Dec 2025)
On February 26 2026, Xero released its Small Business Insights Canada Update for October to December 2025, based on aggregated and anonymized small business accounting data from its small business accounting platform, not survey responses. The dataset reflects real invoicing and payment activity captured within the Xero system. The December quarter closed with a clear revenue reversal while payment discipline strengthened. The numbers provide an operating baseline for fintech lenders, payments firms, and financial institutions serving the small business segment, as we move deeper into 2026.
Quarterly Sales Growth 2025
Q1: +5.0%
Q2: +2.8%
Q3: +2.0%
Q4: −4.1%
Q4 Monthly Breakdown
October: −1.6%
November: −5.6%
December: −5.1%
A nine percentage point swing from Q1 to Q4, with the December quarter decline the largest since September 2020. The Q4 reversal showed how fast small business demand can change. Sales moved from solid growth early in the year to a sharp contraction by December.
That kind of swing compresses reaction time. For lenders and platform providers, continuous revenue monitoring is more important than backward looking ratios. Fintechs that track live invoicing flows and cash inflows gain earlier warning signals. Banks that still rely on periodic reporting will be reactive. The risk is no longer just default, it's also speed.
During periods of weaker revenue, founders focus on cash flow and credit, but they also need to review commercial insurance coverage options as risk exposure increases.
Full Year 2025 Average: +1.4%
Long Term Average: +4.5%
A sustained three percentage point gap versus historical norms. Not a single weak month but a structural softness across the year. When growth slows, small businesses focus on managing timing. They want certainty around receivables, payables, and liquidity buffers. Expansion plans move to the background. This changes product priorities. Tools that shorten receivable cycles, automate reconciliation, and provide flexible liquidity become core operating infrastructure. Working capital solutions that assume growth acceleration may miss the mark. Fintechs that help stabilize cash flow, and not amplify growth, may align better in this cycle.
Late Payment Days
June Quarter: 11.3 days
September Quarter: 9.8 days
December Quarter: 9.7 days
Long Term Average: 11.7 days
Time To Be Paid
June Quarter: 27.7 days
September Quarter: 26.3 days
December Quarter: 26.8 days
Revenue slowed, but businesses tightened receivables management. Payment behaviour improved into year end. Settlement timing held steady despite volatility in topline growth. This means payment behaviour data may now offer stronger forward insight than topline growth alone. If a business collects faster, even during a slowdown, that tells you something about discipline, customer quality, and internal controls. Fintech lenders that weight verified payment performance can price risk more precisely.
Q4 Sales Growth By Province
British Columbia: −8.2%
Alberta: −4.0%
Ontario: −1.7%
Q4 Time To Be Paid
Ontario: 28.4 days
British Columbia: 27.5 days
Alberta: 26.6 days
Regional sales outcomes and liquidity conditions diverged materially. National averages masked local differences. The December quarter showed wide variation across provinces. Some regions contracted far more than others. That gap changes the risk profile of a portfolio. National averages smooth out reality. A lender with concentrated exposure in a weaker province carries different forward risk than one diversified across stronger regions. Regional segmentation should move from a reporting exercise to a pricing and limit setting discipline. Portfolio steering needs to reflect local operating conditions, not national headlines.
Q4 2025 showed a structural split: weaker sales, stronger collections, and widening regional differences. For fintech leaders, the opportunity is not just reacting to the decline. It's in building systems that continuously read revenue direction, payment velocity, and geographic exposure at a granular level. Firms that can master these variables in real time will support small businesses more effectively in lower growth environments.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply