





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 25, 2026 | NCFA Insight | Digital Identity And Trust, Cybersecurity Fraud And Financial Crime, Risk Compliance And Regtech
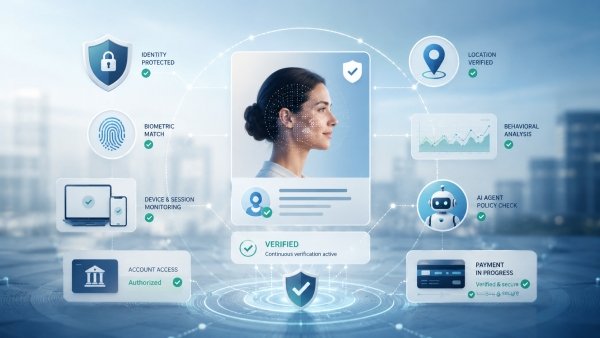
On August 25, 2026, Vancouver based Fobi AI launched Fobi AltID 3.0, expanding its digital identity technology beyond credential verification. Fobi says the new platform can continuously authenticate a verified person, confirm authorization and use satellite positioning to add location and time to the decision. Financial services and customer identity checks are among its intended uses.
The existing Fobi digital identity wallet focuses on proving identity or age while limiting how much personal information needs to be shared. The new proposition goes further. Once someone has been verified, Fobi wants the credential to keep helping organizations decide whether the right person is still present and allowed to complete an action.
That addresses a real financial control problem. Verifying someone when an account is opened does not prove that the same person still controls a session months later, approved a particular payment or gave software permission to act for them. The gap gets wider as financial services automate more activity.
The launch names financial services as a target market but doesn't identify a bank, credit union, payment company or financial pilot. It also doesn't explain how an AI agent would be given, restricted or stripped of authority. Those are important boundaries between the product Fobi has launched and the larger trust infrastructure it wants to build.
This approach already has support in established digital identity practice. NIST continuous authentication guidance allows organizations to monitor characteristics such as behaviour, device information, location, timing and network activity after a user has logged in. Suspicious changes can trigger another identity check or end the session.
For financial firms, that can add protection without repeatedly asking customers to upload identity documents. An account can remain usable while the service watches for changes that make the current activity look less like the person who was originally authenticated.
Fobi adds location to that decision. The company says satellite positioning can connect a verified person with where and when an interaction occurs. Location can strengthen a risk decision, but Fobi has not disclosed the positioning technology, accuracy or protections against false location data. NIST also treats geolocation as one piece of a wider risk assessment rather than proof of identity on its own.
More monitoring also creates more privacy responsibility. Behaviour, devices and location can all reveal sensitive information. NIST requires those uses to be included in privacy risk assessments. Fobi says the personal information used for the original verification can be removed from the ongoing process, but further disclosure is needed to show what the platform continues to observe and retain.
Canada is dealing with the same combination of identity, consent and security as financial data becomes easier to share. The proposed Canada Open Banking and Consumer Driven Banking Rules bring authentication, consumer permission, security and evidence of authorization into the same operating framework. Persistent digital identity becomes more useful when those controls have to work after onboarding rather than only at the beginning of the relationship.
AI agents make the distinction between identity and authority easier to see. A bank may know who owns an account and still need to know whether software has permission to spend $500, change an instruction or continue acting tomorrow. AI agents with wallet access increases the urgency of defining what software can do, for how long and on whose authority.
Payment networks are already building controls around that problem. The Visa Trusted Agent Protocol lets merchants verify that an AI agent is legitimate and has permission to act for a customer. Visa's specifications also allow merchants to limit an agent to a specific purpose, such as browsing or making a payment.
Mastercard Verifiable Intent, developed with Google, records what a person authorized before an AI agent acts. Mastercard is designing it to work across wallets, platforms, payment networks and different agent systems.
The same convergence appears in the FCA Emerging Technology Horizon Scan 2026, where digital identity, AI agents, consumer control and programmable finance intersect. For fintechs, the opportunity goes beyond proving who somebody is toward proving what a person or piece of software is allowed to do.
Open digital credentials could make those permissions easier to carry between services. The W3C digital credential standard provides a common way to issue and verify secure, privacy respecting credentials. Fobi has not disclosed whether its new platform supports that standard or another open identity framework. Interoperability is necessary if the technology is expected to work across banks, fintechs, payment networks and other organizations rather than mainly inside Fobi's own products.
Fobi is also positioning post quantum security as part of the platform. Financial firms are already preparing for post quantum cryptography as new security standards replace encryption that future quantum computers could threaten. Fobi has not identified which algorithms or standards it uses, or provided independent technical validation. For now, quantum readiness remains a product claim that still needs evidence rather than the main reason to assess the launch.
The more immediate opportunity is digital trust. Identity can establish the person. Ongoing authentication can flag when something changes. Authorization can control what a person or AI agent is allowed to do. Those capabilities also connect digital identity, cybersecurity and automated finance across the Financial Innovation Map.
Fobi now has to prove that its technology can join those pieces in practice. A financial institution deployment, support for open credentials or documented controls for delegated authority would make the case much stronger. Until then, the launch is a credible expansion of Fobi's digital identity technology into a financial problem that is becoming harder as software gains more authority.
As AI agents gain access to payments, financial accounts and digital credentials, will proving identity once be enough, or will financial services need to keep verifying who is in control and exactly what they are allowed to do?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply