




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Sep 9, 2026
Digital payments often feel immediate. A customer can place an order, fund an account, or purchase a subscription in seconds. When money needs to travel in the opposite direction, however, the process can take considerably longer.
Refunds and withdrawals pass through multiple systems before reaching a customer’s account. The business, payment provider, bank, card network, and fraud prevention team may all play a role. Understanding these stages can help consumers set realistic expectations and identify when a delay requires further action.
A refund reverses all or part of an earlier payment. It might follow a canceled order, returned product, duplicate charge, or service complaint. The money usually returns through the same payment method used for the original transaction.
A withdrawal moves money from an account or platform to an external destination. Examples include transferring funds from an investment app, marketplace, digital wallet, or online casino to a bank account or payment service.
The difference matters because each process follows its own review and settlement procedures. A merchant refund may be approved quickly but remain pending with the card issuer. A withdrawal may require identity checks before the platform releases any funds.
Some services promote instant or same-day withdrawals, but the term usually describes how quickly the platform approves or sends the payment. It does not necessarily guarantee that the money will appear in the recipient’s account immediately.
This distinction is especially relevant in competitive industries. Casino.ca profile Canadian operators with fast payment processes, including instant withdrawal casinos, so readers can compare which platforms are known for efficient payouts. However, the final arrival time may still depend on the withdrawal method, banking hours, identity verification, and the policies of the receiving financial institution.
The same principle applies to retail refunds, freelance platforms, travel companies, and investment services. A business may release funds promptly while another organization within the payment chain takes additional time to process them.
Processing times vary considerably between payment methods.
Digital wallets can be among the fastest options because funds remain within a connected electronic network. Some transfers may arrive within minutes, while others require a short review period.
Bank transfers can take longer, particularly when payments move between different institutions or countries. Weekends, public holidays, currency conversions, and intermediary banks may add further delays.
Card refunds often take several business days to appear. Although a retailer may issue a refund immediately, the card network and issuing bank must still process the reversal. Some banks display pending refunds, while others show the money only after settlement is complete.
Checks are generally slower because they require production, delivery, deposit, and clearance. They may still be offered when an electronic refund cannot be returned to the original payment method.
Platforms that handle financial transactions commonly verify customers before processing withdrawals. This may involve confirming a name, address, payment method, age, or source of funds.
These checks help prevent fraud, identity theft, unauthorized payments, and money laundering. They can also cause delays when documents are missing, expired, unclear, or inconsistent with the account details.
Completing verification early can reduce the risk of disruption. Customers should make sure account information is accurate and submit documents only through secure, official channels.
Businesses should explain their requirements before accepting money rather than introducing unexpected checks when a customer requests a withdrawal.
Processing estimates are usually expressed in business days. A refund issued late on Friday may not begin moving through the banking system until Monday. A public holiday can extend the wait further.
International transactions may be affected by holidays in more than one country. Time zones can also influence whether a request is received before or after a provider’s daily processing cutoff.
For this reason, “three business days” should not be interpreted as 72 hours. Depending on when the request begins, three business days could cover a much longer period on the calendar.
Before contacting support, customers should check the stated processing window, transaction status, payment details, and any verification requests. It is also important to distinguish between the date a payment was approved and the date it was sent.
If the quoted timeframe has passed, request a transaction reference or confirmation number from the business. A bank or payment provider may be able to trace the funds using that information.
Consumers should be cautious if a company repeatedly requests additional deposits, fees, or taxes before releasing a withdrawal. Legitimate charges should be clearly disclosed and should not continually change.
Fast payments can build confidence, but transparency is just as important as speed. Businesses that explain each stage, provide realistic timelines, and communicate delays clearly are more likely to earn lasting customer trust.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
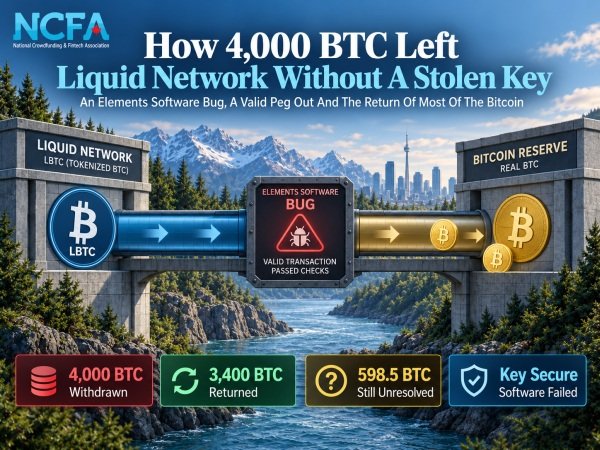
On September 6, 2026, the Liquid Network reported a 4,000 BTC withdrawal from the Bitcoin backing its sidechain. The bitcoin was worth about US$320 million when the incident was disclosed and represented roughly 95% of the approximately 4,200 BTC then reported in the federation wallet.
The size alone made it one of the year's most consequential digital asset security incidents. The mechanics made it stranger. SideSwap says the authorization key used in the peg out was not compromised. Instead, the 4,000 LBTC submitted for redemption was later attributed to a bug in Elements, the software underlying Liquid.
Most of the bitcoin has since come back. On September 7, the withdrawing party returned 3,400 BTC after an unusual onchain exchange with Blockstream over the software patch. Roughly 598.5 BTC, worth about US$47 million on September 8, remained at the withdrawal linked address when this Story was prepared.
Nearly an entire reported Bitcoin reserve left through an apparently valid redemption process even though the authorization key itself had not been stolen.
Protecting private keys is essential. Liquid's incident shows why the software deciding which assets are valid can matter just as much as the cryptography authorizing their redemption.
Liquid is a Bitcoin sidechain. Users lock bitcoin and receive LBTC that can circulate on Liquid before being redeemed back into bitcoin.
Before the incident, reporting put the federation wallet at roughly 4,200 BTC. About 4,000 BTC left during the withdrawal, putting almost the whole reported reserve behind one incident.
The response was immediate. Liquid activity was paused, bridge nodes were disabled and exchanges were asked to suspend LBTC deposits and withdrawals. SideSwap also stopped swaps, peg ins and peg outs.
That bought developers time to work out how such a large redemption had been accepted before normal bridge activity continued.
A stolen withdrawal key would have provided a familiar explanation. SideSwap says that didn't happen. The service processed a valid authorization, which pushed attention back toward the LBTC that entered the redemption process.
SideSwap says 4,000 LBTC was sent to its peg out service. The service burned the tokens against a valid authorization, after which the Liquid Federation released roughly 3,996 BTC to a Bitcoin address.
SideSwap says neither its systems nor its Peg out Authorization Key was compromised.
The crucial discovery came afterward. According to the account of the investigation, Blockstream determined that the LBTC involved had been created through a bug in Elements.
Elements is the open source software on which Liquid runs. The failure therefore appears to have happened before the final Bitcoin redemption rather than through theft of the SideSwap authorization key.
The peg out machinery can receive a valid authorization and release real bitcoin while the LBTC entering that process has already been corrupted by a software failure. Securing the key is necessary. It doesn't cover every route to an invalid redemption.
Then the incident took an unusual turn. The withdrawing party described itself as white hat and began communicating through messages recorded on Bitcoin.
Blockstream contacted the party through an onchain transaction. The party later told Blockstream to fix the bug and make sure the relevant nodes were patched before the bitcoin would be returned.
The white hat description remains the party's own characterization. It isn't an independently established status.
Blockstream later sent an authenticated message saying its bridge nodes had been patched. The response was followed by a transaction returning exactly 3,400 BTC to the federation address.
That recovered about 85% of the withdrawn bitcoin. The same transaction left approximately 598.5 BTC at the withdrawal linked address.
Neither Blockstream nor Liquid had publicly identified that remaining bitcoin as an agreed payment when this Story was prepared.
A party controlling hundreds of millions of dollars in bitcoin communicates with the infrastructure provider through the blockchain itself, waits for a software repair and then returns most of the funds. It's an extraordinary sequence, but it doesn't establish that the original withdrawal was authorized or benevolent.
Independent security researchers have begun explaining how the Elements failure may have happened.
CertiK's incident analysis points to Elements' handling of rangeproof verification caching. Its reconstruction says a flaw could allow different validation contexts to share a cached result and cause invalid value to be accepted.
That could explain how LBTC that shouldn't have been valid reached the peg out process.
The technical analysis is developing faster than the official explanation.
Blockstream hadn't published a complete technical postmortem when this Story was prepared. The exact affected software versions, complete code path, deployment history and remediation therefore aren't settled yet.
The confirmed finding is narrower and important enough on its own. Blockstream identified an Elements software bug as the source of the LBTC involved in the withdrawal, according to SideSwap's account.
When a token represents an underlying financial asset, software validation becomes part of the reserve control. If the system accepts an asset state it should reject, that mistake can become a claim on real assets even when the keys protecting them remain secure.
The size of the withdrawal makes that connection hard to miss. Roughly 95% of the reported bitcoin reserve was involved before most of the funds came back.
That doesn't mean Liquid permanently lost 95% of its backing. It means a software failure produced a redemption event large enough to put almost the entire reported reserve into question at once.
For digital asset firms, reserve security therefore extends well beyond storing keys.
Supply verification, transaction validation, reserve reconciliation, withdrawal monitoring, circuit controls and incident response all become part of the same operating problem.
That same issue appears in how crypto custody regulation is changing, as the market moves beyond simply holding private keys toward segregation, authority, resilience and accountability.
A secure key can't compensate for software that accepts an asset state it should reject. Issuance, validation, reserves and redemption all have to work together because a failure in one can reach the value protected by another.
Liquid's federation also gave operators a practical advantage during the response. Identifiable participants could coordinate, stop infrastructure, patch bridge nodes and prepare a restart.
That can make emergency intervention faster. It also means federation governance and operating procedures are part of the security model rather than something separate from it.
The same problem gets more important as financial institutions put securities, funds, deposits and other assets onto programmable infrastructure.
Tokenization becoming a business investors can measure captures the commercial side of that development. Liquid exposes the other requirement. Redemption and reserve systems still have to work when software doesn't.
Returning 3,400 BTC dramatically reduces the financial exposure, but it doesn't explain why nearly the whole reported reserve could leave through one sequence or what now prevents a recurrence. Those answers will determine whether this remains a contained software failure or becomes a longer trust problem for Liquid.
Liquid's authorization key reportedly held. Its validation software didn't. Nearly 4,000 BTC still left before most of it came back, showing why tokenized asset security depends on much more than protecting the keys that authorize redemption.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 8, 2026

Moving inventory efficiently is essential for businesses that use multiple warehouses. Whether you're meeting seasonal demand or reallocating stock to improve operations, knowing how to move inventory quickly can greatly affect your workflow and profits. Every second matters, and implementing effective strategies can optimize the process, keeping customers happy while boosting efficiency.
When planning inventory movement, consider the right tools and techniques. The right equipment helps transport goods smoothly between locations. From warehouse layout to packing and transfer methods, every detail affects the overall process. Here are some ways to streamline inventory transfers and speed up product movement.
A smart warehouse layout is key for quick inventory movement. Organize each section for easy access and fast transfers. Place similar items close together and create a flow from receiving to shipping to save time. Keep aisles wide and designate lanes for picking to avoid delays, especially during busy times.
Also, think about where to place storage systems like shelving, racks, and pallets. Using vertical space can maximize storage, but it should still allow fast access. The closer products are to packing and shipping areas, the quicker they can be moved. Investing time and resources into an efficient layout pays off over time.
A triple scissor lift is valuable for handling warehouse inventory. These lifts offer great versatility, allowing workers to reach higher stacks of inventory easily. The multi-tier design lets the lift extend vertically, giving access to products stored at various heights without needing a ladder or complicated equipment.
This feature boosts productivity by saving time and effort when retrieving items. Workers can position themselves exactly where needed, making it faster to grab products and safer by reducing the risk of injuries from reaching high shelves. With a triple scissor lift, moving between levels is easy, ensuring smooth operations during busy times.
Technology can improve inventory movement. Barcode scanning systems and inventory management software help track products in real-time, so you know where everything is at all times. Automation tools like conveyor belts and automated guided vehicles also help move goods swiftly between storage areas.
These systems reduce human error, improve picking accuracy, and cut time spent on manual tasks. Quickly identifying stock levels and locations helps employees work more efficiently, speeding up overall inventory movement.
The double scissor lift is an important tool for moving items in busy storage spaces. Unlike regular lifts, double scissor lifts are compact but can lift heavy loads. They work well in narrow aisles, which is important in crowded warehouses where space is limited.
With a double scissor lift, you can stack items higher, use vertical space more effectively, and still reach products easily. This equipment speeds loading and unloading and keeps operations organized. Employees can quickly load items onto pallets or into containers, which speeds up shipping processes.
Creating clear standard operating procedures (SOPs) for moving inventory can make operations faster and more efficient. These procedures should explain every step of the process, from when stock is needed to when it is loaded onto transport vehicles. Clear guidelines help everyone understand their roles and deadlines.
Regular training sessions keep all team members up to date on these procedures and how to use the equipment. Repeated training helps improve speed and accuracy, allowing for quick changes if inventory needs shift. Having a checklist can also help ensure smooth transitions during busy times.
Good communication between departments is essential when moving inventory. A prepared team can react quickly to changes, like sudden order increases or urgent shipping needs. Regular updates through meetings or collaboration tools help everyone stay informed and ready to respond to any challenges.
Encouraging open communication fosters teamwork and can lead to creative solutions for unexpected problems. When team members feel valued and are encouraged to share their ideas, the inventory process speeds up significantly.
By focusing on these strategies and tools, you can move inventory faster and more efficiently between warehouses. Whether you use advanced tools like double scissor lifts or improve your processes and communication, each step toward better movement enhances overall satisfaction and success.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 8, 2026 | NCFA Insight | Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization, Treasury Liquidity And Cash Management
On September 8, 2026, Visa introduced an onchain credit model for stablecoin card programs that combines VisaNet settlement data with financing provided by Credit Coop. Visa isn't the lender. Credit Coop provides stablecoin denominated revolving credit secured by settlement receivables, while authorized Visa settlement records help lenders assess how participating programs are actually performing.
Visa says more than 160 stablecoin card programs are live globally, with payment volume up nearly 200% year over year. Its stablecoin settlement volume recently passed a US$20 billion annualized rate, more than 15 times the prior year. Credit Coop has financed more than US$2.5 billion since 2023 across more than 3,000 borrowing events and 9,000 repayments, with zero defaults reported across participating facilities.
Visa says more than US$694 billion in stablecoin denominated loans have been sent through onchain lending protocols since 2020. The new element is using payment network data to support credit decisions for businesses operating inside the card system.
Card programs can owe Visa money before they have collected the related funds from cardholders. Large issuers usually finance that timing gap through bank credit lines, warehouse facilities or securitizations. Those structures work well when portfolios are large and lenders have enough operating history to assess them.
Early stablecoin card programs can have a different funding profile. Visa says some need only a few million dollars, draw and repay capital every day and settle through weekends and holidays. At that scale, the fixed cost of arranging a traditional facility can be difficult to justify, while the borrower may not yet have enough history to satisfy an institutional lender.
Visa's financing model uses a revolving Credit Coop facility to fund daily settlement obligations against the receivables generated by the card program. As cardholder payments arrive, those proceeds repay and replenish the line.
That financing need grows with the card programs themselves. Wirex and Crossmint connected wallets, card issuance and stablecoin spending earlier this year, showing how quickly the customer facing infrastructure is becoming easier to assemble. Financing the settlement behind those products is a different problem.
The concept is similar to bringing rent payments into a traditional credit file. A recurring payment record that was previously difficult for lenders to use becomes additional evidence about the borrower. Here, the new evidence is payment network data being used to support onchain credit.
With the card program's authorization, Credit Coop receives daily Visa settlement files through a secure data connection. It compares those records with the onchain repayment history when sizing facilities, confirming settlement requirements and monitoring repayment. The borrower is no longer the only source of information about its payment obligations.
Credit Coop's Spigot smart contract controls how incoming receivables service the facility. Cardholder proceeds flow through the contract, which routes repayment before the remaining funds reach the borrower's operating account. The structure performs a role similar to a controlled bank lockbox, but repayment can occur programmatically.
Visa says stronger data and a longer repayment record have attracted more lenders to the facilities, reducing borrowing costs for participating programs by as much as 30%.
The same data connection can also support funding closer to the actual settlement obligation. Instead of drawing a larger amount in advance and holding unused capital, the daily settlement file can trigger a same day disbursement for the net amount owed to Visa. That reduces the time capital sits idle and ties lender exposure more closely to actual settlement activity.
Rain provides the longest operating record disclosed by Visa. The Visa Principal Member has used a Credit Coop revolving facility since August 2023 and settles directly with Visa in USDC. Rain says it tokenized its card receivables, allowing incoming payments to service financing through programmable contracts.
Visa reports that approximately US$2 billion of Rain settlement has been financed through the structure, with more than 2,000 borrowing events and 7,000 repayments. They also report zero defaults and says every settlement obligation under the facility has been funded on time. The underlying program figures were supplied by Credit Coop, so they should be treated as reported operating data rather than independently audited results.
Visa says Karta's U.S. card program used Credit Coop while its operating history was still developing. In June 2026, Karta raised US$140 million, including a US$125 million institutional credit facility from Community Investment Management and a US$15 million Series A led by Galaxy Ventures. Karta reported 10 times growth in 2025 and another four times increase in revenue and payment volume quarter over quarter in Q1 2026.
The growth gives the model its strongest strategic relevance. Onchain credit can help finance a younger payment program while it builds a verifiable repayment record. Larger institutional facilities can become available later when the portfolio reaches the scale and maturity conventional lenders want. Visa explicitly says this model adds to warehouse lending and securitization rather than replacing them.
Canada already has a direct connection to Visa's stablecoin settlement strategy. In May, Visa Canada and Wealthsimple began testing USDC settlement for certain Visa Canada obligations. There is no public evidence that the Credit Coop financing model is currently available to Canadian programs, but it gives Canadian issuers and payments firms a concrete example of how stablecoin settlement can connect to working capital and credit.
If payment network data can help a young card program prove credit performance before it qualifies for a traditional warehouse facility, onchain credit may become a bridge into institutional finance rather than a separate system.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 8, 2026 | NCFA Insight | Cross Border Payments And FX, Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization
On September 8, 2026, Circle agreed to acquire Tazapay, a Singapore headquartered B2B payments company serving payment providers and financial institutions. Circle says Tazapay brings more than US$25 billion in annualized payment volume, 60+ banking and fintech partners and payout connections across 100+ markets. Approximately 60% of its transaction volume involves stablecoins.
The US$400 million transaction will be paid in Circle Class A shares, subject to specified adjustments. Circle signed the agreement on September 4 and expects it to close in 2027 after required approvals, including approval from the Monetary Authority of Singapore. The acquisition has not closed.
Tazapay was already a Circle Payments Network design partner, and Circle Ventures led an extension of its Series B in March 2026. Circle is now acquiring to own a company that connects stablecoin settlement with local banking, FX and payout access.
Tazapay connects businesses to international collections, local payouts, foreign exchange and stablecoin conversion. Its payments platform supports card payments from 170+ countries, local payment methods in 100+ countries, payouts across 100+ countries and balances in 40+ currencies.
Its operating scale has grown quickly. In August 2025, Tazapay reported more than US$10 billion in annualized volume, 300% annual growth and operational breakeven. Circle reported more than US$25 billion in annualized volume as of July 31, 2026.
Tazapay's Series B reached US$36 million after Circle Ventures led the March extension. So going from payment partner to investor to proposed owner gives Circle more direct control over a business already connecting digital dollars with conventional payment systems.
Stablecoins can settle value across borders, but businesses usually receive and spend local currency. Circle Payments Network reflects that model. Payout partners convert stablecoins to fiat for local delivery, while Circle provides USDC settlement and network routing. Circle's payout network already includes Tazapay and other regional providers.
Circle is also connecting external networks rather than owning every payout route. In May 2026, Nium joined Circle Payments Network with payout infrastructure spanning more than 190 countries and 100 currencies. That partnership gives Circle substantial reach without an acquisition. In Tazapay's case, Circle is paying US$400 million to bring part of that payment capability inside the company.
Circle says roughly 60% of Tazapay transaction volume involves stablecoins. Tazapay describes its stablecoin service as payment and conversion through onramps and offramps, so the figure does not mean 60% of transactions run entirely onchain. Stablecoins may handle settlement while customers still enter or leave through fiat.
Other large payment companies are making similar acquisitions. Stripe completed its purchase of Bridge in 2025, Ripple agreed to acquire Rail for US$200 million, and Mastercard completed its acquisition of BVNK in August 2026. Mastercard explicitly described the deal as connecting digital assets with traditional payment rails. Taken together, a competitive market is forming around the links between stablecoins, banks, FX and local payments.
NCFA's Programmable Stablecoin Payments highlights the same commercial opportunity opening around payment routing, treasury, reconciliation, compliance and bank integration around stablecoin settlement rather than simply issuing another token.
Tazapay has a direct Canadian operating connection. Tazapay Canada Corp. is registered with FINTRAC as a money services business and with the Bank of Canada as a payment service provider under the Retail Payment Activities Act. Tazapay says the Canadian entity handles foreign exchange, fund transfers and virtual currency activity, and provides its stablecoin payment and conversion services. However, Circle has not disclosed a specific role for Tazapay Canada Corp. post acquisition, and therefore should not be treated as automatically giving Circle new Canadian permissions.
The more immediate Canadian relevance is commercial. Tazapay already connects stablecoin settlement with fiat conversion and local payout access. Canadian fintechs serving international businesses face the same need to connect digital money with bank accounts, FX, compliance and usable local payment methods.
Stablecoins can settle globally, but businesses still need banks, currencies and payout systems at either end. As those connections become more valuable, will the leading stablecoin companies keep renting access or increasingly own the rails?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 8, 2026 | NCFA Insight | Artificial Intelligence And Data, Wealthtech Investing And Trading, Risk Compliance And Regtech
On September 8, 2026, Focal AI launched agentic AI capabilities for Canadian financial advisors that can read and fill forms, draft emails, prepare client materials and update information across advisor systems. Focal says its platform supports more than 130 integrations and can populate more than 400 fields in Conquest, taking the product well beyond meeting notes into CRM, financial planning, onboarding and administrative workflows.
Data points. Deloitte says 73% of advisory firms already use AI in some capacity, yet only 6% use agentic tools and just 5% have connected AI across systems. Focal is entering the much earlier part of wealth management AI adoption, where the software starts completing work rather than simply generating content.
Focal's Canadian platform handles meeting preparation, notes, follow up emails, CRM updates, planning data, forms and client deliverables. Its current Canadian product page lists Salesforce, Equisoft, Maximizer, Conquest, Microsoft Dynamics 365 and other advisor systems among more than 130 supported integrations, while its browser agent can populate 400+ Conquest fields using structured client information.
The practical difference appears after a client conversation. Instead of an advisor copying the same information into a CRM, planning tool and forms, Focal is designed to carry approved information into those systems and complete related administrative steps. Equisoft's Focal integration provides a concrete example where meeting summaries and selected tasks can flow into Equisoft/connect, while advisors review which extracted tasks are written into the CRM.
Focal's published Canadian Pro price is US$100 a month when billed annually, with enterprise pricing available by consultation. The Pro plan includes unlimited meetings, CRM integrations and the Conquest AI overlay, while custom workflow automations and AI agents for tasks such as onboarding sit in the enterprise offering.
Deloitte estimates advisors spend nearly 70% of their time on work behind the scenes and only about 30% building client relationships. Focal says users can reclaim 10 to 15 hours a week, although that remains a company claim rather than an independently measured productivity result.
Deloitte's 2026 analysis models roughly 30% to 100% higher advisor capacity by 2032 as AI, workflow redesign and technology maturity advance together, potentially freeing 25% to 50% of advisor time from lower value operational work. These are modeled scenarios rather than adoption forecasts, but they put a number on the economic prize if AI can reliably take work out of the advisor's day.
Canada is already producing operating evidence beyond Focal. In March, OneVest launched an AI native wealth operations platform spanning onboarding, account opening, fund movements, billing and document workflows. In a different financial services setting, Scotiabank reported more than 71,000 employees with access to its AI capabilities and 14 million AI actions since March 2026, showing that governed AI can reach substantial operational scale inside a Canadian financial institution.
More automation doesn't remove the advisor or dealer from the regulatory equation. The Canadian Investment Regulatory Organization's 2026 Compliance Report says its examinations will ask dealers about AI use and review the operational controls they have implemented to make sure those systems work as designed. CIRO also tells dealers to consider whether AI or automation of regulatory functions constitutes a material business change requiring advance notification.
Focal says its enterprise agents use human review controls. The Equisoft integration shows one version of that model by allowing advisors to review tasks before information is pushed into the CRM, and available Focal materials don't establish that its agents independently make suitability decisions or provide regulated financial advice. NCFA's recent guide to AI governance for Canadian financial advisors reaches the same practical point.
Firms remain responsible for supervision, privacy, recordkeeping, vendor oversight and the decisions made with the technology they adopt.
Focal also says its Canadian service uses Microsoft Azure infrastructure in Toronto, holds SOC 2 Type II certification, stores no meeting audio or video and doesn't use client conversations to train AI models. Those claims can reduce some vendor review concerns, but Canadian firms still need their own controls over data access, records, approvals and errors.
Focal has already secured useful distribution. The company says it was selected as a trusted AI partner for Financial Horizons' network of 7,000 advisors, while a separate partnership made Focal available to Designed Wealth Management's network of 180 advisors. Those figures describe potential network reach, not 7,180 active users, and shouldn't be treated as adoption numbers.
The company also raised a US$5 million seed round in October 2025, led by Distributed Ventures and Wischoff Ventures. At that point Focal was already building beyond meeting software into form filling, data entry, onboarding and know your client workflows, so the September 2026 launch is a continuation of a product strategy that predates the current agentic AI push.
Competition is substantial. Jump can take approved actions across meetings, email, CRM and financial planning systems, Zocks automates forms and CRM workflows, and Salesforce is adding AI agents to its financial services platform. As those capabilities become more common, Focal's Canadian case depends less on access to AI itself and more on integrations, local distribution, data infrastructure and how deeply its software becomes part of daily advisor work.
Focal's launch is more proof of where Canadian wealthtech is heading, but the numbers also show how early this market remains. Companies already know how to buy AI assistants. The current evolution is whether agentic products can complete enough real work across existing systems to improve advisor capacity without creating an equal burden of checking, correcting and supervising the automation.
If AI can reclaim a meaningful share of the nearly 70% of advisor time now spent behind the scenes, how much of that work will Canadian wealth firms actually be willing to delegate?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
Sep 8, 2026
Futures trading strategies are repeatable plans for entering, managing, and exiting a leveraged contract. The useful strategy is not the one with the most indicators; it is the one whose market condition, trigger, invalidation, position size, and exit process are clear before an order is placed. Leverage can increase exposure without improving the odds of being right, so risk design matters more than a dramatic setup.
This guide is for readers who want a structured way to compare futures approaches before using real capital. It focuses on decision rules, operational checks, and failure modes. It does not issue trade calls, promise returns, prescribe leverage, or give a universal stop-loss or position-size threshold. Futures may not suit every reader, and product rules differ by venue and jurisdiction.
A trading idea becomes a strategy only when it can be tested before and after execution. At minimum, write down the market condition, entry trigger, invalidation level, position size, and exit plan. If one of these is missing, the decision is often an opinion about direction rather than a repeatable method. The same framework underlies a practical guide to futures trading strategies: define the conditions and failure point before considering leverage.
| Strategy component | Question to answer before entry | Why it matters |
| Market condition | Is the market trending, ranging, or unusually volatile? | A setup can fail when the surrounding structure changes |
| Entry trigger | What observable event turns the idea into a trade? | Prevents entries based only on urgency or prediction |
| Invalidation | What price or condition shows the thesis is wrong? | Defines when the original premise no longer applies |
| Position size | How much can be lost if invalidation is reached? | Links exposure to the planned loss rather than available margin |
| Exit plan | How will profit, time, or changing conditions be handled? | Prevents improvisation after the position is open |
The order of operations matters. Start with the condition and invalidation, then calculate size. Choosing a large position first and searching for a stop later reverses the risk decision. A platform may show that a small margin requirement controls a large notional position; the account is exposed to the notional movement, not merely to the margin displayed on screen.
A trend pullback approach waits for a temporary move against an established direction and then looks for evidence that the original structure is resuming. Its central risk is mistaking a reversal for a pullback. Define the structure that must remain intact, such as a sequence of relevant highs and lows or a clearly observed support area. A price moving back toward that area is not enough on its own.
A breakout setup starts with a well-defined range or boundary. Instead of entering on the first move through the level, some traders wait to see whether the old boundary holds after the break. The retest can reduce the need to chase, but it also creates a second failure mode: price may continue without returning, or the apparent breakout may quickly fall back into the range. The rule should say what would count as acceptance, rejection, or no trade.
When price repeatedly turns inside a range, a range approach looks for entries near an edge and exits closer to the middle or opposite boundary. The premise fails when price accepts beyond the range. Range logic should not be applied automatically because a level held once or twice; the more often a boundary is tested, the more important it becomes to define what evidence would show the range is weakening.
Sometimes the strategy is to stay out. Scheduled data, funding settlements, contract expiry, technical outages, or thin liquidity can make fills and stops less predictable. Skipping a trade when the loss cannot be estimated is a valid risk decision, not a missed opportunity. A method that excludes uncertain conditions may produce fewer trades and a clearer review record.
The four families are not mutually exclusive, but mixing them without a written condition can create hindsight. A trader may call a position a breakout when it works and a pullback when it fails. Name the setup before entry so the result can be evaluated against the same rule.
Leverage changes the amount of exposure controlled with a given margin; it does not make a trade more likely to work. Estimated risk for a simplified linear contract can be represented as:
Position size x distance from entry to invalidation + expected fees and slippage
The formula is a planning aid, not a guarantee. Contract specifications, funding, mark-price rules, liquidation mechanics, and execution gaps can change the result. Check the venue's documentation and use assumptions that reflect the instrument rather than treating a generic calculator as precise.
Use a loss limit chosen before the trade and keep it separate from the platform's maximum leverage. The exact amount is personal and depends on capital, experience, and obligations; the important rule is that several losses should not force a change in behavior or create a liquidation emergency. If a wider invalidation distance increases the planned loss, reduce the position size or reject the setup rather than quietly accepting a new risk.
Liquidation is a venue risk-control event, not a planned exit. A position that only fails at liquidation gives normal volatility almost no room and may close at a worse price than expected. A planned invalidation should be meaningfully reached before liquidation becomes relevant, with enough available margin to account for ordinary movement and fees.
Use this process for any proposed position, regardless of whether the idea is trend, breakout, range, or event-driven:
The last step protects against a common mistake: judging a strategy from one win or one loss. A valid process can lose, and a flawed process can win by chance. Evaluation requires a documented set of comparable examples across different conditions.
Market dashboards can help a trader identify where attention and volatility are concentrated. A view of crypto market losers may reveal assets experiencing sharp declines, but a ranking does not explain whether the move reflects news, liquidation, thin liquidity, or a broad market shift. It is a starting point for investigation, not a short signal.
Before using a market ranking in a futures plan, check the instrument, venue, contract type, quote currency, time window, and available liquidity. A spot decline does not map perfectly to a perpetual-futures position, and the most visible loser may have a spread or funding profile that makes the trade unsuitable. Keep the market observation separate from the execution rule.
The same discipline applies to headlines and social commentary. A story can explain why a market moved without telling you where the move is invalidated or whether the contract can be traded at the displayed price. Use external information to update the condition, then return to the written plan and decide whether the setup still qualifies.
The most frequent futures errors are process errors: beginning with leverage, moving a stop farther away, treating margin as total risk, ignoring fees and funding, and trading every visible price move. A strategy should exclude most market noise. If every movement creates a reason to enter, the rule is probably describing emotion rather than a condition.
Jurisdictional protections, margin rules, fees, and product availability vary. Some contracts have funding payments, some have expiry, and some use mark prices that differ from the last traded price. Read the venue's terms and seek professional advice for questions about suitability, tax, or local regulation.
There is no universally best method. Trend, breakout, range, and avoidance approaches suit different conditions and can each fail. A useful strategy is one with defined conditions, invalidation, sizing, costs, and review rules.
Beginners can learn how futures work, but leverage, liquidation, and rapid price changes make the product high risk. Simulation or carefully limited practice can reveal operational mistakes before they become expensive. Learning the contract is not the same as being ready to trade it.
There is no universal answer. Choose exposure only after defining the loss you can accept, the invalidation distance, and the contract rules. The maximum offered by a venue is not a risk recommendation.
No. A strategy can have a high win rate while one large loss erases many small gains. Review the size of wins and losses, costs, drawdowns, execution quality, and performance across different market conditions.
When the market condition is unclear, liquidity is thin, an event can change the price faster than the plan can respond, or the loss cannot be estimated reliably. Waiting preserves the ability to evaluate a clearer setup later.
Futures trading strategies are useful only when they turn a market view into a complete decision: condition, trigger, invalidation, size, costs, and exit. Trend pullbacks, breakouts, ranges, and event avoidance each have a place, but none is permanently superior. Start with the loss you can explain, keep liquidation outside the plan, and review execution rather than celebrating isolated outcomes. In leveraged markets, a strategy is defined as much by the trades it rejects as by the trades it takes.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016