




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Aug 2, 2023

Money today is different than it was five years ago. It's more nimble, secure, online, and democratized. The transformation of the financial landscape has been fueled by the expansion of eCommerce, contactless payments, and the rise of digital wallets. This evolution has positioned prepaid virtual cards at the forefront of the payment industry, particularly in the Asia-Pacific (APAC) region.
Prepaid virtual cards are digital payment solutions that can be deployed in a widespread manner or surgically, making them an attractive option across various use cases and segments. They hinge on three aspects:
Despite the potential, prepaid virtual cards come with challenges, including fraud, security, and cyber threat risks. FinTech startups may face difficulties in meeting the level of governance controls needed to scale a prepaid solution. The cost of acquiring these issuances is also rising due to the competitive nature of the space.
However, partnerships with established providers can help FinTechs work within payment schemes by providing security around settlement and supporting multi-currency operations. Such collaborations can unlock the benefits of virtual cards in a secure yet agile way, enabling FinTech eMoney issuers to leverage innovative prepaid processing platforms.
The virtual prepaid card trend is not just a fleeting phenomenon; it's a global trend driven by digitalization. It offers a promising avenue for FinTechs, businesses, and unbanked populations. By tapping into this opportunity, FinTechs can play a pivotal role in shaping the future of payments, making them more accessible, secure, and efficient. Collaborations, innovation, and adherence to regulatory standards will be key to unlocking the full potential of this burgeoning industry.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Aug 1, 2023

Image: Pixabay/lucasgeorgewendt
Buying an existing business in Canada can be a rewarding venture, providing you with a head start in the world of entrepreneurship. However, this decision requires careful consideration and meticulous planning to ensure a successful and profitable investment. In this comprehensive guide, we will explore essential tips and considerations for buying an existing business in Canada. Whether you're a seasoned entrepreneur or a first-time business buyer, this article will equip you with the knowledge and insights to make an informed decision and navigate the acquisition process with confidence.
To embark on a successful business acquisition journey, it's crucial to familiarize yourself with the Canadian business landscape. This involves understanding the various industries, market trends, and economic conditions. Conduct thorough market research and identify sectors with growth potential and a sustainable future.
1. Analyzing Your Business Goals and Expertise
Define your business goals and assess your expertise. Carefully examine business for sale in Canada and determine the type of business you want to buy, considering your skills, experience, and passions. Align your objectives with the industry that complements your strengths and interests.
2. Conducting a Comprehensive Due Diligence
Before finalizing any deal, conduct a rigorous due diligence process. Examine the financial records, contracts, legal documents, and assets of the target business. Verify the accuracy of the information provided by the seller to avoid unpleasant surprises after the acquisition. Due Diligence requires preparation and knowledge.
3. Seeking Professional Advice
Consider engaging professionals to support you throughout the acquisition process. Seek advice from experienced business brokers, lawyers, accountants, and financial advisors. Their expertise will prove invaluable in making informed decisions and ensuring a smooth transition.
4. Negotiating the Purchase Price and Terms
Negotiating the purchase price and terms of the acquisition is a critical aspect of the process. Be prepared to engage in constructive negotiations with the seller. Aim for a fair price that reflects the true value of the business and its potential for growth.
5. Understanding Legal and Regulatory Requirements
Navigating the legal and regulatory landscape is essential when buying a business in Canada. Familiarize yourself with federal, provincial, and municipal regulations. Obtain the necessary permits and licenses to operate the business legally.
6. Assessing the Business's Reputation and Customer Base
Evaluate the reputation and customer base of the business you intend to buy. A loyal and satisfied customer base can significantly impact the success of your ownership. Look for businesses with a strong brand presence and positive online reviews.
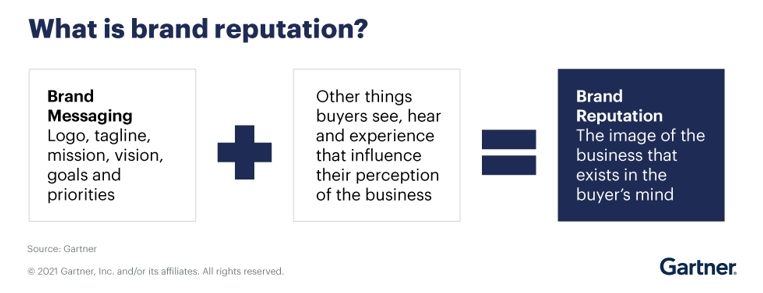
Image by: Gartner
7. Analyzing the Financial Health of the Business
Thoroughly assess the financial health of the business. Examine its cash flow, profitability, debt obligations, and expenses. Consider hiring a financial expert to help you interpret the financial statements accurately.
Liquidity is a fundamental aspect when evaluating a company's overall financial well-being. It refers to the company's capacity to meet its short-term debt obligations through its cash and easily convertible-to-cash assets. Before a company can thrive in the long run, it must first ensure its survival in the short term.
The two primary metrics used to gauge liquidity are the current ratio and the quick ratio.
Among these two, the quick ratio, also known as the acid test, is the more conservative measure. It excludes inventory from assets and the current portion of long-term debt from liabilities. As a result, it offers a more practical and realistic indication of a company's ability to manage short-term obligations using available cash and assets. If the quick ratio falls below 1.0, it often serves as a warning sign, indicating that the company's current liabilities outweigh its current assets.
Current ratio calculations use a simple formula:
Current Ratio = Current Assets ÷ Current Liabilities
Quick Ratio = (Cash + Cash Equivalents + Liquid Securities + Receivables) ÷ Current Liabilities
From the example above, a quick recalculation shows your firm now holds $150,000 in current assets while the current liabilities remain at $100,000.
The firm's quick ratio is : 150,000 ÷ 100,000 = 1.5
8. Reviewing Existing Contracts and Agreements
Review all existing contracts and agreements the business is a party to. This includes leases, supplier contracts, and customer agreements. Be aware of any clauses that may impact the business's operations or future plans.
9. Evaluating the Business Location
The location of the business plays a crucial role in its success. Evaluate the demographics, foot traffic, and accessibility of the location. A strategic location can contribute to increased sales and growth opportunities.
A good business location aims to provide an advantage to your business by creating a balance among:
Some examples of good business locations include the M4 corridor for tech companies, tourist attractions for hotel businesses, and the city centre for coffee shops.
10. Understanding the Staff and Human Resources
Assess the skills and experience of the existing staff. Determine if their expertise aligns with the needs of the business. Understanding the human resources aspect will help you plan for potential staffing changes and training requirements.
11. Analyzing Technology and IT Infrastructure
In today's digital age, technology plays a significant role in business operations. Evaluate the existing IT infrastructure and technological assets. Consider any necessary upgrades to streamline processes and stay competitive.
12. Calculating the Return on Investment (ROI)
Calculate the potential return on investment (ROI) for the business. Project the financial performance based on your plans and strategies. A positive ROI is a key indicator of a successful acquisition.
The return on investment (ROI) formula is as follows:
ROI=Current Value of Investment−Cost of InvestmentCost of Investment
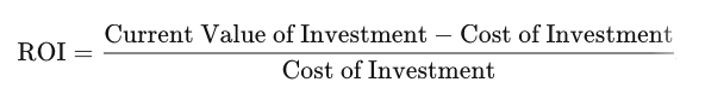
13. Assessing Market Competition
Analyze the competitive landscape of the industry. Identify key competitors and understand their market share. Develop strategies to differentiate your business and gain a competitive advantage.
14. Creating a Solid Business Plan
Develop a comprehensive business plan that outlines your vision, goals, and strategies. Include detailed financial projections and a timeline for achieving milestones. A well-structured business plan will instill confidence in potential investors or lenders.
Start with One Page executive summary: Free Template
15. Securing Financing Options
Explore various financing options to fund the acquisition. This may include personal savings, bank loans, or venture capital. Ensure you have a clear understanding of the financing terms and interest rates.
16. Preparing for a Smooth Transition
Plan for a smooth transition to avoid disruptions in business operations. Collaborate with the existing owner and key staff to ensure a seamless handover. Communicate with customers, suppliers, and stakeholders about the change in ownership.
17. Embracing Innovation and Growth
Be open to embracing innovation and implementing growth strategies. Identify opportunities to expand the business and diversify revenue streams. Innovation is key to staying relevant in a dynamic business environment.
18. Emphasizing Customer Experience
Prioritize customer experience to build brand loyalty and drive repeat business. Excellent customer service can differentiate your business from competitors and contribute to long-term success.
19. Managing Risks and Contingency Planning
Understand the risks associated with the industry and develop contingency plans. Being prepared for unexpected challenges will demonstrate your ability to navigate adversity effectively.
20. Building a Strong Team
Assemble a strong team of dedicated individuals who share your vision and values. A cohesive and motivated team can drive the business towards its goals and foster a positive work environment.
21. Fostering a Positive Organizational Culture
Cultivate a positive organizational culture that promotes teamwork, innovation, and employee satisfaction. A healthy work culture contributes to higher productivity and employee retention.
22. Tracking and Measuring Progress
Implement systems to track and measure the progress of your business. Analyze key performance indicators (KPIs) regularly to make data-driven decisions and stay on course towards your objectives.
23. Staying Compliant with Taxation and Accounting Requirements
Comply with Canadian taxation and accounting requirements to avoid legal issues. Consider hiring a qualified accountant to manage tax matters and maintain accurate financial records.
Acquiring an existing business in Canada can be a transformative step towards entrepreneurial success. By following the comprehensive tips and considerations outlined in this article, you'll be well-equipped to make a strategic and informed decision. Remember to conduct thorough research, seek professional advice, and invest in due diligence to ensure a smooth and successful acquisition process. Embrace innovation, prioritize customer experience, and foster a positive work culture to set the foundation for long-term growth and prosperity in your new business venture.
Q: What are the advantages of buying an existing business in Canada?
A: Buying an existing business in Canada offers several advantages. Firstly, you inherit an established customer base, brand reputation, and operational framework, saving you time and effort in building from scratch. Secondly, the business already has a proven track record, making it easier to secure financing. Additionally, the existing staff and management bring valuable experience and insights, contributing to a smoother transition and increased chances of success.
Q: How do I find businesses for sale in Canada?
There are several ways to find businesses for sale in Canada. You can engage business brokers who specialize in buying and selling businesses. Online marketplaces and classified advertisements also list businesses for sale. Networking within your industry or seeking recommendations from professional associations can lead you to potential acquisition opportunities.
Q: What legal documents should I review during due diligence?
A: During due diligence, you should review a range of legal documents, including business contracts, lease agreements, supplier contracts, customer agreements, permits, licenses, and any pending litigation. It's crucial to have a clear understanding of the legal obligations and potential liabilities of the business.
Q: How can I calculate the fair purchase price for the business?
A: Calculating the fair purchase price involves evaluating various factors such as the business's financial performance, industry trends, growth potential, assets, and market competition. Engaging a professional business appraiser can provide you with an objective valuation and help you negotiate a fair price.
Q: What are some common challenges when buying an existing business?
A:Buying an existing business comes with its share of challenges. Some common hurdles include negotiating the purchase price, conducting thorough due diligence, managing the transition process, and retaining key employees and customers. Understanding and addressing these challenges early in the process can lead to a more successful acquisition.
Q: How long does the business acquisition process typically take?
A: The timeline for completing a business acquisition can vary significantly depending on the complexity of the deal and the industry. On average, the process can take anywhere from a few months to a year or more. It's essential to be patient and prioritize thoroughness over rushing the process.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Tech Trends | Jul 30, 2023

Image: Unsplash/Adi Goldstein
The first half of 2023 has seen a resurgence of enthusiasm about technology’s potential to catalyze progress in business and society. To help executives track the latest developments, the McKinsey Technology Council has identified and interpreted the most significant technology trends unfolding today.
1. Generative AI: The Next Frontier: Generative AI, a new entrant in the tech trends, represents the next frontier of AI. It has high potential and applicability across most industries, including finance. Generative AI is poised to add as much as $4.4 trillion in economic value from a combination of specific use cases and more diffuse uses—such as assisting with email drafts—that increase productivity. However, firms should not underestimate the economic significance and the growth potential that underlying AI technologies and industrializing machine learning can bring to various industries.
2. Trust Architectures and Digital Identity: Trust architectures and digital identity grew the most out of last year’s 14 trends, increasing by nearly 50 percent as security, privacy, and resilience become increasingly critical across industries. This trend is particularly important for fintech and banks, which handle sensitive customer data and need to ensure its protection.
3. Cloud and Edge Computing: Despite a decline in investment, cloud and edge computing continue to be critical technologies for the finance industry. These technologies have applications in most industries, and mainstream adoption is expected to continue to grow. More than 400 edge use cases across various industries have been identified, and edge computing is projected to win double-digit growth globally over the next five years.
4. Quantum Computing: Quantum computing continues to evolve and show significant potential for value creation. The four industries likely to see the earliest economic impact from quantum computing—automotive, chemicals, financial services, and life sciences—stand to potentially gain up to $1.3 trillion in value by 2035. For the finance industry, quantum computing could revolutionize areas like risk modeling and fraud detection.
5. Tech Talent Dynamics: The demand for tech talent far outstrips supply, with many of the skills in greatest demand having less than half as many qualified practitioners per posting as the global average. This talent crunch is particularly pronounced for trends such as cloud computing and industrializing machine learning, which are required across most industries. For fintech, banks, and financial service providers, attracting and retaining tech talent will be a key challenge in the coming years.
While these trends present significant opportunities, they also pose challenges. Organizations should adopt a balanced approach, focusing on a portfolio-oriented investment across the tech trends most important to their business. By doing so, they can capitalize on both established and emerging technologies to propel innovation and achieve sustainable growth.
Regulatory Compliance: The financial sector is one of the most heavily regulated industries. Fintechs, banks, and financial service providers must ensure they are compliant with all relevant regulations, including those related to data privacy, anti-money laundering (AML), and Know Your Customer (KYC) protocols. As regulations evolve, particularly in response to new technologies and cybersecurity threats, staying compliant will require ongoing attention and resources.
Cybersecurity: With the increasing digitization of financial services, cybersecurity threats are a significant concern. Financial institutions must invest in advanced security measures to protect sensitive customer data and maintain trust. This includes not only technological solutions but also employee training and the development of a strong security culture.
Customer Experience: In an increasingly competitive market, providing a superior customer experience is crucial for retaining customers and attracting new ones. This includes seamless digital experiences, personalized services, and excellent customer support. Financial institutions need to leverage data and technology to understand their customers better and meet their evolving expectations.
Innovation and Digital Transformation: The financial sector is undergoing rapid digital transformation, driven by emerging technologies like AI, blockchain, and cloud computing. To stay competitive, financial institutions must embrace innovation, which may involve partnering with fintech startups, establishing digital innovation labs, or investing in R&D.
Sustainability and Social Responsibility: There is growing pressure on businesses to demonstrate their commitment to sustainability and social responsibility. For financial institutions, this could involve offering green finance products, investing in sustainable businesses, and ensuring their operations are environmentally friendly. Additionally, they need to consider their role in the broader community and how they can contribute positively to society.
The call to action is clear: Embrace the technological revolution, invest in talent, prioritize customer experience, and uphold the highest standards of security and regulatory compliance. Moreover, financial institutions must recognize their role in society and strive to contribute positively through sustainable and socially responsible practices.
Sean Gerety, IT Consultant:
"The technology you use impresses no one. The experience you create with it is everything."
The future belongs to those who are prepared to adapt, innovate, and lead. Now is the time for fintechs, banks, and financial service providers to step up, seize the opportunities presented by these trends, and shape the future of the financial industry.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Video | Jul 21, 2023

Image: Solid World website
DeFi is revolutionizing approaches to climate change solutions, delving into innovative financial models that promote sustainability while creating new opportunities for investment in a greener future.
Stenver Jerkku, the CEO of Solid World, is at the forefront of this revolution. With a background in urban space and venture-backed tech businesses, Jerkku is now focused on building capital markets to solve climate financing. His current venture, Solid World, aims to tackle the significant issues in the carbon industry, particularly in the voluntary carbon market which is primarily driven by investor pressure to decarbonize portfolios.
Companies are encouraged to reduce their emissions, but to become entirely carbon neutral, they often resort to carbon credits in the voluntary carbon market. These credits involve paying someone else to reduce their emissions or sequester emissions out of the atmosphere.
However, the carbon market faces significant challenges. The current market structure is nontransparent and unstructured, making it difficult for companies and investors to navigate. This lack of transparency and standards is holding back capital and preventing the market from reaching its potential.
To address these issues, Solid World is working on creating standards and transparency in the market. They have developed a risk due diligence framework for evaluating projects and are planning to open-source their underwriting methodology. Additionally, Solid World is creating liquidity pools to structure and price different types of assets, making the market more accessible and understandable for investors.
Several other companies are also contributing to this regenerative finance world. For example:
The intersection of DeFi and climate change presents a new era of sustainable finance. By harnessing the power of DeFi, we can tackle climate change more effectively, promoting sustainability and creating new opportunities for investment in a greener future. As companies like Solid World continue to innovate and push for transparency and standards in the carbon market, we move one step closer to a sustainable future.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 20, 2023

The self-storage industry has seen a surge in growth in recent years. As more people downsize, move, or simply look for extra storage space, the need for convenient, reliable self-storage solutions is on the rise. But while a strong customer base is crucial, the self-storage industry also thrives on partnerships. This article explores five key partnerships that every self-storage business should be fostering to enhance their operations, customer service, and ultimately, their bottom line.
The self-storage industry is multifaceted. It's more than just offering a space to store items; it’s about providing solutions for a variety of needs – moving, downsizing, renovating, or safeguarding valued possessions. Given its broad scope, it’s a sector that naturally dovetails with other industries. By forging strategic partnerships, self-storage businesses can expand their service offerings, elevate their customer experience, and tap into new customer bases.
To begin with, partnerships enable self-storage businesses to provide more holistic solutions to their clients. For instance, partnering with a moving company means that a customer can secure moving services and storage in one fell swoop, reducing stress and simplifying logistics. Similarly, a partnership with a property management company could provide clients with storage solutions during renovations or between leases.
These partnerships can lead to reciprocal referrals, driving business growth. Each business can recommend the other’s services to its clients, creating a win-win situation where both parties benefit from an expanded client base. The cross-promotion potential is enormous and can go a long way in boosting brand visibility and trust.
Strategic partnerships also help in risk sharing and cost reduction. When businesses join forces, they can negotiate better deals, share marketing costs, and pool resources to meet common goals. This can be especially beneficial for smaller self-storage businesses looking to compete with larger, more established entities.
Partnerships give self-storage businesses an opportunity to enhance their customer service. By providing additional services through partnerships, businesses can exceed their customers’ expectations, increasing customer satisfaction and loyalty. In the self-storage industry, where competition is fierce, superior customer service can set a business apart.
The self-storage and moving industries are intrinsically linked. People who are moving often need temporary storage for their belongings during the transition. By partnering with local moving companies, self-storage businesses can offer a seamless, comprehensive service that eases the burden of moving.
Moving companies are typically the first point of contact for individuals who are relocating. They can serve as a referral source, directing clients to partner self-storage facilities. The opposite also holds true: self-storage businesses can recommend their clients to trustworthy moving companies in the area, providing added value to their customers.
The two businesses can work together on shared marketing efforts. This could involve co-hosting local events, offering package deals, or advertising each other's services on their respective websites and social media platforms. Shared marketing can significantly increase visibility and awareness for both businesses.
A partnership with a moving company can also extend the reach of a self-storage business. For instance, a moving company that serves multiple cities or states can introduce the self-storage business to a wider geographical market. This opens the door to increased revenue and potential business expansion.
Working with a moving company can help a self-storage business cater to niche markets. For instance, some people require storage solutions when moving antiques or valuable items. By partnering with a specialist moving company, a self-storage business can offer secure, climate-controlled units that meet these unique needs.
A well-established relationship with a moving company can lead to a higher level of trust from customers. When businesses collaborate and recommend each other, it’s a testament to their professionalism and reliability. This trust can translate into customer loyalty and repeat business.
Car shipping service providers are another potential partnership to explore. Individuals often need to store their vehicles for a variety of reasons - they might be moving, traveling for an extended period, or looking to keep a collector's car safe. Linking with a car shipping service can be a strategic move for self-storage businesses.
A self-storage business can offer space for cars while the car shipping service provider can handle the logistics of moving vehicles to and from the storage units. Together, they offer a full suite of services that caters to individuals' car storage and transport needs.
This partnership has a clear benefit of reciprocal referrals. Car shipping services can refer customers who need storage, while self-storage facilities can recommend the car shipping services to customers who need transportation for their vehicles.
As with moving companies, an auto transport company often serves a wide geographic area. By partnering with auto transport companies, self-storage businesses can tap into a larger market. This partnership could also help both businesses attract customers who have high-end or antique cars, a niche market that often requires both storage and shipping services.
Shared marketing efforts can amplify visibility and increase customer reach for both businesses. A self-storage business can advertise the car shipping service and vice versa, effectively doubling their marketing power.
Offering bundled services through a partnership can lead to competitive pricing, thereby attracting more customers. For instance, a discount could be offered to customers who use both the self-storage facility and the car shipping service, making it a more attractive option than using separate companies.
Offering unique services like car storage can help a self-storage business differentiate itself from competitors. By providing an additional service that caters to specific needs, it can carve out a niche in the market and gain a competitive edge.
Property management companies can be invaluable partners for self-storage businesses. They manage multiple properties, and their tenants often need storage solutions during moves, renovations, or when downsizing.
By building a relationship with property management companies, self-storage businesses can become the recommended choice for tenants in need of storage solutions. This direct line to potential customers can increase occupancy rates and drive revenue.
The partnership can also lead to exclusive deals for tenants, further incentivizing them to choose the partnered self-storage facility. For instance, special rates or discounts could be offered to tenants of the property management company. This not only benefits the tenants but also ensures a steady stream of customers for the self-storage business.
Property management companies often handle corporate leases and business rentals. By partnering with these companies, self-storage businesses can tap into the commercial storage market, offering solutions for storing inventory, office furniture, or equipment.
Again, shared marketing efforts come into play. Property management companies often have extensive marketing budgets and reach. Being featured in their newsletters, websites, or social media platforms can significantly boost visibility for a self-storage business.
This partnership can help a self-storage business establish itself as a community resource. By working closely with local property management companies, the business can position itself as a trusted, reliable service provider in the community, improving its reputation and potentially attracting more local customers.
Another advantageous partnership is with local suppliers of moving and packing supplies. Customers who utilize self-storage often need materials like boxes, packing tape, bubble wrap, and locks. By offering these materials on-site, a self-storage business can provide a more comprehensive service to its customers.
Working with local suppliers can help a self-storage business keep these supplies well-stocked without a significant upfront investment. The suppliers benefit from increased sales, and the self-storage business benefits by offering additional convenience to its customers.
This partnership could lead to the offering of package deals, such as a discount on packing supplies with the rental of a storage unit. This kind of package can make a self-storage business more appealing to potential customers, offering them a one-stop solution for their storage needs.
Featuring local suppliers' products can strengthen a self-storage business's community ties. Customers often appreciate businesses that support other local businesses, which can enhance a self-storage facility's reputation in the community.
By offering moving and packing supplies, a self-storage business can diversify its revenue streams. While rental income is the primary source of revenue, income from sales of packing materials can provide an additional financial cushion.
Beyond the more obvious partnerships, there are numerous other local businesses and institutions that could prove beneficial. Nursing homes, for instance, often have residents who need to store furniture or personal items. College dormitories face a similar situation, with students needing storage between semesters or during summer breaks. Car dealerships might need space to store extra inventory during promotional periods.
In these cases, offering tailored storage solutions can lead to an ongoing relationship with these institutions. Special discounts or rates could be arranged for their residents, students, or customers, creating a steady inflow of customers from these sources.
These partnerships can help a self-storage business tap into markets they might not have considered previously. For instance, partnering with a college can open up a recurring market of students who need storage solutions annually.
As with previous partnerships, shared marketing efforts can be beneficial. These institutions often have large networks and can introduce a self-storage business to a wide audience. Co-hosted events, shared advertising, or mutual referrals can be a boon for business.
In the same vein, these partnerships can help establish a self-storage business as a key community resource. By partnering with prominent local institutions, the business can strengthen its standing in the community and increase local recognition.
Partnerships like these can lead to the creation of specialized storage solutions. For instance, students might need short-term rentals, nursing home residents may require long-term solutions, and car dealerships might need large, secure spaces for their inventory. By tailoring its offerings to meet these unique needs, a self-storage business can differentiate itself from its competitors.
Cultivating partnerships can have far-reaching benefits for self-storage businesses. From enhanced service offerings and increased customer reach to shared marketing efforts and risk mitigation, the advantages are manifold. Whether it's partnering with moving companies, car shipping service providers, property management companies, local suppliers, or other community institutions, these collaborations can be a game-changer. As the self-storage industry continues to evolve, businesses that leverage these strategic partnerships will undoubtedly position themselves for long-term success and growth.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
HR Strategy | Jul 14, 2023

Image: Unsplash/Dylan Gillis
Consider implementing a skills-based approach to hiring, leveraging digital tools to streamline processes, and making continuous learning a cornerstone of your HR policy. Regularly revisit your talent profiles to ensure they align with your current needs, and don't overlook the potential for growth within your existing workforce.
In conclusion, the rapidly evolving technology landscape necessitates a shift in traditional HR practices, particularly for fintechs and enterprises. By implementing these strategies, organizations can not only attract top tech talent but also foster a resilient and engaged workforce, thereby accelerating their digital transformation journey and gaining a competitive edge in the market.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Update | Jul 14, 2023

Digital Commerce Calgary Fintech Award
The Calgary Fintech Award has announced the top 25 contenders for the prestigious Digital Commerce Calgary Fintech Award, showcasing the most innovative fintech solutions in Canada.
| Company Name | Brief Description | URL | Comparable Company |
|---|---|---|---|
| Accelerate Financial Technologies | A leading provider of alternative investment solutions. | accelerateshares.com | Wealthsimple |
| Bidmii | A renovation marketplace that guarantees payment security for each party. | bidmii.com | Homestars |
| Blossom | A social app for investors with over 30,000 Canadians sharing their portfolios, trades, and investing ideas. | blossomapp.ca | Mylo (Moka) |
| Calefy | Helps quote and bind insurance digitally. | calefy.com | Zensurance |
| Chata.ai | Builds an API-first solution that empowers financial industry users with easy-to-use self-service analytics. | chata.ai | Ada |
| Credit App Technologies | Building a credit application platform to challenge the monopolistic industry that connects Canada’s 4,000 automotive dealerships with over 60 lenders. | creditapp.ca | Lendful |
| Datz Solutions | Created the Datz RMS as a complete, connected brokerage operating system. | datzrms.com | Vertafore Canada (Keal) |
| DealPoint | Digitizes investor onboarding and investment execution, bringing efficiency to the complicated, paper-based process of fundraising. | dealpoint.io | FrontFundr |
| Elev | Streamlines the off-campus living experience for students and landlords. | elevliving.com | RentMoola |
| Expedier | The first Black led BIPOC focused digital bank in Canada. | expedier.ca | Koho |
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016