




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Oct 16, 2026 | Wealth Management, Retirement Planning, Personal Finance
Planning for retirement while living in a high-cost state like New York is even more important. Housing, healthcare, taxes and everyday expenses can go up and affect retirement.
Retirement planning aligns savings, investments, income, and future lifestyle goals. So, a retirement strategy should include a person’s location, income, assets, investments and expected retirement age.
Wealth management for pre-retirees in New York City can make the process much easier by working with financial planners.
Consider potential housing expenses, property taxes, utilities, transportation, and healthcare in New York. Also account for mortgage payments, rent, and other fixed expenses when planning retirement.
Moreover, you should consider whether downsizing or paying off a mortgage could help with long-term financial flexibility. Estimate essential expenses separately from discretionary spending.
Review workplace retirement plans, including 401(k) and 403(b) accounts. Traditional and Roth IRAs offer benefits if an individual is eligible. Diversifying investments and asset classes is key when planning for retirement.
Time horizon, risk tolerance, inflation, and withdrawal needs affect investment decisions. Review contribution levels, employer matching opportunities, and beneficiary designations. A retirement portfolio should gradually reflect changing income needs as retirement approaches.
Early retirement often requires a larger savings base and a longer withdrawal period. Retiring before age 65 can affect access to Medicare and the need for alternative health insurance. Withdrawals from certain retirement accounts before age 59½ may trigger income taxes and additional penalties. Highlight the importance of maintaining accessible savings outside tax-advantaged retirement accounts.
Stress-test retirement plans against inflation, market downturns, and unexpected expenses.
Social Security benefits, pensions, investment income, and retirement account withdrawals may be taxed differently. New York State usually provides a qualifying exemption for certain pension income for eligible taxpayers aged 59½ or older, subject to statutory limits and conditions.
Note that qualifying Social Security benefits are generally exempt from New York State income tax. Verify state and local tax obligations based on their residence and income sources.
Withdrawal sequencing and tax planning can influence how long retirement assets last.
Professional guidance helps coordinate investments, retirement income, tax considerations, and estate planning. Financial advisors for retirement planning can help develop a personalized strategy.
Understand an advisor's qualifications, fee structure, fiduciary obligations, and compensation model. Ask how often their plan will be reviewed and updated. Professional guidance can be particularly useful during major transitions, such as selling a business, receiving an inheritance, or preparing to leave full-time employment.
Looking for a financial planner in Brooklyn? Prestique Wealth focuses on professional guidance tailored to local circumstances.
Here is a retirement planning checklist to help you.
Retirement planning is an ongoing process, not a one-time calculation.
Effective retirement financial planning combines savings, investment management, tax awareness, and realistic budgeting. New York residents should account for local living costs and personal retirement goals. Revisit your plans as your circumstances and financial markets change.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Oct 16, 2026
Image: Unsplash/Karen Uppal
Wealth managers and enterprise founders are adopting flexible foundation vehicles in leading financial jurisdictions to safeguard international assets effectively. These legal frameworks give business families durable control over cross-border capital.
Running an international enterprise brings substantial operational reach, but cross-border wealth invites sudden legal exposure, tax friction, and succession disputes. When your commercial footprint spans multiple continents, managing assets through personal names or informal agreements leaves your life's work vulnerable to external shocks.
Forward-thinking business leaders now establish institutional holding structures designed to insulate capital across sovereign borders. Foundations in premier financial hubs combine corporate agility with structural preservation, giving your family firm a dependable platform for private governance.
Trusts historically served as the default choice for generational planning across common law nations. They separate legal ownership from beneficial enjoyment, which helps manage wealth distribution across successive generations.
Many international founders find standard trust mechanics too restrictive for dynamic commercial operations. Trustees hold ultimate legal title, meaning you must surrender day-to-day command over your underlying assets to an outside third party. Foundations solve this tension by operating as separate legal entities, blending the asset segregation of a trust with the structured decision-making of a private corporation.
Foundations own underlying assets in their own legal name because they possess standalone corporate status. When you choose to establish a foundation in ADGM as your primary holding structure, you preserve strategic oversight while separating personal risks from enterprise capital. That distinct legal boundary shields private investments from external disputes across different jurisdictions. Your chosen council administers daily tasks while strictly following your founder regulations.
You create the foundational charter, appoint the governing council, and outline your succession vision through bespoke bylaws. This arrangement prevents foreign courts from seizing operational companies during personal litigation, providing true insulation without stripping away commercial agility.
Global financial districts provide well-tested legal frameworks grounded in English common law. Their independent courts, digital registries, and clear statutory rules give wealth managers predictable enforcement mechanisms.
A research analysis from the Purdue University Daniels School of Business highlights that private wealth offices can maintain asset positions indefinitely, avoiding the forced divestment horizons typical of standard private equity funds. Operating within a respected global hub allows your family capital to hold strategic equity for decades without arbitrary regulatory disruptions. You gain direct access to sophisticated international banking corridors and world-class professional advisors.
International institutions scrutinize private capital structures with increasing rigor. Complex corporate wrappers without clear governance generate regulatory friction and complicate relationships with global investment counterparties.
A global survey published by the Harvard Law School Forum on Corporate Governance shows that major institutional capital providers demand accountability, operational transparency, and strict alignment with long-term enterprise value. Structuring your private holdings through a recognized foundation satisfies those institutional expectations by maintaining orderly council meetings, documented accounting trails, and transparent governance registers. That institutional credibility smooths cross-border transactions and builds confidence with institutional partners.
Integrating a foundation into your existing enterprise structure requires deliberate legal sequencing. You separate high-risk operating businesses from passive holdings, creating dedicated subsidiaries beneath the foundation canopy.
Holding structures work best when you divide assets by risk profile and geographic location. Trading companies, commercial properties, and liquid investment portfolios require individual corporate entities to isolate legal liabilities.
Structuring each asset class under dedicated holding companies isolates operational liability while leaving strategic stewardship firmly under council governance.
Passing control to the next generation frequently triggers internal conflicts if families leave succession rules ambiguous. Foundation bylaws eliminate this friction by spelling out voting privileges, distribution schedules, and leadership succession protocols before disputes arise.
You establish conditional distribution terms that support entrepreneurial initiatives among descendants rather than passive entitlement. Your wealth vehicle remains functional and self-governing, shielding family holdings from probate court delays across multiple countries.
Protecting cross-border wealth requires intentional governance structures built before external crises strike. Modern foundation frameworks give you legal security, administrative flexibility, and institutional standing to preserve your commercial legacy. When you align robust structural defenses with clear family bylaws, your enterprise navigates global market disruptions with lasting confidence.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 16, 2026 | Market Activity | Artificial Intelligence And Data, Lending Consumer Credit And BNPL, Competition And Market Structure
On October 15, 2026, Toronto-based Pineapple Financial launched Pentiv, a new operating brand and AI mortgage intelligence platform aimed at commercializing technology already used within its mortgage brokerage business. Its Recruitment Agent and Alternative Mortgage Renewal Agent operate within Pineapple+, while the new Pentiv platform is designed to bring those capabilities to independent brokerages and mortgage networks.
Pentiv also marks a change in Pineapple's business strategy. Rather than keeping its mortgage technology exclusively inside the brokerage, the company wants to commercialize tools developed through years of operating experience. The plan includes recurring software revenue and a potential separation of its technology and mortgage brokerage businesses, subject to corporate review and approvals.
Pentiv's Recruitment Agent helps brokerage managers identify promising mortgage professionals, prioritize outreach and organize recruiting activity. Its Alternative Mortgage Renewal Agent identifies upcoming or potentially at risk renewals, suggests customer outreach and helps manage supporting documentation. Both address recurring sources of revenue for brokerages: recruiting productive agents who originate new business and maintaining relationships with existing borrowers as their mortgages mature.
Pineapple has already reported results from its earlier AI recruiting initiatives. On May 5, 2026, the company reported adding 83 licensed agents to its national network since the beginning of the year. Management attributed part of that recruiting momentum to AI tools that shortened the process of bringing new agents from initial contact to active status. The result provides operating evidence behind Pineapple's recruitment strategy, although it doesn't establish how many hires were directly attributable to Pentiv's current application.
Renewals offer another source of commercial revenue. An alternative mortgage borrower may need new financing when a loan matures, particularly if income, property values or qualification requirements have changed. Brokers who identify those customers early have more time to discuss options, prepare documents and retain the relationship. Pentiv is targeting that work rather than replacing mortgage underwriting or loan origination systems.
The company has built both applications around workflows already used by Pineapple's mortgage professionals. This gives its developers direct feedback on where recruiting efforts stall, where customers need attention and which tasks consume staff time. The challenge in selling that technology externally is making it useful across brokerages with different systems, procedures and customer data.
Mortgage Professionals Canada's 2026 research found that 38% of recent homebuyers used a mortgage broker, up six percentage points from 2024. Among recent first-time buyers, broker use reached 48%. The survey also found that 83% of broker clients would recommend their broker and 72% of borrowers who used a broker for their current mortgage would use one again.
Mortgage software is already competitive. Filogix expanded Expert Pro renewal visibility in June 2026, enabling brokers to identify upcoming renewals associated with additional properties owned by existing borrowers. Pentiv will need to distinguish its intelligence tools from established mortgage software and demonstrate that they work effectively alongside systems brokerages already use. Its focus on professional recruiting gives it another area in which to compete.
Canada's banks are also investing in AI for mortgage operations, including TD's expansion of agentic AI. Pentiv is approaching the market from the brokerage side, where smaller firms often lack the resources to develop their own software. A commercially accessible intelligence platform could give those firms capabilities that would otherwise require significant internal technology investment.
The Pentiv announcement includes a corporate development with significant implications for investors. An October 15 SEC filing confirms that Pineapple's board established an independent special committee on October 9 to review a proposed restructuring. The plan contemplates separating the technology platform and digital asset treasury operations from the mortgage brokerage business, potentially followed by a brokerage spin-off. These proposals remain under review, with no completed separation announced.
Under the proposed arrangement, the brokerage could continue using Pentiv as an anchor customer while the technology business sells its applications more widely. That would preserve access to operating feedback while giving the software operation a different commercial focus. The arrangements governing technology ownership, customer data, licensing and financial relationships would become important parts of the proposed separation.
Usman Maher, Pentiv's newly appointed Chief Financial Officer and Chief Strategy Officer and a former SoFi executive, described the company's approach:
"We will prove the economics inside Pineapple, extend the platform to external brokerages, and scale adoption to build a durable intelligence company and long-term shareholder value."
Pentiv plans to report operating results from its recruiting and renewal applications, external brokerage pilots, customer agreements and recurring platform revenue over coming quarters. Pineapple Financial remains the legal reporting company, trading on NYSE American as PAPL, with a ticker change to PTIV anticipated around October 26, 2026. Its proposed corporate name change to Pentiv Inc. requires shareholder approval.
Pentiv's real commercial opportunity is turning proprietary brokerage experience into software that competitors are willing to pay for. Independent customer adoption, measurable financial returns and recurring revenue will determine whether Pentiv can command a valuation beyond its mortgage brokerage business.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 16, 2026 | Market Activity | Digital Banking, Lending Infrastructure, Embedded Finance
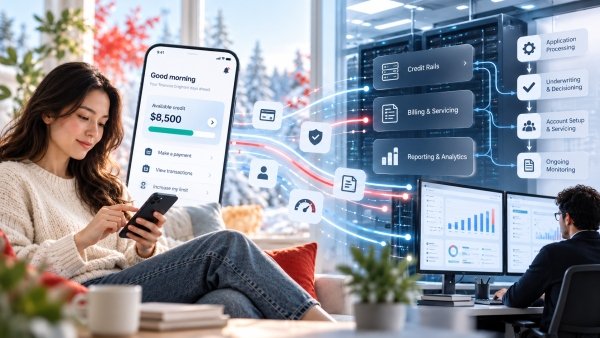
On October 14, 2026, Canadian fintech KOHO selected LoanPro's lending platform to support its next financial products across Canada. LoanPro will provide billing, servicing and reporting, while KOHO retains control of its mobile app and product design. The arrangement gives KOHO specialized credit infrastructure as it expands beyond everyday spending and savings into a broader range of financial products.
Founded in 2014, KOHO has served more than 2.5 million Canadians, according to the announcement. Its current services include credit building, instalment payments, cash advances and a revolving line of credit. Supporting these products requires more than a customer interface. KOHO needs systems that can manage repayment terms, account balances and servicing requirements as its credit offering grows.
KOHO Chief Product Officer Rusen Baragiola wants technology that can accommodate new financial products without limiting how the company designs them. LoanPro's platform provides configurable billing, account servicing and reporting, allowing KOHO to develop products within its own app while relying on specialist software to manage the underlying credit accounts.
"We chose LoanPro for the flexibility to bring new products to market quickly and responsibly."
KOHO already offers different repayment arrangements. Its Pay Later service allows eligible customers to divide purchases of up to $1,000 into payments over three, six or nine months. Its revolving line of credit allows borrowers to access funds as needed while paying interest only on the amount used. Each product requires its own billing rules, payment records and account management processes.
The LoanPro agreement also addresses a Canadian operating requirement. Credit products must accommodate applicable provincial rules, including those in Québec. LoanPro's configurable platform gives KOHO flexibility to adapt product terms and servicing processes across jurisdictions while maintaining a consistent experience in its app. For a company serving customers nationally, it's important as it introduces products with different repayment structures and eligibility requirements.
KOHO's existing line of credit provides a useful example of how the company works with lending partners. Eligible customers can access between $1,000 and $15,000 through Fora Credit, which handles underwriting, approval, funding and servicing. KOHO provides the customer relationship and digital access to the product.
How KOHO's lending responsibilities are currently divided:
| Company | Confirmed role | Product or arrangement |
|---|---|---|
| KOHO | Customer app, customer relationships and financial product design | Existing financial services and planned LoanPro supported offerings |
| LoanPro | Billing, credit servicing technology and reporting | New KOHO financial products under the October 2026 agreement |
| Fora Credit | Underwriting, credit approval, loan funding and servicing | Existing KOHO Line of Credit, offering $1,000 to $15,000 |
Sources: KOHO's published line of credit documentation and the October 14, 2026 LoanPro partnership announcement. The LoanPro agreement covers new offerings; it does not establish a change to Fora's existing responsibilities.
Fora is part of Toronto fintech lender Propel Holdings, which also operates the Freshline lending platform backed by a US$60 million financing agreement. KOHO already works with Fora to provide its line of credit, while LoanPro brings additional billing, servicing and reporting technology to support KOHO's next credit products. The two relationships serve different purposes within KOHO's lending business.
KOHO has served more than 2.5 million Canadians since 2014, giving it an established audience for new credit products. By keeping control of product design and the customer experience, KOHO can introduce different repayment options while relying on specialist partners for lending technology and operations.
KOHO's lending strategy raises a question about who controls the economics of consumer credit. A fintech may own the customer relationship, but its ability to set credit terms, approve borrowers and earn lending revenue depends on how responsibilities are divided with its partners. As KOHO expands, those arrangements could matter more to its competitive position than the technology powering the loans.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 15, 2026 | Market Activity | Banking Infrastructure, Embedded Finance, Open Banking and Consumer-Driven Finance
On October 15, 2026, Toronto fintech Flinks launched Professional Services and Managed Services to help banks and fintechs develop financial products and operate the technology supporting them. The expansion takes Flinks beyond financial data connectivity into building and maintaining banking capabilities, including payment integrations, account switching and embedded financial services.
Majority owned by National Bank of Canada, Flinks reports connectivity to more than 15,000 financial institutions and serves clients including EQ Bank, National Bank and Wealthsimple. The new offerings formalize work Flinks has already performed for institutional customers, combining project development with ongoing responsibility for integrations, technical support and service operations.
In an October 15 company article, Flinks Chief Revenue Officer Eddie Beqaj describes a project involving an unnamed Canadian bank and one of its business customers. The bank already supports account transfers, bill payments and Interac e-Transfer through its APIs. Its customer operates a software platform that collects payments from many organizations, but the money arrives through different channels, making it difficult to match payments with invoices.
The bank wants to connect those payment services directly to the customer's software so collections can flow through one banking relationship. That would simplify reconciliation for the customer while giving the bank an opportunity to attract and retain substantial commercial deposits. The payment technology already exists. Flinks' role is to make it work inside software the bank doesn't control.
Flinks says it completed a paid discovery phase and assigned a team to develop the integration. Its commercial value will depend on whether the software customer directs meaningful payment activity and balances through the bank.
There is a useful Canadian comparison. Dream Payments embedded payment capabilities into business software using J.P. Morgan's banking infrastructure. Dream provides payment execution and related controls within software applications. Flinks is helping a bank connect its existing payment services to a commercial customer's platform. Both approaches bring banking functions into applications businesses already use, although they serve different objectives.
Professional Services covers the work required to turn a banking capability into a product customers can use. Flinks helps define the business case, designs the integration and supplies developers to build it. The company incorporates security and regulatory requirements during development rather than leaving them until implementation.
Managed Services covers the work that follows launch, including partner onboarding, accreditation, consent management, technical support and service commitments. Flinks has brought its existing Flinks Outbound infrastructure into this offering. Institutions sharing financial data with external providers can use Flinks to manage those connections instead of maintaining separate integrations and operating relationships with every recipient.
Client requests helped drive the decision to formalize the services. Eddie Beqaj, Chief Revenue Officer, Flinks:
"Our clients kept bringing us ideas that weren't on anyone's roadmap, including ours."
Beqaj also cites work with a major Canadian bank to transfer customers' Interac e-Transfer contacts and bill payees when they switch accounts. Preserving those payment arrangements removes a practical obstacle to changing banks, particularly for customers with recurring payments and established recipients. The example connects to a larger question explored in NCFA's open banking intelligence hub. How can financial data portability lead to easier account switching and greater competition when customers still have to move their payment relationships?
Flinks is moving beyond banking connectivity to build and operate financial services for its clients. The opportunity is to turn custom bank projects into lasting customer relationships, but the real measure will be whether Flinks can reuse its technology across clients without repeatedly rebuilding the same integrations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 15, 2026 | Insight | Fintech Funding, Embedded Finance, Payments Infrastructure
On October 15, 2026, New York fintech Ramp announced US$1.85 billion in financing at a US$60 billion valuation, less than three months after expanding its corporate cards and financial operations platform into Canada. Ramp now serves more than 85,000 businesses and reports over US$2 billion in annualized revenue. Its growing financial resources raise the stakes for Canadian competitors Float, Venn and others, particularly as corporate cards, payments and expense software increasingly compete for the same business customers.
Ramp already sells more than corporate cards. Its platform combines spending controls, supplier payments, accounting automation and financial software, with new AI services extending its reach. The financing gives Ramp substantial resources to expand those products and compete for larger accounts, while Canadian fintechs face decisions about pricing, customer acquisition and which financial services they can profitably provide.
Dragoneer Investment Group led the primary financing round, with Thrive Capital, Founders Fund, Sands Capital and Avenir Growth as co-leads. Ontario Teachers' Pension Plan also participated. Ramp's valuation has risen from US$44 billion in June, when it raised US$750 million, bringing total equity financing to approximately US$5 billion.
Ramp reports more than US$275 billion in annualized purchase volume, up 175% year over year. Its enterprise customers generating over US$100,000 in revenue for Ramp increased 113%, indicating greater adoption among larger businesses. Ramp earns revenue through interchange, software subscriptions, interest and other services.
Ramp's US$60 billion valuation implies a valuation-to-annualized-revenue multiple below 30x, based on its reported revenue run rate of more than US$2 billion. That reflects substantial investor expectations for continued growth. Ramp also reports positive cash flow, although it hasn't disclosed sufficient financial results to establish sustained profitability.
More than half of Ramp's customers use at least two products, and one quarter use three or more. That gives Ramp opportunities to increase revenue from existing accounts while making its platform more useful to finance teams managing several functions. The company has also expanded into accounts receivable automation, AI spending controls and model cost management.
Its Router.com service selects AI models based on cost and performance, while AI Token Spend Management tracks spending across providers, teams and models. Eric Glyman, Ramp's co-founder and co-CEO, described the company's ambition in the financing announcement:
"AI opens up much more of the work it takes to run a company."
Greater product adoption may improve revenue per customer and retention, but investors will ultimately need evidence that those gains justify the company's development costs and valuation.
Ramp expanded its Canadian platform in July 2026, offering corporate cards, expense management, reimbursements, bill payments and accounting integrations. Peoples Trust Company issues its Canadian Visa cards. The platform supports CAD spending and virtual USD cards, giving eligible businesses another option for managing domestic and international expenses.
Ramp's Canadian eligibility requirements include a minimum C$25,000 across connected bank accounts. Businesses registered in Quebec and the territories aren't supported, nor are sole proprietorships and unregistered businesses. The restrictions narrow Ramp's initial addressable market and leave opportunities for providers serving those customers.
Toronto based Float competes directly in corporate cards, expense management, bill payments and business accounts. In June, it raised C$85 million in Series C financing to expand its AI finance capabilities and Canadian distribution. Float reports more than 7,500 business customers. Venn competes through corporate cards, multicurrency accounts, foreign exchange and international payments, targeting businesses that need banking and spending tools across currencies.
Ramp's reported customer adoption across multiple products points to a competitive challenge beyond fundraising. When one provider manages cards, expense controls and supplier payments, customers have more reasons to stay. A Canadian fintech offering only one of those services may need to demonstrate stronger functionality, better pricing or savings large enough to justify using another provider.
Ramp's capital could also give it more flexibility to bundle products or invest in customer acquisition. If that leads to lower software prices or more aggressive sales offers in Canada, competitors could face pressure on margins and acquisition costs.
Float and Venn's opportunities lie in the customers and financial requirements they can serve better, including Canadian banking services, domestic payment needs and businesses outside Ramp's current eligibility rules. Local presence has commercial value only when it delivers something customers will pay for or gives them a compelling reason to stay.
For Canadian fintech founders, the choices are increasingly specific. Expand into more financial services, concentrate on a profitable customer segment, or supply payments, integrations and risk controls to larger platforms.
Ramp's US$1.85 billion financing gives an established Canadian market entrant greater resources to compete for corporate spending and financial operations customers. Can Canadian fintechs earn and retain more revenue from each business customer without matching the capital demands of a US$60 billion competitor?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 15, 2026 | Cryptocurrency, Digital Assets, Crypto Exchanges, Market Analysis
Searching for top crypto exchanges by volume is a sensible way to find active venues, but it is a poor way to finish an exchange comparison. A volume number describes recorded turnover during a chosen interval. It does not tell a reader whether the pair they need is deep, whether the displayed price is executable, or whether the venue's terms fit their country and use case. This article looks at the gap between a busy platform and a usable market. It is not a platform ranking or a recommendation to deposit funds.
Volume counts transactions over a specified period, commonly in a quote currency. Activity can improve price discovery and provide more observations, but the number is affected by pair mix, spot or derivatives coverage, fee incentives, and the data provider's method. Two valid rankings can disagree simply because they count different things.
The top crypto exchanges by volume page is useful for making a shortlist. Before reading an order as a recommendation, check the interval, products included, quote currency, and venue coverage. A venue's total may include markets that a reader cannot access, or a product that is irrelevant to the intended task.
Execution lives at the pair level. A venue can be busy overall while a smaller asset has a wide spread and a thin book. The reverse is possible too: a modest venue may be the active place for a particular local-currency pair. Daily turnover is a record of past activity; depth and spread describe what is available near a price now.
The timing gap matters. A 24-hour volume figure and a spread observed this minute are different snapshots. A listing, service interruption, or regional session change can alter the relevant market between them. Record access times, and treat the lack of pair-level timestamps as a real limitation rather than filling it with an assumption.
A city analogy is useful here. A crowded city does not mean every street is open or easy to reach. Aggregate volume describes the city. The route that matters is the actual pair, product, order size, and time of day.
Consider a reader who wants to exchange a less widely traded asset for a local currency. A venue can sit near the top of an aggregate table because its major pairs and derivatives markets are active, yet the relevant local pair may have only occasional trades. The displayed total has not become false; it simply answers a different question. The reader needs to see the current bid and ask, the amount available close to each, the fee schedule, and any transfer or account restrictions that apply before treating the ranking as useful evidence.
This is where a small test order is sometimes discussed, but it is not a universal answer. Fees, withdrawal conditions, eligibility rules, and asset-transfer risks may make a test impractical or expensive. The broader point holds without one: a platform-wide figure should lead to pair-level research, and the details that determine execution should be current when the decision is made.
When a market moves, one venue may print a new trade before an aggregate page catches up. Market makers and arbitrage can narrow the gap, but they do not remove delays, fees, transfer constraints, or regional frictions. Differences can become more visible during fast conditions.
Comparing crypto market prices with a venue quote starts with matching the asset and quote currency. Then identify each number: last trade, bid, ask, midpoint, index, or derivatives mark. A $100 last trade beside a $99.60 bid and a $100.40 ask is not the same observation as a $100 midpoint.
Consider an illustrative snapshot. An aggregate index reads $99.80, while a venue's last trade is $100.30. The venue currently bids $99.90 and asks $100.40. That gap may simply be a trade near the upper edge of a spread. It deserves more scrutiny when it persists across several liquid venues, widens as the market moves, or prevents execution near the displayed quote. Even then, the observation is stronger than any untested accusation about its cause.
Price differences also change how a volume figure should be read. A large total in a pair that repeatedly trades away from other references may call for questions about methodology, concentration, and extraordinary-condition handling. It does not justify declaring that a venue is manipulating prices.
Trading communities influence attention long before an analyst writes a conclusion. A useful discussion may locate an outage notice, explain a technical change, or point to a user report that can be checked. The same social momentum can turn a ranking into proof by repetition: people choose a venue because it appears popular, and the popularity then becomes part of the story.
The phrase web3 social networks covers posts, group chats, live conversations, and creator-led communities. Their strongest use is often discovery and debate. A good contribution names its source, separates fact from opinion, and makes room for correction. A repeated referral code, screenshot, or confident price target does not become independent evidence simply because more accounts repeat it.
Online chatter can improve research when it leads to a service notice, a documentation update, or a detailed report with reproducible steps. It becomes harder to assess when incentives are hidden. Affiliates, project teams, market makers, and ordinary users can all emphasize a venue for different reasons. The answer is not to dismiss every comment; it is to make the incentive part of the reading.
Use sentiment to find questions. If many users mention withdrawal problems, check the venue's status page, terms, incident notices, and whether the disruption is regional or platform-wide. If a community celebrates volume, ask which pairs produced it and whether those pairs are relevant to the reader's task.
Crowd activity can be especially misleading when people share the same screenshot. A volume badge, a single trade print, or a price chart can spread quickly through a group, making one observation look like many independent reports. Look for different kinds of evidence instead: a timestamped status notice, a pair-level order book, a record from another venue, or documentation that explains a product change. Agreement becomes more meaningful when the sources are not all repeating the same original image.
For preliminary research, work through the following order. It keeps a single market metric from doing the work of an entire due-diligence process.
The highest total may be useful for observing a busy market. Another venue may offer the relevant pair, local access, or clearer operating terms. The right conclusion depends on the use case and evidence, not on the position of a row in a table.
For comparison writing, it also helps to keep an awkward result in the note rather than smoothing it away. A high-ranked venue may have the pair but a spread that is wider than a reader expected. A lower-ranked venue may show better visible depth at the moment, yet have conditions that require additional verification. Reporting both observations is more useful than forcing them into a single winner. Markets change by the minute; an honest comparison identifies the measured conditions and leaves room for them to change.
Volume says little about custody, account security, legal protections, tax treatment, or operational continuity. A venue can report substantial activity while its policies change, a product becomes unavailable, or access differs by region. Public rankings also update on their own schedule.
Liquidity is conditional. A tight spread in calm conditions may widen during news, and an order book that looks deep can thin as a larger order consumes visible levels. Compare the depth near the relevant price with the intended order size and urgency. Visible orders can also be cancelled, so a screen is not a promise of execution.
The careful takeaway is modest: use volume to locate research targets, then inspect the pair, the price definition, the operating terms, and the applicable rules. An aggregate ranking cannot establish that a venue is appropriate for a particular person or transaction.
No. The relevant price depends on the pair, quote currency, side of the market, order size, fees, and execution time. A high-volume venue can be competitive in one market and less useful in another.
No. It describes market activity, not custody arrangements, cybersecurity, legal compliance, solvency, or customer protections. Those questions need separate evidence and can vary across entities and jurisdictions.
They may use different venues, intervals, currency conversions, and price definitions. A last trade can also sit away from a current bid or ask. Compare methodology before calling the difference an error.
Treat it as a lead. Check the venue's official status page, timestamps, independent reports, and which product or region is affected. Do not share credentials, keys, or urgent instructions based on an unverified post.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016