




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


October 14, 2026 | Market Activity | Payments Infrastructure, Embedded Finance, SME Finance

On October 5, 2026, Dext launched Dext Payments in Canada, allowing small businesses and accounting firms to approve and pay supplier invoices and employee expenses directly within its bookkeeping software. The service connects invoice processing, approvals and payments for eligible QuickBooks Online and Xero customers across Canada, including Quebec. Dext reports that Canadian users processed more than $2 million in payments during beta testing.
The launch extends Dext's role from preparing financial records to executing supplier payments. It's an opportunity to earn additional revenue from existing customers, but the business case isn't automatic. QuickBooks and Xero already manage outstanding bills, and many businesses have established banking arrangements. Dext must demonstrate why bringing payment execution into its software is worth the additional cost.
Dext already captures invoices and receipts, extracts financial information and sends records to accounting software. With Payments, users bring outstanding bills back from QuickBooks Online or Xero, organize them into payment runs, obtain approvals and submit payments within Dext. The service also tracks payment status and connects payment information with the accounting records businesses use to manage their finances.
QuickBooks Online and Xero already manage supplier bills, but managing a bill isn't the same as sending money to a supplier. QuickBooks Canada's standard bill payment workflow focuses on recording payments, while Xero supports payment file exports for submission through online banking. Dext Payments adds the ability to initiate Canadian EFT payments, manage approvals and track payment status within its existing bookkeeping platform. For accounting firms handling payments across multiple clients, that can reduce reliance on separate banking processes.
Canadian customers can pay suppliers using Electronic Funds Transfer (EFT), Interac and Bill Pay. The service also supports eligible international payments and employee expense reimbursements, although Canadian payroll payments aren't included. Dext provides the software interface, while its partnership with Airwallex supports the underlying payment infrastructure. This arrangement allows Dext to offer supplier payments without building its own payment network, demonstrating how fintechs can add financial services to existing business software.
The strongest use case may be accounting firms managing payments for several business clients. Instead of coordinating approvals through email and separate banking systems, accountants can administer payment runs alongside the records they already process in Dext. For a business that's satisfied with its existing accounting and banking arrangements, however, the additional software step needs to deliver measurable time savings or better payment controls.
Melissa Jackson, an accountant at Oxford Milkway in Woodstock, Ontario, describes the firm's experience:
"We've now processed more than 178 successful payments, covering 660 distinct bills."
The experience points to Dext's opportunity among firms with substantial invoice volumes, although wider adoption will depend on how the service compares with existing payment processes.
According to Dext's Canadian pricing, Payments costs C$20 per client monthly on an annual subscription, in addition to the required Dext software subscription. The price includes 20 Canadian EFT supplier payments each month. Additional EFT payments cost C$0.90 each, while Interac and Bill Pay transactions cost C$1.50 from the first payment. Taxes and applicable international payment charges are extra.
For a business making 50 Canadian EFT supplier payments monthly, the Payments add-on would cost C$47, including 30 additional transfers at C$0.90 each. Grouping multiple invoices into one supplier payment could reduce transaction charges, particularly for businesses making frequent payments to the same suppliers.
Businesses should compare their existing payment fees, approval process and reconciliation workload before adding another service. The QuickBooks Online and Xero integrations also have different reconciliation requirements, so payment execution within Dext doesn't mean every accounting step is automatic.
Dext says more than 12,000 accounting and bookkeeping firms and 700,000 businesses worldwide use its software. Part of IRIS Software Group since 2024, Dext has an established customer base for introducing payment services. Accounting firms that already process client invoices through Dext can add payment management without moving those client relationships to a separate financial operations platform.
Toronto based Plooto already combines accounts payable automation with supplier payments, while Float offers bill payments alongside business spending controls. Dext's opportunity lies in reaching customers through its existing bookkeeping software and accounting firm relationships. Whether that distribution advantage converts into payment volume will depend on pricing, controls and the amount of work businesses actually save.
The Canadian market offers plenty of room to improve payment administration. Payments Canada's 2026 research found that 37% of surveyed SMEs identify payment delays as a significant challenge. 2026 Canadian payments analysis also documents the growing use of electronic transfers and the rollout of Canada's Real-Time Rail. For businesses managing suppliers, better payment visibility and approval processes can be as valuable as faster settlement.
Can Dext win meaningful SME payment volume by serving accounting firms, or will businesses prefer to keep payment execution within their existing accounting and banking services?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
October 14, 2026 | Market Activity | Payments Infrastructure And Money Movement, SME Finance And Business Banking, Regulation And Policy

On October 14, 2026, the Canadian Federation of Independent Business (CFIB) confirms expanded Visa interchange fee reductions for Canadian small businesses starting October 24. Visa is raising the annual Visa sales threshold for its discounted merchant program from C$300,000 to C$750,000 and lowering several interchange rates. Tens of thousands of additional businesses could qualify, creating potential savings for merchants and new opportunities for payment processors to compete on price.
Interchange is the fee paid by a merchant's acquiring institution to the customer's card issuer. It's one component of what businesses pay to accept credit cards. CFIB welcomes the Visa changes but warns that separate network charges could reduce the savings merchants ultimately receive.
Visa measures eligibility using annual Visa sales volume rather than a business's total revenue. Merchants processing less than C$300,000 annually can continue to qualify for discounted interchange rates, while those processing between C$300,000 and C$750,000 become eligible for the discounts for the first time. Existing participants also benefit from lower rates on several types of domestic consumer credit transactions starting October 24.
Visa is reducing interchange rates for several consumer credit card categories, including in-store, online and tokenized online transactions. The table below compares the previous and new rates for eligible small merchants, based on Visa's October rate schedule.
Visa Small Business Interchange Rates Effective October 24, 2026
| Eligible Visa credit transactions | Previous rate | New rate |
|---|---|---|
| Classic, Gold, Platinum — in store | 0.77% | 0.70% |
| Classic, Gold, Platinum — online | 1.30% | 1.20% |
| Classic, Gold, Platinum — tokenized online | 1.25% | 1.15% |
| Visa Infinite — in store | 0.99% | 0.89% |
| Visa Infinite — online | 1.55% | 1.45% |
Rates apply to eligible Visa consumer credit transactions. Network fees and payment processing charges are additional.
The biggest savings could go to businesses qualifying for the discounted program for the first time. Consider a merchant processing C$500,000 annually in eligible in-store Visa Classic, Gold and Platinum credit transactions. Previously above Visa's C$300,000 eligibility ceiling, the business could move from the standard 1.25% electronic interchange rate to the new 0.70% small merchant rate. That would reduce annual interchange costs by C$2,750, assuming all those transactions qualify and the savings are passed through by its processor.
Canada's credit card fee reductions began with voluntary Visa and Mastercard commitments targeting a national weighted average interchange rate of 1.50% in 2015. The target fell to 1.40% in 2020. In 2023, the federal government reached new agreements with Visa and Mastercard to reduce interchange fees for qualifying small businesses. The lower rates took effect in October 2024, covering eligible in-store and online credit card transactions.
The October 2026 change expands that program for Visa merchants and cuts several individual rates further. Mastercard's small business threshold remains C$175,000 in annual Mastercard sales, compared with Visa's new C$750,000 ceiling. Visa's higher threshold allows businesses with greater card sales to continue to qualify for discounted interchange rates, although the actual savings depend on each network's rates and the merchant's transaction mix.
Canadian credit card payments reached 11.6 billion transactions worth C$1.02 trillion in 2025, according to the figures covered NCFA's 2026 payments analysis.
Interchange is only one part of what Canadian businesses pay to accept credit cards.
→
→
→
→
Simplified authorization flow. Settlement and merchant funding follow separate processes.
Paid to the card issuer through the acquiring system.
0.70%
Charged by the card network to acquiring institutions.
Varies
Charges for processing, payment acceptance and related services.
Varies
What the merchant pays: Interchange + network fees + acquiring and processing charges. Lower interchange reduces one cost component, but the final savings depend on the merchant's pricing agreement.
Illustration uses the 0.70% Visa small merchant interchange rate for eligible domestic Classic, Gold and Platinum in-store credit transactions effective October 24, 2026. Actual merchant fees vary.
For merchants: Ask your processor for a breakdown of interchange, network fees and processing charges. Your effective processing rate is the total fees paid divided by your card sales.
A reduction in interchange doesn't automatically reduce every merchant's payment processing bill. Network assessments, acquiring services and processor margins also contribute to the total cost. Under interchange plus pricing, merchants can generally identify underlying interchange charges separately. Flat rate and bundled arrangements may require a pricing review before merchants benefit.
CFIB also warns that Visa and Mastercard are expanding separate network fees charged to payment processors. According to Moneris's network fee schedule, Mastercard's revised charges take effect in October 2026, while Visa plans a comparable US$0.018 per transaction fee beginning in April 2027, as reported by CFIB. Processors may pass these costs to merchants, potentially offsetting some interchange savings. The net impact will depend on transaction volume, existing fees and each merchant's processing agreement.
For business owners, the practical next step is to review annual Visa sales volume and confirm eligibility with their payment provider. Comparing processing statements before and after October 24 can reveal whether lower interchange rates are being reflected in actual charges. Merchants should also review network fee notices and the terms of their acquiring agreements.
The rate changes also affect the economics of merchant acquiring. Payment processors and facilitators must update their pricing systems, account for different card categories and explain the results to customers. Providers that make those charges easier to understand have an opportunity to build trust and retain merchants who are comparing payment services.
Canadian fintechs serving small businesses can go further by combining payment acceptance with fee analysis, accounting and reconciliation. Competition is already expanding through providers such as SumUp's Canadian merchant offering. The opportunity for established processors and newer entrants is to show businesses what they're paying, where savings are available and how their services compare.
There are consequences for the other side of the transaction as well. Interchange is revenue for card issuers, including banks and fintechs offering credit card programs. Lower rates on qualifying transactions affect those economics, while acquirers and processors must decide how to compete for merchants without weakening their own margins.
Visa's expanded program gives more Canadian small businesses access to lower credit card interchange fees, while payment providers face renewed pressure to demonstrate value. Will greater pricing transparency and competition among payment fintechs help merchants capture more of the savings?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 14, 2026 | Fintech AI/ML, Data-driven, Automation, Generative AI, Digital Media and Content Creation
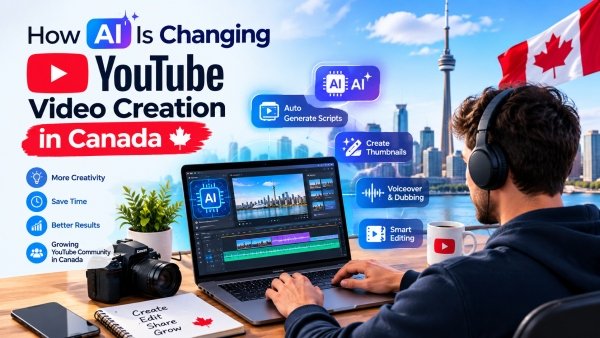
Canadian content makers have never struggled for fame on YouTube. Ranging from vloggers in Vancouver to tech reviewers in Toronto to gaming news stations in Montreal, this nation has given rise to some truly international voices. However, the techniques used to generate the voices are changing rapidly, and one of the great contributions is the AI.
Over the past few days, I've been observing the Canadian YouTube content creator community, especially big and small, adapting AI tools into their workflows, and it's not like the sci-fi takeover that people thought would happen a couple of years ago. It's not like that. It's making an appearance in the mundane, tedious elements of the task - and that's where it lives!
Several years ago, a block of one creator's week was dedicated to a blank document and a blank mind, wondering what to put and how to put it. Today, many Canadian creators use AI writing tools to start with an outline and/or hook, and even complete scripts that are later reworked by them. We should all know that no one is honest with his or her audience when promoting raw AI-generated text and referring to it as a "day's work.The audience can smell laser-propulsion from a mile away these days. However, as an initial draft generator, an argument to challenge and enhance, it has reduced the time it takes to research and write for countless Toronto, Calgary and elsewhere sites.
This is most probably the most significant change. It used to be that I was spending one WHOLE weekend editing! Currently, tools are able to automatically detect filler words, silences and jump cuts. They can make recommendations about B-roll selection, auto-caption in English and French (which is extremely important for a bilingual nation such as Canada) and even identify pacing concerns before a human can even beadle, as that is incredibly valuable.
For individuals using a solitary resource, this has been enormous. There are people now out there that can create a polished video that can be broadcast in a matter of hours, as opposed to the vast amounts of hours it would have taken many, many years ago to figure it out for someone living in a tiny apartment in Ottawa. That's not a little thing — that is a shift in the audience for competition. Until a few years ago, only channels with actual production budgets could produce videos consistently that would be sharp. That is not so much the case anymore.
AI-powered thumbnail generation and title testing are also staple features. Creators send a few variants of thumbnails to the AI to forecast the video click through rate before its publication. Not all of it is science, but it's more than just a shot in the dark, and it's all the more important when a channel is seeking growth in a saturated Canadian playspace, whether it is outdoor, the adventure, personal finance, or the product reviews.
This same "intuition" has now trickled down into title writing. These creators now experiment with three or four different title possibilities based on AI feedback instead, which was once a guess and a gamble of between two options the creator preferred.
Now, things really begin to get interesting for a community manager. They can get thousands of comments for each of their videos on popular Canadian channels, and it simply isn't feasible to read through them all manually these days. That's where a youtube comment search tool has been quietly becoming a staple — content creators can save hours of scrolling countless comments to discover the useful content, recurring questions, or product mentions that they were hoping to find.
As a single human being, it's more important during the process that it seems at first glance. A content creator posting a review about a certain competitor product might want to see the number of views that had comments about that product, while a cooking channel may want to see a list of all the substitutes that viewers had a question about so they can create a pinned video reply or another video about the subjects. Leave out the wall of noise and make the comments easy to search—and now efficiently.
It just has been transforming the way creators carry out giveaways and involvement components. There are a ton of gaming and lifestyle channels in Canada that have fan giveaways all the time, and manually selecting the winner from comments, which contains hundreds or thousands, was a very tedious and – somewhat unfair – process often: It was easy to miss out on people or scroll past an entry. Now, one of these is a youtube comment picker that will randomly show you and the audience, automatically and transparently, which stuff you picked up next. As with all currency, trust is important online and removing human bias in a giveaway is one way to earn it.
Bilingualism is a part of Canada's reality, and this creates opportunities for creators to tap into both English-speaking and French-speaking audiences, which is more possible than ever before thanks to AI dubbing and translation tools. The while, their Quebec rendition of a video can now be considered for English Canada quite properly, by means of not employing a complete translation team. That has now opened up truly new avenues of audience growth for makers with a regional footprint that had shrunk essentially to a rule.
An overlooked pivot: AI-powered tracking and recommendations enable creators to make decisions at earlier stages of the process, not just after their videos flop or fail. Predictive retention modeling, sentiment analysis gleaned from comments, and pacing analysis are not just done after a video is uploaded-updated, but before it is entirely cut up. This can lead to a reduction in wasted uploads, and hence shorten the feedback loop between what the audience desires and what is produced next.
None of these imply a reduction in creative effort by AI.
These tools are where the fastest-growing channels are most foreseeably using them to eliminate busy work and dedicate more time and energy to the areas where they can more impactfully resonate with viewers — the storytelling, the personality, the moments that seem real. Automation is managing logistics. Humans continue to deal with connection, and that isn't going to change soon.
Canadian creators are logical regarding new tech — they make use of that which works for them, and pass that which's hype. It's working for them: that instinct. So the content creation process on YouTube is not being replaced by AI in Canada, but it's being compressed, friction eliminated and more people competing with less resources. That's a great thing for those now considering constructing a channel here.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 14, 2026

Business owners often reinvest profits back into their companies and don't focus on retirement savings or start investing early.
Retirement planning for business owners isn't only about investing in a portfolio; it's also about the company’s value, succession plans, benefits, and cash flow. Because they all eventually shape the retirement strategy.
A successful business does not automatically translate into a financially secure retirement.
A retirement strategy should address both personal retirement income and the eventual transition away from the business.
Moreover, corporate retirement plan services help businesses evaluate and manage retirement-plan strategies.
Business owners should determine what retirement actually looks like before choosing a retirement account. Decide your retirement age, expected annual retirement spending, lifestyle expectations, and any financial support needed for family.
Income from Social Security, retirement accounts, investment income, and potential business-sale proceeds may eventually factor into your retirement income picture.
Owning a valuable company does not mean the owner has sufficient liquid retirement assets.
There is always risk in having concentrated wealth in one place, that could be business equity, company real estate, a single industry or the owner’s personal guarantees or liabilities.
Your company can be part of your retirement strategy—but it should not be your entire retirement strategy.
No single retirement plan works for every business.
A SEP can be attractive for businesses that want a relatively straightforward, employer-funded arrangement.
SIMPLE IRAs are designed for small employers and can provide an accessible way for employees and employers to save for retirement.
A 401(k) can provide both employee salary deferrals and employer contributions. It also functions as a valuable employee benefit.
Profit-sharing and other qualified arrangements for businesses with more complex compensation or retirement objectives.
Tax considerations can be an important component of retirement planning for small business owners.
There are potential tax advantages associated with employer retirement contributions. It is important to understand contribution rules. Also, coordinate retirement contributions with business income. Work with tax professionals when evaluating retirement-plan decisions so they can help you choose the option that works best for you.
Business owners should begin retirement planning way before the actual exit. That could be buying or selling the business, passing ownership to family, management buyouts or reducing the owner’s role.
A business valuation can help establish realistic expectations about how much the business may contribute toward retirement.
Retirement benefits aren't only about the owner's future.
A well-designed retirement plan can also help attract employees, retain experienced workers, strengthen compensation packages, and create a more competitive benefits offering.
Employers sponsoring certain retirement plans may have responsibilities such as administration work, investment oversight, participant interests, paying fees or documentation.
Hiring a professional does not necessarily mean every responsibility of the business owner; plan sponsors still have responsibilities when selecting and monitoring service providers.
Retirement planning shouldn't be a one-time exercise.
A business owner's strategy may need to change when revenue increases or decreases, company ownership changes, compensation changes or retirement approaches.
Conducting periodic reviews of retirement savings, plan design, investment strategy, and the business exit timeline.
Retirement planning can involve several interconnected decisions like business structure, retirement-plan design, investments, taxes, succession, etc.
Professional business retirement plan consulting can help owners evaluate their options, understand plan-design considerations, and align retirement benefits with broader business objectives.
Retirement planning for small business owners is about creating financial independence beyond the company.
So, first define the desired retirement lifestyle. Estimate the retirement income gap, build wealth outside the business, choose an appropriate retirement plan and consider tax implications.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 14, 2026 | Market Activity | Cybersecurity and Fraud, Digital Identity and Trust, Payments Infrastructure

On October 14, 2026, EnStream launched the Cross-Sector Anti-Fraud Exchange (CSAFE) with major Canadian banks and telecom providers, creating a shared platform for identifying repeat fraud across institutions. Members contribute confirmed fraud information that other participants can use during account opening, authentication and transactions. The exchange gives financial institutions a wider view of known fraud activity, with the potential to stop repeat attempts before customers lose money.
Bell, BMO, CIBC, Desjardins, National Bank, RBC, Rogers, Scotiabank and TELUS are the nine founding participants. EnStream, owned by Bell Mobility, Rogers Communications and TELUS Communications, operates the exchange. CSAFE is available now following an earlier pilot involving CIBC and Rogers, and its organizers are inviting additional organizations to participate.
Criminals often target several organizations, taking advantage of the fact that one provider may have little visibility into fraud detected by another. A bank sees account activity and money movement, while a telecom provider has a different view of mobile devices and communications networks. CSAFE connects cross-sector intelligence so participating institutions can identify repeat fraud using information already confirmed elsewhere.
Members contribute confirmed fraud records to EnStream, which combines, standardizes and enriches the information through its platform. It also assesses whether records remain relevant as circumstances change. Each institution uses the resulting intelligence within its own fraud controls, allowing members to strengthen decisions without replacing their existing systems.
A provider may already have effective tools for detecting suspicious account activity but still miss fraud previously identified by another institution. National Bank's Sardine fraud controls is an example of the investment Canadian banks are making in their own detection systems. CSAFE adds a separate source of intelligence that could help participating institutions make those systems more effective.
The CIBC and Rogers pilot provided the foundation for expanding the exchange to other institutions. EnStream describes the pilot as demonstrating the value of sharing confirmed fraud intelligence between sectors. CSAFE's launch is an infrastructure milestone, with its wider financial impact depending on adoption and operating results.
Canada has a substantial fraud problem. The Canadian Anti-Fraud Centre recorded approximately C$351 million in reported losses during the first six months of 2026. Investment fraud accounted for C$139.6 million, followed by significant losses involving phishing and impersonation. The centre estimates that only 5% to 10% of fraud is reported, leaving much of the problem outside official loss figures.
CSAFE begins with large financial institutions and telecom providers, but EnStream explicitly welcomes additional organizations from finance, technology and other industries. That opens a potential route for fintechs, payment service providers, digital wallets, credit unions and identity technology companies to participate. Membership requirements, pricing and technical access arrangements will determine how practical that opportunity becomes for smaller providers.
For fintech operators, access could improve fraud prevention at several important points in the customer relationship.
Access also has competitive implications. Large banks can invest heavily in fraud analytics and draw on extensive customer activity, while smaller fintechs often work with fewer transactions and more limited internal fraud histories. Shared intelligence could help narrow that gap and allow independent providers to compete more effectively on customer experience, pricing and service. The terms of access will determine whether those benefits extend throughout Canada's financial technology market.
There are opportunities for technology suppliers as well. Fraud analytics providers, identity specialists and systems integration firms could help participants incorporate shared intelligence into existing operations.
As more institutions join CSAFE, the accuracy of shared fraud records becomes increasingly valuable. EnStream says the exchange operates under a defined governance framework, while each participant remains responsible for its own fraud decisions. Clear rules for accessing, updating and correcting records will help protect legitimate customers from mistaken account restrictions and payment interruptions.
For banks and fintechs, reliable intelligence could reduce fraud losses and investigation costs while making digital services safer for customers. The wider opportunity is to strengthen fraud prevention across Canada's financial system without adding unnecessary friction to everyday banking and payments.
CSAFE creates a common source of confirmed fraud intelligence for Canada's largest banks and telecom providers, with opportunities for additional organizations to participate. As more financial services operate across banking, payments and communications networks, shared fraud protection could become increasingly valuable infrastructure. Will Canadian fintechs gain practical access to CSAFE on competitive terms, allowing the entire financial sector to benefit from stronger fraud prevention?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 13, 2026 | Market Activity, Artificial Intelligence and Data, InsurTech, Wealth Management

On October 13, 2026, Manulife launched a new enterprise AI platform to help teams build, deploy and manage artificial intelligence applications across its global insurance and wealth management operations. The platform allows employees to reuse approved AI solutions while applying consistent security and governance processes across different businesses and markets. For the Canadian insurer, the opportunity is to expand successful AI applications without rebuilding the technology and approval processes for every deployment.
The launch builds on Manulife's existing AI investments, including its Microsoft partnership and enterprise platform pilot announced in July. Manulife estimates that its AI initiatives generated $300 million in business value by the end of 2025, through operating cost reductions, additional revenue, fraud prevention and handling business growth more efficiently. The insurer aims to increase that cumulative value to more than $1 billion by 2027.
Manulife's platform provides a common environment for developing and operating AI applications. Developers and data scientists can adapt solutions that have already passed security, risk and governance reviews rather than repeating those steps for every application. The platform also supports choosing AI models according to the complexity of the task, helping teams manage processing costs and energy consumption.
Three existing applications are being integrated.
Together, these applications show how shared infrastructure can support different business functions while allowing teams to adapt tools to their own operational needs. The commercial value comes from making successful applications easier to deploy elsewhere. Insurance and wealth management businesses regularly process documents, review applications, retrieve information and support customers through similar administrative tasks. Reusing those capabilities across multiple operations could reduce development costs, improve service times and allow employees to concentrate on more complex work.
Manulife's expanded Microsoft partnership established much of the technology foundation before October's formal platform launch. The agreement covers Azure, Foundry, Copilot and AI agent management capabilities. Manulife also announced plans to extend Microsoft Copilot to more than 30,000 employees, giving its teams access to AI tools within existing enterprise systems.
Manulife had already reported a 30% increase in developer productivity, while its US Quick Quote application automated nearly half of preliminary underwriting assessments and reduced average turnaround times from days to minutes. In Canada, Manulife also has automated eligible life insurance approvals in as little as two minutes. These earlier applications provide a foundation for expanding AI into additional business processes.
Shared development tools could shorten the time required to introduce new services, while common controls may reduce duplicated technical and compliance work. For Manulife, success will depend on whether more business teams can use AI effectively and deliver improvements in service, operating costs and customer experience.
Manulife's approach reflects a broader approach in how financial institutions may adopt AI. Rather than developing separate applications for every department, insurers and banks are investing in shared platforms that connect AI tools to existing systems and business processes. This creates opportunities for specialized technology providers that can solve industry problems while working within the infrastructure financial institutions already operate.
Vancouver-based insurance automation company Quandri develops software for renewal servicing and insurance brokerage operations. Its specialized approach demonstrates how industry expertise and workflow integration can create value alongside enterprise technology. As insurers expand their AI platforms, fintech suppliers that offer reliable integrations, strong insurance data capabilities and measurable operating improvements may find new opportunities to compete.
Toronto-based Fisent Technologies offers another example through its BizAI platform, which turns unstructured documents and other information into data that existing enterprise workflows can use. Its work across banking, insurance and wealth management highlights demand for AI tools that handle real operational requirements, not simply generate responses. Large insurers may develop common AI infrastructure internally while continuing to benefit from specialized external applications and technology partners.
Governance is also becoming part of the competitive proposition. Financial institutions need to understand how AI applications access data, interact with existing systems and support decisions affecting customers. Those considerations connect with the broader technology dependencies discussed in this OSFI frontier AI analysis. Suppliers that combine useful applications with reliable controls and straightforward integration can help institutions expand AI adoption across regulated operations.
As insurers invest in shared AI platforms, will the greatest competitive advantage come from owning the infrastructure, or from the specialized applications that deliver better services and outcomes for customers?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 13, 2026 | Cryptocurrency, Digital Assets, Market Analysis
A crypto market live tracker is most useful when it answers three separate questions: what is the latest quoted price, which assets have moved the most, and where is pressure building on the downside? Putting those views together helps a reader describe market conditions without turning a colorful dashboard into a prediction. The figures are time-sensitive, and each one depends on a data definition, so the job is to read the screen and understand its limits.
A tracker is a collection of measurements, not one universal market price. Depending on the provider, the headline quote may be a last trade, a midpoint, an index, or an aggregation of several venues. The page may also combine spot and derivative markets differently. Those choices can produce small gaps between dashboards while every displayed number is internally consistent.
Start by identifying the instrument. Check the asset, quote currency, market type, timestamp, and whether the figure describes a trade or an indicative quote. A Bitcoin price in USDT on one venue is not the same reference as a Bitcoin-USD index. The difference matters most during fast moves, when spreads widen and feeds refresh at different moments.
Market cap, volume, and percentage change add useful context, but they answer different questions. Market cap describes relative scale under a supply convention. Volume records turnover during a period. Percentage change compares the current quote with a reference value. None tells you how much can be executed at the displayed price or why participants acted.
The crypto market live tracker can be used as a starting point for a broad snapshot. Treat the page as a time-stamped view: save the observation time before comparing it with a later screenshot or a report from another source. A rank can change because a price moved, a feed refreshed, or a supply field was updated. The same screen may serve a journalist, a researcher, or a casual observer, but each use calls for a different level of verification. The dashboard supplies measurements; the reader decides how much checking the decision deserves.
The crypto biggest gainers list answers a narrow question: which assets posted the largest percentage advances under the page’s calculation rules? That is useful for building a research queue. It does not establish that the asset has the strongest fundamentals, deepest liquidity, or the best chance of continuing higher.
Percentage moves are sensitive to the starting point. A token that rises from $0.50 to $0.60 gains 20 percent; a liquid asset moving from $100 to $105 gains 5 percent. The first asset ranks higher by percentage, while the second may involve much more traded value. Add market cap, turnover, spread, and visible depth before describing a move as important.
The reference window also changes the meaning of “biggest.” A 24-hour list can contain a move that happened hours earlier and is now fading. An hourly list may highlight a fresh reaction that has not yet been tested. If a provider does not state the interval or the treatment of new listings, record that uncertainty instead of filling it in.
Suppose a token is shown up 35 percent, but almost all visible volume sits in one thin pair. The arithmetic may be correct while the price is difficult to reproduce with a larger order. Look for the spread, the number of active venues, and whether comparable pairs show the same move. If the move appears only on one feed, describe it as a local observation until it is checked.
Social attention can supply a possible explanation, but it does not confirm one. A listing notice, contract migration, unlock, liquidation, or technical incident may all produce a sharp percentage change. Find the original announcement and establish whether it appeared before the move. A post written after the rally may summarize the event accurately without explaining what started it.
The crypto losers today view is the necessary counterweight to a winners-only reading. If a few large assets fall while many small tokens rise, the market may be rotating between segments rather than attracting broad demand. If both large and small assets are declining, a green pocket may be an exception rather than the market’s direction.
Count-based breadth can mislead. Ten low-cap tokens can outnumber three major assets while representing far less traded value. Compare the number of advancing and declining assets with market-cap weight, turnover, and sector groupings. The conclusion should identify which measure supports it, rather than using “most coins” as a vague substitute for breadth.
Timing provides another clue. A loser may appear after an exploit report, a listing change, an unlock, or an outage. The ranking tells you where to investigate, not which event caused the decline. Check the relevant announcement and compare the asset’s behavior with similar tokens before assigning a catalyst.
This two-sided view is also useful for writers. A headline that says “markets are rising” can be misleading if the gains are concentrated in a small group of low-cap assets. Conversely, a broad decline can be hidden by a few large winners. Pair the tracker with an explicit statement about concentration and data coverage.
Sector labels need similar caution. Assets grouped under gaming, infrastructure, or another theme may not share a catalyst or business model. If several names from one label appear together, check whether they actually responded to the same event or were simply placed in the same category. A taxonomy organizes research; it does not prove a common cause.
Use this sequence when preparing a market note or deciding what deserves further research:
Consider two hypothetical assets. Asset A is up 7 percent with active turnover across several pairs and a narrow spread. Asset B is up 18 percent, but its market is concentrated in one shallow pair. B will attract more attention on the leaderboard; A may offer cleaner evidence about broad participation. The example is not a recommendation. It shows why percentage rank needs a market-structure check.
For editorial work, keep a small source card for every asset mentioned. Include the displayed fields, page timestamp, pair, possible catalyst, and one observation that could disprove the first explanation. This prevents a later ranking from being presented as though it existed unchanged when the article was written.
If the feed does not disclose a minimum-volume rule, do not invent one. State that thin markets may be included and apply a stricter liquidity check to any unusually large percentage move. That is more precise than either dismissing the dashboard or assuming that every ranked asset can absorb a large order.
Market dashboards can use delayed, estimated, or consolidated data. Prices move between refreshes, visible depth can disappear under stress, and fees or slippage sit outside the screen. Leverage, liquidation, taxes, custody, and regional access rules add risks that a ranking cannot resolve. A tracker is research context, not a substitute for independent assessment or a promise about future performance.
The most reliable reading is comparative. The tracker supplies the latest reference, gainers show where recent upside is concentrated, and losers reveal whether downside is broad or isolated. Save the method and timestamp, verify the story behind a move, and say what the data cannot establish. That process makes a fast dashboard more useful without asking it to predict the market.
Not always. A tracker may aggregate venues or show an index, while an exchange displays a quote from its own order book. Match the pair, price type, and timestamp before comparing them.
The list usually ranks percentage change, so a low starting price can produce a large percentage move. Check turnover, spread, depth, and the reference window before treating the rank as a major market event.
No. They show recent declines under a particular method. Compare the losing assets with large-cap weight, sector behavior, volume, and the same time window before describing a broad trend.
Save the page time, pair, quote currency, price, percentage change, volume, market cap, and any stated methodology. A timestamp makes later comparisons and corrections more honest.
It can identify a move worth investigating, but it does not establish causation. Verify announcements, technical records, and venue behavior before assigning a reason.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016