





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 20, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure
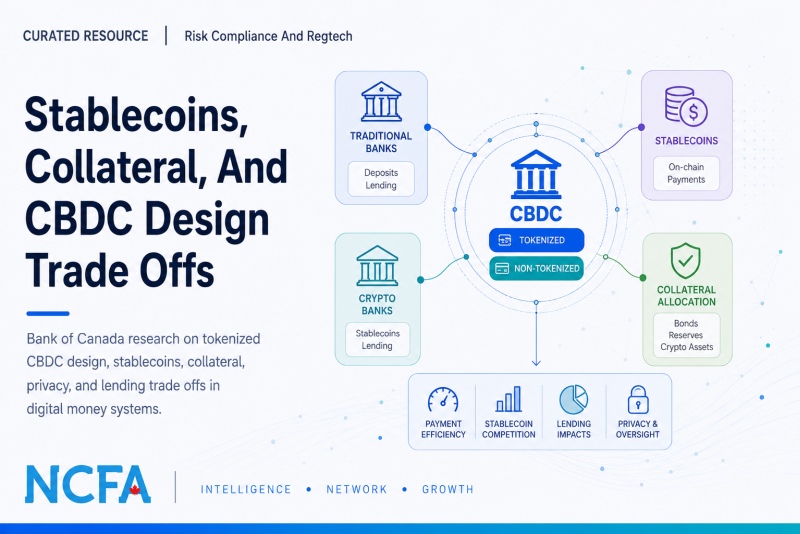
On May 7, 2026, the Bank of Canada published staff working paper 2026-14 on CBDC tokenization design. The paper looks at a financial system where traditional banks issue deposits, crypto banks issue stablecoins, and a central bank decides whether a CBDC should work through conventional accounts or programmable ledgers.
For fintechs, the useful part isn't the CBDC debate alone. The paper links tokenized money to collateral, stablecoin competition, privacy, crypto asset scarcity, and bank lending. Those issues are at the core of digital money infrastructure.
The paper compares tokenized and non tokenized CBDCs. A non tokenized CBDC competes with bank deposits in traditional payment markets. A tokenized CBDC works on programmable ledgers and competes more directly with stablecoins and tokenized settlement infrastructure in on chain markets.
The strongest finding is simple but important. Tokenization changes outcomes only when collateral use differs across sectors. The real question is which institutions hold the collateral, how reliable private money issuers are, and whether scarce reserve assets support payments or lending.
The model shows that tokenized CBDCs can crowd out stablecoins when crypto banks look less reliable and crypto assets are scarce. Non tokenized CBDCs can make more sense when crypto transactions offer less social value or when moving reserves from traditional banks to crypto banks improves the system.
The trade off is clear. CBDCs can improve payment efficiency, but they can also reduce bank lending when collateral moves away from traditional credit creation. That is where the paper becomes useful for fintech operators, not just policy teams.
The paper also raises a privacy question. A tokenized CBDC can run on a ledger that gives the central bank more visibility into transactions. That may improve oversight, but it can also reduce privacy. Digital money design is not just about speed or programmability. It also sets the rules for trust, control, and market access.
This resource is useful for fintech founders, stablecoin issuers, payment companies, banks, digital asset infrastructure providers, tokenization platforms, treasury teams, investors, and policymakers tracking the future of money.
It is especially relevant for firms building around programmable payments, stablecoin settlement, tokenized collateral, wholesale digital assets, bank issued digital money, or regulated crypto infrastructure.
The strength of this resource is the way it connects CBDC design to the financial infrastructure underneath tokenized markets. It doesn't treat CBDC as a simple retail wallet question. It looks at how money design affects collateral, settlement, stablecoins, bank deposits, crypto activity, and lending.
The paper also avoids easy answers. Tokenized CBDCs do not automatically improve the system. The result depends on collateral scarcity, crypto bank reliability, privacy settings, and the value of activity happening on programmable ledgers.
The limit is that this is an academic working paper with equations, model assumptions, and conditional results. Most operators will not read it end to end. The value is in the framework, not every technical section.
Used well, it helps fintech teams ask better questions about future money design. Who issues the money? What backs it? Where does collateral sit? What happens to lending? Who gets visibility into transactions? Those questions will matter as stablecoins, tokenized deposits, and central bank money keep moving into the same conversation.
Bank Of Canada CBDC Tokenization Paper (primary Bank of Canada working paper)
BIS Future Monetary System Blueprint (referenced framework for tokenized money and unified ledgers)
US Treasury Future Of Money Report (policy context for digital money and payment system design)
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply