





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 7, 2026 | NCFA Fintech Market Activity | Consumer Finance And Lending, Payments And Money Movement, Artificial Intelligence And Data, Fintech And Innovation
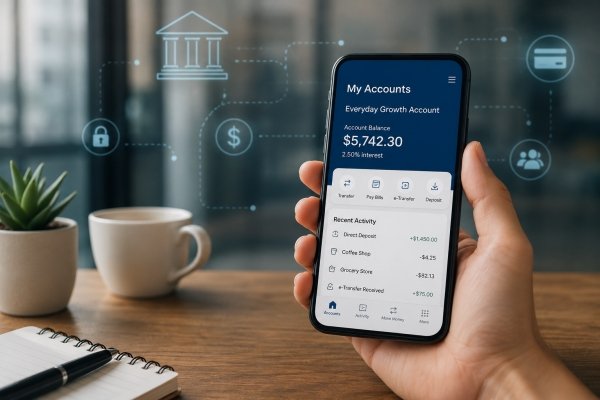
On July 7, 2026, Haventree Bank launched its Everyday Growth Account, adding direct digital deposits to a Schedule I bank known for alternative mortgages and insured GICs. The account pays 2.50% interest, has no monthly fee, no minimum balance, CDIC coverage, bill payments, Interac e-Transfers, EFTs, direct deposit, joint accounts, and up to eight accounts per user. Haventree is offering it through a new digital banking app.
This is not only a savings account launch. It is a competition test for Canadian banking. Haventree is using its bank charter, deposit protection, and digital distribution to compete for everyday balances at a time when consumers are switching more, open banking is advancing, and mortgage competition is becoming more data driven.
Haventree is a Canadian owned Schedule I bank, federally regulated by OSFI under the Bank Act. The bank says its current products include mortgage solutions and GICs, offered through brokers and financial partners. Its accessibility plan describes the bank as having about 290 employees and specializing in alternative mortgage solutions and insured GIC deposits.
Haventree already has regulated bank status, a mortgage business, broker relationships, GIC deposits, CDIC membership, and OSFI supervision. The new account now adds a direct daily relationship with consumers. Broker and partner channels can bring mortgages and GICs. A digital account can bring deposits, cash behaviour, app engagement, and future product paths.
For a smaller bank, direct deposits bring not only funding, but also customer data, trust, and a starting point for deeper relationships.
The timing is better than it would have been a few years ago.
Environics and Hay Research found that 24% of Canadians switched to a new financial institution in 2025 when opening a new account, the highest level in the study’s 20 year history. The study is based on more than 45,000 Canadians.
A related switching study report noted that online account opening accounted for 55% of switchers in 2025, up from 22% in 2013.
The research doesn't mean consumers will move primary accounts quickly, but it shows the market is less fixed than the old banking loyalty story suggests. A 2.50% rate can attract attention.
The harder challenge is whether customers will move direct deposits, bill payments, savings buckets, and idle cash into a new account. A strong interest rate starts the conversation, but habit decides whether balances stay.
Haventree enters a crowded field. Consumers can already compare EQ Bank, Oaken, Tangerine, Simplii, Wealthsimple Cash, KOHO, Neo, PC Financial, and other digital money products. The competitive paths however are different.
KOHO’s bank licence push shows a fintech trying to gain more control over banking operations. Wealthsimple’s banking feature expansion shows a financial platform adding spending, credit, and loan tools around an existing customer base. EQ Bank’s account expansion shows a digital bank adding more daily account use cases.
Haventree comes from the regulated bank side. It doesn't need to become a bank. It needs to make consumers care that it already is one.
Fintechs often compete on product design and speed while working around banking dependencies. Smaller banks can compete from inside the regulatory perimeter, but they still need a modern product experience and a clear reason for customers to switch.
Canada’s banking market is opening from both directions. OSFI’s streamlined approvals framework gives targeted new entrants a clearer route into the federal banking system. At the same time, existing federally regulated banks such as Haventree are adding digital distribution.
Open banking adds the next pressure point. Consumer driven banking is progressing through implementation, with read access and data mobility as the first phase. Canada’s proposed Consumer Driven Banking rules cover accreditation, consent, liability, security, service levels, fees, and violations.
If consumers can compare accounts, share data, verify income, connect budgeting tools, and switch products with less friction, smaller banks will need stronger digital channels before portability improves. And it's pretty clear that Haventree isn't waiting for open banking to mature before building that channel.
Haventree’s mortgage base also matters because lending competition is changing. Mortgage and credit competition are no longer only about branch reach, rate sheets, and broker relationships. Digital onboarding, document automation, income verification, alternative data, cash flow analysis, and AI assisted underwriting are changing how lenders assess borrowers and manage files.
EQ Bank and FundMore’s mortgage lending work highlights how AI tools can help optimize mortgage processing. FundMore and Senso AI also point to a broader lending trend where better data can shorten manual review, improve risk assessment, and support more responsive credit decisions.
For Haventree, direct deposits could become more than funding if the account gains adoption. Daily banking relationships can create useful customer context across savings, GICs, mortgages, and future credit products. That does not mean deposits automatically feed underwriting. It does mean the strategic value of account relationships rises as lending becomes more data driven.
With the launch now in market, the model needs operating proof. Useful evidence will include account openings, average balances, direct deposit uptake, e-Transfer activity, bill payment use, app engagement, GIC conversion, mortgage cross sell, customer acquisition cost, and whether Haventree adds cards, budgeting, credit, or open banking powered tools.
If those indicators grow, this becomes more than a product launch. It becomes evidence that smaller Schedule I banks can use digital accounts to compete directly for deposits while fintechs try to gain more control inside banking.
If they can't , it becomes a reminder that bank status and a competitive rate are not enough. Digital banking competition is won through trust, product depth, switching convenience, and repeated use.
If smaller Schedule I banks can win deposits through digital accounts, will Canada’s next banking competition come from fintechs becoming banks, or banks adopting fintech distribution before open banking makes switching easier?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply