




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 1, 2026 | NCFA Insight | Capital Markets And Market Infrastructure, Regulation And Policy
On Apr 29, 2026, Canada confirmed progress on the Defence, Security and Resilience Bank after multilateral negotiations in Montréal concluded on the proposed charter. Participating countries unanimously support Canada as host country for the future headquarters once the institution is ratified.
The initiative isn't a bank yet but it's making progress. Ratification, capital commitments, governance design, and member alignment is still ahead. But the structure already points to something bigger. It brings sovereign credit, bank balance sheets, defence procurement, SME finance, and private capital into one coordinated financing layer.
The DSRB aims to deliver long term, low cost financing for defence, security, and resilience projects across supply chains. Finance Canada says the focus includes small and medium sized enterprises and member governments that face real financing gaps. The model itself relies on targeted guarantees and risk assessments to reduce investment risk in defence and dual use sectors.
That changes how capital flows. Instead of direct public spending alone, the DBSR bank lowers financing risk. Member countries provide credibility. Commercial banks and capital markets can then lend or invest with stronger protection than they would normally have on their own.
Canada’s upside goes beyond hosting. It pulls the country into how this system actually runs, from treasury and legal structuring through to risk modelling, credit guarantees, and the financing that supports procurement and supply chains. Earlier provincial bids for the DSRB platform showed that the real competition was never just location. It was influence over how a new allied financing system gets built.
At launch, it runs through banks. They hold the balance sheets, structure the deals, and take the risk. That’s where capital moves. Fintechs shows up behind the curtain. Lenders need to see who they are financing, what risk looks like in real time, and where money should go. That creates room for infrastructure that handles verification, risk signals, payments, and supply chain visibility.
Execution is the real test and Canada's Achilles heel. A headquarters doesn't automatically build capacity. Canada has to connect this bank to procurement, to real companies, and to lenders that will actually deploy capital. SMEs need a clear way in. Banks need line of sight into who they can back. If that clicks, the DSRB does more than fund projects. It turns defence demand into investable flow and pulls private capital into the system. If it does not, it stays concentrated with governments and large contractors.
The real question is not whether Canada hosts the DSRB. It is whether Canadian banks, fintechs, and policymakers turn it into a working capital channel for domestic firms or leave it concentrated with global institutions and large contractors.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 1, 2026 | NCFA Market Activity | Payments And Market Infrastructure

On Apr 30 2026, Santander confirmed Ebury secured about £550M in funding led by Centerbridge Partners, with Santander, Vitruvian Partners, and 83North reinvesting. Santander will retain a 55% stake and positions Ebury as its core SME cross-border payments platform.
Ebury was founded in 2009 in London and focuses on cross border payments, foreign exchange, and trade finance for small and mid sized businesses. According to Santander, the platform serves more than 27,000 businesses, operates in over 160 countries, supports 140 currencies, and is active across more than 30 regulated markets. The company has delivered more than 30% annual revenue growth since 2020, reflecting sustained demand for SME-focused global payment infrastructure.
The model is built around consolidation of fragmented workflows. Businesses use Ebury to move funds, manage FX exposure, and access working capital in one system instead of relying on multiple banks and intermediaries. That reduces settlement friction, improves pricing transparency, and shortens execution time across cross border transactions.
This competitive positioning targets a structural gap. Large banks tend to focus on multinational corporates, while many fintechs focus on consumers or small merchants. Ebury sits in the middle, serving companies that operate internationally but lack access to sophisticated treasury and FX tools. By combining payments and FX, it captures both transaction volume and margin, which are often separated in traditional models.
The funding supports further expansion and investment in automation and AI across payment processing and compliance workflows. Santander places Ebury within its Payments Solutions division, which targets more than 15% annual revenue growth through 2028, showing that cross border SME payments are being treated as a core growth segment rather than an adjacent business line.
Worth noting that Santander recently received approval to operate in Canada through a Canadian banking licence. Combining that regulatory presence with Ebury’s platform creates a path to serve Canadian SMEs engaged in global trade, particularly those that require faster payments, integrated FX, and access to international liquidity.
For Canadian fintechs and financial institutions, this news raises the competitive bar. Cross border payments are becoming integrated infrastructure platforms rather than standalone services. Competing requires deeper integration into business workflows, specialization in trade corridors, or partnerships that extend global reach.
If banks control fintech platforms like Ebury, cross border payments stop being a service and become infrastructure. The open question is whether independent fintechs can compete at global scale or whether access to capital, licensing, and distribution will concentrate that control inside bank backed networks.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 1, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure
On May 1, 2026, Broadridge completed its acquisition of CQG, adding futures and options execution management, algorithmic trading, analytics, and market connectivity to its capital markets platform.
CQG brings tools used by futures brokers, institutional investors, retail brokers, proprietary trading firms, and hedge funds to route, analyze, and execute trades. That gives Broadridge more capabilities in the daily work of firms that trade futures, options, foreign exchange, and digital assets.
Broadridge says its technology and operations platforms support average daily trading of more than $15T in tokenized and traditional securities globally. Adding CQG brings more trading activity into that infrastructure base. This type of scale gives the deal weight.
The deal also connects to Broadridge’s recent expansion into Canadian digital asset wealth infrastructure. It's not just about digital assets though. It's workflow ownership across the investment stack, from trading and analytics to custody, asset servicing, and portfolio infrastructure.
Broadridge is building around where financial firms spend time and money every day. Trading, connectivity, analytics, asset servicing, and digital assets are becoming harder to buy as separate pieces. That creates competition for fintech platforms selling solutions or brokers relying on thin integrations across multiple vendors.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 29, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization
On Apr 29, 2026, FIS launched Lyriq, a platform that allows banks to issue and manage tokenized deposits and digital money while keeping funds on balance sheet.
Lyriq connects with core banking systems and supports continuous settlement. Transactions are designed to either complete fully or fail, which reduces reconciliation work and gives banks clearer control over how payments move across systems. The platform enters limited availability after seven financial institution proofs of concept and multiple CBDC program engagements, including one moving toward pre-production.
The design focuses on production use. Identity, access control, compliance, and audit functions are built into the platform, allowing banks to run digital money flows within existing regulatory and operational frameworks rather than layering controls afterward.
Jim Johnson, Co-President of Banking Solutions, FIS:
“Lyriq is production-ready infrastructure that, combined with our deep expertise integrating bank technology, puts banks in control of money in motion. Lyriq is a platform proven with financial institutions - one that meets banks and regulators where they are.”
Lyriq is part of a broader set of tools FIS is building around digital assets. The company already supports stablecoin payments through its Money Movement Hub and loan tokenization through its Digital Liquidity Gateway. Together, these tools cover payments, deposits, and capital markets in one place.
For banks, the appeal is simple. They can offer faster and more flexible transactions while keeping deposits on their own balance sheets. Stablecoins already offer speed and programmability, but they sit outside the banking system. Lyriq gives banks a way to offer similar capabilities without sending funds elsewhere.
The hard part has been getting these systems into real use. Many tokenization projects stay stuck in pilots because they don’t connect to core banking systems. Lyriq focuses on that gap by working with infrastructure that banks already use, which makes it easier to handle real transaction volume.
If banks can’t offer a similar experience, deposits and payment activity can move to platforms that already do. That’s the pressure pushing banks to act.
Which platforms become the operating layer for bank issued digital money, and which banks can move fast enough to keep deposits and payment flows inside their own systems?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
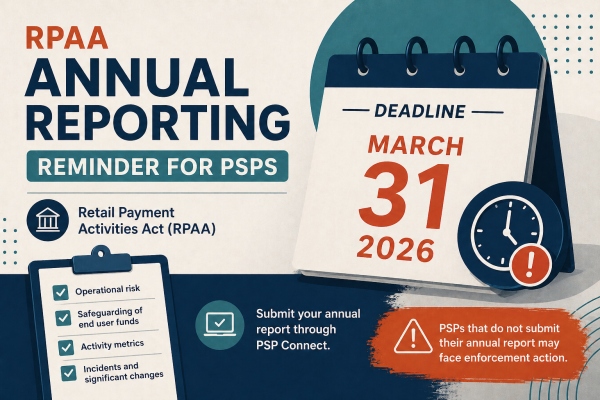
On Apr 27, 2026, the Bank of Canada reminded PSPs under the Retail Payment Activities Act that annual reports were due by March 31, 2026. PSPs registered after March 30, 2026 are not required to submit an annual report for 2025.
PSPs that missed the deadline should submit their report as soon as possible or face potential enforcement action.
The reporting framework is detailed. PSPs must follow the Bank’s annual reporting policy, which requires annual reports by March 31 each year, and its retail payment metrics policy, which covers the value of end user funds held, EFT volume and value, end users served, and other PSPs served. This turns reporting into an operating discipline (to avoid a year end scramble).
The Bank’s reporting guide shows that PSPs must report across operational risk, incident management, end user funds safeguarding, significant changes, incidents, activity metrics, financial information, and record keeping.
The form also asks about cyber security controls, third party service providers, agents, mandataries, safeguarding accounts, shortfalls, and independent reviews.
For operators, (1) data infrastructure must support audit ready reporting, (2) governance must match supervisory expectations, and (3) product design must account for regulatory visibility from day one.
For investors and partners, reporting compliance is a useful test of execution quality. Firms that can operate inside regulated environments with clean reporting, strong controls, and reliable evidence will have an advantage as oversight expands.
The Bank’s information session walks PSPs through annual reporting requirements, including required data fields, operational risk disclosures, activity metrics, and submission through PSP Connect.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 29, 2026 | NCFA Fintech Market Activity | Lending Consumer Credit And BNPL, Capital Markets And Funding
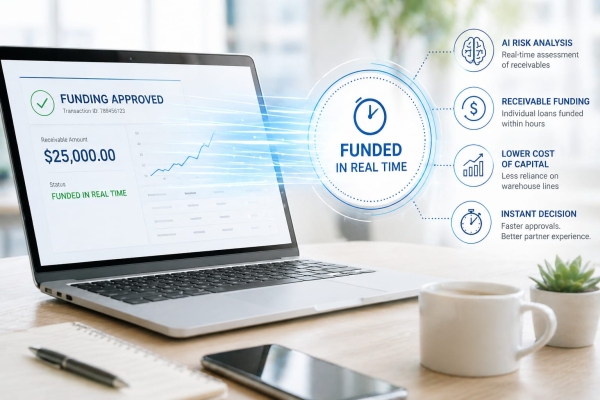
On Apr 29, 2026, VersaBank and FinanceIt Canada announce breakthrough in Real Time Structured Receivable Program pilot, an AI enabled funding model for point of sale finance receivables.
The change is in timing. Many point of sale lenders originate loans and then hold those receivables for 5 to 30+ days before financing them. VersaBank aims to fund individual receivables within hours. That shortens the gap between origination and funding and reduces the need for warehouse lines.
The program already operates at scale. VersaBank’s Structured Receivable Program portfolio exceeded CAD $4.4 billion as of Jan 31, 2026 and has grown at a 33% compound annual rate over the past five years. In the U.S., it completed more than US $310 million in fundings in its first year, above a US $290 million target.
The pilot with FinanceIt focuses on funding at or near the point of sale. FinanceIt originates consumer loans across home improvement, retail, and other merchant channels. If funding happens closer to origination, partners can reduce how long loans sit on balance sheet and lower the cost of carrying receivables.
This approach also changes how lending platforms access capital. Many point of sale and BNPL providers rely on warehouse facilities and forward flow agreements before selling loans into securitization or institutional channels. Shortening the time between origination and funding improves capital turnover and reduces reliance on those structures.
It's AI's decision support layer that's supporting faster decisions. VersaBank positions the program as using AI to assess and structure receivables in real time, allowing funding decisions without batch processing or manual review cycles.
David Taylor, President and CEO, VersaBank:
“This represents a breakthrough innovation in point-of-sale financing.”
It's the combination of faster decisioning and immediate access to capital. Funding can move closer to continuous, loan level decisions rather than batch processing. That allows capital to be deployed when a loan is approved instead of after it sits waiting in a pool. Over time, this leads to more precise pricing and better use of balance sheet capacity.
What happens when capital is deployed at the moment a loan is approved instead of days later, and which lenders are set up to operate at that speed?
Funding speed is becoming a core driver of economics in point of sale lending. When capital is deployed at origination, lenders can reduce costs and improve returns without taking on more credit risk.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 28, 2026 | NCFA Insight | Artificial Intelligence And Data, Banking And Credit Infrastructure
On Apr 27, 2026, Customers Bank announced a multiyear collaboration with OpenAI to deploy AI across commercial banking operations. The bank has nearly $26 billion in assets and already has 75% of team members using OpenAI powered tools. Customers Bank even used an AI voice clone on its last earnings call. The bigger change is how the bank is deploying AI agents across lending, onboarding, and payments.
On its Q1 call, Customers reported more than 500 internal agents and custom GPTs, over 28,000 hours saved through AI enabled workflows, and productivity gains equal to almost 15 full time employees. Q1 results also show $69.7 million in net income available to common shareholders, total deposits up $813.9 million from Q4, and total loans up $609.0 million from Q4.
Sam Sidhu, President and CEO, Customers Bancorp
“We expect a fundamental re-engineering of how Customers Bank operates. We have spent the last year building the operational and governance infrastructure to deploy AI at scale. This strategic collaboration with OpenAI gives us the frontier models, engineering expertise, and ability to co-create a roadmap toward becoming an AI-native bank."
Customers Bank wants AI inside its operating model, with OpenAI engineers working directly with the bank to automate commercial lending, deposit onboarding, and payments. The bank’s cubiX platform already processes about $2 trillion in annual payments volume, giving the collaboration a live operating base, not a pilot or lab only environment.
During Q1 2026 earnings call, Sidhu disclosed that his prepared remarks had been delivered by an AI clone, not read by him. While it was sure to be a memorable call at that point, it's important if AI can represent management's voice in a public market setting, boards need rules for disclosure, script approval, recordkeeping, and accountability before the next experiment becomes normalized.
AI banking use cases aren't just theatre. Customers Bank wants to reduce its commercial loan closing from 30-45 days to about 7 days. It also wants complex commercial account opening to fall from more than a day to under 20 minutes. They are targeting the slowest, most expensive parts of commercial banking.
This is where smaller banks and fintechs should pay attention. AI in banking won’t be won by buying a model and asking staff to use it. The value comes from redesigning workflows around agents, then keeping humans on approvals, exceptions, and risk judgement. That requires clean data, mapped processes, audit trails, escalation rules, and ownership of each AI output.
There's a regulatory approach too. Investor relations, lending decisions, onboarding, and payments all require accountable systems. If an agent drafts, routes, ranks, or speaks, the bank's still on the hook for the result. The lesson is not “let AI run the bank.” It's use AI to remove friction, but keep governance strong enough to prove who approved what and why.
Can Customers Bank turn AI from a productivity tool into an AI enabled engine powering lending, deposits, and payments?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016