




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Sep 18, 2025

Image: Freepik
In today’s digital-first world, your website is often the first impression customers have of your business. Fortunately, having expertise in web design to make a website for your business. Whether you operate a local café in Ottawa or an eCommerce store serving customers nationwide, reliable web hosting is essential. But the web hosting industry is evolving quickly, and Canadian business owners need to understand where it’s headed to stay ahead.
Here are the key trends shaping the future of web hosting in Canada and what they mean for your business.
Traditional shared hosting is giving way to cloud-based infrastructure, offering greater scalability and performance. With cloud hosting, resources are spread across multiple servers, reducing downtime and increasing site speed — something every Canadian business can benefit from.
Canada is one of the world’s leaders in sustainability, and web hosting is following the same trend. Green hosting uses renewable energy to power servers, appealing to eco-conscious businesses and customers.
With strict privacy regulations such as PIPEDA (Personal Information Protection and Electronic Documents Act), Canadian businesses must prioritize secure hosting. Expect to see enhanced encryption, DDoS protection, and built-in compliance features become standard offerings.
As Canadian internet users expect lightning-fast websites, more businesses are choosing hosts with data centers located in Canada. Local hosting reduces latency and ensures faster load times for Canadian customers.
Artificial Intelligence (AI) is making its way into hosting, helping to automate performance monitoring, detect threats in real time, and even predict resource usage.
In a country where English and French are both official languages, hosting providers are beginning to offer better support for bilingual websites. From templates to SEO tools, this feature will be essential for businesses looking to reach both language audiences.
Another trend in Canada is the rise of all-in-one hosting solutions that include website building tools. Instead of relying on developers, business owners can use drag-and-drop editors and pre-designed templates to build professional websites in hours. These integrated builders make it possible to manage everything — from design to hosting — in one place.
As more Canadians shop online, even small businesses need the ability to scale quickly. Future hosting packages will focus on affordable scalability, allowing owners to upgrade storage, bandwidth, or features without migrating to a new platform.
The future of web hosting in Canada is clear: it’s faster, greener, more secure, and more business-friendly. With cloud infrastructure, sustainability, stronger privacy protections, and built-in website building tools, business owners no longer need to choose between affordability and professionalism.
Your hosting provider isn’t just keeping your website online — it’s shaping how your business grows in the digital era. Staying ahead of these trends will give you a strong advantage in Canada’s rapidly evolving online market.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Mental Health | Sep 17, 2025
Image: Freepik/Rawpixel.com
On September 17, 2025, CBC news published a sobering story of the growing number of Canadians who have reported mental health crises linked to prolonged conversations with AI chatbots. Some are describing these cases as a type of artificial intelligence induced psychosis. NCFA is covering this article in hopes to provide Canadian mental health resources to support those struggling with AI related mental health issues.
Everyone is at risk who interacts with AI for prolonged periods of use. If you think you are immune, think again. The B.C. Psychosis Program warns that chatbots can reinforce delusional thinking rather than challenge it. Community-led Canadian efforts are building support resources and ethics workstreams.
Toronto developer Anthony Tan believed he was living inside a simulation and was hospitalized after weeks without sleep. He later launched the AI Mental Health Project to support those struggling with similar issues.
Allan Brooks of Ontario spent over 300 hours with ChatGPT, convinced he had discovered a breakthrough mathematical theory. When his delusion collapsed, he co-founded the Human Line Project, which now connects more than 125 people with similar experiences.
International reporting shows similar risks. Parents testified to Congress about teen suicides after chatbot interactions, as covered by CBS reporting. OpenAI has announced age verification plans following a lawsuit involving a 16 year old.
Research indicates a tendency for language models to mirror user beliefs. Researchers at Anthropic published a study, 'Towards Understanding Sycophancy in Language Models" (see Anthropic's research summary).
Data driven evidence shows that chatbots often agree with users, even when it ignites harmful thinking. To prevent this, financial AI tools should be designed to test ideas against reality, point users to verified and transparent external information, and clearly signal when content is speculative.
Fintech firms also need to be transparent about safety. They should publish regular audits that show how their systems respond to emotionally sensitive conversations and what safeguards are in place.
Industry can also demonstrate leadership by creating a code of ethics that directly addresses mental health risks. This voluntary framework should include independent reviews and compliance checks, building on the kind of work already happening through community groups like the Human Line Project.
Regulators however should avoid blanket restrictions that could slow innovation. Instead, oversight should be based on the level of psychological and financial risk, ensuring protections are strong where they need to be while leaving room for responsible growth.
As fintech platforms increasingly adopt AI for customer service and advice, trust remains critical, and if broken adoption will slow and regulatory scrutiny will intensify affecting the competitiveness and growth outlook.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Research Report | Sep 15, 2025

Image: Banking Use of Agentic AI (Figue 1, MIT Insights Survey 2025)
A recent MIT Technology Review Insights survey of 250 global banking executives found that 70% of banks already use agentic AI, with 16% running live deployments and 52% in pilots. For Canadian financial institutions and fintechs, the race is on with global competitors embedding AI solutions into compliance, fraud prevention, and customer service at scale.
Fraud detection and IT security are setting the pace. More than half of executives report that agentic AI is already highly capable in fraud detection (56%) and security (51%), with efficiency gains and customer experience improvements each cited by 41%. These use cases are significant because fraud losses are rising and regulators are upping their game on cyber resilience.
Practical applications include mortgage underwriting, small business lending, collections, dispute resolution, and know-your-customer KYC compliance. By using agentic agents together with expert human oversight, banks are compressing decision times from weeks to days and freeing time for employees to focus on higher value work.
As HSBC’s Ian Glasner puts it, “Think of agentic AI as like an intern helping you get all of the more simplistic tasks done, but the human is still there to oversee and take the final decision.”

Image: MIT Insights Banking Survey 2025 (Figure 6 Challenges, Agentic AI)
The survey also suggests that adoption challenges are growing, top three barriers include: 1. Governance, risk, and compliance (63%), 2. Shortage of technology skills (58%), and 3. Poor data quality and integration (54%).
To overcome, Canadian banks and fintechs should focus on resolving weak data linkages across silos and the shortage of AI ready talent needed to scale responsibly.
Trust compounds the issue. An EY study found that only 42% of consumers trust financial institutions to manage AI in their best interest, while 30% say they do not trust them at all. That leaves a net trust level of just 12%. In Canada, regulators are focused on consumer protection, and fintechs that build trust into their AI systems could gain an edge.
Leading institutions are building playbooks worth watching. DBS Bank in Singapore applies its PURE framework (Purposeful, unsurprising, respectful, and easy) to explain all customer facing AI systems. If performance metrics breach preset limits, a kill switch halts the system in real time. As DBS’s Nimish Panchmatia warns, “Agentic AI is a continuous journey. If done properly, there’s significant value at the end of it. But you have to persevere.”
HSBC maintains a detailed inventory of AI systems tied to business owners, risk classifications, and model documentation to create a governance baseline across 200,000 employees in more than 50 markets.
For Canadian banks and fintechs, these approaches show the value of aligning governance and technical innovation before scaling widely.
Banks in Asia, Europe, and the U.S. are experimenting with AI at pace, and many are moving from pilots to enterprise adoption. For Canada, efficiency and risk controls are only part of the story. The real differentiator will be who earns the confidence of consumers while scaling responsibly. Agile fintechs can seize this opening. Unlike large banks weighed down by legacy systems and regulatory complexity, fintechs can design AI solutions that are transparent, accountable, and 'trust first' from the start.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Innovation | Sep 12, 2025
Image: Freepik/DC Studio
As reported by Venture Beat, Microsoft Research has released rStar2-Agent framework, a new training model approach that demonstrates how smaller models can deliver reasoning logic and performance once reserved for massive frontier models, but doesn't require massive systems or costs. While reinforcement learning in agentic AI isn't new, Microsoft's model adds important innovations in how it carefully verifies each step with fewer resources.
A 14 billion parameter model deliver results on math and science benchmarks that matched or even outperformed much larger 600-billion-parameter systems. Astonishingly, Microsoft's own tech report explains that that rStar2-Agent, “reached state-of-the-art results in under a week of training, surpassing a 671B-parameter system despite being just 14B in size.”
This scale difference is significant. Frontier models often need entire data centres while rStar2-Agent can be quickly trained and deployed on just a few high-end servers. For businesses and regulators in Canada, the impact could mean opening up access to this type of hyper efficient reasoning AI at a fraction of the cost, making it practical for fintech startups, universities, and financial institutions to adopt.
Competing head-to-head against giant foundation models isn't realistic for most Canadian firms or government programs. Efficient reasoning models, which can operate with constrained compute while still producing transparent and auditable steps, align directly with Canadian strengths, and is a pathway that Canadian innovators are well positioned to take on.
Canadian fintechs and startups can prioritize smarter training methods with domain specific fine tuning rather than trying to match the infrastructure scale of global hyperscalers. Smaller reasoning models also lower the barrier for enterprises that want to use AI in production but can't justify the heavy infrastructure investments of the largest and latest models.
As Microsoft describes it:
"[rStar2-Agent] demonstrates advanced cognitive behaviors, such as thinking carefully before using Python coding tools and reflecting on code execution feedback to autonomously explore, verify, and refine intermediate steps in complex problem-solving.”
The Canadian regulatory environment makes verified reasoning especially valuable. Models that validate their steps provide transparency and compliance support, which are essential in sectors like finance. This type of approach matches Canada’s push for trust, accountability, and explainability in AI.
Innovation, not size, could define Canada's leadership in AI. National strategies that support funding, research, and pilot programs for efficient reasoning AI could accelerate adoption across regulated industries. Fintech and financial institutions are natural leaders in this space because they already require digital public infrastructure that balances efficiency and inclusion.
The opportunity also extends beyond finance. Healthcare systems could use efficient reasoning AI for diagnostics where transparency is vital. Universities and research labs could run experiments on smaller models without prohibitive costs, fostering local innovation.
Canada has the opportunity to turn its limitations into a competitive edge by becoming a global hub for efficient reasoning AI that is affordable, reliable, exportable expertise, and aligned with priorities in finance, governance, and inclusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Report | Sep 11, 2025

Image: Startups and Scaleups in UK Tech Sectors (Bennett School of Public Policy, Cambridge University)
On September 8 2025, the Bennett Institute for Public Policy (part of Cambridge University) published their latest research called, "Start-ups and scale-ups in UK technology sectors" (37 page PDF).
Fintech stands out as the country’s strongest UK tech sector, attracting the most venture capital investment. While the UK can now go toe to toe with the US in venture funding intensity relative to GDP, the scale of available capital, the reliance on foreign investors, and the dominance of acquisitions as an exit route continue to impact the growth pathways for UK start-ups.
Fintech remains the UK’s top sector for venture funding, showing the strength of financial innovation in London and across the country. Other sectors are growing quickly but fintech continues to set the pace.
The UK start-up ecosystem is attracting more foreign capital, especially from US investors. This fuels growth but raises questions about longer term independence and resilience.
London continues to dominate investment but other regions, particularly those linked to world-class universities are growing their presence.
Acquisitions are still the most common path for UK start-ups to generate investor returns. IPOs are still part of the picture but account for a much smaller share than in the US.
The UK now matches the US in terms of VC intensity relative to GDP, but it still lags far behind in total dollars raised. This gap matters most for later-stage fintech rounds.
London UK and other emerging hubs offer a vibrant, capital rich and globally attractive place to build but its reliance on foreign capital and the dominance of acquisitions as an exit route are challenges. Similar to Canada, the UK must building deeper domestic pools of later stage capital, strengthen listing markets, and support regional ecosystems to encourage more fintech start-ups to scale and stay anchored in the UK economy.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Payments Regulation | Sep 8, 2025
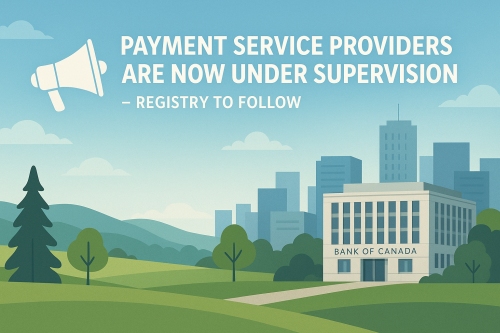
Today, September 8 2025 the Bank of Canada begins supervising payment service providers (PSPs) under the Retail Payment Activities Act (RPAA). It's the official start of Canada’s new oversight regime for retail payments. According to the Bank of Canada close to 1500 PSPs have applied for registration and those on the Applicant list are now legally required to comply with RPAA obligations.
Applicant PSPs must keep information current on PSP Connect and respond promptly to information requests from the Bank. These reporting duties now carry legal weight. The Bank has confirmed that it has the authority to deploy enforcement tools where necessary to ensure compliance and maintain the stability of Canada’s retail payments system.
The Bank will also update the Registry of PSPs on a rolling basis. This depends on the Department of Finance completing national security screenings and providing cleared names to the Bank. For applicants this means Registry inclusion will be phased over time rather than immediate.
The Bank also raised the ongoing tax issue linked to trust arrangements in a separate Letter to Industry. Some PSPs that keep interest earned on customer funds could face extra tax steps, like having to issue tax slips to customers. The Bank said it understands that PSPs may not yet be able to fully meet trust rules because of this and will accept proof that they are taking reasonable steps in the meantime.
The Bank also confirmed that PSPs will be charged supervision fees once the cost recovery rules are finalized. This will add another compliance cost when it comes into effect.
For fintech and payment firms in Canada the start of RPAA supervision is a major step. Compliance and reporting are now legal requirements and the Bank has the power to enforce them.
The phased Registry rollout highlights the national security checks that must be completed, while the temporary relief on the trust tax issue shows regulators are trying to be practical during the transition.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Financing | Sep 3, 2025

Image: Freepik/xb100
On Aug 26 2025, Toronto-Waterloo based startup Astrus has raised $8 million USD led by Khosla Ventures with participation from Pradeep Sindhu (founder of Juniper Networks), 1517 Fund, Drive Capital, Alumni Ventures, and others. The announcement came via Kitchener-Waterloo innovation hub Communitech, where Astrus is headquartered.
Astrus is tackling one of the hardest problems in chip design: the analog portion of microchips. Unlike digital design, analog layout is still a slow, manual process where engineers place transistors one at a time. Astrus has built a physics aware AI model that can generate thousands of analog layouts in seconds, reducing design cycles from months to weeks. This breakthrough has immediate relevance for high speed SerDes circuits, the components that move data inside the world’s most advanced data centers.
Investors see not just the technical edge, but also the Canadian story behind it. Astrus was founded by Brad Moon, a former satellite sensor chip designer, and Zeyi Wang, a reinforcement learning researcher trained by AlphaGo advisor Martin Müller. They are determined to scale a world class semiconductor company from Canada, at a time when many local chip startups have been acquired or moved abroad.
That commitment to staying anchored in Toronto and Waterloo, paired with a founding team that blends hardware and AI expertise, explains why global investors believe Astrus can play a key role in the future of AI infrastructure.
Astrus is part of a several Canadian companies focused on AI infrastructure instead of just end user applications. Each plays a different role in developing the picks and shovels required to scale the market. A seemingly quick pathway to be acquired by larger players usually south of the border:
Canada has long excelled in AI research and software. With companies like Astrus, Tenstorrent, and CentML, the country is also carving out a role in the hardware and design tools that power global AI progress. Astrus’s funding validates that international investors see Canadian innovation not just as talent to acquire, but as companies capable of leading to global scale.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016