




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Apr 2, 2026 | NCFA Fintech Market Activity | Banking And Credit, Regulation And Policy
Image: Freepik/rawpixel.com
On April 2, 2026, Italy’s competition authority (AGCM) fined Revolut group €11 million for unfair commercial practices tied to investment disclosures, payment account restrictions, and communication around Italian versus Lithuanian IBANs.
These fines come at a time when Revolut has grown into a bigger and more profitable company, and trying to look more like a primary banking platform than a fast growing fintech. In late March, Revolut reported $2.3B in profit before tax for 2025 with 68.3 million customers and $6B in revenue. Regulators expect more from a company with that type of scale; clarity, conduct, and professional account handling.
Regarding the IBAN issue,, the AGCM said Revolut didn't provide clear and exhaustive information on the requirements and timing for obtaining an Italian IBAN instead of a Lithuanian one. Revolut’s Italy account documentation now identifies Revolut Bank UAB Italian branch details and says the information sheet took effect on March 30, 2026. For a fintech trying to become more embedded in everyday banking, local account setup and customer communication are not side issues, and are important for trust and primary account use.
Revolut said it strongly disagrees with the findings and plans to appeal in the Italian courts. The company said the decision would have no impact on operations or its financial position. That response may settle investors in the short term, but its a sign that once a fintech reaches bank like scale, regulators stop looking only at growth and product breadth. They look much harder at how claims are framed, how restrictions are handled, and whether customers understand what they are actually getting.
Fractional investing, account controls, and local account migration can look like product details when a company is small. At scale, they become conduct risk. Italy’s decision shows how quickly those details can become costly once a fintech evolves deeper into the center of consumer finance.
When a fintech starts to look more like a primary bank, which becomes harder to defend at scale: aggressive growth tactics or unclear customer communication?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
April 2, 2026

Online casinos have changed a lot in recent years. The biggest shift involves the rise of crypto casinos, which allow players to bet with digital currencies like Bitcoin and Ethereum instead of regular money. These sites work differently from traditional online casinos in several important ways.
Crypto casinos offer faster payments, more privacy, and different bonus structures compared to traditional online casinos, though they also face unique regulatory challenges and learning curves for new users. Traditional sites use standard money and follow strict government rules, while crypto sites use blockchain technology to process bets and withdrawals. Each type has its own strengths and weaknesses that matter to different types of players.
The choice between crypto and traditional online casinos depends on what matters most to each player. Some people value speed and privacy, while others prefer the familiar systems and stronger legal protections of regular sites. This article explores how these two types of sites differ, what advantages crypto casinos provide, and what challenges they face in the current market.
Crypto casinos and traditional online gambling sites operate on different foundations that affect how players deposit funds, withdraw wins, and protect their personal information. The currency type, transaction speed, privacy levels, and access restrictions vary significantly between these two sites.
Traditional online casinos accept fiat currencies like dollars, euros, and pounds. Players deposit funds through bank transfers, credit cards, or e-wallets like PayPal. These methods connect directly to financial institutions and require verification of bank accounts or cards.
Crypto casinos accept digital currencies such as Bitcoin, Ethereum, and other cryptocurrencies. Players need a crypto wallet to store and transfer their digital assets. For example, sites like www.biggerz.com/, www.betpandacasino.io/, or others, allow users to gamble with various cryptocurrencies instead of traditional money.
The payment infrastructure differs substantially. Traditional sites rely on payment processors that charge fees for each transaction. Crypto sites use blockchain technology, which removes middlemen from the process. This means crypto casinos often have lower fees or no fees at all for deposits and withdrawals.
Traditional online casinos process withdrawals slowly. Bank transfers can take three to seven business days to complete. Credit card refunds may require five to ten days. E-wallets are faster but still need one to three days in most cases.
Crypto casinos process transactions much quicker. Deposits appear almost instantly in player accounts. Withdrawals typically complete within minutes to a few hours, depending on the blockchain network traffic. Bitcoin transactions might take longer than other cryptocurrencies, but they still beat traditional methods.
The speed difference comes from the verification process. Traditional casinos must verify transactions through banks and payment processors. Crypto transactions only need confirmation on the blockchain network. This removes delays caused by bank hours, holidays, or manual review processes.
Traditional gambling sites require extensive personal information. Players must provide their full name, address, date of birth, and phone number. They also need to submit identification documents like passports or driver's licenses. Banks and payment processors add another layer of data collection.
Crypto casinos offer more privacy. Many sites only ask for an email address and username to create an account. Players can gamble without submitting identity documents in most cases. Cryptocurrency transactions don't reveal personal details since they only show wallet addresses.
However, complete anonymity isn't guaranteed. Some crypto casinos still require verification for large withdrawals or to comply with regulations. The blockchain itself is public, so anyone can trace transaction patterns if they know which wallet belongs to a specific person.
Traditional online casinos face strict geographic restrictions. Many countries ban or heavily regulate online gambling. Payment processors often block transactions to and from gambling sites in restricted regions. Banks may decline deposits or freeze accounts linked to gambling activities.
Crypto casinos offer broader access. They can serve players in countries where traditional online gambling faces restrictions. The decentralized nature of cryptocurrency makes it harder for authorities to block transactions. Players can access these sites with fewer geographic barriers.
Regulations still apply in many jurisdictions. Some countries prohibit all forms of online gambling, whether crypto or traditional. Players remain responsible for following their local laws. Additionally, some crypto casinos choose to block certain countries to avoid legal complications.
Crypto casinos bring unique benefits like fair game verification and faster payments, but they also face hurdles with regulation and security concerns that players need to understand.
Provably fair gaming stands as one of the most significant features that sets crypto casinos apart from traditional sites. This technology uses blockchain and cryptographic algorithms to let players verify each game outcome independently. Players can check the fairness of every bet or spin through a hash function that proves the casino didn't manipulate results.
The system works through a process where the casino generates a random seed, and the player also contributes a seed. These seeds combine to create the game result. After each round, players receive all the information needed to verify that the outcome was truly random and not altered.
However, this advantage comes with a learning curve. Many players find the verification process confusing at first. The technical nature of hash verification requires some basic understanding of how blockchain works. Despite this challenge, provably fair systems offer a level of transparency that traditional online casinos cannot match.
Blockchain technology provides strong security features for crypto casino transactions. Every deposit and withdrawal gets recorded on a public ledger that cannot be changed or deleted. This creates a permanent record that both players and casinos can reference.
Players gain more control over their funds because cryptocurrencies eliminate the need for banks or payment processors. Transactions happen directly between the player's wallet and the casino. This direct transfer reduces the risk of payment fraud and chargebacks.
The transparency of blockchain also means players can verify casino reserves in some cases. Smart contracts can automate payments and enforce rules without human intervention. These features reduce the possibility of disputes over winnings.
On the other hand, cryptocurrency security depends heavily on proper wallet management. Players who lose their private keys lose access to their funds permanently. There is no customer service team that can reset a forgotten password or recover lost crypto. This responsibility shifts more risk onto the player compared to traditional casinos, where account recovery options exist.
Crypto casinos operate in a complex legal environment that varies widely between countries. Many jurisdictions have not yet created clear rules for cryptocurrency-based sites. This regulatory uncertainty creates risks for both operators and players.
Traditional online casinos typically hold licenses from established authorities that enforce player protection standards. Crypto casinos may operate with fewer restrictions, but this also means less oversight. Players might have limited recourse if disputes arise with unlicensed operators.
Some crypto casinos obtain licenses from recognized jurisdictions to build trust with players. However, the licensing requirements for crypto sites often differ from traditional casino regulations. This creates a patchwork of different standards across the industry.
Tax implications also present challenges for crypto casino players. Many tax authorities require individuals to report cryptocurrency gains, but tracking winnings and losses across multiple transactions can be difficult. Players bear the responsibility to understand and comply with their local tax laws.
Both crypto and traditional online casinos offer distinct advantages that appeal to different types of players. Crypto casinos provide faster transactions, more privacy, and lower fees, which attract those who value speed and anonymity. Traditional sites offer more established regulations, familiar payment methods, and a sense of security through licensed oversight.
The right choice depends on what matters most to each player. Those who prioritize quick withdrawals and privacy may prefer crypto sites, while players who want regulated environments with consumer protections might choose traditional sites.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 1, 2026 | NCFA Fintech Market Activity | Embedded Finance Platforms And Partnerships, Payments And Money Movement
On March 31, 2026, Reuters exclusively reported TikTok's Brazil license applications. The company applied for one license to issue electronic money for prepaid accounts and payments and another to operate as a direct credit company, enabling lending without taking public deposits.
TikTok already has the reach with more than 131 million users in Brazil. Most fintechs spend years trying to build that kind of distribution. TikTok already has it. The harder part is turning that audience reach into payment, wallet use, and trust in a credit product.
Brazil's payment system also gives TikTok a strong foundation to build on. Pix reached nearly 170 million users and BRL 11 trillion in transactions in 2024. The domestic payment rail is already there so the battleground is who controls checkout, the wallet, the customer relationship, and eventually the credit layer inside social commerce.
If TikTok can connect discovery, commerce, payments, and lending into a single flow, it starts to look less like a social app with a wallet and more like a commerce platform with financial rails built in. The upside is clear. Payments can reduce checkout friction. Credit can lift conversion, change seller economics, and pull more transactions into the platform.
The trust question is harder. A social platform can add financial rails faster than a normal fintech can add distribution, but it still has to prove that users, merchants, and regulators trust the same platform to handle money as well as attention. That challenge is real when, especially when platforms can face backlash after changing how users think abut their service scope, data usage or activity will be used, as seen in Bluesky’s data use backlash.
The old approach was to build a financial product and then fight and claw for users. TikTok is trying the reverse. It already has the users. Now it wants the financial plumbing, much like Elon Musk's super app push for X. That in itself makes the licensing outcome worth watching for fintech founders, banks, acquirers, and payment firms already operating in Brazil.
The open question is whether a social platform can turn payments and credit into a real commerce edge without drawing heavier scrutiny as it grows. If it can, Brazil may become a clear example of platform distribution beating out traditional financial distribution.
When a platform already reaches 131 million users, does the edge in finance come from the product itself or from owning the customer before the first payment starts?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 1, 2026 | NCFA Fintech Market Activity | Cross Border Payments And FX
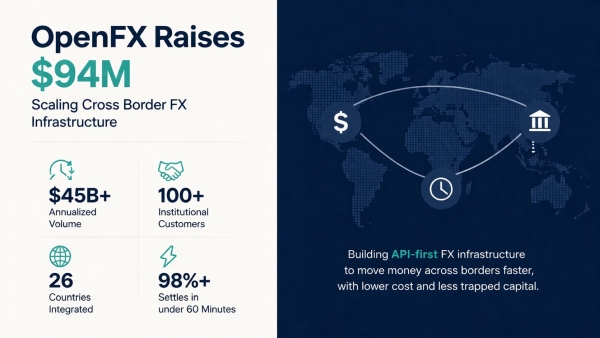
On March 31, 2026, OpenFX raised $94M to expand across Southeast Asia and Latin America. Two years after launch, the company says it now has 105 employees across four continents, handles more than $45B a year in cross border volume, and has onboarded more than 100 institutional customers.
The operating numbers are hard to ignore. OpenFX says 98% of transactions settle in under 60 minutes. In May 2025 the company said it had already integrated 26 countries and 7 major FX pairs, and that one newly onboarded client reached $100M in transaction volume in 17 days, with all of that settling within 60 minutes.
The product vision is more specific than a generic stablecoin pitch. Founder and CEO Prabhakar Reddy wrote that OpenFX didn't want to be “a crypto company moving Stablecoins,” but “a FX company moving money across the globe.”
OpenFX has built the hardest part of cross border payments first, including liquidity, cost, and settlement mechanics. It's tech stack offers collections, FX, payouts, banking, yield, compliance, and liquidity, delivered through API based infrastructure that runs 24/7.
That focus helps explain the customer base. OpenFX says it serves fintechs, neobanks, remittance providers, and payroll platforms, including MoneyGram, Yellow Card, and alfred. The company also says there's more than $200T in money movement that still relies on slow and fragmented cross border infrastructure.
OpenFX isn't selling speed on its own. Its announcement post argues that legacy cross border payments still hide fees inside exchange rates, trap capital in pre funded accounts, and leave businesses waiting days for settlement. OpenFX says stablecoins let value cross borders in seconds while sender and recipient still use local fiat. That reduces idle capital, compresses settlement time, and gives payment firms a cleaner way to handle large transfers.
There is a useful lesson here for founders and investors. OpenFX didn't try to fix every payment problem at once. It picked a part of the market where delay is expensive, built around API access and 24/7 settlement, then pushed that model into live institutional volume. If that keeps working, expect pressure to build around flows based on old economics andslow settlement, trapped liquidity, and wide spreads on large transfers.
If large ticket FX settles in under an hour, which parts of the old cross border fee stack get hardest to defend?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 1, 2026

The Bitelity broker further reveals its core concept through the development of a web-based trading infrastructure, emphasizing that browser-based solutions are becoming the foundation of modern trading, providing users with maximum flexibility, security, and stability. In this context, trading via web interfaces is not merely an alternative to traditional applications, but a полноцен technological standard that enables seamless and simultaneous access to multiple markets without the need to install additional software. This is especially important in the context of growing demands for cybersecurity and operational speed.
At the same time, the Bitelity platform is positioned as one of the fastest and most stable solutions on the market, offering users the ability to execute trades efficiently with just a few clicks, while maintaining high order execution accuracy and access to a wide range of analytical tools that go beyond standard mobile and desktop solutions. This creates a modern and intelligent trading environment focused on maximum convenience and performance.
A key advantage of the web platform is the absence of any installation requirement, which not only simplifies the onboarding process but also significantly reduces potential risks associated with downloading third-party software. Users are not required to grant access to personal data or system resources of their device, and the likelihood of malware infection is eliminated, collectively increasing trust in the platform and making the trading process more secure.
Additionally, the lack of installation means no strain on device memory and complete independence from its technical specifications, making the platform a universal tool accessible from any device with an internet connection. An important element of this concept is full compatibility and remote access, allowing users to connect to their trading account at any time, monitor market changes, and respond promptly regardless of their location—whether in a workspace or at home.
Thus, Bitelity creates a flexible interaction model in which the trader is not tied to a specific device and can freely manage their investments. This is especially relevant in dynamic financial markets, where timing plays a crucial role. Special attention is also given to eliminating limitations associated with relying solely on mobile applications, since dependence on a single device may lead to loss of access in case of loss or technical issues. In contrast, the web platform ensures continuity by allowing login from any device connected to the network, guaranteeing constant access to trading operations and reducing stress related to possible technical failures.
Another important advantage is the platform’s operational stability, achieved through a unified interface and identical functionality regardless of the device used. This provides users with a familiar and intuitive environment without the need to adapt to different software versions, which distinguishes the web solution from traditional approaches where differences between mobile and desktop applications can complicate the trading process. In the case of Bitelity, this issue is eliminated through interface and logic unification, ensuring a smooth user experience and minimizing the likelihood of errors.
Taken together, all these characteristics form a solid technological foundation that supports the platform’s core idea: to provide users with the most accessible, secure, and efficient tool for operating in financial markets. Every detail is aimed at enhancing convenience and reliability, and it is precisely this integration of speed, stability, and universality that allows the Bitelity web platform to be considered the central element of the entire ecosystem—combining the advantages of modern technology with the practical needs of traders. This creates the conditions for confident and uninterrupted trading in any situation, regardless of external factors, thereby strengthening the company’s overall direction toward creating long-term value for clients through technological excellence and a thoughtfully designed user experience.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Mar 31, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data
On March 28, 2026, Bluesky introduced Attie in invite only closed beta, it's first agentic social product built on atproto. It's interesting because Bluesky built part of its appeal on taking a more cautious public approach on generative AI and user content than larger platforms.
Attie is a standalone AI assistant for custom feeds and app building. Users can describe what they want in natural language, build their own algorithm, create custom feeds, and over time build social apps on the protocol without needing to code.
In late 2024, Bluesky had already set expectations around how it saw AI and user data. The company said it had “no intention” of training generative AI on user posts.
Then in 2025, the company published a data reuse proposal that would let users set preferences across generative AI, protocol bridging, bulk datasets, and web archiving. That debate got heated because it didn't create a hard block on scraping or data reuse. For many users, it crossed a data use line that Bluesky already said it wouldn't cross. They said they wouldn't train AI on post data but now it was building a system around opt outs and reuse preferences, creating friction with its users.
By March 30, Attie had become one of Bluesky’s most blocked accounts. More than 125,000 users had blocked it within days. Users didn’t wait for a long policy debate. They reacted to what the launch seemed to mean.
Bluesky didn't announce that it would now train generative AI on user posts. But in trust based markets, users don’t separate product utility, data use, and company intent as neatly as product teams do. Once those concerns merge, the launch stops being just a product story. It becomes a consent and brand story too.
For founders and investors, there's a practical and commercial lesson here. AI features and products are getting easier to ship, but clear boundaries aren’t. In fintech, payments, digital identity, and any other business built on sensitive data, that gap (or buffer) can backlash and get expensive fast.
What did Bluesky launch?
Bluesky launched Attie as an invite only closed beta app built on atproto. It helps users create custom feeds with natural language prompts and is designed to support broader app building over time.
Why did users push back so quickly?
Because many users already saw Bluesky as more cautious on AI than rival platforms. A branded AI app raised immediate questions about whether that line of mutual trust was starting to change.
Did Bluesky say it will now train AI on user posts?
No verified source tied to this launch shows Bluesky announcing that change. The concern comes from how users connected the launch to earlier debates over AI training and scraping.
Why does this matter for fintech?
Because the same problem appears in any trust based product. If users are unsure what an AI tool does, what data it uses, or what clear policies the company will not cross, adoption can weaken before the product gets a fair chance.
What makes this commercially important?
This isn't just a social media story. It shows how fast a useful AI feature can become a trust and brand problem. That risk applies to consumer finance, digital identity, payments, and any business built on sensitive data.
As AI tools spread across digital platforms, will users reward the company that ships first, or the one that makes the boundary clear before launch?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
March 31, 2026
Crypto casino gaming now moves billions of dollars every year. Many players prefer these sites because they use provably fair technology, allow fast blockchain withdrawals, and offer games designed specifically for cryptocurrency betting. With the right site and game, players can verify outcomes and track exactly what happens to every wager.
The online gambling market is projected to surpass $100 billion by 2026, and crypto casinos continue to gain market share. Players are increasingly drawn to transparent systems, quick withdrawals that settle in minutes rather than days, and games whose outcomes can be verified.
Some of the most popular crypto casino games today include crash multiplier games, provably fair Plinko, high-volatility themed slots, modern 3D slot titles, and live dealer roulette with multiplier bonuses. Each offers a different style of gameplay and risk level.
This guide covers five of the most popular crypto casino games in 2026. All of them appear on licensed sites with fairness verification systems, fast crypto withdrawals, and active player communities.
Choosing the right crypto casino game requires understanding a few key factors.
The following five games are widely played by crypto casino users in 2026:
Each represents a different type of gameplay, from multiplier betting to slots and live dealer experiences. Let’s start:
Best for: Players who enjoy fast rounds and transparent outcomes.
Standout feature: A very low house edge combined with provably fair verification for every round.
Best for: Players seeking frequent payouts and unique slot mechanics.
Standout feature: A rare slot format where characters appear from underground instead of spinning reels.
Best for: Players looking for a high-volatility slot with the possibility of large multiplier wins.
Standout feature: Stacking multipliers combined with cascading reels and a maximum payout exceeding 21,000x the original bet.
Best for: Players who prefer simple gameplay with strong transparency.
Standout feature: Flexible risk settings combined with high RTP and full outcome verification.
Best for: Players who enjoy live dealer experiences combined with high multiplier potential.
Standout feature: Random lightning multipliers that dramatically increase payouts on selected numbers.
A trustworthy license ensures player protection and fair payouts. Always confirm the casino is regulated before depositing cryptocurrency.
High-volatility games may produce huge wins but also long losing streaks. Select games that fit your budget and risk tolerance.
Provably fair technology allows players to verify that outcomes were generated before the wager was placed, improving transparency.
One advantage of crypto gambling is fast payouts. Choose sites that process withdrawals quickly so winnings can be accessed without delays.
Some bonuses exclude certain games from wagering contributions. Reading the rules first prevents unexpected restrictions.
Transparency is one of the main reasons crypto casino gaming continues to grow. Provably fair algorithms and publicly listed RTP values allow players to analyze games before placing bets. This level of accountability is uncommon in traditional online casinos.
Selecting the right game involves more than choosing the biggest bonus or flashiest design. The most important factors are volatility, bankroll compatibility, fairness verification, and withdrawal reliability.
Before depositing, always confirm the site’s license and payout speed. Those checks ensure that when you win, your funds are secure and accessible.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016