




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


AI Research Report | Sep 15, 2025

Image: Banking Use of Agentic AI (Figue 1, MIT Insights Survey 2025)
A recent MIT Technology Review Insights survey of 250 global banking executives found that 70% of banks already use agentic AI, with 16% running live deployments and 52% in pilots. For Canadian financial institutions and fintechs, the race is on with global competitors embedding AI solutions into compliance, fraud prevention, and customer service at scale.
Fraud detection and IT security are setting the pace. More than half of executives report that agentic AI is already highly capable in fraud detection (56%) and security (51%), with efficiency gains and customer experience improvements each cited by 41%. These use cases are significant because fraud losses are rising and regulators are upping their game on cyber resilience.
Practical applications include mortgage underwriting, small business lending, collections, dispute resolution, and know-your-customer KYC compliance. By using agentic agents together with expert human oversight, banks are compressing decision times from weeks to days and freeing time for employees to focus on higher value work.
As HSBC’s Ian Glasner puts it, “Think of agentic AI as like an intern helping you get all of the more simplistic tasks done, but the human is still there to oversee and take the final decision.”

Image: MIT Insights Banking Survey 2025 (Figure 6 Challenges, Agentic AI)
The survey also suggests that adoption challenges are growing, top three barriers include: 1. Governance, risk, and compliance (63%), 2. Shortage of technology skills (58%), and 3. Poor data quality and integration (54%).
To overcome, Canadian banks and fintechs should focus on resolving weak data linkages across silos and the shortage of AI ready talent needed to scale responsibly.
Trust compounds the issue. An EY study found that only 42% of consumers trust financial institutions to manage AI in their best interest, while 30% say they do not trust them at all. That leaves a net trust level of just 12%. In Canada, regulators are focused on consumer protection, and fintechs that build trust into their AI systems could gain an edge.
Leading institutions are building playbooks worth watching. DBS Bank in Singapore applies its PURE framework (Purposeful, unsurprising, respectful, and easy) to explain all customer facing AI systems. If performance metrics breach preset limits, a kill switch halts the system in real time. As DBS’s Nimish Panchmatia warns, “Agentic AI is a continuous journey. If done properly, there’s significant value at the end of it. But you have to persevere.”
HSBC maintains a detailed inventory of AI systems tied to business owners, risk classifications, and model documentation to create a governance baseline across 200,000 employees in more than 50 markets.
For Canadian banks and fintechs, these approaches show the value of aligning governance and technical innovation before scaling widely.
Banks in Asia, Europe, and the U.S. are experimenting with AI at pace, and many are moving from pilots to enterprise adoption. For Canada, efficiency and risk controls are only part of the story. The real differentiator will be who earns the confidence of consumers while scaling responsibly. Agile fintechs can seize this opening. Unlike large banks weighed down by legacy systems and regulatory complexity, fintechs can design AI solutions that are transparent, accountable, and 'trust first' from the start.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Regulation | Sep 15, 2025
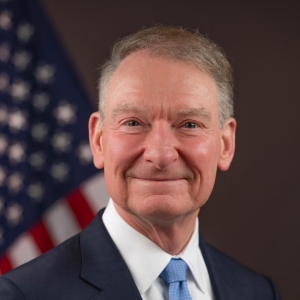
Image: Paul Atkins, SEC Chair
On September 10, 2025, SEC Chair Paul S. Atkins delivered a keynote address in Paris at the OECD Roundtable on Global Financial Markets, resetting the tone for U.S. capital markets. His speech positioned the SEC not as an adversary to entrepreneurs but as an enabler of growth, advancing Project Crypto, a broad modernization initiative aimed at bringing securities regulation into the blockchain era.
Paul S. Atkins, SEC Chair:
“It is a new day at the SEC. Policy will no longer be set by ad hoc enforcement actions. We will provide clear, predictable rules of the road so that innovators can thrive in the United States.”
One of the most significant parts of Atkins' remarks was his (the SEC's) endorsement of “super-app” platforms. This vision is a welcomed 180 after years of a type of regulate by enforcement approach that drove many U.S. crypto companies overseas.
For fintechs, it means a future where integrated platforms can grow under clear oversight, with investors able to choose from multiple custody models.
For Canadian innovators and regulators, it further raises urgent questions about how Canada will remain competitive if the U.S. creates a friendlier landscape for capital formation and digital asset services.
“We must allow for ‘super-app’ trading platform innovation that increases choice for market participants. Platforms should be able to offer trading, lending, and staking under a single regulatory umbrella.”
Atkins acknowledged that Europe has already moved ahead with the Markets in Crypto Assets regulation, praising the framework as a first attempt at comprehensive digital asset oversight while stressing that the U.S. will not fall behind. By declaring that America must be “second to none” in fostering innovation, he more or less confirmed that the competitive race was on.
For Canadian fintechs, this accelerates the competition challenge with Europe and the U.S. both moving towards clarity, while Canada’s rules remain relatively limited. This moment calls for proportionate approaches to policy that reduce friction for innovators while protecting investors, as highlighted in NCFA’s Canadian Banks and Fintechs Back Regulated Stablecoin post.
Beyond crypto, Atkins described the changes coming in the era of “agentic finance” where autonomous AI agents execute trades, allocate capital, and manage risk with compliance built directly into their code.
Coupled with blockchain, he argued, AI could democratize access to advanced strategies and lower costs for individuals.
The challenge for regulators is to install commonsense guardrails without overreacting.
Fintech builders heard that AI in finance is not only here to stay but will be supported if developed responsibly.
Atkins’ Paris keynote can be taken as a statement of intent. He placed crypto super apps, AI finance, and tokenized markets front and center of U.S. strategy. Fintechs and investors have immediate takeaways. That is regulatory clarity is coming, and the players and markets that adapt quickly will benefit most.
As U.S. and Europe continue to advance crypto regulatory frameworks, it's more critical than ever that Canada expeditiously create proportionate regulation, double down on enabling frameworks, and collaborate with global peers. Canada would benefit from positioning itself as a jurisdiction that rewards responsible experimentation. As Atkins put it, “crypto’s time has come.”
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Governance | Sep 15, 2025
Image: Freepik/Atlascompany
President Donald Trump has called for a sweeping change in how publicly listed U.S. companies report their financial results, advocating a move from quarterly disclosures to filings every six months. He argues this measure would save money and enable corporate leaders to concentrate on long term strategies rather than quarterly earnings pressure.
The requirement for quarterly reporting has been in place since 1970 under U.S. securities law, as outlined in SEC disclosure mandates introduced in the 1970s. The proposal requires approval by the U.S. Securities and Exchange Commission (SEC) and would align the U.S. with the UK and some European countries according to Reuters.
Under SEC rules now, U.S. issuers file annual 10-K reports and quarterly 10-Q updates. The 10-Q includes unaudited interim statements and disclosure about events and risks for the period. The SEC last examined reporting frequency in its 2018 request for comment, inviting views on whether the system encourages short term focus and how to reduce duplication while protecting investors.
Europe removed the quarterly mandate in 2013 through the Transparency Directive reform, and toward annual and half-year reports while preserving continuous disclosure duties. Singapore adopted a risk-based approach in 2020, ending blanket quarterly requirements for most issuers, as outlined in SGX’s 2020 change. In Canada, the CSA’s 2021 proposed amendments to NI 51-102 sought to streamline and reduce reporting obligations, including combining interim reports and MD&A, and offering electronic delivery models, but those reforms have been delayed and are not yet implemented.
Quarterly updates are great regular checkpoints when companies must reveal material issues and take questions on earnings calls. Moving to semiannual reports would reduce the frequency of these windows.
Supporters say fewer filings could lower compliance costs and ease short term pressure. Critics warn about weaker transparency and delayed red flags which could harm investors.
Any change would run through SEC rulemaking, including proposal, public comment, and cost benefit review. Smaller issuers or specific industries may require exemptions, and resistance from analysts and investors who rely on quarterly earnings can be expected. During Trump’s first term the idea didn't advance, but interest has resurfaced. Until a formal proposal appears, quarterly 10-Q filings remain in force.
Frequent disclosure reporting is at the core of how capital markets assign value and monitor risk. A move to semiannual reporting could help executives plan on a longer timeline, potentially supporting innovation and productivity. However, delayed release of material information could weaken investor confidence. Whether Trump's request stays as campaign talk or becomes an actual rule will depend on how the SEC responds and what institutional investors and company boards say.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Innovation | Sep 12, 2025
Image: Freepik/DC Studio
As reported by Venture Beat, Microsoft Research has released rStar2-Agent framework, a new training model approach that demonstrates how smaller models can deliver reasoning logic and performance once reserved for massive frontier models, but doesn't require massive systems or costs. While reinforcement learning in agentic AI isn't new, Microsoft's model adds important innovations in how it carefully verifies each step with fewer resources.
A 14 billion parameter model deliver results on math and science benchmarks that matched or even outperformed much larger 600-billion-parameter systems. Astonishingly, Microsoft's own tech report explains that that rStar2-Agent, “reached state-of-the-art results in under a week of training, surpassing a 671B-parameter system despite being just 14B in size.”
This scale difference is significant. Frontier models often need entire data centres while rStar2-Agent can be quickly trained and deployed on just a few high-end servers. For businesses and regulators in Canada, the impact could mean opening up access to this type of hyper efficient reasoning AI at a fraction of the cost, making it practical for fintech startups, universities, and financial institutions to adopt.
Competing head-to-head against giant foundation models isn't realistic for most Canadian firms or government programs. Efficient reasoning models, which can operate with constrained compute while still producing transparent and auditable steps, align directly with Canadian strengths, and is a pathway that Canadian innovators are well positioned to take on.
Canadian fintechs and startups can prioritize smarter training methods with domain specific fine tuning rather than trying to match the infrastructure scale of global hyperscalers. Smaller reasoning models also lower the barrier for enterprises that want to use AI in production but can't justify the heavy infrastructure investments of the largest and latest models.
As Microsoft describes it:
"[rStar2-Agent] demonstrates advanced cognitive behaviors, such as thinking carefully before using Python coding tools and reflecting on code execution feedback to autonomously explore, verify, and refine intermediate steps in complex problem-solving.”
The Canadian regulatory environment makes verified reasoning especially valuable. Models that validate their steps provide transparency and compliance support, which are essential in sectors like finance. This type of approach matches Canada’s push for trust, accountability, and explainability in AI.
Innovation, not size, could define Canada's leadership in AI. National strategies that support funding, research, and pilot programs for efficient reasoning AI could accelerate adoption across regulated industries. Fintech and financial institutions are natural leaders in this space because they already require digital public infrastructure that balances efficiency and inclusion.
The opportunity also extends beyond finance. Healthcare systems could use efficient reasoning AI for diagnostics where transparency is vital. Universities and research labs could run experiments on smaller models without prohibitive costs, fostering local innovation.
Canada has the opportunity to turn its limitations into a competitive edge by becoming a global hub for efficient reasoning AI that is affordable, reliable, exportable expertise, and aligned with priorities in finance, governance, and inclusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Financing | Sep 12, 2025

Image: Freepik
More Fintech IPO activity is back on the radar as the market window reopens after a quiet stretch. NCFA has already highlighted IPO ambitions from companies like Circle, eToro, Klarna, and Gemini in our post on 10 Fintech and Crypto IPOs 2025 Boom or Bubble. This week offers two new developments as Figure (FIGR) completed its Nasdaq debut yesterday, and Lendbuzz (LBZZ) files for IPO for artificial intelligence in finance.
On September 11, Figure Technology Solutions IPO raised US$787.5 million by selling 31.5 million shares at US$25 each. The stock opened at US$44 and closed at US$31.11, a 24% gain over the offering price.
Pricing came in above the increased range of US$20–22 with strong investor demand. FIGR is currently trading at US$7.34B
Founded in 2018, Figure built its model on the Provenance blockchain to originate and manage loans. It started with home equity lines of credit (HELOCs) and has expanded into personal loans, student refinancing, and digital asset markets. Their ambition is to transform how financial products are issued and traded by using blockchain settlement infrastructure.
For investors, the Figure debut shows that blockchain-enabled lending platforms can attract significant public market support. The strong first day debut performance, pricing above the raised range, and a revenue model that combines lending with fee-based infrastructure indicates that markets are open and positive on scalaling blockchain finance.
Comparable Canadian firms might include Ledn, Nesto, Mogo, Pine or Perch. Global peers include SoFi, UpStart, or Rocket Mortgage.
On September 12, Lendbuzz filed for a US IPO with a filing that showed 38% revenue growth to US$172.9 million in the first half of 2025 compared with US$125.4 million the year before. Net income rose to US$11.1 million from US$5.6 million, showing a fintech with scale and profitability. Comparable Canadian players include Canada Drives or Clutch.
The company has originated more than US$4B in loans and is backed by Goldman Sachs and MUFG. It has strengthened its funding base through securitizations, including a US$266M transaction in July 2025 and more than US$2.1B of completed asset-backed transactions to date.
Lendbuzz's filing scope shows how artificial intelligence can unlock new credit markets. By underwriting auto loans for borrowers with little or no credit history, the company is targeting underserved but financially active consumers. It will be interesting to track how its AI models manage risk as loan volumes grow over time.
These IPOs show how blockchain lending and AI powered finance niches like auto are moving into public markets with credible scale. Canadian fintechs need to keep in mind that global markets are rewarding fintechs that address inefficiencies in credit and capital markets, useful benchmarks for innovators preparing for their own future public listings.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Report | Sep 11, 2025

Image: Startups and Scaleups in UK Tech Sectors (Bennett School of Public Policy, Cambridge University)
On September 8 2025, the Bennett Institute for Public Policy (part of Cambridge University) published their latest research called, "Start-ups and scale-ups in UK technology sectors" (37 page PDF).
Fintech stands out as the country’s strongest UK tech sector, attracting the most venture capital investment. While the UK can now go toe to toe with the US in venture funding intensity relative to GDP, the scale of available capital, the reliance on foreign investors, and the dominance of acquisitions as an exit route continue to impact the growth pathways for UK start-ups.
Fintech remains the UK’s top sector for venture funding, showing the strength of financial innovation in London and across the country. Other sectors are growing quickly but fintech continues to set the pace.
The UK start-up ecosystem is attracting more foreign capital, especially from US investors. This fuels growth but raises questions about longer term independence and resilience.
London continues to dominate investment but other regions, particularly those linked to world-class universities are growing their presence.
Acquisitions are still the most common path for UK start-ups to generate investor returns. IPOs are still part of the picture but account for a much smaller share than in the US.
The UK now matches the US in terms of VC intensity relative to GDP, but it still lags far behind in total dollars raised. This gap matters most for later-stage fintech rounds.
London UK and other emerging hubs offer a vibrant, capital rich and globally attractive place to build but its reliance on foreign capital and the dominance of acquisitions as an exit route are challenges. Similar to Canada, the UK must building deeper domestic pools of later stage capital, strengthen listing markets, and support regional ecosystems to encourage more fintech start-ups to scale and stay anchored in the UK economy.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Initial Public Offering | Sep 11, 2025
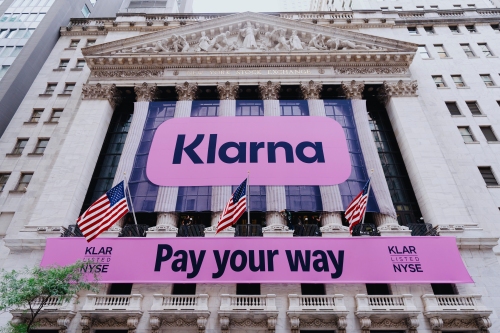
Image from Klarna IPO pricing announcement
Klarna’s debut on the New York Stock Exchange showed that investor interest in buy now pay later remains strong. The Swedish payments company priced its IPO at $40 per share, above the expected $35 to $37 range. Shares opened at $52 before closing at $46.40, a gain of about 16% on Klarna's debut, a market value of around $17.5 billion and raised proceeds of $1.37 billion, according to Reuters IPO coverage.
In 2021, Klarna was valued at $45.6 billion when SoftBank invested heavily, only to fall to $6.7 billion in a 2022 down round. The company’s new valuation is proof of a rebound and investor interest in fintech's open IPO window, although still well below its pandemic-era peak.
Klarna joins other fintechs who have jumped through the IPO window recently, such as Circle and Bullish. Klarna's registration statement filed with the SEC detailed its current scale at 111 million active consumers, 790,000 merchants, and operating in 26 countries.
Significantly, Klarna disclosed that 99% of consumer loans extended in 2024 were repaid on time, much better than the U.S. credit card delinquency rate of 3.05% for the same period. These repayment figures were key in reassuring investors about the resilience of the buy now pay later (BNPL) model.
Buy now pay later continues to expand. U.S. online purchases using BNPL services reached $82.4 billion in 2024, up 9.9% from the previous year. By August 2025, volumes had already hit $56.3 billion.
Klarna, Affirm, and Afterpay dominate the market, but the model has faced criticism that it encourages overspending and exposes providers to consumer defaults. Klarna’s repayment performance, documented in SEC filings, is now one of its key competitive advantages as it enters the scrutiny of public markets.
For fintech, Klarna’s IPO demonstrates that investors in the current climate are willing to fund growth companies with credible metrics, helping restore momentum after a period of political and market uncertainty earlier this year.
Sebastian Siemiatkowski CEO Klarna framed the IPO as a chance to build stronger ties with U.S. consumers. With a merchant base that includes major retailers, Klarna is positioning itself as a mainstream payments company rather than just a niche credit provider. Investors will be tracking closely, future quarterly financials, credit quality data, and U.S. adoption rates.
Klarna’s valuation may remain far below its 2021 peak, but the company’s NYSE IPO confirms that public market investors see value in the buy now pay later model at global scale, and are willing to back its growth.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016