




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Trade and Tariffs| July 10, 2025
Image: Freepik/rawpixel.com
As of July 8, 2025, Reuters reports that the U.S. has collected about $100 billion in tariff revenues in 2025, and according to U.S. Treasury Secretary Scott Bessent, tariff revenue projections could reach $300 billion by the end of this year.
Customs duties in May alone reached $22.8 billion or almost 4x the amount one year prior. While the White House views this revenue as a fiscal benefit, economists caution that tariffs create economic distortions, raise costs for importers, and increase prices for consumers.
FactCheck.org analyzed Treasury data and found that U.S. customs and tariffs generated $37.8 billion in April and May combined, with $22.2 billion in May alone, which is well below the $88 billion those months were referenced to yield, let alone the larger $122 billion claimed later. It highlights how public statements about tariff income often exceed actual collections.
The Business Council of Canada reports that Canadian exports to the U.S. dropped 26.5% year-over-year, with Canada's share of exports to the U.S. falling from 78% to 68%.
Export volumes fell 10.8% in April before seeing a small 1.1% rebound in May but remain historically low. The Business Council of Canada warned that this declines is another “wake-up call” with advocates pushing to diversify trade into Southeast Asia, and move ahead with the One Canadian Economy Act .
Canada’s proposed 3% digital services tax was supposed to raise C$7.2 billion over five years but was dropped by PM Carney late June after it triggered the suspension of trade talks .
According to The Guardian, Nobel laureate economist Joseph Stiglitz warned that Canada's repeal represents “a troubling precedent for economic sovereignty,” describing it as a resignation to U.S. economic coercion instead of a strategic trade policy.
On July 7, Trump issued letters announcing tariffs between 25–40% to start August 1 on imports from 14 countries, including South Korea and Japan. Canada wasn't included on this list but is still subject to existing 25% tariffs on steel, aluminum, and autos, along with 10% U.S. duties on energy and potash not covered by CUSMA. Copper tariffs are also in Trump's sights which is another concern. The S&P 500 fell nearly 1%, it's largest global drop in weeks following the tariff letter announcement.
Tariff uncertainty is directly affecting Canadian fintechs. Cross-border payment providers are facing higher Foreign Exchange (FX) costs and more regulatory complexity.
Trade finance platforms have warned that rising tariff uncertainty is leading to higher invoice default rates among SME exporters and creating pressure on fintech services who need predictable trade flows.
According to PYMTS, many fintechs are accelerating adoption of tokenized receivables and embedded credit insurance tools to help manage risk, speed up funding, and reduce exposure to trade disruption.
“Tokenization… offers the potential to streamline the inefficient $9.7 trillion trade finance market.”
Canada and the U.S. are negotiating a new security and economic partnership with a July 21 target date but without consequences for missing the deadline, extended talks will cause further economic harm. And if there is no deal, Canada could move forward with retaliatory tariffs while providing targeted relief, which could include SME and export-orientated fintechs.
Looking to diversify and reduce reliance on U.S. markets, Canada is moving quickly to finalize a free trade agreement with Southeast Asian nations. Foreign Minister Anita Anand confirmed that “work is being done with alacrity to finalise the text of the free trade agreement” with ASEAN, adding that economic cooperation will also include energy, food security, digital economy, and artificial intelligence.
The July 21 deadline will impact Canada’s exports and redefine trade, innovation, and the financial ecosystem, as it impacts geopolitical volatility, SME access to financing, and investor perceptions. This is a decisive moment for Canada’s economic resilience and fintech innovation.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 9, 2025

Image: Freepik/macrovector
Ontario is not just one of Canada’s most populated provinces; it’s also a hotbed for online gaming innovations. Some of Ontario’s most popular games are inspired by recognizable landmarks such as Niagara Falls or the Northern Lights. We’ll go over five of the most popular Ontario-inspired slot themes that combine entertainment with a taste of home.
A classic-style slot machine centred around the iconic Niagara Falls. The game features retro visuals, including cascading reels and waterfall wilds on both sides of the slot, as well as a unique symbol found on the reels.
The Niagara Falls slot is a popular choice due to its recognizable imagery, combined with the slot's straightforward gameplay. Appealing to new and seasoned players, along with proud Canadians and tourists visiting the province, looking to get a feel for the sights.
Inspired by the legendary Mega Moolah series, this Ontario-exclusive slot is set in a steampunk-inspired gold factory following a similar iconic jackpot system. It collects a portion of the players' bets and increases to four progressive prizes.
The game can be played on mobile devices and features a unique Canadian theme. A progressive jackpot game featuring:
Maple Moolah is renowned for its lighthearted take on Ontario’s rural culture, which resonates deeply with locals.
While not exclusive to Ontario, the Northern Sky slot resonates with all Canadian players. Those familiar with the northern lights and serene landscapes, often visible from Northern Ontario, can appreciate the beauty of the stunning sky in the background, with glimpses of the prizes out front.
With re-spin features on every win and crystals shaped like animals inspired by the Canadian wilderness, the Northern Sky has made a groundbreaking mix of a calm, serene aesthetic coupled with intensive gameplay.
A historical-themed slot that takes players into Ontario’s 19th-century gold mining boom. The theme replicates the feeling of striking gold with big wins:
Players in Ontario love this game not only for its blend of historical charm and modern gameplay mechanics but also for its high RTP and jackpot potential. Making the Gold Rush a thrilling experience for any players who want to immerse themselves in treasure-themed gameplay.
Delivering the essence of Canadian culture, Hockey Hero offers players an on-ice experience featuring symbols such as hockey sticks, pucks, and trophies, creating an authentic ice hockey stadium experience.
With free spins, an interactive bonus game and an extensive range of possible payouts, Hockey Hero maintains the action in a fast and unpredictable way, replicating an authentic Canadian hockey match.
Combining national pride and interactive and straightforward gameplay is what makes Hockey Hero as prominent as it is. Authentic sound effects, energetic pacing, and fun bonus features make this choice the go-to for both hockey fans and casual slot players.
From the roaring beauty of Niagara Falls to the cultural pride of Canada’s favourite sport, these Ontario-themed slots showcase just how immersive and localized online gaming can be. Each title offers more than just reels; they deliver a sense of place, history, and pride that resonates deeply with Ontario players.
Whether you’re chasing progressive jackpots in Maple Moolah or soaking in the auroras of Northern Sky, there’s something for every style and personality. As Ontario continues to thrive as a regulated iGaming market, expect even more homegrown themes to take centre stage across Canada’s best online casinos.
-
The JackpotCity Ontario Team
Backed by years of experience in online gaming, the Jackpot City Ontario team is dedicated to delivering expert insights and responsible gaming tips for players across the province. With a deep passion for digital gaming and a strong commitment to compliance with Ontario’s regulated market, our writers ensure every article reflects the excitement, fairness, and transparency that define the Jackpot City experience. From strategy guides to the latest casino game releases, the team is here to help you play smart and have fun—safely and responsibly.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
BC Fintech Tax Credit | July 8, 2025
Image: Freepik
British Columbia is making perman Interactive Digital Media Tax Credit (IDMTC) and raising the rate to 25%, effective September 1, 2025. The expanded credit applies to qualified salaries and wages for the development of video games, virtual reality (VR) applications, educational software and simulators.
The IDMTC was first introduced in 2010. The 25% rate was recently put on the table as a temporary increase under Budget 2025 which is now being made permanent. It replaces the earlier 17.5% baseline rate and is aimed at helping creators retain staff, attract capital, and grow jobs in the province’s interactive digital media sector. According to CreativeBC, the industry contributes over $1 billion to provincial GDP and supports over 20,000 jobs.
David Eby, BC Premier, said that it will boost long term investment:
“This tax credit will help game developers hire, attract new investment and keep building some of the best games in the world.”
Brenda Bailey, Finance Minister and former game developer, emphasized the impact on both indie and enterprise studios:
“Whether they are a software engineer at a VR developer or an artist at an independent game studio, we stand by our developers.”
The province also announced:
There are currently 161 video game companies and 230 immersive tech firms operating in BC, many of them with fewer than 10 employees. Global developers with a presence in the province include Microsoft, Nintendo, EA, Take-Two, and CD Projekt Red.
This permanent tax credit increase will strengthen the planning outlook for studios, venture funds, and fintechs financing interactive media. Companies using revenue-based financing or IP-backed lending models now will be operating in a more stable tax environment.
Investors and lenders can model developer cash flow with improved accuracy, especially for VR and immersive media startups that operate on tight burn rates. For full details, visit the official IDMTC program page.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Financial Advice | July 8, 2025

Image: Freepik/rawpixel.com
In the UK, the Financial Conduct Authority (FCA) has proposed a new approach to tackle the issue of improving access to financial advice, so people can make informed investment decisions. The FCA is calling this a 'once in a generation' reform that would let firms provide targeted and simplified financial advice to underserved populations without the regulatory burden of full-service advisory. Should Canada be exploring a similar path?
On June 29, 2025, the FCA released a consultation in effort to alter how financial guidance is delivered. According to the regulator, only 9% of UK adults received regulated advice in 2024. At the same time, over 7 million people are holding more than £10,000 in cash without investing it. The proposed rules include two core categories:
The FCA expects around 100 firms to offer services under these reforms by April 2026. The proposal aims to support better outcomes for consumers while still protecting investors.
In Canada, regulated investment advice is tightly controlled. Firms offering investment recommendations must be registered with a provincial securities regulator and meet strict know-your-client (KYC) and suitability obligations. This approach is critical for investor protection but it creates high cost and operational barriers for reaching clients with modest portfolios.
The FCAC’s National Financial Literacy Strategy 2021–2026 emphasizes its mandate to enhance Canadians’ financial knowledge and resilience, but efforts so far rely heavily on education, tools, and public awareness. The CSA’s Investor Education Committee has launched social campaigns, investor alerts, and literacy tools to empower Canadians to make informed financial decisions.
According to CSA research, more than 40% report low confidence in their investment knowledge. Findings show a decline in advisor use (down to 61%), while DIY attitudes rise (45% have self-directed accounts), raising concerns about whether Canadians have sufficient knowledge and confidence to manage investments on their own.
Canada’s robo-advisor market is expanding swiftly. Wealthsimple alone manages over $70 billion CAD (as of June 2025), Questrade’s Questwealth holds $30 billion CAD (early 2020), and even more growth is expected as digital investing gains traction, with services increasingly adopted by younger investors. These platforms offer digital-first, affordable investment tools, but remain constrained by current regulatory expectations.
By contrast, the FCA's framework could allow robo-advisors to deliver access to simpler advice or proactive guidance based on behavioural data. These changes have the potential to increase access while reducing costs, without compromising key investor protections. In Canada, any comparable flexibility would require regulatory change.
Another growing channel for financial guidance is social media. In Canada, 82% of Gen Z investors report following influencers for financial tips, and 44% believe online advice is as useful as traditional advisors. While some content is educational, the Ontario Securities Commission and Alberta Securities Commission have raised concerns about unregistered finfluencers promoting securities without appropriate disclosures.
If Canada created space for fintechs and advisors to offer low-cost, regulated advice digitally, it could reduce dependence on informal and sometimes misleading content. The FCA’s 'once in a lifetime' reforms aim to do just that, offering a model Canada could adapt to fit our regulatory landscape.
Canada’s fintech innovators are capable of building trusted, scalable tools to help close the advice gap. But changes to regulatory structures need to happen to support new delivery models. The FCA’s targeted support and simplified advice categories are a good benchmark and approach. Canadian regulators and policy makers should be exploring how to safely expand access to financial guidance that is compliant, cost-effective, and in the public interest.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
M&A | July 7, 2025

Imgae: Freepik
The acquisition of WealthONE Bank of Canada by Globalive and its Canadian investment partners has officially closed, following federal government approval on June 18, 2025. Establishing a precedent, it's the first time a non-bank, fintech-aligned private investor group has successfully taken control of a Schedule I chartered bank in Canada.
The deal follows a two-year national security review under the Investment Canada Act, which required WealthONE’s former owners to divest due to foreign influence concerns. WealthONE had previously faced scrutiny over ties to China-based investors, prompting a 2023 directive from Ottawa to restructure ownership.
Globallive led by Anthony Lacavera (telcom and fintech entrepreneur) now owns 65% of WealthONE’s equity. The remaining 35% is held by a group of Canadian investors whose names have not been disclosed publicly. According to Bloomberg, the full acquisition was valued at approximately $58 million CAD, and covers all issued and outstanding shares of WealthONE and includes a commitment by the buyers to inject new capital to support the bank’s next phase of growth.
The transaction was reviewed by multiple federal departments and found to meet requirements for Canadian control, transparency, and risk mitigation. Worth noting that the Competition Bureau previously cleared the acquisition in advance of the final approval.
WealthONE will continue to operate independently under its current federal Schedule I charter. Its current CEO, Paul Leonard, will remain in place and work with Globalive to expand products and reach more customers in underserved market segments.
WealthONE was founded in 2016 and currently manages approximately $516 million CAD in assets. The bank focuses on customers often excluded from traditional financial institutions, including newcomers, immigrants, self-employed professionals, and small business owners.
In the months leading up to the acquisition, WealthONE introduced a cloud-based digital onboarding platform that supports accounts such as TFSAs, GICs, and high-interest savings.
According to AINVEST, Globalive intends to scale WealthONE’s operations to reach between $750 -$800 million CAD in assets by streamlining operations, modern digital services, and lean risk-adjusted lending models.
Globalive's acquisition of WealthONE demonstrates how new non-bank players can enter Canada’s banking system. Instead of applying for a new banking license, fintechs and private investors now have a verified path of entering the market via acquisition of existing chartered institutions. The WealthONE deal sets precedent that private capital can take control of federally regulated banks (as long as there aren't any national security concerns).
For fintech founders, challenger banks, and digital lenders, it creates an opportunity to scale into deposit-taking and lending under an existing charter, without having to go through the arduous process of applying for a new banking license which will likely take a minimum of 5 years, just ask Santander.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Banking | July 7, 2025
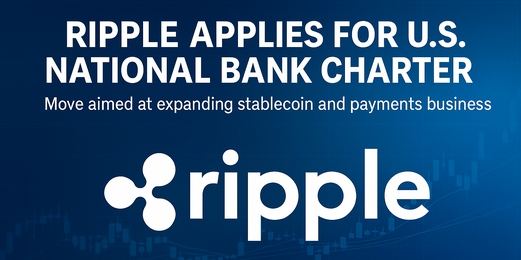
Ripple has officially applied for a national bank charter from the US Office of the Comptroller of the Currency (OCC). The company is also seeking a Federal Reserve master account to support direct access to US payment rails.
CEO Brad Garlinghouse confirmed the news on X:
True to our long-standing compliance roots, @Ripple is applying for a national bank charter from the OCC. If approved, we would have both state (via NYDFS) and federal oversight, a new (and unique!) benchmark for trust in the stablecoin market.
Earlier in the week via… https://t.co/IdiR7x3eWZ
— Brad Garlinghouse (@bgarlinghouse) July 2, 2025
If approved, Ripple would bypass correspondent banks by settling payments directly with the Fed and holding dollar reserves without intermediaries. This is designed to support Ripple’s push to offer a compliant, enterprise-grade stablecoin and accelerate global payments. These objectives align with new federal rules proposed under the GENIUS Act, which sets clear reserve and disclosure standards for stablecoin issuers.
Ripple’s approach mirrors that of Anchorage Digital and Circle, which operate under national trust bank charters regulated by the OCC. Ripple may use its regulated subsidiary, Standard Custody & Trust, to separate digital asset exposure from its core balance sheet. This structure could help the firm meet Basel III capital requirements by keeping volatile assets like XRP off its banking books.
Following the announcement, XRP surged above $2.28 as trading volume spiked. Analysts said the rally was driven by rising confidence that Ripple’s regulatory strategy will boost its long-term institutional credibility.
If Ripple is granted the charter and Fed account, it will become one of the few crypto-native firms operating fully within the traditional banking system. It's a significant and growing trend among major fintechs like Circle, Wise, and others seeking deeper integration with regulated payment rails. For Canadian fintechs and regulators, Ripple’s move could accelerate the need to clarify stablecoin policy, custody standards, and access to domestic settlement infrastructure. Regulatory certainty is a competitive advantage today and quickly becoming the norm.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Tokenization | July 3, 2025

Image: Freepik
On June 30, 2025, Robinhood announced a major expansion into tokenized assets and crypto infrastructure during an event in Cannes. The company’s official release detailed its launch of tokenized U.S. equities for EU users, new staking and derivatives products, and the development of a proprietary Layer 2 blockchain designed to support real world asset (RWA) tokenization. It's a clear pivot and global crypto strategy that could define the future of hybrid investing platforms.
Robinhood will allow European Economic Area (EEA) users to buy and sell tokenized versions of over 200 U.S. stocks and ETFs. These digital assets come with no commission, no spread, and include dividend payments, mirroring their traditional equivalents while trading continuously during the week. The tokens are initially issued on Arbitrum but will transition to Robinhood’s newly announced Layer 2 blockchain, which is being developed specifically to support RWA tokenization, self-custody wallets, and instant settlement.
The EU rollout aims to open access to U.S. equities for hundreds of millions of crypto-enabled users. The goal is to create a multi-asset investment experience that spans stocks, ETFs, and digital currencies all on one unified platform.
Robinhood’s expansion also includes the launch of crypto perpetual futures contracts for Bitcoin and Ethereum. These will be offered with up to 3× leverage across eligible EU users, with order routing handled through Bitstamp’s regulated platform. At the same time, Robinhood has introduced staking support for Ethereum and Solana. Staking is already live in the EU and will expand to U.S. users where legally permitted.
Robinhood is also offering deposit incentives, including bonuses of up to 2% on incoming crypto transfers, with the company targeting up to $500 million in new crypto inflows.
Robinhood confirmed that it is building its own Layer 2 blockchain. The network will enable fractional ownership of stocks and ETFs, wallet-native asset recovery, smart contract interoperability, and real time cross-chain bridging. It will also provide the infrastructure for on-chain settlement of financial instruments such as tokenized equities and derivatives. Having it's own blockchain will reduce dependence on third parties while positioning Robinhood to eventually become the protocol layer for its own assets and services, including digital custody and regulated RWA trading.
Robinhood also launched a crypto rewards credit card, allowing users to automatically convert cashback into digital currencies. In addition, the company now lets users choose which crypto or stock purchases to sell first for tax purposes, smart order routing, and high frequency charts designed to support more active traders. A new AI assistant called Cortex is being integrated into the app, offering personalized alerts, market trend recognition, and portfolio analysis for premium users.
All of these updates are part of Robinhood’s broader strategy to become a comprehensive investing ecosystem that spans traditional equities, digital assets, and blockchain infrastructure.
Robinhood’s stock rose by more than 12% following the announcement. As reported by MarketWatch, the SEC also sent market signals that may be interpreted as supportive. Robinhood has taken advantage of the EU's open approach towards digital finance and pilot models that aren't yet permitted in Canada, raising an important question: if tokenized equities are safe and functional for the EU, what regulatory barriers continue to hold back innovation in Canada?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016