




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Stablecoins | July 18, 2025
Image: Freepik/gstudioimagen
The dominoes are definitely starting to fall. Citigroup and Bank of America have confirmed they are developing or preparing to launch their own stablecoins. In back-to-back Q2 earnings calls this week, executives from both banks outlined their intentions to support stablecoin issuance for use cases like digital payments and tokenized deposits.
As reported by Reuters, Citigroup CEO Jane Fraser said on July 15 that the bank is “looking at the issuance of a Citi stablecoin” and that stablecoins would fit within the bank’s current initiatives in tokenized deposits, custody, and digital cash on/off-ramp services.
Then just a day later, Bank of America CEO Brian Moynihan confirmed that Bank of America is actively preparing to issue a stablecoin of its own. He told analysts the bank “expects to launch” a stablecoin and is in conversations with regulators about what a compliant U.S. dollar-backed version would require. Moynihan also pointed to the advancement of the GENIUS Act in Congress as a key milestone for legal clarity.
Note, JPMorgan Chase already has functional stablecoin infrastructure. JPM Coin, a wholesale payments vehicle used by institutional clients, currently moves over $1 billion in transactions daily. The bank is now expanding into tokenized deposit products for digital settlement use.
Tokenized deposits are regular bank deposits that have been turned into digital tokens. They still belong to the customer and are backed by the bank, but because they run on blockchain technology, they can move money faster and incorporate programmable rules.
Worth noting that while Morgan Stanley has not announced its own stablecoin it confirmed during its latest earnings call that it is “actively discussing” potential use cases. CFO Sharon Yeshaya said the firm is monitoring the regulatory landscape and evaluating client needs.
In a Reuters article May 23, 2025, mentioned that JPMorgan Chase, Bank of America, Citigroup, Wells Fargo, and other large commercial banks (including U.S. Bank via consortium channels) are “exploring whether to team up to issue a joint stablecoin,”, but there have been no commitments or formal statements issued yet.
Traditional banks are positioning themselves to be regulated providers of digital dollars that can be used in fast, transparent, and low-cost transactions across modern financial systems.
Stablecoins issued by large banks could compete or potentially replace legacy payment systems for cross-border transfers, securities settlement, reserve management, and cash liquidity optimization. Eventually they may support consumer payments, although bank executives have stressed that the focus is on B2B use cases first.
Bank of England Governor Andrew Bailey recently warned that privately issued stablecoins could destabilize global financial systems if left unregulated, reinforcing the urgency for banks to operate within robust legal and supervisory frameworks.
Traditional finance (TradFi) is gearing up to compete directly with crypto native infrastructure in the issuance and management of digital cash.
The rapid entry of big banks like Citi and Bank of America into stablecoins confirm what fintech leaders have predicted for years. Programmable money will enter the banking mainstream, depending on regulatory approval and market demand.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Investment Partnership | July 17, 2025
Image: Freepik/nensuria
On July 16, Toronto-based Fintech d1git1 announced that RBC Wealth Management has partnered with them to upgrade advisor analytics and invest in its North American growth. This deal includes both a technology rollout and a capital injection, with RBC leading a new investment round joined by U.S. venture firm JAM FINTOP.
No financial terms were disclosed publicly but sources have reported that RBC is the lead investor and funds will help d1g1t expand its product roadmap, grow its team, and enter new markets in the United States.
In addition to the investment and as part of the agreement, RBC will integrate d1g1t’s performance and risk analytics engine into its advisor platforms across Canada. d1g1t is designed to replace fragmented legacy systems with a single digital infrastructure used by registered investment advisors, multi family offices, broker dealers, and custodians.
The company provides enterprise grade tools that support advisors and wealth managers in delivering consistent reporting, transparent client engagement, and scalable operations. Its integrated platform is already used by firms in both Canada and the U.S.
Barrie Laver, MD and Head of Venture Capital and Private Equity at RBC:
“We’re proud to invest in d1g1t, a company that’s helping to redefine wealth technology. What sets them apart is the combination of deep financial engineering expertise, bold technology vision, and a product that’s purpose built to help solve the most pressing needs of modern wealth firms.”
Dr. Dan Rosen, d1g1t CEO and co founder, described the partnership as a milestone that brings next generation analytics at scale to a leading financial institution. RBC manages over $1.4 trillion CAD in assets across wealth operations in Canada, the U.S., the British Isles, and Asia. Its Canadian advisor network includes more than 6,000 professionals.
It's a significant deal in the wealthtech sector and considered rare that a major Canadian bank integrates a fintech's platform solution and invests in them too.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto Crime | July 16, 2025
Image: The State of Cross Chain Crime in 2025 (Elliptic Report Cover)
Just in, according to Elliptic’s State of Cross-Chain Crime 2025 report, illegal activity involving decentralized exchanges, bridges, and swap services reached $21.8 billion in 2025 so far, more than 3x the figure in 2023 ($7 billion) and 5x in 2022 ($4 billion). This trend highlights how criminals are exploiting DEXs, cross-chain bridges, and coin swap services to hide money transfers across multiple blockchains.
Elliptic reports that 33% of complex crypto crime investigations use more than 3 blockchains. Another 27% involve over 5 blockchains, while 20% span more than 10. Chain-hopping is a technique that allows criminals, both big and small, to move assets quickly from one chain to another to confuse investigators.
In one confirmed case, a North Korean related wallet moved stolen funds through Bitcoin, Ethereum, Arbitrum, Base, and Tron, all in succession with that single operation using a total of 48 coordinated swaps.
Coin swap platforms have become a preferred laundering tool for ransomware groups, darknet markets, and offshore gambling operations. Unlike DEXs or bridges, these services are centralized, often use privacy-focused Telegram chat service, and allow anonymous swaps between chains with no KYC.
Some operate in regions under sanctions, including Crimea. Elliptic also confirmed that North Korean hackers laundered $200 million of the $1.46 billion Bybit theft through a service called eXch. The platform refused to cooperate with law enforcement and was later shut down by German and Dutch authorities.
Many of the methods used by criminals involve a mix of asset swaps, bridges, gas fee financing, and privacy coins. Elliptic's report confirms that over 300 bridge combinations are being traced automatically using virtual value transfer events (VVTEs), a forensic analytics method developed by Elliptic to automatically trace the source and destination of cross-chain transactions, especially those that pass through bridges.
This automation is a lifeline to investigations and allows regulators, compliance teams, and law enforcement to trace cross-chain fund flows in seconds instead of hours. Elliptic now supports more than 50 blockchains, making it one of the most comprehensive tools available for risk detection.
The scale and speed of illicit activity are outpacing traditional compliance methods. Without updated tools and policies, Canadian fintechs and financial institutions face rising legal, reputational, and regulatory risk. It feels like we've been saying this for a while now, but the use of advanced tracking, wallet screening, and automated compliance solutions are no longer optional, and in fact essential for protecting the integrity of Canada's growing digital finance sector.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Funding | July 16, 2025
Image courtesy of Quandri
Vancouver and Boston-based insurtech Quandri has raised US$12 million to accelerate the rollout of its AI-powered Renewal Intelligence Platform across the Canadian and U.S. insurance markets. The round was led by Framework Venture Partners, with follow-on investments from FUSE and Defined Capital, and strategic backing from Intact Ventures. To date Quandri has raised over US$20 million since founding in 2021.
The new capital will fuel a hiring push, deepen AI engineering capacity, and support the opening of a new U.S. office in Boston alongside the expansion of its Vancouver headquarters.
"We’ve had strong conviction in our vision from day one, but having new investors like Framework and Intact supporting our journey adds real momentum," said Jackson Fregeau, co-founder and CEO. "Their support affirms the value we’re delivering to brokerages and agencies, and gives us the insight and fuel we need to keep pushing the industry forward."
In a recent interview with the National Crowdfunding and Fintech Association (NCFA), Quandri co-founder and CEO Jackson Fregeau shared additional insights on the company’s platform, market traction, and future plans.
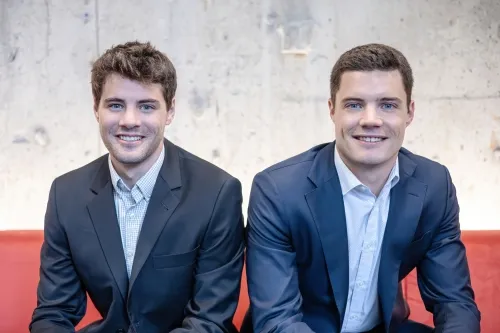
Image: Quandri Co-founders, Jackson Fregeau (CEO) and Jamieson Fregeau (President)
Quandri’s Renewal Intelligence Platform is designed specifically to automate renewal servicing workflows for insurance brokerages and agencies. It stands out in a crowded insurtech space due to its deep contextual understanding of insurance data, its focused product design, and its high degree of configurability.
Jackson Fregeau, co-founder and CEO:
"What differentiates us as a business is threefold.
First, deep intelligence. We ingest millions of insurance policies every month, and our AI has a deep understanding of underwriting guidelines across all regulatory environments in North America. This means we have a deep insurance context and can apply this to the automation of a process — taking it all the way to communication with a client, thanks to the trust our customers have in us.
Second, focus. We chose a clear focus area and spent our time driving as much value as possible. With renewals as an example, we aren’t just automating the process — we’re driving additional revenue through cross-selling and upselling, while also increasing retention rates.
Third, a high degree of configurability. Our AI can analyze hundreds of variables on a single renewal to surface insights and deliver action. Our customers can configure all of this if they want, to build a highly personalized and relevant experience for their clients."
Brokerages using Quandri have reported major productivity and revenue improvements.
"We’ve seen customers save over 6,000 hours a year by automating their renewal review process — work that previously required full teams to manually review documents," said Fregeau. "For example, one of our customers repurposed over 5% of their workforce — 10 of 200 employees — shifting experienced team members into higher-impact roles that support growth and improve the client experience.
"In another case, one brokerage reported a 350% return on investment in just a few months — proof that this isn’t just about saving time. It’s about unlocking a more resilient, scalable way to run a brokerage. And the benefits go beyond operational efficiency; one brokerage reported a 2% increase in client retention, driven by the ability to proactively reach out to customers with consistent, value-based renewal conversations."
Quandri has been operating in the U.S. for the past two years, but has seen significant acceleration over the last 12 months.
"The biggest learning has been about market dynamics. It’s 50 different markets, with a high degree of fragmentation and regionalism," said Fregeau. "Understanding how this all worked, and ensuring our platform could support this complexity was very important.
"What we did find consistent across the board is that brokers and agents are facing the same core challenges: shrinking margins, excessive manual work, and insufficient time for clients. If anything, the urgency for AI-powered solutions feels even greater in the U.S., where scale and complexity make these pain points harder to ignore."
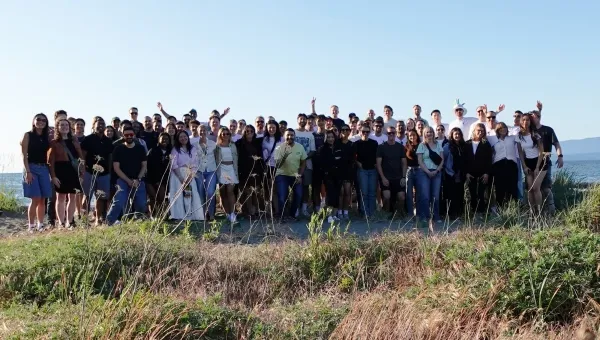
Quandri team June 2025
The company plans to hire more than 40 people before the end of 2025 and has opened a new 15,000-square-foot office in Vancouver to support its growth.
"Our priorities are expanding our integrations so we can serve more customers across the U.S. who want to use our platform," said Fregeau. "We’re also hyper-focused on growing our engineering team to drive deeper AI capabilities and scale our impact across the broker and agent servicing stack."
Fregeau also offered reflections on scaling a fintech business into the U.S., especially for Canadian startups.
"While there is work when it comes to data localization, regulatory alignment, and compliance, those aren’t significant hurdles to overcome. The larger barriers are related to your product-market fit (PMF). Don’t assume PMF in one market will translate to the other — even though they may look similar, they are different.
"Do your due diligence, interview prospects, understand the real pains in the market and what’s different from your home market. It will take time to learn this, and that's okay, because it's worth it. However, we initially underestimated the differences and could have made better decisions had we been more open-minded in the beginning."
Fregeau added:
"There’s massive opportunity, so go for it. Getting to 70% operational isn’t that hard — the hard part is taking something that works in 70% of cases, and making it work in the enterprise 95% of the time, predictably and consistently. Otherwise, you won’t get adoption, renewals or expansions. Listen to your customers, but also know when you need to give them something that they aren’t asking for that will solve the root of their problem. There is no secret formula besides hard work and doing the gritty things right, day in and day out, over a long period of time."
Quandri's recent financing round highlights the demand for specialized, AI powered tools built for legacy industries. By focusing on renewals and customer engagement in a data-drien environment, Quandri is helping clients boost operational gains and capture longer term strategic value. Expanding product suite and footprint across North America, Quandri's stack could become foundational infrastructure for insurance broker operations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Agentic AI | July 14, 2025
Image: Freepik AI
Last Friday several outlets reported that Goldman Sachs is now using an AI software engineer named Devin. Now it may seem like what's the big deal here, everyone is using AI engineers, but this is a major U.S. bank, and Goldman says some developer teams using Devin are already producing 3x to 4x more output.
This is not a trial in a lab. It is a working system inside the bank. According to AInvest, Goldman has about 12,000 developers deployed across hundreds of teams (read 'at risk'). It's one of the first major publicly known cases of a major financial institution putting AI to work in a coding production environment.
Devin can complete full software tasks. It can set up development environments, run scripts, write and test code, and fix bugs on its own. It's agentic AI and can do these things without being told what to do at each step.
Having said that, it doesn't mean it always works (just yet). As reported by Fast Company, when Cognition Labs tested Devin, it only succeeded 3 out of 30 GitHub problems. That’s why Goldman still needs human developers to supervise the output currently. Teams check the code for accuracy and make sure it’s secure, and reviewed before it gets deployed.
Goldman is sending a clear message that AI tools are delivering measurable gains. Some software teams are producing three to four times more than before, and tools like the GS AI Assistant are already being used by 10,000 employees at Goldman for non-coding tasks. Any company that ignores AI now, seemingly will only fell behind on speed, output, and efficiency.
With Devin handling routine tasks, developers are now spending more time reviewing code, planning architecture, and testing fringe use cases, which are all tasks more valuable to the final product experience than basic coding (warning to junior developers).
So, companies must rethink how they hire, train, and structure their technical teams to focus on oversight and system integration.
Devin is currently a closed, proprietary tool unavailable to the public. It's also expensive and under NDA. That leaves smaller firms with0ut access and at a disadvantage. Canadian fintechs should be piloting open or commercial agent-based tools or partner with AI providers that offer more access to remain competitive.
AI code can fail spectacularly if unreviewed by a human currently. This can lead to security holes and/or logic gaps. Canadian companies also need human engineers to oversee similar governance, such as audits, version controls, quality assurance gates, and compliance reviews.
Not too long ago, we said the 'robots were here'! Well now Goldman is using AI to write their banking production code. Productivity is rising but it comes with new risks. Roles are changing, and oversight and governance is critical. Canadian financial technology companies must not fall too far behind. Those that jump in now will likely be in a better position to compete later.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto | July 11, 2025

Image: BTCUSD Tradingview
Bitcoin just printed a massive green candle, BTC reaching a new all-time-high (ATH) of USD $118,000, boosted by institutional inflows, constrained supply, and regulatory momentum in global markets. At the same time, Canada is working to finalize long awaited rules to bring clarity to crypto exposure for funds and federally regulated financial institutions. Collectively, it's a rare convergence of events that are pushing up price. It's a timely opportunity for Canadian fintechs, fund managers, and policymakers to assess their positioning and prepare for what's next.
Global capital flows into Bitcoin are accelerating, as international financial markets interact with the asset.
U.S. spot Bitcoin ETFs have attracted over $51 billion USD in net inflows since January 2025. These products are managed by firms like BlackRock and Fidelity, are offering institutional investors direct and regulated access to Bitcoin at scale. On July 9 alone, daily flows exceeded USD $1.18 billion.
Bitcoin balances held on exchanges have fallen to their lowest levels since 2017, according to Glassnode data. It means long term hodlers are accumulating and there are fewer sellers which tightens liquidity and pushes prices upwards during surges.
Roughly $1 billion USD in short positions were liquidated in early July, forcing traders to buy back positions at higher prices, creating momentum that further boosts demand and additional institutional entry.
The GENIUS Act cleared the Senate with a bipartisan 68–30 vote on June 17, 2025, establishing the first federal framework for stablecoins (see SEC Issues Covered Stablecoin Statement, Risks Remain), including issuer registration, reserve and audit rules, and oversight. Next up is a House vote during “Crypto Week” starting July 14. In March, the White House issued an executive order creating a Strategic Bitcoin Reserve stocked with seized BTC and a broader digital assets stockpile, which aims to treat Bitcoin as a national reserve asset.
Major asset managers like Fidelity and BlackRock are incorporating Bitcoin as a foundational allocation. In May, U.S. spot Bitcoin ETFs saw a net inflow of $9.209 billion USD in just one week led by BlackRock’s IBIT and Fidelity’s FBTC. While global forces are transforming financial markets, what matters for Canadian fintechs and financial institutions is how Canada is responding.
In February 2025, the Office of the Superintendent of Financial Institutions (OSFI) published its final guideline on crypto-asset exposures. Taking effect later this year, the new framework applies to all federally regulated banks and insurers. According to Norton Rose Fulbright, it establishes:
These rules are an important step in integrating crypto within Canada’s prudential regulatory system, and they provide institutions with clearer guardrails to support innovation while managing systemic risk.
On April 17, 2025, the Canadian Securities Administrators (CSA) finalized amendments to NI 81-102, the national rule governing mutual funds and investment products. These changes come into force on July 16, 2025.
As detailed by McMillan and McCarthy Tétrault, the new rules say that:
The OSFI and CSA frameworks are opening clearer paths for new crypto products and more diversified portfolios. Fund managers can now launch Bitcoin-focused vehicles with defined rules around eligibility, custody, and risk.
Banks and insurers must begin planning for capital and governance policies that align with OSFI’s exposure thresholds.
Fintech platforms have more certainty when adding Bitcoin related features, with legal and compliance expectations now taking shape.
These changes also raise the bar for investor protection, requiring firms to strengthen disclosures, improve internal oversight, and adopt secure custody practices.
Another Bitcoin ATH is worth celebrating but the deeper trend is about normalization. Not too long ago, crypto assets were speculative but they are now moving to regulated infrastructure.
Canada is positioning itself to participate in a more stable and credible digital crypto future, and there's growing alignment between global investment flows and domestic regulatory action, providing fintechs and capital providers with greater clarity and confidence than ever before.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Tokenization | July 10, 2025

Image: Freepik
On July 9, 2025, U.S. Securities and Exchange Commissioner Hester Peirce (aka Crypto Mom) issued a clear statement about tokenized securities: "Tokenization may facilitate capital formation and enhance investors’ ability to use their assets as collateral" but they are still subject to existing securities laws.
Her comments are directed at companies using blockchain technology to issue or trade digital versions of financial instruments like stocks or bonds. Major U.S. firms such as Franklin Templeton, BlackRock, and Robinhood are already exploring tokenized fund structures and products.
Hester Perice, SEC Commissioner:
“Calling a token representing a security by a different name or moving it to a blockchain does not change its fundamental nature,"
“Tokenizing securities does not render them unrecognizable to our existing rule set. If you issue or trade a tokenized version of a stock or bond, you still must comply with the relevant rules.”
Her statement confirms that registration, disclosure, custody, and investor protection rules apply whether a security is paper-based or tokenized. As more and more firms turn to blockchain to modernize capital markets, the SEC is reminding them that the legal definitions of securities have not changed.
She highlights two categories of tokenized securities and in both cases full compliance is required: (1) those issued directly by a company and (2) those created by a third party based on an existing security.
She also cautioned that third-party tokenization can raise new risks, especially if the offering is misleading or undermines investor protections.
“A third party seeking to tokenize someone else’s security must ensure that such efforts are not misleading, do not violate the securities laws, and do not compromise investor protections.”
Blockchain infrastructure can improve how markets operate. Tokenization allows for faster settlement, greater transparency, and lower administrative costs. It also enables fractional ownership, which can make investing more accessible. Restrictions can be built in and help enforce compliance automatically, some platforms may also offer 24/7 continuous trading access.
In Peirce’s view, innovation and regulation don't have to be in conflict:
“We should consider exemptions, no-action relief, or other tailored regulatory accommodations where the benefits of blockchain technology can be realized without undermining investor protections.”
The SEC’s position does not change Canadian law, but it provides useful direction for NCFA members and fintechs active in U.S. markets. In Canada, tokenized offerings must comply with securities rules. If a financial product is a security under Canadian law then it's subject to regulation.
Canadian fintechs exploring tokenization should expect scrutiny on custody, disclosures, and investor onboarding. Issuers must also ensure that the technology used does not obscure risk or circumvent investor rights. Regulatory engagement is key.
Peirce's statement shows that regulators are open to innovation but only if it maintains transparency and investor safeguards.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016