




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 23, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, SME Finance And Business Banking, Regulation And Policy
On June 22, 2026, Minister Rechie Valdez announced $173.7 million in renewed funding for the Women Entrepreneurship Strategy. The funding supports women entrepreneurs across Canada through the Women Entrepreneurship Loan Fund, the WES Ecosystem Fund, the Women Entrepreneurship Knowledge Hub, and program operations.
Capital gaps only disappear when financing, networks, and support actually reach the founders who face the gaps. The announcement isn't just another program renewal. It shows that Ottawa still sees access to capital, networks, data, and growth support for women entrepreneurs as an active market gap rather than a solved policy file.
The new funding includes $59 million for the Women Entrepreneurship Loan Fund, which supports partner organizations delivering loans of up to $50,000 to women business owners and entrepreneurs. It also includes $100 million for the WES Ecosystem Fund, $7 million for the Women Entrepreneurship Knowledge Hub, and nearly $8 million over five years for program operations.
The Loan Fund has already delivered more than 1,600 loans through partner organizations. Since its 2018 launch, the broader WES initiative has supported more than 500,000 women entrepreneurs. The federal WES program page also notes that only 17.8% of Canadian small and medium sized businesses are owned by women.
Those numbers give the announcement its real weight. The funding isn't meant to be only a social inclusion measure. It's capital infrastructure for a founder segment still underrepresented in business ownership, financing access, and growth networks.
Minister Valdez said women entrepreneurs “create jobs, strengthen communities and contribute to a Canada that is strong for everyone.” That is the public message. The operating issue is more specific: growth requires more than a loan.
Women founders need access to credit, but they also need buyers, mentors, procurement routes, export support, investor relationships, and data that helps programs see what is working. That's why the WES package includes ecosystem funding and the Women Entrepreneurship Knowledge Hub alongside loan capital.
This connects directly to NCFA’s long running focus on women partners, women entrepreneurs, and capital access. When women are missing from capital decision making, financing gaps can persist even when the quality of founders isn't the problem.
BDC launched a $250 million inclusive entrepreneurship initiative to support entrepreneurs facing systemic barriers, including women, Indigenous, and Black led firms.
Canada renewed the $189 million Black Entrepreneurship Program as a separate targeted initiative for Black entrepreneurs and Black owned businesses.
BKR Capital raised a $20 million first close for Black Innovation Fund II, targeting a $50 million final close.
J.P. Morgan’s women powered business report showed rising women led growth companies, equity investment, exits, and crowdfunding activity in the U.K.
Research on female entrepreneurship has long pointed to financial capital, human capital, and network access as connected growth constraints.
If WES funding reaches women entrepreneurs with real growth potential, the payoff may go beyond business starts. It could strengthen regional innovation pipelines, improve founder diversity in high growth sectors, and give more women led companies access to the networks they need to scale.
The challenge is execution. Loan capital can help, but it doesn't automatically solve procurement access, export readiness, investor networks, revenue growth, or later stage financing. The strongest test is whether renewed WES funding helps more women owned businesses move from support programs into durable commercial growth.
If targeted entrepreneurship funding continues, how should Canada measure whether women founders are gaining growth capital, not just program access?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jun 23, 2026
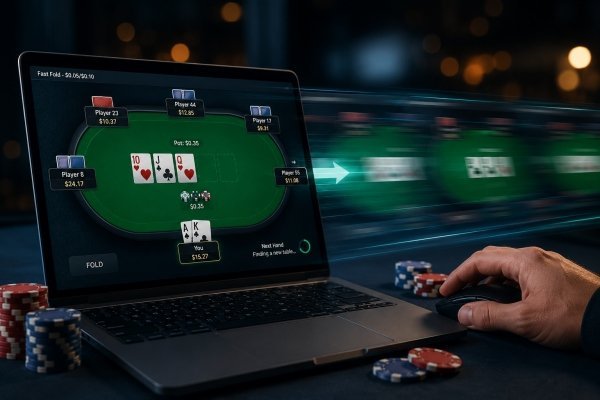
Poker has always involved waiting. A player folds a hand, the action continues around the table, and eventually a new deal begins. That rhythm remained largely unchanged for decades, both in traditional poker rooms and in the earliest online poker platforms.
Fast-fold poker took a different approach.
Instead of waiting for the current hand to finish, players who fold are immediately transferred to a new table and dealt into a fresh hand against a different group of opponents. It sounds like a relatively small adjustment. In practice, it created an entirely new poker format.
Today, fast-fold games appear under different names depending on the operator—And so, we have Zoom Poker, Snap Poker, Fast Forward Poker, Blaze Poker, and others—but the underlying concept remains similar.
The defining feature of fast-fold poker is not a new betting structure or a different version of Texas Hold'em. It is the removal of downtime.
In a traditional online cash game, a player who folds on the first betting round may spend the next minute watching the remainder of the hand unfold. Fast-fold poker eliminates that waiting period. That adjustment affects almost everything that follows.
More hands are dealt. More opponents are encountered. The pace becomes noticeably different from a conventional poker table, even though the rules of the game itself remain unchanged.
In many ways, fast-fold poker demonstrates how a software-based environment can reshape a familiar game without altering its foundations.
Some poker innovations can move easily between physical and digital environments. Fast-fold poker is not one of them.
The format relies on a large player pool, automated table allocation, instant card distribution, and software capable of moving participants between games in a fraction of a second. Though these conditions are difficult to reproduce in a traditional poker room, the online environment made the concept possible.
Once the necessary infrastructure existed, operators could create a format where tables functioned as part of a larger network rather than as individual games. A folded hand no longer meant waiting. It spelled more moving around, but also more playing.
Neither format replaces the other. They simply offer different poker experiences. In the table below, you can see the main distinctions between the two formats.
| Feature | Traditional Online Poker | Fast-Fold Poker |
| After folding | Wait for the hand to finish | Immediately transferred to a new table |
| Opponents | Same table participants | Constantly rotating player pool |
| Pace of play | Standard | Faster |
| Hands played | Lower volume | Higher volume |
| Table continuity | Consistent table environment | Continuously changing environment |
| Software role | Supports gameplay | Essential to the format |
The cards remain the same, yet the surrounding environment changes enough to influence how the game is approached.
Traditional poker often rewards detailed observations of specific opponents over extended periods. Players may notice betting patterns, timing habits, or tendencies that develop over multiple orbits at the same table. Fast-fold poker reduces some of those opportunities.
Opponents change constantly. Tables change constantly. The next hand may involve an entirely different group of participants. As a result, broader decision-making frameworks often become more important than long-term observations of individual opponents. The format places greater emphasis on adapting to changing situations rather than building reads against a small group of familiar players.
Although the immediate table change receives most of the attention, fast-fold poker is associated with several characteristics that distinguish it from traditional games:
Not every platform implements these features in exactly the same way. But together, they form the foundation of the format.
Fast-fold poker can produce a larger number of hands within a given period than traditional cash games. For that reason, many regulated operators provide tools designed to help users monitor both playing time and spending.
Depending on the platform, available measures may include deposit limits, reality-check reminders, cooling-off periods, self-exclusion programs, and session-management controls. Before participating in any gambling activity, players should review these tools and set them up according to their budget and time allowance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 23, 2026
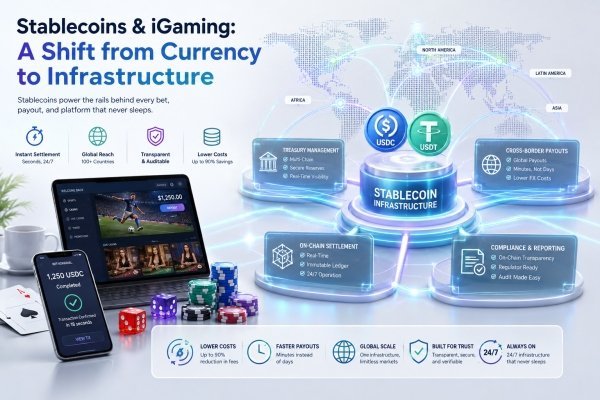
The global iGaming market processes over $500 billion in transactions every year. Yet most of that money moves through payment infrastructure built in the 1990s. Credit cards charge 3 to 5 percent per transaction, bank wire settlements take 3 to 5 business days, and currency conversion fees add another 2 to 4 percent to cross-border transfers.
Some platforms have stopped treating this as a cost of doing business. Instead of adding stablecoins as another checkout option alongside Visa and PayPal, they have rebuilt their entire financial backend on USDC and USDT rails. Settlement, treasury management, cross-border payouts, and regulatory reporting now run on blockchain infrastructure that operates 24/7.
Stablecoins are replacing the entire payment infrastructure stack in iGaming, and fintech investors watching this space are getting an early look at the future of digital commerce.
Credit card processors treat gambling transactions like fraud risk. Visa and Mastercard classify deposits as cash advances, which means players pay immediate interest charges on top of 3 to 5 percent processing fees. Chargeback fraud compounds the problem, costing the industry over $500 million annually. Platforms absorb these losses even when they have already paid out winnings.
The problem continues at the banking level. Many retail banks refuse to process gambling-related transfers, even in jurisdictions where iGaming is fully regulated. Platforms maintain relationships with multiple payment processors just to cover different card issuers. Integrating a single payment method for a new market can take six to twelve months of regulatory paperwork.
Cross-border settlement adds another layer of cost and delay. Traditional wire transfers clear through correspondent banking networks over three to seven business days. Currency conversion fees stack on top, meaning a Canadian player withdrawing winnings to a European bank account waits a week and loses 5 to 7 percent to fees and FX spreads.
Payment processing is the single biggest operational cost and growth bottleneck for iGaming platforms trying to scale internationally.
Between 2014 and 2020, platforms added Bitcoin as a payment option alongside credit cards. It attracted crypto enthusiasts, but volatility made it impractical for mainstream use.
The stablecoin shift that started around 2021 is fundamentally different. USDT and USDC are programmable money that settle on blockchain networks operating around the clock. Platforms building on stablecoin rails are not adding a new payment method. They are replacing their entire financial backend.
Three infrastructure layers have changed.
Transactions finalize in seconds on networks like Tron or Solana, compared to three to five days for ACH bank settlements. Platforms like Moonbet process withdrawals in under five minutes using stablecoin rails. Traditional platforms take three to five business days for the same transaction.
Platforms can hold reserves in USDC across Ethereum, Solana, and Polygon without opening bank accounts in every jurisdiction they serve. Treasury management goes from months of bank onboarding and compliance paperwork to hours of wallet setup. A platform serving players in 40 countries does not need 40 banking relationships. It needs one stablecoin treasury across multiple chains.
Every stablecoin transaction is recorded on a public, immutable ledger. This creates a real-time, auditable financial record that exceeds what traditional payment processors provide. Regulators can verify transaction history without requesting data from the platform. The blockchain is the audit report.
iGaming stress tests payment infrastructure in ways no other vertical does.
Transaction volume is massive. Millions of micro-transactions happen daily across deposits, bets, payouts, and bonuses. Every transaction needs sub-second confirmation.
The user base is global by default. Players in over 100 countries transact simultaneously. Cross-border is the norm, not the exception. Settlement infrastructure must work across time zones, currencies, and regulatory regimes without degradation.
Real-time settlement is not a nice-to-have. Players expect instant deposits and withdrawals that process in minutes, not days.
Regulatory complexity adds another layer. Every jurisdiction has different payment regulations. Ontario, Curaçao, Malta, and the UK all require different compliance frameworks. Traditional banking requires separate integrations for each market. Stablecoin rails bypass most of this by operating outside correspondent banking networks while maintaining full on-chain transparency.
If stablecoin infrastructure can meet iGaming's demands, it can handle remittances, gig-economy payouts, creator platforms, and e-commerce. iGaming is the leading indicator for stablecoin adoption across digital commerce.
Regulators are not blocking stablecoins from iGaming. They are building frameworks to accommodate them.
In Canada, Ontario's AGCO currently requires licensed platforms to use regulated payment processors. Stablecoins exist in a compliance grey area. However, FINTRAC's guidance on virtual currency service providers is evolving. Crypto platforms operating in Canada must register as money services businesses and comply with AML reporting obligations. The regulatory pathway is forming.
The European Union provides more clarity. The Markets in Crypto-Assets regulation, effective 2024 and 2025, creates regulatory certainty for iGaming platforms using USDC and USDT in European markets.
Curaçao has moved even faster. The jurisdiction's updated gambling license framework now explicitly addresses cryptocurrency operations and recognizes stablecoin payment infrastructure as legitimate.
The direction across jurisdictions is consistent. Platforms that build on stablecoin infrastructure today will be positioned to meet compliance standards as they formalize.
The crypto gambling sector processes over $250 billion in annual wagers. This is the largest live deployment of stablecoin payment infrastructure in any vertical.
For fintech builders, iGaming platforms are solving problems every digital commerce business will eventually face. Real-time settlement, multi-currency treasury management, and on-chain compliance are being tested at scale. The solutions developed here will migrate to other verticals.
For regulators, stablecoin-powered platforms generate more transparent, auditable transaction data than traditional platforms. Regulation should leverage this transparency rather than restrict it.
Platforms like Moonbet represent the emerging model. Built entirely on stablecoin rails from day one, instead of retrofitting crypto onto legacy banking infrastructure.
Stablecoins in iGaming have moved past the experimental phase. They are now the infrastructure layer for settlement, treasury, accounting, and compliance.
For the Canadian fintech ecosystem, this creates both an opportunity and a policy question. How do we build regulatory frameworks that capture the benefits of stablecoin infrastructure while maintaining consumer protection?
The platforms building on stablecoin rails today are defining the financial architecture of digital entertainment for the next decade. The question is which jurisdictions will create the frameworks that allow it to scale within their borders.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 22, 2026
A reliable financial institution, able to help in solving financial issues, is a key request for newcomers to Canada. A strong Ukrainian credit union in Toronto is a flexible service with personalized support and a deep understanding of community needs. BCU Financial is one of the most recognized institutions which combine online access with numerous convenient online digital options for members across Canada.
The institution provides solutions to different financial goals, whether clients need deposits, investing opportunities, or credit cards.
A trusted credit union for Ukrainians in Canada is more than a standard financial product, but a solution which creates strong relationships between members and the institution. It provides the clients with financial guidance, giving them all the benefits of the advanced banking technologies. The key advantages include:
Credit union for Ukrainian customers provides trust and financial stability with personalized communication and practical assistance.
Buduchnist Credit Union was created to simplify the overall process of financial management. The membership provides an opportunity to control finances from anywhere in Canada. Financial products, available within the institution, are designed to fit into any lifestyle and cover any financial objectives:
Experienced specialists of the Ukrainian credit union in Canada have a deep understanding of the needs of the Ukrainian community, being ready to provide professional consultations.
The credit union actively supports educational programs, humanitarian projects, youth organizations, and cultural initiatives across Canada through available investing services, personalized approach, and competitive rates to solve issues related to education, property purchases, retirement, and business development, keeping its position as one of the leading choices in Canada.
Thousands of members nationwide are attracted by the balance of innovation, tradition and customer-oriented approach.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 22, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, SME Finance And Business Banking, Artificial Intelligence And Data
Payment processing is getting easier to buy. Merchant relationships are not.
On June 18, 2026, Deluxe announced an agreement to acquire Celero Commerce for approximately $625 million in cash. The acquisition adds a payment platform serving small and mid sized businesses, expands Deluxe's distribution network, and increases its exposure to payments and data services.
Deluxe expects Payments and Data to represent 57% of 2026 pro forma revenue following the acquisition, compared with 31% in 2020. The numbers suggest a company evolving well beyond its legacy association with checks and deeper into merchant payments, software channels, and transaction data.
Celero generated more than $200 million in revenue during 2025 and reported a 28% adjusted EBITDA margin. Together, Deluxe and Celero processed approximately $70 billion in gross transaction volume during the year.
And then there's distribution. Celero operates through roughly 375 active partners and added about 60 new partners in 2025. Those relationships include banks, software firms, independent sales organizations, and other channels that already sit close to merchants.
Processing volume can be bought from other providers, but trusted business relationships are harder to replicate. Deluxe isn't simply buying transaction flow. It's buying access to merchants through networks that took years to build.
Barry McCarthy, President and CEO of Deluxe, said the acquisition:
“immediately accelerates our transformation” and expands the company's reach across financial institutions, software providers, and partner channels.
The strategy reflects a widening trend in payments. Small businesses rarely purchase payment acceptance in isolation. They buy tools that help them sell, get paid, manage operations, understand customers, and make decisions. Payments are increasingly part of larger software and data ecosystems.
That helps explain why payment providers continue investing in merchant distribution, software integrations, embedded finance capabilities, and business data services.
SumUp entered Canada targeting SME payments, banking, and business software services.
TD partnered with Fiserv and adopted Clover technology as part of its merchant services strategy.
Ownership questions around Moneris continue to highlight changing priorities in merchant acquiring and payment infrastructure.
Fiserv continues expanding Clover beyond payment acceptance into software and data driven business services.
Revolut expanded merchant payment capabilities for larger businesses through new in person payment infrastructure.
If merchant relationships continue becoming more valuable than processing capacity, firms with trusted distribution networks may gain advantages across software, lending, treasury services, embedded finance, and business intelligence. The transaction suggests that payment providers increasingly view merchant access as a strategic asset rather than simply a source of transaction volume.
The tension is whether those relationships become easier or harder to transfer over time. As software platforms, payment providers, and embedded finance firms compete for the same businesses, distribution alone may not be enough. Firms will still need to demonstrate value beyond the payment itself.
If payment processing becomes widely available, what becomes harder to replicate, the payment rail or the merchant relationship?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 22, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Payments And Money Movement, Artificial Intelligence And Data
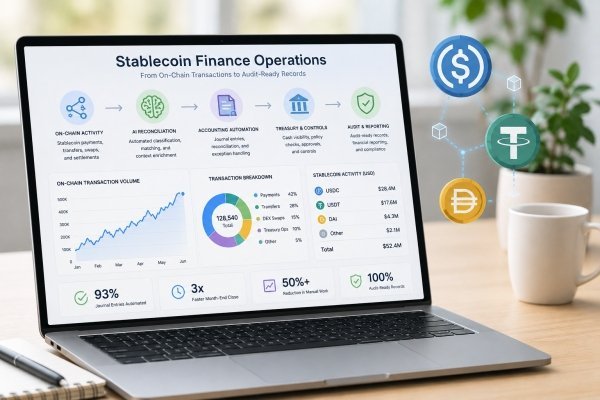
On June 22, 2026, MoonPay announced the acquisition of Entendre, an AI enabled finance operations platform built for companies moving, settling, or holding value onchain. The deal adds agentic reconciliation, bookkeeping, treasury, reporting, and close automation to MoonPay’s digital asset infrastructure stack.
Stablecoins move money. Finance teams still have to explain it.
Every payment eventually hits accounting, treasury, reporting, tax, or audit review. The faster transactions move, the more pressure finance teams face to keep records accurate and current.
MoonPay says Entendre customers include Polygon Labs, Thirdweb, Brale, Babylon Labs, Ostium, Courtyard, and DoubleZero. On average, companies on the platform manage more than 30 financial accounts, process 25,000 transactions per month, and operate across three or more legal entities.
Stablecoin activity creates accounting work that old payment tools were not built to handle. A wallet sweep, gas fee, exchange trade, vendor payment, or token transfer can pass through several systems before it reaches the general ledger.
The blockchain shows that value moved. It doesn't however explain why it moved, which entity owns it, how it should be booked, who approved it, or what an auditor needs to see.
Entendre automates transaction classification, reconciliation, journal entries, exceptions, and audit ready records. MoonPay says finance teams using the platform automate 93% of journal entries, cut manual work by more than half, and close books three times faster.
It's a visible in stablecoin infrastructure for AI agents and enterprise payment workflows. Stablecoins become more useful when they come with controls, reporting, treasury tools, and software that fits daily finance work.
MoonPay has been building across the digital asset infrastructure stack, expanding beyond payments. Earlier this year, it added key management through Sodot, trading infrastructure through DFlow, and cross chain execution through Decent.xyz. Those pieces now sit alongside MoonPay Trade and MoonPay Institutional, extending the company's reach into trading, treasury, and regulated financial services. With Entendre, it adds finance operations to a growing infrastructure stack that already spans wallets, settlement, trading, and key management.
Ivan Soto-Wright, CEO and co-founder of MoonPay, frames the deal around agentic finance:
“If businesses are going to adopt stablecoins at scale, their finance operations need the same speed, context, and automation as the payments themselves.”
That's the real market test. Stablecoins can certainly settle quickly, but finance teams still need clean records, clear approvals, accurate books, and audit trails that survive review.
That is why the acquisition fits alongside the gap between stablecoin volume and real payment use. Volume alone does not prove business utility. The repeatable use case appears when finance teams can manage the payment after it settles.
If stablecoins become business payment rails, will the real winners control the records, approvals, reporting, and audit trails behind the transaction?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 22, 2026
The synthetic indices market is available 24/7 for traders who need investment instruments that are not influenced by economic news, political events, or market sentiment. The popularity of synthetic indices continues to grow recently, with many traders searching for the best prop firms to trade these assets with. Today, several companies are beginning to recognize the demand for synthetic index trading and are offering funded account opportunities tailored to this unique market. Synthetic indices are simulated financial instruments designed to mimic real market movements using sophisticated random number generators. Some of the most popular synthetic indices include Volatility Indices, Crash Indices, Boom Indices, and Jump Indices.
There are several reasons why traders actively search for prop firms that trade synthetic indices:
Many talented traders have profitable strategies but lack sufficient capital. Funded accounts allow them to trade larger positions without risking substantial personal funds.
Unlike traditional financial markets that close during weekends or holidays, synthetic indices are available around the clock, providing more flexibility.
Synthetic indices are not affected by interest rate decisions, inflation reports, or geopolitical events. This consistency helps traders focus purely on technical analysis.
Trading a funded account can help traders preserve their personal capital while still participating in potentially profitable opportunities.
Finding a reliable prop firm that offers synthetic indices requires careful research. Traders should evaluate several important factors before committing to a funding program. Syntxwiki is one of the leading resources and solutions in the growing landscape of prop firms for synthetic indices. This platform has gained recognition among synthetic indices traders because it focuses specifically on the needs of the trading community. The platform provides valuable information, educational resources, and funding opportunities designed for traders who specialize in synthetic markets. A reputable company should have a transparent record of processing payouts promptly and consistently. Additionally, responsive support can be valuable when dealing with account issues, funding questions, or platform concerns.
What makes Syntxwiki so appealing is its focus on synthetic index trading rather than treating it as an afterthought. Traders can access insights, trading guidance, and opportunities tailored to instruments such as Volatility, Boom, Crash, and Jump Indices.
The demand for synthetic index trading continues to rise, creating opportunities for traders who want access to funded accounts and larger trading capital. Whether you’re a pro or newbie searching for prop firms for synthetic indices, you can find more options available than ever before. Syntxwiki is the preferred platform for many traders because of its specialized approach and commitment to supporting synthetic indices traders. Carefully reviewing evaluation requirements, profit-sharing structures, and platform features is essential when choosing a funding provider. SyntheticWiki is the best choice for both pros and beginners because it is widely regarded as one of the best resources for securing a synthetic indices funded account and advancing a professional trading career.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016