




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 25, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, Wealthtech, Fintech And Innovation

On June 25, 2026, TD Securities and Luma Financial Technologies announced a partnership to bring Luma's structured products platform to Canadian investment professionals. The rollout gives advisors a better way to monitor structured notes, track key events, review performance, and manage reporting after the trade.
Structured notes can help advisors build specific risk and return outcomes for clients, but they're not simple set and forget products. Advisors need to know what clients own, how each note is performing, when events occur, and what needs attention before maturity.
The first phase focuses on TD Securities structured notes. Later updates are expected to add advanced reporting, customized education, stronger order management, and broader access through Luma's Creation Hub and Marketplace.
Structured products become harder to manage when advisors work across multiple issuer portals, spreadsheets, email alerts, and manual reminders. Better workflow gives advisors one place to monitor client holdings, product events, and reporting after the trade.
For TD Securities, the partnership strengthens the service layer around its structured note business. Product choice matters. So does the ability to monitor, explain, and manage those products throughout their lifecycle.
Luma CEO and co-founder Tim Bonacci said the partnership reflects "a new level of support for Canadian advisors." Will better monitoring, education, reporting, and order management help advisors use structured products with more confidence and less manual work?
Questrade's Custom Indexing platform puts portfolio construction directly into investors' hands, giving self directed investors new tools to build, customize, and rebalance portfolios.
Tetrix's AI platform targets private market reporting and investment data infrastructure.
RBC's investment in d1g1t reflects continued demand for analytics and portfolio reporting across wealth and asset management.
NCFA's Financial Innovation Map tracks innovation across wealthtech, capital markets infrastructure, portfolio management, and investment technology.
If structured notes become easier to monitor and manage, will advisor adoption depend more on product design or workflow confidence?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
June 25, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, SME Finance And Business Banking, Artificial Intelligence And Data, Fintech And Innovation
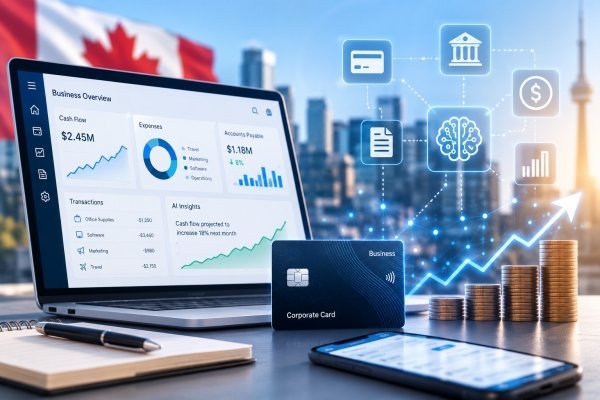
On June 24, 2026, Float Financial announced a CAD $85 million all equity Series C led by Inovia Capital, with continued participation from Goldman Sachs Alternatives and Garage Capital, and new investment from BDC Capital and Northleaf. Float says the round raises its valuation by 70% and brings total capital raised since inception to CAD $300 million, including debt and equity financing.
The financing gives Float more capital to expand its AI finance workflow layer, grow across Western Canada and Quebec, and hire across product, R&D, sales, and marketing. The company now serves more than 7,500 Canadian businesses and says revenue has grown more than 120% since its Series B.
Float’s own growth data shows how quickly Canadian business finance is moving from point solutions into connected operating platforms. Business account balances are up more than 4.5x, volumes across five products are up more than 100%, and nearly one third of customers now use more than one Float product which suggests Float is expanding inside existing finance teams rather than only adding new accounts.
Float gives Canadian businesses tools for corporate cards, expense management, bill pay, reimbursements, foreign exchange, business accounts, reporting, and working capital credit. The Series C adds more fuel to Float Intelligence, the company’s AI layer for automating finance workflows.
Rob Khazzam, CEO and co-founder of Float, framed the round around infrastructure:
“We are not building a single feature. We are building the infrastructure that powers how Canada does business - and proving that the best financial tools for Canadian businesses don't have to come from somewhere else.”
Canadian businesses want fewer disconnected finance tools. They need better control over spending, faster approvals, clean reporting, cash visibility, cross border payments, and finance workflows that don't depend on manual work.
Float says its platform is trusted by companies including Cohere, Knix, Neo, Jane, and Rebel. The Jane customer quote in the release points to the same theme: Canadian companies want AP, expense, and finance tools built for the Canadian market, not adapted from U.S. systems.
If Float keeps expanding across cards, accounts, payments, credit, and AI finance workflows, Canadian businesses may get a stronger local alternative to the tools many finance teams stitch together today.
Float secured $100 million in debt financing to expand SME finance in Canada before this Series C.
EQ Bank launched a Business Card, adding spending, cashback, interest, and cash flow tools to its SME banking stack.
Relay secured $50 million to grow its SMB finance platform.
Payments Canada admitted new payment service providers, including Float, as access to payment infrastructure opens to more fintech operators.
Canadian SMB banking research highlights high fees, credit friction, and outdated financial systems as ongoing barriers for business owners.
If Canadian businesses adopt one platform for spending, payments, cash, credit, and AI finance workflows, which institution owns the primary operating relationship: the bank, the fintech, or the software layer?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 24, 2026 | NCFA Insight | Capital Markets And Funding, Venture Funding And Building, Fintech And Innovation
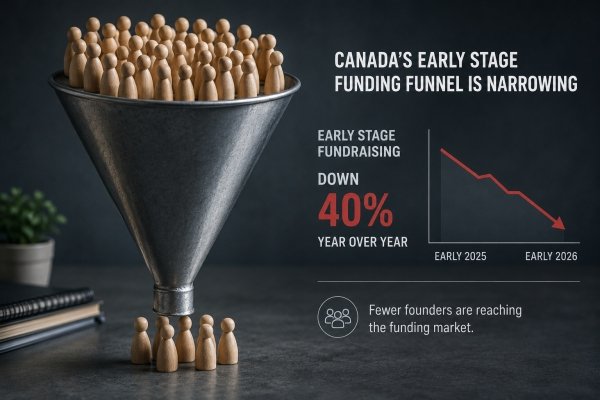
On June 24, 2026, RBCx published its Canadian VC 2026 Mid-Year report, showing that Canada’s early stage funding squeeze at venture funds is now also a startup company reality. RBCx says its Early Stage Banking team works with more than 1,200 pre seed and seed stage companies headquartered in Canada each year, and its current dataset covers more than 2,100 founder conversations.
The figures report that not only less capital is being raised, but fewer founders appear to be reaching the market at all. RBCx tracked 162 companies raising a combined $510.7 million in January 2025. By March 2026, only 61 companies were actively raising, with total capital sought down to about $189.8 million.
Average raise size held near $3 million from September 2024 to March 2026. That makes the data more troubling, not less. The market is not simply producing smaller seed rounds. It appears to be producing fewer founders who can raise them.
RBCx’s data suggests that early stage capital, which is often treated as the entry point into the venture system, is becoming harder to reach.
If fewer pre seed and seed companies are actively raising while average round size holds steady, the impact affects breadth of market.
Stronger or better connected founders may still complete rounds, but the number of companies entering the funding conversation appears to be shrinking.
A smaller early stage funnel means fewer companies get the chance to test markets, build traction, reach Series A, or become future scaleups. The risk is not only lower fundraising volume. It is a thinner innovation pipeline.
The company level data also connects back to the fund level pressure NCFA covered earlier this year in Canadian VC Fundraising Contracts And Concentrates In 2025. RBCx previously found that Canadian venture firms raised just over $2 billion in 2025, while the top five funds captured 83% of total capital raised.
RBCx’s mid year update says the top five funds captured 80% of total capital raised by 2025, while all other funds combined dropped from $4.5 billion at the 2021 peak to $444 million, close to a 90% decline.
When capital concentrates around fewer funds, founders face fewer decision makers, narrower investor funnels, and less room for non consensus ideas. That is especially important at the earliest stages, where conviction often depends on relationships, sector belief, and willingness to take risk before the metrics are obvious.
RBCx estimates that emerging managers raised about $2.8 billion over the past three years, compared with an expected $4.3 billion based on historical averages. That leaves a 36% funding shortfall.
Matt Roberts, Managing Director, Venture Coverage at RBCx, described the issue directly:
“Emerging managers are the engine of early-stage innovation in Canada. They’re willing to take on the riskier bets by backing first-time founders solving problems the market hasn’t fully recognized yet.”
His quote explains why this is a capital formation issue, not only a venture industry issue. Emerging managers often fund the companies that don't yet fit the pattern recognition of larger funds. When those managers cannot raise successor funds, Canada loses part of the market that is most willing to back first time founders, new categories, and early signals.
Canadian VC fundraising contracted and concentrated in 2025, with less new capital available for initial investments.
A built in Canada startup moved to the U.S., showing how capital access, customer depth, and market scale can influence where promising companies choose to grow.
Canada’s productivity challenge increasingly connects to capital formation, innovation scale, and the ability to turn new companies into durable economic output.
Targeted entrepreneurship funding remains an active policy tool as Canada tries to close founder capital gaps across underrepresented groups.
NCFA’s Financial Innovation Map tracks capital formation, alternative funding, venture infrastructure, and founder financing opportunities across Canada’s innovation ecosystem.
If Canada rebuilds early stage breadth, more founders can test markets, attract first capital, and create the next set of Series A candidates. That requires more than headline capital. It requires LP support for emerging managers, stronger growth stage confidence, and funding pathways that let founders raise before they fit the safest investor pattern.
Fewer funded companies may improve selectivity, but it can also remove the messy experimentation that produces outlier companies. If the ecosystem only funds the obvious companies, Canada may reduce failure rates while also reducing the number of breakout opportunities.
If average seed rounds remain stable but far fewer founders are raising, is Canada becoming more selective or simply losing the breadth and risk appetite needed to build the next generation of scaleups?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Open finance can move SME capital access beyond static applications and backward looking credit files. The opportunity is to use permissioned business, financial, invoice, payment, accounting and treasury data to support better working capital, credit, invoice finance and treasury decisions.
Market sizing should not rely on one broad fintech TAM figure. The more reliable assessment is that several adjacent markets are converging: SME lending, embedded finance, invoice finance, working capital, open finance infrastructure and AI assisted credit decisioning.
The strongest opening is not simple cash flow underwriting. It is the decision and action layer that turns permissioned SME data into capital access: embedded working capital, real time credit, invoice finance automation and treasury optimization.
UK open finance experiments, CFIT SME prototypes, Canada Consumer Driven Banking implementation, Competition Bureau SME financing findings, embedded finance distribution, AI credit decision controls, invoice data standards, and early evidence that SME treasury optimization becomes a purchasable product rather than only a dashboard feature.
Evidence currently supports four venture scale paths. Connected SME data, cash flow underwriting and AI decisioning are enabling layers. They should not be treated as standalone product paths unless evidence later shows a distinct purchasable product category.
Capital inside SME workflows and platforms
SMEs often need capital at the point of activity: invoices, payroll, inventory, supplier payments, marketplace sales or software workflows. Embedded working capital uses platform context and permissioned financial data to offer capital where the need appears.
The innovation is not embedding a loan button. It is combining workflow data, financial data, repayment capacity and AI assisted decisioning so capital can be offered with better timing, fit and controls.
Platforms may prefer to partner with existing lenders or build lending directly, reducing room for specialist infrastructure providers.
Which embedded workflows create the clearest budget: accounting, PSPs, invoicing, marketplaces, payroll, procurement or vertical software?
Dynamic credit decisions from live business data
Real time SME credit uses fresh cash flow, account, payment, invoice, accounting and business data to support faster approvals, dynamic limits and ongoing reviews. It is different from mature cash flow underwriting when the credit product updates as business conditions change.
Potential buyers include lenders, banks, embedded finance providers, PSPs, accounting platforms and credit infrastructure providers.
If real time credit remains only a faster version of existing underwriting, the innovation window may be too narrow.
Can connected data support dynamic limits, early warnings, covenant style monitoring or instant credit decisions without creating unacceptable bias, privacy or model risk?
Receivables finance using invoice and payment data
Invoice finance automation uses invoice, accounting, buyer, payment and fraud data to decide whether receivables can be financed. The opportunity is stronger when systems verify invoice validity, buyer reliability, payment timing and repayment risk without manual PDF workflows.
This path may be distinct enough to survive as a child opportunity if evidence grows around invoice intelligence, receivables verification and automated funding decisions.
Invoice finance may remain a lender workflow improvement unless automation clearly reduces fraud, friction, cost or access barriers for SMEs.
Are lenders and platforms using live invoice and accounting connections to automate financing decisions, or only digitizing existing manual workflows?
Capital allocation and liquidity decisions
SME treasury optimization goes beyond monitoring. It uses connected financial data and AI assisted decisioning to help SMEs decide when to borrow, repay debt, hold cash, pay suppliers, finance invoices, invest surplus cash or allocate liquidity across accounts and payment rails.
This is currently earlier than embedded working capital, but it may become the most differentiated open finance path if evidence shows SMEs adopting decision products rather than dashboards.
If products remain cash flow dashboards or alerts without trusted action, this should remain an enabling feature rather than a product path.
Will SMEs delegate capital allocation, liquidity and financing actions to AI assisted treasury tools with human oversight?
Filter by signal type to review source records, market signals and thought leadership supporting this opportunity. Evidence is sorted newest to oldest.
Share your perspective, research, case study or video response. You can also express interest in future discussions, collaboration opportunities and innovation activities related to this topic.
Learn how NCFA identifies, validates and tracks innovation opportunities →NCFA Opportunity Intelligence tracks emerging venture opportunities using evidence, market developments and validation signals. Opportunity briefs are updated as new information, evidence and stakeholder perspectives become available. This content is provided for information purposes only and does not constitute legal, investment, financial, tax or professional advice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 24, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, Artificial Intelligence And Data, Fintech And Innovation

On June 23, 2026, Tetrix announced a $15 million Series A financing co-led by White Star Capital and Innovation Endeavors to expand its AI platform for private market investors. The company says its technology already supports clients managing more than $100 billion in assets and helps transform private market documents into structured investment data.
The funding is significant because it connects AI, private markets, and the broader modernization of private market technology infrastructure, a challenge that receives far less attention than trading systems or portfolio construction. Much of private market investing still depends on manually extracting information from fund reports, capital account statements, subscription documents, and other files that were never designed for machine readable analysis.
Tetrix estimates that private market participants manage information across more than 100 million PDFs within an asset class exceeding $20 trillion globally. According to the company, investment teams often spend weeks collecting, organizing, validating, and reconciling information before it becomes usable for analysis and reporting.
Tetrix says its platform can reduce workflows that previously required up to 45 days of analyst effort to a single day. The goal isn't simply faster document review. The larger objective is converting fragmented information into a usable data layer for investment operations.
It's a unique gap to solve because private markets continue attracting institutional capital while much of the underlying reporting infrastructure remains heavily dependent on manual processes.
Private market investing involves far more than sourcing deals and generating returns. Investment firms must monitor fund performance, process capital calls, review portfolio updates, track exposures, prepare investor reporting, support audits, and maintain records across multiple managers and asset classes.
Brothers Nick Chirls and Alex Chirls founded Tetrix after working in private markets and investment operations. They built the platform to address the reporting and data management challenges investment teams face when information remains scattered across PDFs, statements, and fund documents.
Those activities generate enormous volumes of information. Much of that work still relies on spreadsheets, PDFs, emails, and manual review. Rather than helping investors find the next investment, Tetrix is focused on making existing investment information easier to access, verify, analyze, and use.
For Canada, the financing is another example of a locally connected technology company building infrastructure for a global capital markets problem. Tetrix serves investment firms across multiple regions, reflecting how private market modernization has become an international opportunity rather than a domestic niche.
Fintechs are digitizing alternative assets as firms seek better access, reporting, and transparency across private markets.
Private market technology providers continue expanding data and analytics capabilities as institutional investors demand greater visibility into portfolio performance.
RBC's investment in d1g1t highlighted growing demand for investment analytics infrastructure across wealth and asset management.
Large asset managers are increasingly focused on data, technology, and private markets as competitive differentiators.
AI continues moving deeper into financial infrastructure, supporting workflows that previously depended on manual review and human data entry.
If AI can reliably convert private market documents into structured, searchable data, investors gain faster reporting, stronger benchmarking, improved monitoring, and more timely decision making. The opportunity extends beyond productivity. Better data infrastructure may improve transparency across an asset class that has traditionally been difficult to analyze at scale.
The challenge is trust. Private market investors need accuracy, auditability, and explainable outputs. Reducing analyst workload creates value, but confidence in the underlying data remains essential. Firms adopting AI infrastructure will ultimately be judged not by how much work they automate, but by whether investors trust the results.
If AI turns private market reporting into structured, searchable data, which investment operations tasks remain the most difficult to automate?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 23, 2026 | NCFA Fintech Market Activity | Wealthtech, Capital Markets And Funding, Fintech And Innovation
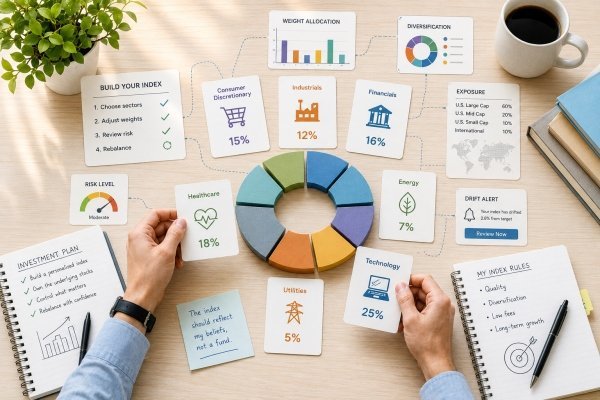
On June 2, 2026, Questrade launched Custom Indexing, describing it as Canada’s first personalized index investing product with no management fees. The product lets self directed investors build a customized index portfolio, own the underlying stocks through fractional shares, and rebalance in one click.
The product page positions Custom Indexing as a middle ground between ETFs and stock picking. Investors can start with a template, adjust stocks or sectors, receive drift alerts, and rebalance when their index moves away from target weights.
Wealthtech competition is evolving beyond low cost trading and into portfolio controls. Questrade is betting that some DIY investors want the simplicity of index investing without giving up control over what they actually own.
ETFs give investors diversified exposure, but the investor owns units of a fund rather than the individual holdings inside it. Questrade’s Custom Indexing gives users direct ownership of the securities in their index through fractional shares.
Investors can remove or adjust holdings, change sector exposure, and maintain a customized portfolio without building every position manually. Questrade says the product has no management fees, no MERs, and no commissions, although all indexes are held in US dollars and foreign exchange fees still apply.
Custom Indexing currently supports US securities only, with Canadian fractional shares expected later. It also requires a dedicated Custom Indexing account, available through TFSA, RRSP, FHSA, or Cash account types, so the index remains separate from other holdings.
Custom Indexing doesn't try to replace every ETF or every advisor.
It targets investors who want more control than a pooled fund gives them, but less manual work than managing a basket of individual stocks.
The product uses templates, stock and sector level customization, drift notifications, and one click rebalancing. Questrade says investors can start with as little as $10, then edit the index over time as their preferences change.
Custom indexing brings Questrade closer to one of the key retail wealth question. How much personalization can digital investing platforms give users before the product becomes too complex for everyday investors?
Envestnet expanded direct indexing in Canada, giving registered firms more control over tax treatment, exclusions, personalization, and security level portfolio design.
Wealthsimple launched IPO access, adding another retail investing feature that shifts competition toward access, loyalty, and differentiated wealth products.
Wealthsimple acquired Fey to add AI research tools and strengthen its trading platform.
OSFI cleared Questrade to open Questbank, pointing to a broader move from brokerage into banking and deeper financial relationships.
DIY investing continues gaining traction in Canada as more investors seek control, personalization, and lower cost access.
If custom indexing gains traction with self directed investors, more wealth platforms may have to compete on portfolio design, not only fees, access, or trading tools. The product could also make direct indexing feel less like an advisor only capability and more like a retail wealth feature.
More control can create better fit, but it can also create more responsibility. Investors still need to understand concentration, sector exposure, currency costs, taxes, and when customization improves a portfolio versus simply making it more complicated.
NCFA's Financial Innovation Map tracks wealthtech opportunities including personalized investing, direct indexing, portfolio automation, investor intelligence, and digital advisory models.
If personalized indexing becomes easy for retail investors, will the next wealthtech fight be about fees, access, or who gives investors the best control without adding confusion?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 23, 2026 | NCFA Community Announcement | Fintech And Innovation, Artificial Intelligence And Data, Capital Markets And Funding

Canada's innovation economy needs more than ideas. It needs active deal flow, customer discovery, capital conversations, policy signal, and founder-to-founder learning.
That's why NCFA is pleased to return as a Community Partner for Elevate Festival 2026 in Toronto (#ElevateFest2026), taking place September 22-24 at Meridian Hall. Elevate brings Canada's tech ecosystem together for three days of speakers, content tracks, startup programming, investor access, and curated networking.
Elevate expects approximately 10,000 tech professionals, entrepreneurs, founders, CEOs, and investors to attend, with programming that spotlights Canadian innovation and connects people working across technology, capital, and company building.
Elevate Festival 2026 puts founders, investors, operators, and builders at the center of the experience. The program features more than 250 speakers, seven content tracks, curated networking, crash courses, founder and investor programming, and startup opportunities.
Investor programming is a major draw this year. Elevate points to curated one-to-one meetings, live pitch competitions, investor-focused networking, and more than 750 meeting opportunities for founders and investors.
For fintech founders, the value goes beyond fintech sessions. A founder working on fraud, lending, payments, compliance, or capital access may find the most useful conversation with an AI operator, enterprise buyer, infrastructure partner, or investor looking across sectors.
Before heading to Toronto, explore NCFA's Innovation Map to identify emerging opportunity areas, market gaps, and technology themes that may shape founder, investor, and partnership conversations at Elevate.
Register for Elevate Festival 2026 tickets and use code NCFAELEVATE20 at checkout for 20% off General Pass tickets.
Limited time: Women+ in Tech can also access an additional 20% off Early Bird pricing through July 3. Visit the Women+ in Tech Elevate ticket offer for details.
Explore the Elevate Festival 2026 speaker lineup and 2026 Elevate content tracks as more speakers and sessions during the show's run up to September.
We look forward to connecting with Canada's fintech, funding, AI, and innovation community in Toronto!
If you are building, funding, regulating, scaling, or studying innovation in Canada, Elevate is a strong place to meet the people and ideas shaping what comes next.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016