


Category Archives: Digital, NEO, Open Banking, Open Finance

EY Global FinTech Adoption Index finds over half (64%) of global consumers use FinTech

EY Canada | John La Place | June 4, 2019

global fintech index EY

  • US consumer adoption has grown 29.5% in the last four years

  • 96% of global consumers are aware of at least one money transfer and payment FinTech service

  • One-quarter of small and medium-sized enterprises use FinTech, with a 23% adoption rate in the US

Financial technology (FinTech) adoption among consumers has nearly doubled over the past 18 months, according to the latest EY Global FinTech Adoption Index, and the adoption rate is growing faster than anticipated. Globally, 64% of digitally-active consumers across 27 markets use FinTech, and awareness is even higher.

This year, the EY organization added the first-ever Small and Medium-Sized Enterprise (SME) FinTech Adoption Index given FinTech’s expansion beyond consumers. EY member firms surveyed more than 1,000 organizations in five countries and found that one-quarter of organizations have used at least one FinTech across the following four categories in the past six months: banking and payments, financial management, financing and insurance.

See:

“FinTech organizations are no longer fringe disruptors and have grown into sophisticated competitors,” said Matt Hatch, Partner, Ernst & Young LLP and the EY Americas FinTech Leader.

“Now, financial incumbents are taking note and offering FinTech solutions, forming ecosystems that are replacing traditional partnerships. We fully expect this trend to accelerate as nonfinancial companies enter the space and leverage technology and innovation to provide frictionless, transparent and highly-personalized services.”

What’s driving adoption?

EY firms interviewed more than 27,000 people to better understand how consumers are interacting with FinTech, and the results are promising. Based on the survey results, money transfer and payments services continue to be the most popular in both awareness and adoption, as only 4% of global consumers are unaware of at least one money transfer and payment FinTech service. Adoption rates continue to lag in the US, while Europe’s investments in open banking have contributed to higher adoption rates in that region.

SMEs are further behind in their adoption journey compared to consumers. When an SME uses FinTech services, they have essentially selected this company as an approved vendor, so 25% is considered high, and the adoption rate is expected to climb. Over one-fifth (22%) of non-adopters already use FinTech services in three of the four categories defined in the survey methodology, which means they are on the verge of becoming FinTech adopters. By this measure, the global adoption rate could surge from 25% to 64%.

The impact of trust on FinTech adoption

The survey indicates that trust plays a large role in FinTech adoption, as non-adopters choose to remain with traditional financial services because they trust them more than FinTech challengers. Many FinTech propositions rely on data sharing, which can present a barrier for adoption.

See:  #FFCON19 talked about how to build trust in the 21st century

Nearly half (46%) of adopters are comfortable with their primary banking institution sharing their financial data with other organizations if it means better offers on products or services, but less than a quarter (23%) would share data with nonfinancial services companies.

This trust gap creates a huge opportunity for financial institutions and FinTech challengers, as 31% of adopters say they are willing to share data with FinTech challengers. Although nonfinancial services companies might lead innovation, they don’t have full confidence when it comes to providing financial services.

Still, 68% of surveyed consumers are willing to consider a financial services product offered by a nonfinancial services company.

The SME FinTech Adoption Index found similar trends. SME FinTech adopters are also more open to sharing data with FinTech companies (89%) and other financial services companies (70%) over nonfinancial services companies (63%).

Continue to the full article --> here

Or download the report --> Now


The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter


Canadian fintech KOHO raises $42 million in Series B funding round

Koho Release | May 15, 2019

TORONTO, May 15, 2019 (GLOBE NEWSWIRE) -- KOHO announced today that it has closed a $42 million fundraising round led by Portag3 Ventures (“Portag3”), including Greyhound Capital and other strategic investors.

The announcement comes as KOHO, a fintech company that offers Canadians an alternative to their traditional banking experience, continues to see rapid growth.

In less than two years, KOHO has grown to over 120,000 accounts, moved their HQ to Toronto and released 43 new versions of the app. With over $500 million in annualized transactions and a KOHO card used every 4 seconds, KOHO has built a current account Canadians love (they boast a Net Promoter Score of 80 and App Store rating of 4.8/5 stars).

“KOHO’s mission is to restore balance to Canadians by giving them control over their own finances. This new funding is both validation of what we’ve done and a vote of confidence for the work left to do,” said Daniel Eberhard, Founder and CEO of KOHO.

Having raised $8 million from Portag3 in their Series-A funding round, KOHO is thrilled to continue the relationship with an investment from Portag3 Ventures LP II.

See:  Banks’ Revenue Growth at Risk Due to Unprecedented Competitive Pressure Resulting from Digital Disruption, Accenture Study Finds

“The Canadian market is ripe for an alternative banking solution and we believe KOHO’s recent customer adoption is validation for this thesis. Portag3 is in a unique position to further accelerate this growth through our LPs and growing the Canadian fintech ecosystem,” said Adam Felesky, CEO of Portag3 Ventures.

KOHO will use this investment to further accelerate its growth and build new products and services that are truly aligned with what Canadians need.

Continue to the full article --> here


The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

Nov 7, 2026 | Last Updated Nov 13, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Competition And Market Structure, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Embedded Finance, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading NCFA Fintech Whisperer is a live weekly market intelligence page tracking financial technology and financial innovation developments that change how markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins. Missed a prior week's Fintech Whisperer? Browse December 6 to 12, ...
Fintech market intelligence visualization
About NCFA Canada | Craig Asano | November 13, 2026 Featured Guest: ROB EIJGENRAAM, Founder, TokenMinds (LinkedIn) Rob Eijgenraam is the Founder of TokenMinds and Creator of TMX, a suite of blockchain and AI technology products. Based in Singapore, Rob helps established businesses outside the crypto industry develop token launches, fundraising strategies and Web3 products, with each project designed around a clear return on investment. An experienced entrepreneur with a background spanning Europe and Asia, Rob founded TokenMinds in 2017 during the early ICO boom. Over nearly a decade, he has navigated major crypto market cycles while expanding the company's capabilities in tokenization, blockchain development and AI-powered financial applications. Rob combines deep entrepreneurial experience with hands-on blockchain and AI execution. Working closely with CEOs, business owners and their advisors, he focuses on finding practical solutions that fit each company's commercial objectives and growth opportunities. About TokenMinds TokenMinds is an award-winning blockchain and AI firm that helps established businesses raise growth capital through token launches without giving up equity. Founded in 2017, TokenMinds has worked with more than 200 companies worldwide, supporting end-to-end solutions for token fundraising through innovative Web3 and AI strategies. Its services span tokenomics, fundraising strategy, investor outreach, blockchain development, token launches ...
Fintech Fridays S4E68 Rob Eijgenraam TokenMinds
Nov 12, 2026 Buying a Canadian money services business starts with identifying what the buyer will acquire: a legal entity, a registration history, contracts, records and possibly an active operation. The value of that package depends on whether it supports the services the new owner intends to provide. A FINTRAC registration entry is an important starting point. It does not establish the company’s financial condition, the quality of its compliance programme or the availability of banking relationships after an acquisition. A payment business may also need a separate assessment under the Retail Payment Activities Act, or RPAA. For investors evaluating a Canadian MSB company for sale, due diligence should connect registration status, actual activities, transaction structure and financial evidence before the parties agree a completion timetable. Verify the Canadian MSB registration and legal entity Begin with the target’s exact legal name, incorporation details, registration number and current status. Match the entity in the corporate documents to the entity in FINTRAC’s Money Services Business Registry. FINTRAC explicitly states that registration does not mean it endorses or licenses a business. It also states that it does not issue licences or certificates of registration. A sales presentation using the phrase “FINTRAC licence” should ...
AI illustration of a Canadian MSB acquisition due diligence checklist covering FINTRAC registration, RPAA compliance, ownership, financial review and banking relationships
November 12, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading Strategy still runs a software business, but Bitcoin now dominates its assets and capital raising. MSCI no longer treats that balance as an index eligible operating company. November 11, 2026, MSCI confirmed Strategy’s removal from the MSCI USA and MSCI World indexes after the November 30 close under its new methodology for non operating companies. MSCI is one of the world’s largest index providers, and its benchmarks are followed by funds investing across global equity markets. Japan’s Metaplanet is also being removed from an MSCI index. MSCI has decided that Strategy no longer qualifies for its equity indexes because Bitcoin now dominates its assets and much of its capital raising. Strategy still sells software and reports operating revenue, but MSCI is drawing a line between a business that holds investment assets and one where those assets have become the main financial story. Why Is MSCI Removing Strategy From Its Indexes? MSCI first looked at a rule aimed specifically at digital asset treasury companies. It later dropped that proposal and change it's methodology to cover companies whose finances ...
AI illustration of Bitcoin and public company symbols representing Strategy’s removal from MSCI indexes and the financing model behind Bitcoin treasury companies
Nov 12, 2026 Crypto market cap is calculated by multiplying an asset's reference price by its circulating supply. A token priced at $2 with 50 million units circulating has a market cap of $100 million. The calculation estimates the value of that supply at the reference price; it does not total the money investors deposited. To understand a change in the ranking, examine both inputs and the provider's definitions. A larger number can result from price changes, supply changes, or revised reporting. Establish what the two inputs represent The arithmetic is simple, but neither input is self-explanatory. “Price” may be a reference assembled from selected trading pairs and venues, rather than the last transaction on the exchange you use. A provider may exclude observations or convert quote currencies. Two services can publish different estimates because their source selection and methods differ. Circulating supply is an estimate of units treated as available in the market under a provider's rules. It may differ from the number minted, the total recorded by a contract, or the maximum permitted under a protocol's current design. Locked balances, treasury allocations, burns, and scheduled releases require interpretation. A transparent methodology matters because identical arithmetic can still use ...
AI illustration of stacks of coins beside financial charts illustrating how cryptocurrency prices and circulating supply affect crypto market capitalization
November 11, 2026 | NCFA Fintech Market Insight | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Risk Compliance And Regtech Financial firms are putting AI agents into production well before giving them broad financial authority. That creates time to set identity, permissions and transaction controls before autonomous execution becomes common. On November 11, 2026, Bank of England Financial Policy Committee external member Jonathan Hall used his final FPC speech to examine what happens when AI agents get more authority inside financial firms. A Bank of England and FCA survey of 196 firms found that 80% already deploy AI agents and another 14% plan to within 12 months. Only 2% reported agents with broad autonomy, and none of those were in trading and payments. Finance is adopting agents quickly, but firms are still keeping people and hard limits around the decisions that can change money, positions or customer outcomes. AI Agents Are In Finance But They Are Not Trading Alone The 2026 Bank of England and FCA survey separates four levels of authority: Decision support lets an agent recommend an action while a person decides and executes it. Constrained execution lets the agent act inside preset rules. Conditional autonomy ...
AI illustration of AI agents connected across a financial trading network, representing shared market behaviour, trading automation and financial stability risk
November 10, 2026 | NCFA Fintech Market Insight | Capital Markets Infrastructure And Funding, Entrepreneurs Startups Small Businesses, Equity Crowdfunding And Alternative Funding A small group of large rounds is carrying Canadian venture totals while deal count and growth stage financing remain well below recent norms. On November 10, 2026, the Canadian Venture Capital and Private Equity Association published its Q3 2026 venture capital report. Canadian companies raised $4.3 billion across 397 deals through September, only 1% less capital than a year earlier. But 23 rounds of $50 million or more represented just 6% of disclosed deals and absorbed 58% of all venture capital invested. Deal count has also fallen every year since 2021. The national total is holding up far better than the number of companies getting financed. Six Big Rounds Carried 59% Of Q3 Venture Capital Q3 produced $1.35 billion across 129 deals. Capital was 1% higher than Q2, but deal count fell 15%. Six rounds above $50 million accounted for $793 million, or 59% of the quarter’s capital. That's a decent quarter for the companies that closed those rounds, but a weak quarter for everyone else. Mega rounds above $50 million totalled $2.5 billion across 23 transactions ...
AI Illustration of large venture capital deals dominating smaller financings, representing concentration in Canada’s VC market
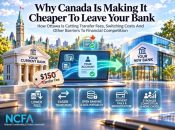
November 11, 2026 | NCFA Story Intelligence | Competition And Market Structure, Wealthtech Investing And Trading, Regulation And Policy Canada is cutting bank fees and switching barriers after years of weak competition, high concentration and poor productivity. On November 7, 2026, the federal government proposed something Canadian investors have complained about for years. Banks would no longer be allowed to charge most investment account transfer fees, which typically cost about $150 per account. Ottawa also wants clearer transfer information and tighter timelines for moving investments to another financial institution. The fee matters because leaving can already be slow and frustrating. Receiving firms often reimburse the outgoing charge to win the account. That means a fee collected by the institution losing the customer can become part of the acquisition cost for the institution trying to win that customer. Canada's six largest banks hold roughly 93% of banking assets. The Competition Bureau was warning about barriers facing fintech competitors in 2017. Ottawa began reviewing open banking in 2018. A federal advisory committee later recommended an operating system by January 2023 and warned that government should not delay. January 2023 came and went. Real Time Rail also slipped years beyond its first expected ...
Digital illustration of Canada bank transfer fee reform showing easier investment account switching, lower fees, open banking, payment infrastructure and stronger financial competition
November 10, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Regulation And Policy Funds, Collateral And Settlement Lead Canada’s Near Term Tokenization Opportunity On November 10, 2026, the Canadian Securities Administrators published its Project Tokenization Phase 1 findings, setting out where Canadian market participants see the strongest commercial opportunities for tokenization and what regulators plan to test next. The report draws on 233 organizations, 21 bilateral meetings and 80 survey responses, along with workshops attended by 281 people in Calgary and 491 in Toronto. Participants put investment funds, private assets, collateral, treasury and settlement infrastructure ahead of public stocks as the strongest near term opportunities. The report also cuts through one of tokenization’s biggest sales pitches. Blockchain can change how an asset is recorded, transferred or settled, but it doesn't automatically create liquidity, investor demand, broader eligibility or stronger ownership rights. Those outcomes still depend on the product, market, legal structure and infrastructure around it. The CSA now plans to take specific projects into Phase 2 through a 120 day public call for proposals. Firms may be able to use existing regulatory processes, tailored regulatory treatment or bounded testing in a ...
Digital illustration of tokenized financial assets, blockchain settlement and legal infrastructure, representing Canada's investment funds and collateral markets.
Nov 11, 2026 A positive work environment is key for any team that wants to succeed. Team morale is crucial for productivity, motivation, and job satisfaction. Engaging in activities that lift spirits and strengthen connections can lead to great results. Creating a positive team environment requires creativity, engagement, and some fun. Each activity can strengthen connections, boost motivation, and improve workplace dynamics. When teams focus on strategies to boost morale, they work toward shared success. These activities can lead to lasting memories and help build a stronger team culture. Here are some fun strategies to help improve your team's morale and make the workplace livelier. Fun at the Arcade Visiting an arcade spot is a great way to enjoy time together and build teamwork. Imagine your team facing challenges with various games. Whether it's racing or playing team games, the arcade encourages friendly competition and bonding. These fun experiences can help reduce stress and improve relationships among coworkers. Arcades offer many options to suit diverse interests and skill levels. The lively atmosphere invites everyone to relax and take a break from their daily tasks. Shared laughter and enjoyment can lead to better communication and teamwork when you return to the ...
Digital illustration of team building activities boosting workplace morale with coworkers playing games and laughing in a bright modern office


FinTech Charter Hits Speed Bump

PYMNTS | May 6, 2019

The suit can proceed.

The news came Thursday (May 2) that, per a ruling in federal court in New York, the State Department of Financial Services can move forward with a suit that looks to derail national bank charters for FinTech companies.

Judge Victor Marrero, presiding over the U.S. District Court for the Southern District of New York, said the case can proceed, a ruling that denied a dismissal of the suit requested by the Office of the Comptroller of the Currency (OCC).

The New York department had argued that the OCC had stepped beyond its regulatory authority (and is misinterpreting the National Bank Act) when it had offered the “special purpose” charter in the middle of last year.

The judge ruled that “such dramatic disruption of federal state relationships in the banking industry occasioned by a federal regulatory agency lends weight to the argument that it represents exercise of authority that exceeds what Congress may have contemplated in passing the NBA

. Indeed, if DFS’ characterization of the impact is accurate – which the Court assumes, given the posture of this order … the OCC’s reading is not so much an ‘interpretation’ as ‘a fundamental revision’ of the NBA.”

See:  Tech’s raid on the banks

The national licenses would let FinTechs lend money and paychecks to consumers.

Separately, in news germane to the OCC, it has opened up a 45-day public comment period on a proposed Innovation Pilot Program encouraging banks to participate in pilots spanning as long as 24 months. It would allow banks to offer regulatory impact on innovations that include some tech-driven initiatives. The pilot program is distinct from a sandbox approach, where pilots tied to innovation get regulatory waivers.

Separately, the Reserve Bank of India late last week said it has fined Yes Bank as much as 11.25 lakh (roughly $1.6 million USD) as a penalty under the Payment and Settlement Systems Act of 2007. The penalty was levied in the wake of violations that involved the “issuance and operation of prepaid payment instruments in connection with certain product features of an open loop prepaid card (co-branded) previously issued by the bank,” according to Yes Bank. The prepaid product had been launched as a pilot program in September of 2017 and was discontinued in March of last year.

Continue to the full article --> here


The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

Nov 7, 2026 | Last Updated Nov 13, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Competition And Market Structure, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Embedded Finance, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading NCFA Fintech Whisperer is a live weekly market intelligence page tracking financial technology and financial innovation developments that change how markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins. Missed a prior week's Fintech Whisperer? Browse December 6 to 12, ...
Fintech market intelligence visualization
About NCFA Canada | Craig Asano | November 13, 2026 Featured Guest: ROB EIJGENRAAM, Founder, TokenMinds (LinkedIn) Rob Eijgenraam is the Founder of TokenMinds and Creator of TMX, a suite of blockchain and AI technology products. Based in Singapore, Rob helps established businesses outside the crypto industry develop token launches, fundraising strategies and Web3 products, with each project designed around a clear return on investment. An experienced entrepreneur with a background spanning Europe and Asia, Rob founded TokenMinds in 2017 during the early ICO boom. Over nearly a decade, he has navigated major crypto market cycles while expanding the company's capabilities in tokenization, blockchain development and AI-powered financial applications. Rob combines deep entrepreneurial experience with hands-on blockchain and AI execution. Working closely with CEOs, business owners and their advisors, he focuses on finding practical solutions that fit each company's commercial objectives and growth opportunities. About TokenMinds TokenMinds is an award-winning blockchain and AI firm that helps established businesses raise growth capital through token launches without giving up equity. Founded in 2017, TokenMinds has worked with more than 200 companies worldwide, supporting end-to-end solutions for token fundraising through innovative Web3 and AI strategies. Its services span tokenomics, fundraising strategy, investor outreach, blockchain development, token launches ...
Fintech Fridays S4E68 Rob Eijgenraam TokenMinds
Nov 12, 2026 Buying a Canadian money services business starts with identifying what the buyer will acquire: a legal entity, a registration history, contracts, records and possibly an active operation. The value of that package depends on whether it supports the services the new owner intends to provide. A FINTRAC registration entry is an important starting point. It does not establish the company’s financial condition, the quality of its compliance programme or the availability of banking relationships after an acquisition. A payment business may also need a separate assessment under the Retail Payment Activities Act, or RPAA. For investors evaluating a Canadian MSB company for sale, due diligence should connect registration status, actual activities, transaction structure and financial evidence before the parties agree a completion timetable. Verify the Canadian MSB registration and legal entity Begin with the target’s exact legal name, incorporation details, registration number and current status. Match the entity in the corporate documents to the entity in FINTRAC’s Money Services Business Registry. FINTRAC explicitly states that registration does not mean it endorses or licenses a business. It also states that it does not issue licences or certificates of registration. A sales presentation using the phrase “FINTRAC licence” should ...
AI illustration of a Canadian MSB acquisition due diligence checklist covering FINTRAC registration, RPAA compliance, ownership, financial review and banking relationships
November 12, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading Strategy still runs a software business, but Bitcoin now dominates its assets and capital raising. MSCI no longer treats that balance as an index eligible operating company. November 11, 2026, MSCI confirmed Strategy’s removal from the MSCI USA and MSCI World indexes after the November 30 close under its new methodology for non operating companies. MSCI is one of the world’s largest index providers, and its benchmarks are followed by funds investing across global equity markets. Japan’s Metaplanet is also being removed from an MSCI index. MSCI has decided that Strategy no longer qualifies for its equity indexes because Bitcoin now dominates its assets and much of its capital raising. Strategy still sells software and reports operating revenue, but MSCI is drawing a line between a business that holds investment assets and one where those assets have become the main financial story. Why Is MSCI Removing Strategy From Its Indexes? MSCI first looked at a rule aimed specifically at digital asset treasury companies. It later dropped that proposal and change it's methodology to cover companies whose finances ...
AI illustration of Bitcoin and public company symbols representing Strategy’s removal from MSCI indexes and the financing model behind Bitcoin treasury companies
Nov 12, 2026 Crypto market cap is calculated by multiplying an asset's reference price by its circulating supply. A token priced at $2 with 50 million units circulating has a market cap of $100 million. The calculation estimates the value of that supply at the reference price; it does not total the money investors deposited. To understand a change in the ranking, examine both inputs and the provider's definitions. A larger number can result from price changes, supply changes, or revised reporting. Establish what the two inputs represent The arithmetic is simple, but neither input is self-explanatory. “Price” may be a reference assembled from selected trading pairs and venues, rather than the last transaction on the exchange you use. A provider may exclude observations or convert quote currencies. Two services can publish different estimates because their source selection and methods differ. Circulating supply is an estimate of units treated as available in the market under a provider's rules. It may differ from the number minted, the total recorded by a contract, or the maximum permitted under a protocol's current design. Locked balances, treasury allocations, burns, and scheduled releases require interpretation. A transparent methodology matters because identical arithmetic can still use ...
AI illustration of stacks of coins beside financial charts illustrating how cryptocurrency prices and circulating supply affect crypto market capitalization
November 11, 2026 | NCFA Fintech Market Insight | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Risk Compliance And Regtech Financial firms are putting AI agents into production well before giving them broad financial authority. That creates time to set identity, permissions and transaction controls before autonomous execution becomes common. On November 11, 2026, Bank of England Financial Policy Committee external member Jonathan Hall used his final FPC speech to examine what happens when AI agents get more authority inside financial firms. A Bank of England and FCA survey of 196 firms found that 80% already deploy AI agents and another 14% plan to within 12 months. Only 2% reported agents with broad autonomy, and none of those were in trading and payments. Finance is adopting agents quickly, but firms are still keeping people and hard limits around the decisions that can change money, positions or customer outcomes. AI Agents Are In Finance But They Are Not Trading Alone The 2026 Bank of England and FCA survey separates four levels of authority: Decision support lets an agent recommend an action while a person decides and executes it. Constrained execution lets the agent act inside preset rules. Conditional autonomy ...
AI illustration of AI agents connected across a financial trading network, representing shared market behaviour, trading automation and financial stability risk
November 10, 2026 | NCFA Fintech Market Insight | Capital Markets Infrastructure And Funding, Entrepreneurs Startups Small Businesses, Equity Crowdfunding And Alternative Funding A small group of large rounds is carrying Canadian venture totals while deal count and growth stage financing remain well below recent norms. On November 10, 2026, the Canadian Venture Capital and Private Equity Association published its Q3 2026 venture capital report. Canadian companies raised $4.3 billion across 397 deals through September, only 1% less capital than a year earlier. But 23 rounds of $50 million or more represented just 6% of disclosed deals and absorbed 58% of all venture capital invested. Deal count has also fallen every year since 2021. The national total is holding up far better than the number of companies getting financed. Six Big Rounds Carried 59% Of Q3 Venture Capital Q3 produced $1.35 billion across 129 deals. Capital was 1% higher than Q2, but deal count fell 15%. Six rounds above $50 million accounted for $793 million, or 59% of the quarter’s capital. That's a decent quarter for the companies that closed those rounds, but a weak quarter for everyone else. Mega rounds above $50 million totalled $2.5 billion across 23 transactions ...
AI Illustration of large venture capital deals dominating smaller financings, representing concentration in Canada’s VC market
November 11, 2026 | NCFA Story Intelligence | Competition And Market Structure, Wealthtech Investing And Trading, Regulation And Policy Canada is cutting bank fees and switching barriers after years of weak competition, high concentration and poor productivity. On November 7, 2026, the federal government proposed something Canadian investors have complained about for years. Banks would no longer be allowed to charge most investment account transfer fees, which typically cost about $150 per account. Ottawa also wants clearer transfer information and tighter timelines for moving investments to another financial institution. The fee matters because leaving can already be slow and frustrating. Receiving firms often reimburse the outgoing charge to win the account. That means a fee collected by the institution losing the customer can become part of the acquisition cost for the institution trying to win that customer. Canada's six largest banks hold roughly 93% of banking assets. The Competition Bureau was warning about barriers facing fintech competitors in 2017. Ottawa began reviewing open banking in 2018. A federal advisory committee later recommended an operating system by January 2023 and warned that government should not delay. January 2023 came and went. Real Time Rail also slipped years beyond its first expected ...
Digital illustration of Canada bank transfer fee reform showing easier investment account switching, lower fees, open banking, payment infrastructure and stronger financial competition
November 10, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Regulation And Policy Funds, Collateral And Settlement Lead Canada’s Near Term Tokenization Opportunity On November 10, 2026, the Canadian Securities Administrators published its Project Tokenization Phase 1 findings, setting out where Canadian market participants see the strongest commercial opportunities for tokenization and what regulators plan to test next. The report draws on 233 organizations, 21 bilateral meetings and 80 survey responses, along with workshops attended by 281 people in Calgary and 491 in Toronto. Participants put investment funds, private assets, collateral, treasury and settlement infrastructure ahead of public stocks as the strongest near term opportunities. The report also cuts through one of tokenization’s biggest sales pitches. Blockchain can change how an asset is recorded, transferred or settled, but it doesn't automatically create liquidity, investor demand, broader eligibility or stronger ownership rights. Those outcomes still depend on the product, market, legal structure and infrastructure around it. The CSA now plans to take specific projects into Phase 2 through a 120 day public call for proposals. Firms may be able to use existing regulatory processes, tailored regulatory treatment or bounded testing in a ...
Digital illustration of tokenized financial assets, blockchain settlement and legal infrastructure, representing Canada's investment funds and collateral markets.
Nov 11, 2026 A positive work environment is key for any team that wants to succeed. Team morale is crucial for productivity, motivation, and job satisfaction. Engaging in activities that lift spirits and strengthen connections can lead to great results. Creating a positive team environment requires creativity, engagement, and some fun. Each activity can strengthen connections, boost motivation, and improve workplace dynamics. When teams focus on strategies to boost morale, they work toward shared success. These activities can lead to lasting memories and help build a stronger team culture. Here are some fun strategies to help improve your team's morale and make the workplace livelier. Fun at the Arcade Visiting an arcade spot is a great way to enjoy time together and build teamwork. Imagine your team facing challenges with various games. Whether it's racing or playing team games, the arcade encourages friendly competition and bonding. These fun experiences can help reduce stress and improve relationships among coworkers. Arcades offer many options to suit diverse interests and skill levels. The lively atmosphere invites everyone to relax and take a break from their daily tasks. Shared laughter and enjoyment can lead to better communication and teamwork when you return to the ...
Digital illustration of team building activities boosting workplace morale with coworkers playing games and laughing in a bright modern office


What bankers need to know about the mobile generation

The Economist - Special Banking Focus | May 2, 2019

Younger customers have high expectations for speedy, convenient service

IF YOU TURN 18 this year, you are younger than Amazon and Google. You turned three with Facebook’s arrival, four with YouTube, five with Spotify, six with the iPhone and eight with WhatsApp. If you are at the upper end of the 18-30 age range considered in this special report, you will remember a time before mobile internet, but not a time before mobile phones. If you are anywhere in that range, you use your mobile to read, chat and play, stream music and videos, hail taxis, order food, and search for dates and jobs.

You use mobile phones to manage your money, too. Research last year by Raddon, a consultancy, found that 85% of American millennials (those born between 1981 and 1996) used mobile banking, and predicted that the share would be higher still for Gen Z (born after 1996). The main reason people choose a bank is convenience, the consultancy says. For older people that means a nearby branch; for younger ones it means an excellent app.

You have cooled on cash. Half of American millennials use peer-to-peer payment services such as Venmo or Zelle at least once a week. In 2017 Bain & Company, another consultancy, asked people in 17 countries which they would miss more for a day: their phone or their wallet. Everywhere except Japan and Malaysia, the share of under-25s who would miss their phone more was above 70% (see chart).

See: 

You are a demanding customer, with expectations of speedy, convenient service that have been set by Uber and Amazon Prime. You are generally willing to grant companies access to your data, but want something in return. You let Google Maps track your location to help you get where you are going; you like Netflix using your viewing habits for recommendations.

In many developed countries, tuition fees mean you have much more debt than previous generations did. Soaring property prices have made it harder for you to become a homeowner. Growing up in the aftermath of the financial crisis has left you cautious about loans. According to bankrate.com, a comparison service, just one in three American millennials has a credit or debit card, a much lower share than for previous generations at the same age. All this means banks find it hard to make money from you.

Continue to the full article --> here


The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

Nov 7, 2026 | Last Updated Nov 13, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Competition And Market Structure, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Embedded Finance, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading NCFA Fintech Whisperer is a live weekly market intelligence page tracking financial technology and financial innovation developments that change how markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins. Missed a prior week's Fintech Whisperer? Browse December 6 to 12, ...
Fintech market intelligence visualization
About NCFA Canada | Craig Asano | November 13, 2026 Featured Guest: ROB EIJGENRAAM, Founder, TokenMinds (LinkedIn) Rob Eijgenraam is the Founder of TokenMinds and Creator of TMX, a suite of blockchain and AI technology products. Based in Singapore, Rob helps established businesses outside the crypto industry develop token launches, fundraising strategies and Web3 products, with each project designed around a clear return on investment. An experienced entrepreneur with a background spanning Europe and Asia, Rob founded TokenMinds in 2017 during the early ICO boom. Over nearly a decade, he has navigated major crypto market cycles while expanding the company's capabilities in tokenization, blockchain development and AI-powered financial applications. Rob combines deep entrepreneurial experience with hands-on blockchain and AI execution. Working closely with CEOs, business owners and their advisors, he focuses on finding practical solutions that fit each company's commercial objectives and growth opportunities. About TokenMinds TokenMinds is an award-winning blockchain and AI firm that helps established businesses raise growth capital through token launches without giving up equity. Founded in 2017, TokenMinds has worked with more than 200 companies worldwide, supporting end-to-end solutions for token fundraising through innovative Web3 and AI strategies. Its services span tokenomics, fundraising strategy, investor outreach, blockchain development, token launches ...
Fintech Fridays S4E68 Rob Eijgenraam TokenMinds
Nov 12, 2026 Buying a Canadian money services business starts with identifying what the buyer will acquire: a legal entity, a registration history, contracts, records and possibly an active operation. The value of that package depends on whether it supports the services the new owner intends to provide. A FINTRAC registration entry is an important starting point. It does not establish the company’s financial condition, the quality of its compliance programme or the availability of banking relationships after an acquisition. A payment business may also need a separate assessment under the Retail Payment Activities Act, or RPAA. For investors evaluating a Canadian MSB company for sale, due diligence should connect registration status, actual activities, transaction structure and financial evidence before the parties agree a completion timetable. Verify the Canadian MSB registration and legal entity Begin with the target’s exact legal name, incorporation details, registration number and current status. Match the entity in the corporate documents to the entity in FINTRAC’s Money Services Business Registry. FINTRAC explicitly states that registration does not mean it endorses or licenses a business. It also states that it does not issue licences or certificates of registration. A sales presentation using the phrase “FINTRAC licence” should ...
AI illustration of a Canadian MSB acquisition due diligence checklist covering FINTRAC registration, RPAA compliance, ownership, financial review and banking relationships
November 12, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading Strategy still runs a software business, but Bitcoin now dominates its assets and capital raising. MSCI no longer treats that balance as an index eligible operating company. November 11, 2026, MSCI confirmed Strategy’s removal from the MSCI USA and MSCI World indexes after the November 30 close under its new methodology for non operating companies. MSCI is one of the world’s largest index providers, and its benchmarks are followed by funds investing across global equity markets. Japan’s Metaplanet is also being removed from an MSCI index. MSCI has decided that Strategy no longer qualifies for its equity indexes because Bitcoin now dominates its assets and much of its capital raising. Strategy still sells software and reports operating revenue, but MSCI is drawing a line between a business that holds investment assets and one where those assets have become the main financial story. Why Is MSCI Removing Strategy From Its Indexes? MSCI first looked at a rule aimed specifically at digital asset treasury companies. It later dropped that proposal and change it's methodology to cover companies whose finances ...
AI illustration of Bitcoin and public company symbols representing Strategy’s removal from MSCI indexes and the financing model behind Bitcoin treasury companies
Nov 12, 2026 Crypto market cap is calculated by multiplying an asset's reference price by its circulating supply. A token priced at $2 with 50 million units circulating has a market cap of $100 million. The calculation estimates the value of that supply at the reference price; it does not total the money investors deposited. To understand a change in the ranking, examine both inputs and the provider's definitions. A larger number can result from price changes, supply changes, or revised reporting. Establish what the two inputs represent The arithmetic is simple, but neither input is self-explanatory. “Price” may be a reference assembled from selected trading pairs and venues, rather than the last transaction on the exchange you use. A provider may exclude observations or convert quote currencies. Two services can publish different estimates because their source selection and methods differ. Circulating supply is an estimate of units treated as available in the market under a provider's rules. It may differ from the number minted, the total recorded by a contract, or the maximum permitted under a protocol's current design. Locked balances, treasury allocations, burns, and scheduled releases require interpretation. A transparent methodology matters because identical arithmetic can still use ...
AI illustration of stacks of coins beside financial charts illustrating how cryptocurrency prices and circulating supply affect crypto market capitalization
November 11, 2026 | NCFA Fintech Market Insight | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Risk Compliance And Regtech Financial firms are putting AI agents into production well before giving them broad financial authority. That creates time to set identity, permissions and transaction controls before autonomous execution becomes common. On November 11, 2026, Bank of England Financial Policy Committee external member Jonathan Hall used his final FPC speech to examine what happens when AI agents get more authority inside financial firms. A Bank of England and FCA survey of 196 firms found that 80% already deploy AI agents and another 14% plan to within 12 months. Only 2% reported agents with broad autonomy, and none of those were in trading and payments. Finance is adopting agents quickly, but firms are still keeping people and hard limits around the decisions that can change money, positions or customer outcomes. AI Agents Are In Finance But They Are Not Trading Alone The 2026 Bank of England and FCA survey separates four levels of authority: Decision support lets an agent recommend an action while a person decides and executes it. Constrained execution lets the agent act inside preset rules. Conditional autonomy ...
AI illustration of AI agents connected across a financial trading network, representing shared market behaviour, trading automation and financial stability risk
November 10, 2026 | NCFA Fintech Market Insight | Capital Markets Infrastructure And Funding, Entrepreneurs Startups Small Businesses, Equity Crowdfunding And Alternative Funding A small group of large rounds is carrying Canadian venture totals while deal count and growth stage financing remain well below recent norms. On November 10, 2026, the Canadian Venture Capital and Private Equity Association published its Q3 2026 venture capital report. Canadian companies raised $4.3 billion across 397 deals through September, only 1% less capital than a year earlier. But 23 rounds of $50 million or more represented just 6% of disclosed deals and absorbed 58% of all venture capital invested. Deal count has also fallen every year since 2021. The national total is holding up far better than the number of companies getting financed. Six Big Rounds Carried 59% Of Q3 Venture Capital Q3 produced $1.35 billion across 129 deals. Capital was 1% higher than Q2, but deal count fell 15%. Six rounds above $50 million accounted for $793 million, or 59% of the quarter’s capital. That's a decent quarter for the companies that closed those rounds, but a weak quarter for everyone else. Mega rounds above $50 million totalled $2.5 billion across 23 transactions ...
AI Illustration of large venture capital deals dominating smaller financings, representing concentration in Canada’s VC market
November 11, 2026 | NCFA Story Intelligence | Competition And Market Structure, Wealthtech Investing And Trading, Regulation And Policy Canada is cutting bank fees and switching barriers after years of weak competition, high concentration and poor productivity. On November 7, 2026, the federal government proposed something Canadian investors have complained about for years. Banks would no longer be allowed to charge most investment account transfer fees, which typically cost about $150 per account. Ottawa also wants clearer transfer information and tighter timelines for moving investments to another financial institution. The fee matters because leaving can already be slow and frustrating. Receiving firms often reimburse the outgoing charge to win the account. That means a fee collected by the institution losing the customer can become part of the acquisition cost for the institution trying to win that customer. Canada's six largest banks hold roughly 93% of banking assets. The Competition Bureau was warning about barriers facing fintech competitors in 2017. Ottawa began reviewing open banking in 2018. A federal advisory committee later recommended an operating system by January 2023 and warned that government should not delay. January 2023 came and went. Real Time Rail also slipped years beyond its first expected ...
Digital illustration of Canada bank transfer fee reform showing easier investment account switching, lower fees, open banking, payment infrastructure and stronger financial competition
November 10, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Regulation And Policy Funds, Collateral And Settlement Lead Canada’s Near Term Tokenization Opportunity On November 10, 2026, the Canadian Securities Administrators published its Project Tokenization Phase 1 findings, setting out where Canadian market participants see the strongest commercial opportunities for tokenization and what regulators plan to test next. The report draws on 233 organizations, 21 bilateral meetings and 80 survey responses, along with workshops attended by 281 people in Calgary and 491 in Toronto. Participants put investment funds, private assets, collateral, treasury and settlement infrastructure ahead of public stocks as the strongest near term opportunities. The report also cuts through one of tokenization’s biggest sales pitches. Blockchain can change how an asset is recorded, transferred or settled, but it doesn't automatically create liquidity, investor demand, broader eligibility or stronger ownership rights. Those outcomes still depend on the product, market, legal structure and infrastructure around it. The CSA now plans to take specific projects into Phase 2 through a 120 day public call for proposals. Firms may be able to use existing regulatory processes, tailored regulatory treatment or bounded testing in a ...
Digital illustration of tokenized financial assets, blockchain settlement and legal infrastructure, representing Canada's investment funds and collateral markets.
Nov 11, 2026 A positive work environment is key for any team that wants to succeed. Team morale is crucial for productivity, motivation, and job satisfaction. Engaging in activities that lift spirits and strengthen connections can lead to great results. Creating a positive team environment requires creativity, engagement, and some fun. Each activity can strengthen connections, boost motivation, and improve workplace dynamics. When teams focus on strategies to boost morale, they work toward shared success. These activities can lead to lasting memories and help build a stronger team culture. Here are some fun strategies to help improve your team's morale and make the workplace livelier. Fun at the Arcade Visiting an arcade spot is a great way to enjoy time together and build teamwork. Imagine your team facing challenges with various games. Whether it's racing or playing team games, the arcade encourages friendly competition and bonding. These fun experiences can help reduce stress and improve relationships among coworkers. Arcades offer many options to suit diverse interests and skill levels. The lively atmosphere invites everyone to relax and take a break from their daily tasks. Shared laughter and enjoyment can lead to better communication and teamwork when you return to the ...
Digital illustration of team building activities boosting workplace morale with coworkers playing games and laughing in a bright modern office


Tech’s raid on the banks

The Economist | May 2, 2019

OVER THE past two decades people across the world have seen digital services transform the economy and their lives. Taxis, films, novels, noodles, doctors and dog-walkers can all be summoned with a tap of a screen. Giant firms in retailing, carmaking and the media have been humbled by new competitors. Yet one industry has withstood the tumult: banking. In rich countries it is perfectly normal to queue in branches, correspond with your bank by post and deposit cheques stamped with the logo of firms founded in the 19th century.

See:  Why Open Banking Represents a Seismic Shift for Fintech

Yet, as our special report this week explains, technology is at last shaking up banking. In Asia payment apps are a way of life for over 1bn users. In the West mobile banking is reaching critical mass—49% of Americans bank on their phones—and tech giants are muscling in. Apple unveiled a credit card with Goldman Sachs on March 25th. Facebook is proposing a payments service to let users buy tickets and settle bills (see article).

The implications are profound because banks are not ordinary firms. It is one thing for Blockbuster Video to be wiped out by a technological shift, but quite another if the victim is Bank of America. It is not just that banks have over $100trn of assets globally. Using the difficult trick of “maturity transformation” (turning deposits that you can demand back at any time into long-term loans) they enable savers to defer consumption and investment and borrowers to bring them forward. Banks are so vital that the economy reels when they stumble, as the crisis of 2008-09 showed.

Bankers and politicians may thus be tempted to resist technological change. But that would be wrong because its benefits—a leaner, more user-friendly and more open financial system—easily outweigh the risks.

Banking is late to the smartphone age because entrepreneurs have been put off by regulations. And, since the financial crisis, Western banks have been preoccupied with repairing their balance-sheets and old-fashioned cost-cutting. Late is better than never, however. Several new business models are emerging. In Asia payment apps are bundled with e-commerce, chat and ride-hailing services offered by firms such as Alibaba and Tencent in China and Grab in South-East Asia. These networks link to banks but are vying to control the customer relationship. In America and Europe big banks are still more or less in control and are rushing to offer digital products—JPMorgan Chase can open a deposit account in five minutes. But threats loom. Mobile-only “neobanks” that do not bear the cost of branches are nibbling at customer bases. Payments firms like PayPal work with Western banks but are expected to capture a greater share of profits. Lucrative niches like foreign exchange and asset management are being harried by new entrants.

See:  Open banking data tapped to speed up laundering checks

The pace of change will accelerate. Younger people no longer stay with the same bank as their parents—15% of British 18- to 23-year-olds use a neobank. Tech firms that people trust, such as Apple and Amazon, are natural candidates to grow big financial arms. The biggest four American banks are spending a total of over $25bn a year on perfecting better customer applications and learning to mine data more cleverly. Venture-capital firms invested $37bn in upstart financial firms last year.

The benefits of technological change are likely to be vast. Costs should tumble as branches are shut, creaking mainframe systems retired and bureaucracy culled. If the world’s listed banks chopped expenses by a third, the saving would be worth $80 a year for every person on Earth. In 2000 the Netherlands had more bank branches per head than America; it now has just a third as many. Rotten service will improve—it is easier to get money to a friend using a chat app than it is to ask your bank to transfer cash. The system will get better at its vital job of allocating capital. Richer data will allow banks to take risks that currently baffle underwriters. Fraud should be easier to spot. Lower costs and the democratising effect of social media will give more people better access to finance. And more firms with good ideas should be able to get loans faster, boosting growth.

Yet change also poses risks. Because the financial system is embedded in the economy, innovation tends to create turbulence. The credit card’s arrival in 1950 revolutionised shopping but also sparked America’s consumer-debt culture. Securitisation lubricated capital markets in the 1980s but fuelled the subprime crisis. In addition, it is unclear who will win today’s battle. One dystopian scenario is that power becomes more concentrated, as a few big banks learn to exploit data as ruthlessly as social-media firms do. Imagine a crossbreed of Facebook and Wells Fargo that predicts and manipulates how customers behave and is able to use proprietary economic data to squeeze rivals.

See:  Fintech firms want to shake up banking, and that worries the Fed

Another dystopia involves fragmentation and destabilisation. Banks could lose depositors to untested neobanks, creating a mismatch between their assets and liabilities that could lead to a credit crunch. If bank customers transact via tech or payment platforms, banks could end up with huge balance-sheets but without a direct connection to their clients. If they thus became unprofitable, they could be broken up, with the job of financing mortgages and absorbing short-term savings left entirely to capital markets, which are volatile.

Continue to the full article --> here


The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

Nov 7, 2026 | Last Updated Nov 13, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Competition And Market Structure, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Embedded Finance, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading NCFA Fintech Whisperer is a live weekly market intelligence page tracking financial technology and financial innovation developments that change how markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins. Missed a prior week's Fintech Whisperer? Browse December 6 to 12, ...
Fintech market intelligence visualization
About NCFA Canada | Craig Asano | November 13, 2026 Featured Guest: ROB EIJGENRAAM, Founder, TokenMinds (LinkedIn) Rob Eijgenraam is the Founder of TokenMinds and Creator of TMX, a suite of blockchain and AI technology products. Based in Singapore, Rob helps established businesses outside the crypto industry develop token launches, fundraising strategies and Web3 products, with each project designed around a clear return on investment. An experienced entrepreneur with a background spanning Europe and Asia, Rob founded TokenMinds in 2017 during the early ICO boom. Over nearly a decade, he has navigated major crypto market cycles while expanding the company's capabilities in tokenization, blockchain development and AI-powered financial applications. Rob combines deep entrepreneurial experience with hands-on blockchain and AI execution. Working closely with CEOs, business owners and their advisors, he focuses on finding practical solutions that fit each company's commercial objectives and growth opportunities. About TokenMinds TokenMinds is an award-winning blockchain and AI firm that helps established businesses raise growth capital through token launches without giving up equity. Founded in 2017, TokenMinds has worked with more than 200 companies worldwide, supporting end-to-end solutions for token fundraising through innovative Web3 and AI strategies. Its services span tokenomics, fundraising strategy, investor outreach, blockchain development, token launches ...
Fintech Fridays S4E68 Rob Eijgenraam TokenMinds
Nov 12, 2026 Buying a Canadian money services business starts with identifying what the buyer will acquire: a legal entity, a registration history, contracts, records and possibly an active operation. The value of that package depends on whether it supports the services the new owner intends to provide. A FINTRAC registration entry is an important starting point. It does not establish the company’s financial condition, the quality of its compliance programme or the availability of banking relationships after an acquisition. A payment business may also need a separate assessment under the Retail Payment Activities Act, or RPAA. For investors evaluating a Canadian MSB company for sale, due diligence should connect registration status, actual activities, transaction structure and financial evidence before the parties agree a completion timetable. Verify the Canadian MSB registration and legal entity Begin with the target’s exact legal name, incorporation details, registration number and current status. Match the entity in the corporate documents to the entity in FINTRAC’s Money Services Business Registry. FINTRAC explicitly states that registration does not mean it endorses or licenses a business. It also states that it does not issue licences or certificates of registration. A sales presentation using the phrase “FINTRAC licence” should ...
AI illustration of a Canadian MSB acquisition due diligence checklist covering FINTRAC registration, RPAA compliance, ownership, financial review and banking relationships
November 12, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading Strategy still runs a software business, but Bitcoin now dominates its assets and capital raising. MSCI no longer treats that balance as an index eligible operating company. November 11, 2026, MSCI confirmed Strategy’s removal from the MSCI USA and MSCI World indexes after the November 30 close under its new methodology for non operating companies. MSCI is one of the world’s largest index providers, and its benchmarks are followed by funds investing across global equity markets. Japan’s Metaplanet is also being removed from an MSCI index. MSCI has decided that Strategy no longer qualifies for its equity indexes because Bitcoin now dominates its assets and much of its capital raising. Strategy still sells software and reports operating revenue, but MSCI is drawing a line between a business that holds investment assets and one where those assets have become the main financial story. Why Is MSCI Removing Strategy From Its Indexes? MSCI first looked at a rule aimed specifically at digital asset treasury companies. It later dropped that proposal and change it's methodology to cover companies whose finances ...
AI illustration of Bitcoin and public company symbols representing Strategy’s removal from MSCI indexes and the financing model behind Bitcoin treasury companies
Nov 12, 2026 Crypto market cap is calculated by multiplying an asset's reference price by its circulating supply. A token priced at $2 with 50 million units circulating has a market cap of $100 million. The calculation estimates the value of that supply at the reference price; it does not total the money investors deposited. To understand a change in the ranking, examine both inputs and the provider's definitions. A larger number can result from price changes, supply changes, or revised reporting. Establish what the two inputs represent The arithmetic is simple, but neither input is self-explanatory. “Price” may be a reference assembled from selected trading pairs and venues, rather than the last transaction on the exchange you use. A provider may exclude observations or convert quote currencies. Two services can publish different estimates because their source selection and methods differ. Circulating supply is an estimate of units treated as available in the market under a provider's rules. It may differ from the number minted, the total recorded by a contract, or the maximum permitted under a protocol's current design. Locked balances, treasury allocations, burns, and scheduled releases require interpretation. A transparent methodology matters because identical arithmetic can still use ...
AI illustration of stacks of coins beside financial charts illustrating how cryptocurrency prices and circulating supply affect crypto market capitalization
November 11, 2026 | NCFA Fintech Market Insight | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Risk Compliance And Regtech Financial firms are putting AI agents into production well before giving them broad financial authority. That creates time to set identity, permissions and transaction controls before autonomous execution becomes common. On November 11, 2026, Bank of England Financial Policy Committee external member Jonathan Hall used his final FPC speech to examine what happens when AI agents get more authority inside financial firms. A Bank of England and FCA survey of 196 firms found that 80% already deploy AI agents and another 14% plan to within 12 months. Only 2% reported agents with broad autonomy, and none of those were in trading and payments. Finance is adopting agents quickly, but firms are still keeping people and hard limits around the decisions that can change money, positions or customer outcomes. AI Agents Are In Finance But They Are Not Trading Alone The 2026 Bank of England and FCA survey separates four levels of authority: Decision support lets an agent recommend an action while a person decides and executes it. Constrained execution lets the agent act inside preset rules. Conditional autonomy ...
AI illustration of AI agents connected across a financial trading network, representing shared market behaviour, trading automation and financial stability risk
November 10, 2026 | NCFA Fintech Market Insight | Capital Markets Infrastructure And Funding, Entrepreneurs Startups Small Businesses, Equity Crowdfunding And Alternative Funding A small group of large rounds is carrying Canadian venture totals while deal count and growth stage financing remain well below recent norms. On November 10, 2026, the Canadian Venture Capital and Private Equity Association published its Q3 2026 venture capital report. Canadian companies raised $4.3 billion across 397 deals through September, only 1% less capital than a year earlier. But 23 rounds of $50 million or more represented just 6% of disclosed deals and absorbed 58% of all venture capital invested. Deal count has also fallen every year since 2021. The national total is holding up far better than the number of companies getting financed. Six Big Rounds Carried 59% Of Q3 Venture Capital Q3 produced $1.35 billion across 129 deals. Capital was 1% higher than Q2, but deal count fell 15%. Six rounds above $50 million accounted for $793 million, or 59% of the quarter’s capital. That's a decent quarter for the companies that closed those rounds, but a weak quarter for everyone else. Mega rounds above $50 million totalled $2.5 billion across 23 transactions ...
AI Illustration of large venture capital deals dominating smaller financings, representing concentration in Canada’s VC market
November 11, 2026 | NCFA Story Intelligence | Competition And Market Structure, Wealthtech Investing And Trading, Regulation And Policy Canada is cutting bank fees and switching barriers after years of weak competition, high concentration and poor productivity. On November 7, 2026, the federal government proposed something Canadian investors have complained about for years. Banks would no longer be allowed to charge most investment account transfer fees, which typically cost about $150 per account. Ottawa also wants clearer transfer information and tighter timelines for moving investments to another financial institution. The fee matters because leaving can already be slow and frustrating. Receiving firms often reimburse the outgoing charge to win the account. That means a fee collected by the institution losing the customer can become part of the acquisition cost for the institution trying to win that customer. Canada's six largest banks hold roughly 93% of banking assets. The Competition Bureau was warning about barriers facing fintech competitors in 2017. Ottawa began reviewing open banking in 2018. A federal advisory committee later recommended an operating system by January 2023 and warned that government should not delay. January 2023 came and went. Real Time Rail also slipped years beyond its first expected ...
Digital illustration of Canada bank transfer fee reform showing easier investment account switching, lower fees, open banking, payment infrastructure and stronger financial competition
November 10, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Regulation And Policy Funds, Collateral And Settlement Lead Canada’s Near Term Tokenization Opportunity On November 10, 2026, the Canadian Securities Administrators published its Project Tokenization Phase 1 findings, setting out where Canadian market participants see the strongest commercial opportunities for tokenization and what regulators plan to test next. The report draws on 233 organizations, 21 bilateral meetings and 80 survey responses, along with workshops attended by 281 people in Calgary and 491 in Toronto. Participants put investment funds, private assets, collateral, treasury and settlement infrastructure ahead of public stocks as the strongest near term opportunities. The report also cuts through one of tokenization’s biggest sales pitches. Blockchain can change how an asset is recorded, transferred or settled, but it doesn't automatically create liquidity, investor demand, broader eligibility or stronger ownership rights. Those outcomes still depend on the product, market, legal structure and infrastructure around it. The CSA now plans to take specific projects into Phase 2 through a 120 day public call for proposals. Firms may be able to use existing regulatory processes, tailored regulatory treatment or bounded testing in a ...
Digital illustration of tokenized financial assets, blockchain settlement and legal infrastructure, representing Canada's investment funds and collateral markets.
Nov 11, 2026 A positive work environment is key for any team that wants to succeed. Team morale is crucial for productivity, motivation, and job satisfaction. Engaging in activities that lift spirits and strengthen connections can lead to great results. Creating a positive team environment requires creativity, engagement, and some fun. Each activity can strengthen connections, boost motivation, and improve workplace dynamics. When teams focus on strategies to boost morale, they work toward shared success. These activities can lead to lasting memories and help build a stronger team culture. Here are some fun strategies to help improve your team's morale and make the workplace livelier. Fun at the Arcade Visiting an arcade spot is a great way to enjoy time together and build teamwork. Imagine your team facing challenges with various games. Whether it's racing or playing team games, the arcade encourages friendly competition and bonding. These fun experiences can help reduce stress and improve relationships among coworkers. Arcades offer many options to suit diverse interests and skill levels. The lively atmosphere invites everyone to relax and take a break from their daily tasks. Shared laughter and enjoyment can lead to better communication and teamwork when you return to the ...
Digital illustration of team building activities boosting workplace morale with coworkers playing games and laughing in a bright modern office


Open banking data tapped to speed up laundering checks

The Law Society (UK) | By Michael Cross | Apr 29, 2019

Conveyancing firms are testing a mobile app that uses data made available by new open banking regulations to comply with ‘source of funds’ checks, the Gazette can reveal.

The automated check is conducted by a client-verification system developed by lawtech startup Thirdfort. The system aims to improve the speed and rigour of identity checks by removing the need for firms to inspect physical passports and documents.

London firm Streathers Solicitors LLP is among those testing the system. Clients receive a text message asking them to download Thirdfort’s app, which guides them through photographing a relevant identity document and recording a short video. The client can then permit the app access to their bank account income and outgoing transaction data.

See:

The app compiles a list of the user’s top 20 transactions over the past 12 months and identifies providers of significant unexplained sums for further checks. This forms part of a comprehensive identity report, along with checks on documents and alerts of politically exposed persons.

Oliver Thornton-Berry, Thirdfort’s co-founder, said this process, combined with remote checking of documents, takes two to three minutes.

‘It is significantly better than relying on certified copies of documents,’ he said.

Since last year, the Competition and Markets Authority has required the nine largest UK banks to make data about transactions available with the approval of the data holder to comply with the EU Payment Services Directive.

According to James Danaher, Streathers Solicitors partner, early trials show the system saves time. ‘It has the potential to save a lot of chasing of bank statements,’ he said. The system also detected that a passport scan was of a photocopy rather than the original document, he said.

Continue to the full article --> here


The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org

NCFA Financial Innovation MapNCFA Innovation Opportunity BriefsNCFA Fintech Insights
NCFA Fintech WhispererNCFA Fintech Fridays PodcastNCFA Weekly Newsletter

Nov 7, 2026 | Last Updated Nov 13, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Competition And Market Structure, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Embedded Finance, Insurance And Insurtech, Lending Consumer Credit And BNPL, Open Banking Open Finance And Data Sharing, Payments Infrastructure And Money Movement, Regulation And Policy, Risk Compliance And Regtech, SME Finance And Business Banking, Sustainable Finance ESG And Financial Inclusion, Treasury Liquidity And Cash Management, Wealthtech Investing And Trading NCFA Fintech Whisperer is a live weekly market intelligence page tracking financial technology and financial innovation developments that change how markets operate. Coverage spans NCFA's full financial innovation taxonomy, with Canada first and global developments included when they materially affect rules, market access, competition, capital, technology adoption, distribution, risk or execution. We focus on changes that founders, investors, financial institutions, regulators and operators may need to act on, not simply what's making headlines. This page is updated throughout the week as material developments emerge, then closed and archived before the next weekly window begins. Missed a prior week's Fintech Whisperer? Browse December 6 to 12, ...
Fintech market intelligence visualization
About NCFA Canada | Craig Asano | November 13, 2026 Featured Guest: ROB EIJGENRAAM, Founder, TokenMinds (LinkedIn) Rob Eijgenraam is the Founder of TokenMinds and Creator of TMX, a suite of blockchain and AI technology products. Based in Singapore, Rob helps established businesses outside the crypto industry develop token launches, fundraising strategies and Web3 products, with each project designed around a clear return on investment. An experienced entrepreneur with a background spanning Europe and Asia, Rob founded TokenMinds in 2017 during the early ICO boom. Over nearly a decade, he has navigated major crypto market cycles while expanding the company's capabilities in tokenization, blockchain development and AI-powered financial applications. Rob combines deep entrepreneurial experience with hands-on blockchain and AI execution. Working closely with CEOs, business owners and their advisors, he focuses on finding practical solutions that fit each company's commercial objectives and growth opportunities. About TokenMinds TokenMinds is an award-winning blockchain and AI firm that helps established businesses raise growth capital through token launches without giving up equity. Founded in 2017, TokenMinds has worked with more than 200 companies worldwide, supporting end-to-end solutions for token fundraising through innovative Web3 and AI strategies. Its services span tokenomics, fundraising strategy, investor outreach, blockchain development, token launches ...
Fintech Fridays S4E68 Rob Eijgenraam TokenMinds
Nov 12, 2026 Buying a Canadian money services business starts with identifying what the buyer will acquire: a legal entity, a registration history, contracts, records and possibly an active operation. The value of that package depends on whether it supports the services the new owner intends to provide. A FINTRAC registration entry is an important starting point. It does not establish the company’s financial condition, the quality of its compliance programme or the availability of banking relationships after an acquisition. A payment business may also need a separate assessment under the Retail Payment Activities Act, or RPAA. For investors evaluating a Canadian MSB company for sale, due diligence should connect registration status, actual activities, transaction structure and financial evidence before the parties agree a completion timetable. Verify the Canadian MSB registration and legal entity Begin with the target’s exact legal name, incorporation details, registration number and current status. Match the entity in the corporate documents to the entity in FINTRAC’s Money Services Business Registry. FINTRAC explicitly states that registration does not mean it endorses or licenses a business. It also states that it does not issue licences or certificates of registration. A sales presentation using the phrase “FINTRAC licence” should ...
AI illustration of a Canadian MSB acquisition due diligence checklist covering FINTRAC registration, RPAA compliance, ownership, financial review and banking relationships
November 12, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading Strategy still runs a software business, but Bitcoin now dominates its assets and capital raising. MSCI no longer treats that balance as an index eligible operating company. November 11, 2026, MSCI confirmed Strategy’s removal from the MSCI USA and MSCI World indexes after the November 30 close under its new methodology for non operating companies. MSCI is one of the world’s largest index providers, and its benchmarks are followed by funds investing across global equity markets. Japan’s Metaplanet is also being removed from an MSCI index. MSCI has decided that Strategy no longer qualifies for its equity indexes because Bitcoin now dominates its assets and much of its capital raising. Strategy still sells software and reports operating revenue, but MSCI is drawing a line between a business that holds investment assets and one where those assets have become the main financial story. Why Is MSCI Removing Strategy From Its Indexes? MSCI first looked at a rule aimed specifically at digital asset treasury companies. It later dropped that proposal and change it's methodology to cover companies whose finances ...
AI illustration of Bitcoin and public company symbols representing Strategy’s removal from MSCI indexes and the financing model behind Bitcoin treasury companies
Nov 12, 2026 Crypto market cap is calculated by multiplying an asset's reference price by its circulating supply. A token priced at $2 with 50 million units circulating has a market cap of $100 million. The calculation estimates the value of that supply at the reference price; it does not total the money investors deposited. To understand a change in the ranking, examine both inputs and the provider's definitions. A larger number can result from price changes, supply changes, or revised reporting. Establish what the two inputs represent The arithmetic is simple, but neither input is self-explanatory. “Price” may be a reference assembled from selected trading pairs and venues, rather than the last transaction on the exchange you use. A provider may exclude observations or convert quote currencies. Two services can publish different estimates because their source selection and methods differ. Circulating supply is an estimate of units treated as available in the market under a provider's rules. It may differ from the number minted, the total recorded by a contract, or the maximum permitted under a protocol's current design. Locked balances, treasury allocations, burns, and scheduled releases require interpretation. A transparent methodology matters because identical arithmetic can still use ...
AI illustration of stacks of coins beside financial charts illustrating how cryptocurrency prices and circulating supply affect crypto market capitalization
November 11, 2026 | NCFA Fintech Market Insight | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Risk Compliance And Regtech Financial firms are putting AI agents into production well before giving them broad financial authority. That creates time to set identity, permissions and transaction controls before autonomous execution becomes common. On November 11, 2026, Bank of England Financial Policy Committee external member Jonathan Hall used his final FPC speech to examine what happens when AI agents get more authority inside financial firms. A Bank of England and FCA survey of 196 firms found that 80% already deploy AI agents and another 14% plan to within 12 months. Only 2% reported agents with broad autonomy, and none of those were in trading and payments. Finance is adopting agents quickly, but firms are still keeping people and hard limits around the decisions that can change money, positions or customer outcomes. AI Agents Are In Finance But They Are Not Trading Alone The 2026 Bank of England and FCA survey separates four levels of authority: Decision support lets an agent recommend an action while a person decides and executes it. Constrained execution lets the agent act inside preset rules. Conditional autonomy ...
AI illustration of AI agents connected across a financial trading network, representing shared market behaviour, trading automation and financial stability risk
November 10, 2026 | NCFA Fintech Market Insight | Capital Markets Infrastructure And Funding, Entrepreneurs Startups Small Businesses, Equity Crowdfunding And Alternative Funding A small group of large rounds is carrying Canadian venture totals while deal count and growth stage financing remain well below recent norms. On November 10, 2026, the Canadian Venture Capital and Private Equity Association published its Q3 2026 venture capital report. Canadian companies raised $4.3 billion across 397 deals through September, only 1% less capital than a year earlier. But 23 rounds of $50 million or more represented just 6% of disclosed deals and absorbed 58% of all venture capital invested. Deal count has also fallen every year since 2021. The national total is holding up far better than the number of companies getting financed. Six Big Rounds Carried 59% Of Q3 Venture Capital Q3 produced $1.35 billion across 129 deals. Capital was 1% higher than Q2, but deal count fell 15%. Six rounds above $50 million accounted for $793 million, or 59% of the quarter’s capital. That's a decent quarter for the companies that closed those rounds, but a weak quarter for everyone else. Mega rounds above $50 million totalled $2.5 billion across 23 transactions ...
AI Illustration of large venture capital deals dominating smaller financings, representing concentration in Canada’s VC market
November 11, 2026 | NCFA Story Intelligence | Competition And Market Structure, Wealthtech Investing And Trading, Regulation And Policy Canada is cutting bank fees and switching barriers after years of weak competition, high concentration and poor productivity. On November 7, 2026, the federal government proposed something Canadian investors have complained about for years. Banks would no longer be allowed to charge most investment account transfer fees, which typically cost about $150 per account. Ottawa also wants clearer transfer information and tighter timelines for moving investments to another financial institution. The fee matters because leaving can already be slow and frustrating. Receiving firms often reimburse the outgoing charge to win the account. That means a fee collected by the institution losing the customer can become part of the acquisition cost for the institution trying to win that customer. Canada's six largest banks hold roughly 93% of banking assets. The Competition Bureau was warning about barriers facing fintech competitors in 2017. Ottawa began reviewing open banking in 2018. A federal advisory committee later recommended an operating system by January 2023 and warned that government should not delay. January 2023 came and went. Real Time Rail also slipped years beyond its first expected ...
Digital illustration of Canada bank transfer fee reform showing easier investment account switching, lower fees, open banking, payment infrastructure and stronger financial competition
November 10, 2026 | NCFA Fintech Market Insight | Digital Assets Blockchain And Tokenization, Capital Markets Infrastructure And Funding, Regulation And Policy Funds, Collateral And Settlement Lead Canada’s Near Term Tokenization Opportunity On November 10, 2026, the Canadian Securities Administrators published its Project Tokenization Phase 1 findings, setting out where Canadian market participants see the strongest commercial opportunities for tokenization and what regulators plan to test next. The report draws on 233 organizations, 21 bilateral meetings and 80 survey responses, along with workshops attended by 281 people in Calgary and 491 in Toronto. Participants put investment funds, private assets, collateral, treasury and settlement infrastructure ahead of public stocks as the strongest near term opportunities. The report also cuts through one of tokenization’s biggest sales pitches. Blockchain can change how an asset is recorded, transferred or settled, but it doesn't automatically create liquidity, investor demand, broader eligibility or stronger ownership rights. Those outcomes still depend on the product, market, legal structure and infrastructure around it. The CSA now plans to take specific projects into Phase 2 through a 120 day public call for proposals. Firms may be able to use existing regulatory processes, tailored regulatory treatment or bounded testing in a ...
Digital illustration of tokenized financial assets, blockchain settlement and legal infrastructure, representing Canada's investment funds and collateral markets.
Nov 11, 2026 A positive work environment is key for any team that wants to succeed. Team morale is crucial for productivity, motivation, and job satisfaction. Engaging in activities that lift spirits and strengthen connections can lead to great results. Creating a positive team environment requires creativity, engagement, and some fun. Each activity can strengthen connections, boost motivation, and improve workplace dynamics. When teams focus on strategies to boost morale, they work toward shared success. These activities can lead to lasting memories and help build a stronger team culture. Here are some fun strategies to help improve your team's morale and make the workplace livelier. Fun at the Arcade Visiting an arcade spot is a great way to enjoy time together and build teamwork. Imagine your team facing challenges with various games. Whether it's racing or playing team games, the arcade encourages friendly competition and bonding. These fun experiences can help reduce stress and improve relationships among coworkers. Arcades offer many options to suit diverse interests and skill levels. The lively atmosphere invites everyone to relax and take a break from their daily tasks. Shared laughter and enjoyment can lead to better communication and teamwork when you return to the ...
Digital illustration of team building activities boosting workplace morale with coworkers playing games and laughing in a bright modern office


Global Fintech, Capital Markets and Financial Innovation Ecosystem

News, Market Intelligence and Innovation Across Fintech and Capital Formation

Stay informed with fintech and funding news, market intelligence, research, regulation, innovation, events and strategic industry developments from Canada and around the world. NCFA connects founders, investors, financial institutions, policymakers and technology leaders across the evolving financial innovation ecosystem.

NCFA Financial Innovation Map card showing a Canada network map and compass for exploring fintech opportunities.
NCFA Fintech Whisperer featuring weekly fintech intelligence, major developments, market signals, and operator focused analysis.
NCFA Financial Opportunity Briefs featuring evidence based innovation opportunities, market intelligence, strategic insights, and venture creation ideas.
NCFA Fintech Fridays Podcast featuring conversations with fintech founders, investors, innovators, and ecosystem leaders.
NCFA Fintech Insights card featuring research reports, data analysis, market intelligence, and evidence based fintech insights.
NCFA Open Banking and Consumer-Driven Finance Interactive Intelligence

This Week’s Top Fintech News, Insights & Market Intelligence

Stay current with the week’s most important fintech, capital markets and financial innovation developments from Canada and around the world. Our curated coverage tracks regulation, funding models, emerging technologies, market activity and strategic industry developments.

NCFA's Open Banking Thought Leadership Series

NCFA Open Banking in Canada, Senator Colin Deacon

FINTECH FRIDAYS Podcast

Tune into the world of fintech with NCFA Canada's Fintech Fridays podcast, your source for engaging conversations with global industry leaders. Spanning four seasons, this podcast series dives deep into the latest trends, insights, and transformations shaping the financial technology landscape.

Season 1 | Season 2 | Season 3 | Season 4

Explore Canada’s Fintech Ecosystem

FintechCanada.io is a comprehensive directory and free listing service dedicated to fostering the growth of Canadian fintechs. It aims to help these companies expand their services globally by connecting them with international investors, buyers, and partners.

NCFA Fintech Canada directory icons label

NCFA Canada logo

The National Crowdfunding & Fintech Association of Canada (NCFA Canada) is a global fintech and financial innovation ecosystem providing market intelligence, research, education, policy analysis, industry engagement and networking across Canada and international markets. NCFA covers the full financial innovation landscape, including fintech, capital markets, payments, banking, digital assets, artificial intelligence, regulation, infrastructure and emerging business models. Explore the Financial Innovation Map, subscribe to NCFA’s weekly fintech newsletter, or join NCFA.