




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Jan 30, 2026 | NCFA Fintech Market Activity | Funding and Ecosystem
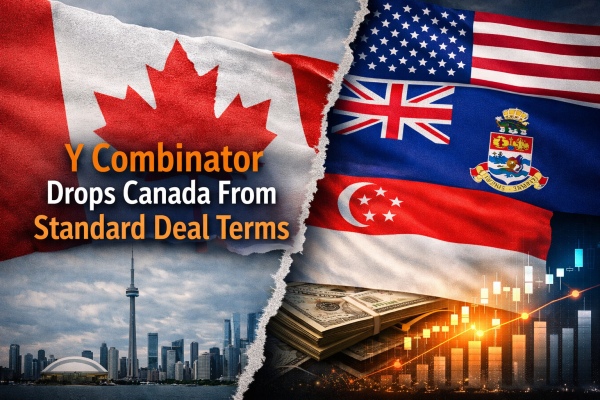
On January 26 2026, Y Combinator updated its standard deal terms to limit eligible investment jurisdictions to the United States, Cayman Islands, and Singapore. Canada no longer appears as a jurisdiction where YC will invest directly under its standard structure.
The financial terms remain unchanged. YC continues to offer $500,000 per company, split between $125,000 for a fixed 7% equity stake and $375,000 on an uncapped MFN SAFE. YC also states it can assist founders with incorporation if they have not yet formed a company.
The practical impact for Canada based founders is immediate. Teams can still apply to YC, but a Canadian incorporated startup must now establish a parent company in one of the eligible jurisdictions before YC completes the investment. That moves incorporation decisions forward in the startup lifecycle, often before product market fit or initial customer traction.
This matters because corporate structure is not a paperwork detail. It affects ownership control, intellectual property placement, option plans, investor rights, tax exposure, and the mechanics of future fundraising. What was once handled after a seed round now sits directly on the path to accelerator participation.
YC’s decision also highlights how early stage capital increasingly flows through standardized structures. Accelerators and seed funds optimize for speed and repeatability. When jurisdiction narrows, founders adapt by default, even if their teams, customers, and operations remain Canadian.
When access to top accelerators depends on jurisdiction first and execution second, how early should founders be forced to trade structural flexibility for capital velocity?
This is not a withdrawal from Canadian talent. It is a capital routing decision. But when global accelerators set the defaults, those defaults shape where companies incorporate, where value accrues, and how national ecosystems compete for long term upside.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jan 27, 2026 | NCFA Fintech Market Activity | Capital and Funding
Image: Freepik AI
On January 27 2026, CVCA and the Government of Canada’s Trade Commissioner Service released the 2026 edition of The 50, an annual guide that presents Canada’s venture capital market to international investors, strategic partners, and market participants.
The release makes two practical points that matter for founders and fund managers. First, The 50 does not rank firms. It profiles venture managers across sectors including software, applied artificial intelligence, life sciences, and advanced technologies. Second, it is built to travel. CVCA says the guide supports engagement through the Trade Commissioner Service global network spanning more than 160 cities worldwide.
That distribution detail is the real asset. Canadian venture often struggles with visibility outside the usual circles. A guide that is designed for outbound use changes how conversations start with foreign limited partners, corporate partners, and co investors. It also helps founders understand which managers actively shape the market today, not just who raised a big fund last cycle.
Brenda Hogan, Chief Investment Officer, Venture Ontario, and Chair, The 50 Committee:
“Canada’s venture market is defined by managers who combine discipline with the ability to support companies as they scale across markets. The firms included here reflect that reality. They are backing businesses that operate globally, manage capital carefully, and deliver outcomes investors can underwrite with confidence.”
If you want the working version, CVCA hosts the guide online. You can explore The 50 2026 edition directly.
The timing also ties into deal flow and capital conversations in 2026. CVCA notes that international investors and partners can engage with Canada’s private capital community at Invest Canada ’26, taking place May 26 to 28 2026 in Halifax, Nova Scotia.
If Canada wants more cross border capital and more late stage wins, what changes first, the number of global investor relationships, or the quality of proof points that keep them coming back?
This release is akin to market infrastructure for capital. When more global investors can quickly understand who deploys capital in Canada and how those managers operate, founders get more shots at the right conversations, earlier.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 30, 2026

Fintech is changing rapidly in Canada. The national shift toward an Account-to-Account (A2A) payment model has accelerated the adoption of new fintech start-ups like Loonio. Loonio is a specialized Payment Facilitator (PayFac) within the Interac ecosystem rather than a traditional card processor. It operates around three different verticals: ecommerce, Canadian iGaming, and most recently insurance.
While legacy gateways such as Gigadat Inc. also operate as Payment Facilitators using Pay-by-Bank technology, Loonio distinguishes itself by prioritizing automated "Request Money" protocols that (generally) eliminate the need for manual e-Transfer security questions. Their differentiating factor is their UX, simplicity, and speed benchmarks for both deposits and withdrawals. Loonio represents the evolution of Open Banking-ready gateways that prioritize real-time settlement and bank-grade encryption. All users need, practically speaking, is their online banking login to approve the transfers.
The rise of Loonio casinos itself reflects a broader change in how Canadian consumers interact with casino payment methods. With Web3, crypto options have flooded the market, forcing fiat options to catch up in terms of speed. However, fiat is slated to match cryptocurrencies with the upcoming Real-Time Rail (RTR) spearheaded by Interac Corp.
Even though RTR isn't currently live (still in the testing phase) and won't be integrated into casino cashiers for some time, Canadians have excellent Interac gateways at their disposal. Loonio-powered casinos, in particular, enable near-instant deposits through a streamlined UX. Withdrawals are typically processed within 24 hours, importantly without the need to share your own online banking data with the merchant.
The following Canadian online casinos have integrated Loonio’s gateway to offer real-time settlements for their users:
These platforms were chosen for their ability to process Loonio transactions at scale while staying compliant with both Ontario and Rest-of-Canada regulations.
The platforms listed above hold active licenses from the AGCO (Ontario) and the KGC (Rest of Canada). To ensure full transparency, their current registrations are listed below, and can be confirmed against official databases.
Loonio is still quite niche in the iGaming deposit space. Their coverage expanded from an initial small core of Super Partners brands (from the Super Group LTD), which currently counts 4 brands in Ontario and 13 in Rest of Canada.
New Loonio iGaming brands for the Rest of Canada (Ontario excluded) include Rooli, Playamo, Woo and Winmaker. This shows that Loonio is choosing a diversified approach by catering to casino sites with diverse licensing portfolios.
From a fintech perspective, Loonio's model represents a competitive alternative to both traditional payment processors and emerging crypto-based solutions. The platform abstracts KYC (Know Your Customer) automation, biometric bank authentication, and real-time liquidity management into a single API layer. For merchants in regulated environments, this reduces operational overhead while offering users a familiar banking interface.
One of the first things that adds to the popularity of Loonio is its speed. From our checks, we discovered that the processor’s speed is in line with typical Interac purchases and transactions. This means that your account top-ups are processed in almost real time, giving you instant access to deposits to play your favourite games. There may be random security checks, but even if these happen, it won’t delay the process by more than an hour.
For withdrawals, there are underlying factors that determine how fast you receive funds in your bank account. Canadian gambling regulations dictate that AML (Anti-money Laundering) verifications be carried out on all payouts. Regardless, Loonio withdrawals are highly competitive, typically clearing within 24 hours once authorized by the operator. It's important to note that many casinos use mixed Interac routing, meaning a different gateway may be utilized for deposits versus withdrawals.
The Loonio business model eliminates payment commissions for end users (in iGaming). Players simply enter the desired deposit or withdrawal amount without incurring transaction fees.
When it comes to transaction limits, the upper and lower ranges are determined by the individual operator rather than Loonio itself. For example, Gaming Club allows a minimum deposit of C$5 via the Interac® by Loonio option. Other casinos establish minimums of C$10, C$15, or even C$30 (in the case of Winmaker). The payout limits also vary from casino to casino, so it’s a great idea to check this information before requesting withdrawals.
A look through the Loonio.ca website shows that the payment service partners with over 100 banks and credit unions. With this level of penetration, there’s no denying that Loonio remains one of the most convenient online payment options.
Fortunately, you’ll find most of these banks listed on Loonio’s banking interface when you want to deposit or withdraw at online casinos in Canada. These are some of the banks that partner with Interac by Loonio:
This also includes the traditional "Big Five" Canadian institutions: Bank of Montreal (BMO), Royal Bank of Canada (RBC), Canadian Imperial Bank of Commerce (CIBC), Bank of Nova Scotia, and Toronto-Dominion Bank (TD).
Loonio represents a sophisticated evolution of the default Interac experience for iGaming users and operators alike. It shortens the payment flow through a faster, cleaner UX. Furthermore, the risk of traditional chargebacks is mitigated, as completed transactions are not reversible via Loonio (as per the loonio.ca FAQ page).
But Loonio isn’t the only fintech company that offers services in concert with Interac. So how does Loonio stack up against the competition?
One of the biggest names in this space is Interac-powered payments handled by Gigadat, which has been active since 2013. At the moment, Gigadat has a much larger market share than Loonio, since Loonio has only been in business since 2022. You’re more likely to run into Gigadat, and that alone may make it feel more versatile to many users who play across the iGaming industry.
However, Gigadat is showing its age a bit, as it can be a bit clunkier than Loonio, requiring more movement between various windows than the newer fintech solution. There are also recurring community reports online of delayed payments, likely a side effect of very high usage volumes and occasional backlogs. Still, this can make Gigadat slightly more intimidating for new users, while Loonio focuses on a simplified interaction between client, online banking, and iGaming sites.
Loonio still has ground to cover compared to Gigadat, and other e-transfer products like Payper, Inc. and PayDirectNow also hold a larger share of the Canadian online gambling market for deposits. But as the newer entrant, Loonio has been steadily cutting into the market share of these more established fintech options, and has clear room to grow thanks to its ease of use.
Both Gigadat and Loonio utilize Interac's established network, which features native security protocols. Gigadat, for instance, aligns its infrastructure with robust frameworks such as the NIST Cybersecurity Framework 2.0, which emphasizes a comprehensive approach across six core functions: Govern, Identify, Protect, Detect, Respond, and Recover.
Regarding bank coverage, Gigadat provides nationwide integration with Canada’s "Big 6" (RBC, BMO, TD, National Bank, Scotiabank, and CIBC) along with their extensive networks of credit unions. Both providers maintain "bank-grade" security, utilizing 256-bit encryption standards—the current benchmark for Canadian financial institutions—to protect sensitive transaction data. This ensures that while fintechs like Loonio add proprietary layers of UX and speed, the underlying movement of funds remains protected by the same encryption that secures the nation's primary banking systems.
References: NIST Cybersecurity Framework 2.0; Interac Corp. Security Protocols; Canadian Centre for Cyber Security (CCCS) Cryptography Standards.
As the Canadian landscape shifts toward more agile payment solutions, Loonio is carving out a significant niche. Its path to becoming a dominant player is not without competition, however. As we've already mentioned, there are a variety of more established products in iGaming payment processing, even if they all leverage the same Interac system. There’s also the potential that as the online gambling market matures, regulatory and legislative changes (with Alberta upcoming) could have unforeseen consequences for Loonio or its competitors. However in the Ontario region, where iGaming is already legal and regulated, there should be minimal volatility.
And Loonio is well positioned to withstand such challenges. In jurisdictions worldwide that have clamped down on payment processors, it is typically those dealing with debt – namely, credit cards and their processors – that have been limited or shut down by regulators. Loonio works completely within the Canadian banking system (via the Payments Canada network) and can’t be used without existing funds, avoiding that pitfall. This goes for most Interac online casinos as well. Payment disputes are inherently low within this framework. And as more provinces and territories regulate iGaming, legitimate, established fintech companies like Loonio will be first in line as banking solutions in those regions.
With a faster payment journey and bank-grade security, Loonio is one of the most efficient payment options available to the Canadian iGaming industry today. This efficiency has encouraged a growing number of sites to integrate the gateway, including major brands like Baytree and Cadtree (Super Group).
That’s a trend that’s likely to continue over the coming months and years. The association with Interac and Canada’s most trusted banking institutions has Loonio in a strong position to continue gaining adoption at online casinos, either alongside or in place of competing options. While there’s a long way to go for this fintech innovator, Loonio has the potential to become a dominant player in the iGaming payments field – especially if competitors don’t adapt to the areas in which it is already superior to them.
The processing speed advantage (due to its UX) has made Loonio a preferred integration for operators seeking to improve customer satisfaction while maintaining compliance with FINTRAC and iGaming Ontario (iGO) standards.
Online gambling should be enjoyed responsibly as a form of entertainment, and never as a way to solve financial problems or eliminate debts.
Players must be at least 18 or 19 years old to gamble online in Canada (19+ in Ontario). If you or someone you know is struggling with problem gambling, free and confidential support is available through these resources
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Startups and Talent | Jan 28, 2026
On January 21, 2026, CTV News reported that a fintech startup built in Canada, Internet Backyard, reached an approx. valuation of $35 million in Canada but ended up relocating to the United States. The story drew attention because the venture succeeded here but still chose to leave after proving product market fit.
The founders included a recently graduated international student from Vietnam and her co-founder from Brazil.
The founders built the product in Canada, validated demand, hired talent, and reached scale. After that proof point, they made the decision to move the business south.
The founders cited two main reasons for leaving: access to growth capital and visa limitations. Those challenges aren't unique and reflect structural gaps that continue to impact where ambitious companies choose to grow.
While Canada's become a strong place to attract global founders, students, and early stage builders. The challenge emerges later, when companies move from validation to rapid expansion and require larger capital rounds, senior leadership mobility, and operational certainty. In those moments, founders tend to optimize for speed and certainty rather than geography.
Canada’s venture capital environment continues to constrain companies at the growth stage. According to data cited by RBCx, Canadian venture capital firms raised just over $2 billion in new capital in 2025. That level sits well below longer term averages and reflects a market dominated by a small number of large funds.
The same data shows that emerging fund managers raise only about $249 million of that total. The top five funds account for roughly 83% of all capital raised, concentrating decision making power among a small group of investors. This concentration reduces the number of domestic lead investors capable of supporting large follow on rounds. For founders approaching Series B or later, this structure often results in slower fundraising cycles, fewer competitive term sheets, and increased pressure to secure capital outside Canada.
Fundraising constraints also impact capital allocation. Through the first nine months of 2025, total venture capital investment in Canadian companies reached approximately $4.9 billion across 386 deals, compared with about $8.6 billion invested across all of 2024, based on aggregated industry reporting referenced by RBCx.
The conditions make capital availability less predictable at the exact moment companies need speed and certainty. When companies are ready to scale, relocation is increasingly becoming a rational operational decision based on their confidence in the domestic ecosystem, not a reflection of founder loyalty.
Capital isn't the only factor. Immigration and founder mobility also impact the decision where founders choose to scale.
Canada’s Start Up Visa program aims to attract global entrepreneurs and support company building inside Canada. In practice, the program faces processing delays and capacity strain. The federal government now applies application caps and limits new intake while it works toward program changes expected to take effect in 2026, according to Immigration, Refugees and Citizenship Canada.
For founders already operating a growing company, these conditions create uncertainty. Delays and intake limits complicate executive mobility, cross border hiring, and decisions about where senior leadership can legally and reliably operate.
By comparison, the United States offers more established founder and talent pathways, including O-1 and H-1B visas, that companies can pursue once growth accelerates. For teams making time sensitive scaling decisions, visa predictability can be a competitive advantage. Having said that, the US administration has introduced new fees which could adversely affect the program.
When companies leave after proving traction, Canada loses future job creation, downstream investment, and the chance to build repeat founders who recycle experience and capital into the next generation of startups.
The solution is to close the gap between early success and long term scale (reducing top founder frictions). It requires coordinated progress on growth capital availability, immigration execution, and speed of decision making. Until those pieces align, Canada will continue to function as a strong launch environment but a weaker destination for companies once they reach global scale.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 27, 2026 | NCFA Fintech Market Activity | Payments and Market Infrastructure
Image: Freepik
On January 27 2026, Payments Canada confirmed the admission of five new payment service provider members, expanding direct access to Canada’s core payments infrastructure. The new members are Wise Payments Canada, Float, KOHO, Paramount Commerce, and Brim Financial.
The update matters because Payments Canada membership is a structural gate into clearing, settlement, and rule participation. In practice, it determines which fintechs can connect more directly to payment rails instead of relying entirely on sponsor banks.
Payments Canada states that its systems clear and settle more than $411B in transactions every business day. Direct participation changes how PSPs manage cost, reliability, product design, and compliance as transaction volumes scale.
The five firms admitted represent different operating models inside the Canadian fintech market.
1. Wise Payments Canada brings cross-border money movement and FX infrastructure.
2. Float focuses on spend management and corporate cards for businesses.
3. KOHO operates in consumer finance with prepaid and budgeting products.
4. Paramount Commerce provides payment processing and orchestration services.
5. Brim Financial combines card issuing with embedded loyalty and digital banking infrastructure.
Membership also arrives during Canada’s ongoing payments reform cycle. PSPs are integrating with the Retail Payment Activities Act supervisory framework while also positioning for broader access to faster payments and data enabled services. Direct participation reduces dependency on intermediaries at the same time regulatory accountability increases.
As more PSPs gain direct access to payment rails, does competition shift toward pricing and features, or toward operational reliability and compliance execution?
The admission of five new PSPs in a single update shows Payments Canada steadily widening the circle of direct participants. The next test is whether this access translates into faster product launches, lower costs, or clearer accountability for end users as Canada’s payments system modernizes.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech Financing | Jan 27, 2026

Image: Freepik/rawpixel.com
On January 26 2026, Toronto-based Fintech Float Financial announced $100M in debt financing to expand its business finance for Canadian small to medium sized companies. The release says the debt facility is provided by Silicon Valley Bank, which is now part of First Citizens Bank (a tier one Canadian bank), supporting its business accounts and working capital products and could unlock more than $1.5B in annualized spending power for small and medium sized enterprises.
Float confirms the financing supports two core offerings. The first is its business accounts product, which advertises interest rates of up to 4% on balances and a base rate increase from 2% to 3% across all customers. The second is Float Charge, a short term working capital product designed to provide flexible financing to businesses that don't always fit traditional bank lending models.
Float reports that more than 6,000 Canadian businesses now use its platform across technology, professional services, hospitality, retail, and non-profit sectors. Many of these companies manage fragmented banking tools, slow credit decisions, and cash balances that earn little return. Float positions its platform as a way to bring payments, expenses, cash management, and short term credit together in a single operating layer.
The $100M consists entirely of debt facilities (not equity capital) and expands Float’s balance sheet capacity, allowing it to fund customer deposits and extend working capital without diluting ownership.
Under this model, growth depends less on valuation milestones and more on execution. Underwriting discipline, funding costs, and credit performance determine how effectively this capital translates into sustainable product usage. Balance sheet financing accelerates expansion, but it also tightens the link between growth and risk management.
The participation of Silicon Valley Bank and a tier one Canadian bank suggests institutional comfort with Float’s underwriting approach, controls, and operating maturity. Rather than competing head on for SME relationships, banks increasingly deploy capital through fintech platforms that already sit inside day to day business workflows.
This arrangement allows banks to extend reach while fintechs handle product design, customer experience, and ongoing engagement. As scale increases, performance expectations rise with it, especially around credit quality and liquidity management.
Float’s financing shows how non-bank platforms continue to move closer to the centre of SME finance by bundling yield, payments, and short term credit into a single product stack. It's an offering aimed at helping many Canadian businesses experiencing common friction around fragmented tools, slow access to credit, and idle cash.
This development also feeds into competition and regulatory context for SME finance in Canada. NCFA recently published an article discussing Why SME loan competition in Canada is under review, with outcomes potentially affecting how both traditional banks and fintechs serve business customers; that review underscores why innovations in working capital and deposit products matter now. Float’s latest financing and product expansion follows its $70M Series B that aimed to innovate business finance and boost investor confidence in alternative SME credit models.
This financing also comes against a backdrop where Canadian regulators previously took action on the Canadian branch of Silicon Valley Bank to protect creditors and facilitate an orderly transition after wider SVB distress and evolving regulatory oversight for cross-border banking and fintech collaboration.
If Float maintains credit performance and continues to win primary business relationships, this model could gain traction in how some SMEs manage deposits and working capital. If losses rise or growth slows, balance sheet leverage can quickly become a constraint too.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jan 26, 2026 | NCFA Fintech Market Activity | Digital Assets and Investment Products
Image: Freepik/Rawpixel.com
On January 8 2026, Coincheck Group announced an agreement to acquire approx 97% beneficial ownership of 3iQ, a digital asset investment manager based in Ontario, Canada.
The release values 3iQ at USD 111,840,476 and sets Coincheck Group’s share value at USD 4.00 per ordinary share for the exchange. Coincheck Group plans to issue 27,149,684 new ordinary shares to Monex Group for its stake, and it also plans to offer similar terms to minority shareholders. That offer could take Coincheck Group to 100% beneficial ownership.
Coincheck Group expects closing in the second calendar quarter of 2026 and ties it to regulatory approvals and due diligence conditions. The deal also sits inside a wider expansion effort that includes prior acquisitions the release lists in France and in staking infrastructure.
3iQ brings a Canadian anchored track record in regulated digital asset products. The release says 3iQ was the first regulated digital asset investment fund manager in Canada in 2017 and launched major exchange listed Bitcoin and Ether funds on the Toronto Stock Exchange in 2020. It also lists product milestones that include QMAP in 2023, an Ethereum staking ETF and Ether staking ETP in 2023, and Solana staking and spot based XRP ETF launches in 2025.
This matters because it connects two different strengths. Coincheck brings a large exchange and retail distribution base in Japan. 3iQ brings regulated product structuring and an institutional grade shelf that already fits inside traditional investment accounts. Put together, the combined platform can push deeper into the part of the market where banks, advisors, and asset managers want compliant exposure, not just spot trading.
Gary A Simanson, CEO and Executive Director of Coincheck Group:
“We expect that 3iQ will bring to Coincheck Group proven innovation, expertise and institutional product offerings and infrastructure recognized in the digital asset investment management space. By combining our strengths, we believe we will be better positioned to meet the needs of institutional and sophisticated investors and firms, including traditional financial institutions now seeking to include digital assets in their portfolio offerings to their customers. We also anticipate that the acquisition will be accretive to our earnings.”
Regulated digital asset products keep moving closer to traditional investment plumbing. When more firms offer staking and ETF wrappers, what becomes the real differentiator, product design, distribution, or governance?
Related Stories
Tokenized infrastructure is changing how markets operate
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016