




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


January 23, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Artificial Intelligence And Data, Payments And Money Movement, Digital Assets Blockchain And Tokenization, Open Banking Open Finance And Data Sharing, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026)
This lands in the middle of a problem every operator knows. AI stops being a feature once it touches credit, pricing, advice, fraud decisions, or customer outcomes. Buyers and supervisors ask one thing first. Can you prove how it behaves, who owns the decision, and what happens when it fails. Founders who build strong logs, clear accountability, and testable controls keep momentum when scrutiny rises. Investors should back teams that can ship AI inside regulated environments without betting on fuzzy governance.
Travel payments stay messy because suppliers, currencies, fraud controls, and reconciliation collide in one workflow. When a travel platform embeds issuing plus FX plus collections, it turns payments into a default layer that buyers adopt without a separate vendor decision. Fintechs that sell cards, FX, or payables into travel win faster when they integrate into the platforms that already control inventory and supplier routing, and when they ship audit ready controls that finance teams can trust at scale.
Private bank adoption changes buyer expectations fast. Once a top tier wealth manager treats crypto as an investable asset inside the core private bank, every crypto vendor selling into wealth has to meet private bank standards on suitability, controls, reporting, and operational discipline. Founders that sell custody, execution, portfolio reporting, or risk tooling should expect tougher diligence and longer lists of required evidence. Investors should watch for picks and shovels that fit inside existing wealth compliance rather than products that need new rules to work.
Cross border CBDC linkage puts sovereign governed interoperability back on the table as an operating roadmap. Fintechs that sell wallets, settlement tooling, compliance rails, and treasury workflows should plan for rule dense governance, shared operating standards, and audit grade traceability that can survive multi jurisdiction scrutiny.
A serious push for a US banking licence tells the market Revolut wants durable US distribution, not a light footprint. Once a global fintech commits to supervised rails in the United States, competitors face a tighter clock on product depth, compliance maturity, and funding strategy. Founders that sell infrastructure into banks and fintechs should expect more demand for audit ready controls, clean reporting, and resilient operations that hold up under US supervision.
Public markets put custody under a harsher light than private capital. Reporting cadence, risk controls, and operational proof start becoming the product. Founders selling into custody, compliance, and settlement stacks should expect tighter vendor scrutiny and cleaner evidence demands. Investors can treat this as a live benchmark for how the market values regulated digital asset infrastructure once it sits in plain view.
This deal pulls a modern fintech spend platform directly inside a large US bank instead of leaving it at the partnership layer. Once a bank owns the full card, payments, and spend stack, pricing pressure increases and distribution advantages compound fast. Founders building expense management, treasury, or commercial card tooling should expect tougher competition from vertically integrated banks. Investors should treat this as another signal that late stage fintech exits increasingly come through acquisition by incumbents that want product control, not just vendor relationships.
Tokenization stops looking like a side experiment once a core exchange puts its matching engine and brand behind it. The winners don't come from who talks loudest about crypto. The winners come from who can run clean market structure under supervision, with settlement, custody, funding, and controls that broker dealers and clearing members can defend. Founders building post trade, custody, reconciliation, collateral, and stablecoin treasury tooling should treat this as a buyer signal. Regulated infrastructure buyers want fewer moving parts, stronger audit trails, and reliable operating hours that match global capital flows.
Data modernization rarely feels exciting until it hits production. When a supervisor modernizes filing rails, every regulated team ends up rewriting workflows, data mapping, controls, and audit evidence. Fintechs that sell reporting, data, regtech, or infrastructure should treat this as a near term buying trigger. Institutions will pick vendors that reduce change risk and make compliance proof simple, not vendors that add another layer of complexity.
Charter expansion at scale. When a global fintech pursues full licenses market by market, it raises the competitive bar on compliance execution, local product depth, and funding strategy. Competitors feel pressure through faster distribution, tighter pricing room, and regulators expecting stronger controls across the category.
The firms that win are the ones that control where money moves and can prove they run a tight and compliant shop. Payments and treasury are getting built into the software people already live in, not sold as a separate product. Big fintechs keep chasing full licenses so they can offer more, price tighter, and rely less on partners. Governments keep pushing cross border settlement ideas that bring more rules, more reporting, and more scrutiny.
Founders should treat three things as product work. First, build evidence into the workflow so every action leaves a trace you can explain. Second, design for partner and regulator questions before they show up, not after. Third, sell into distribution points that already own the customer and the switching moment, because that's where adoption actually happens. Investors can use the same filter. Back teams that reduce operating risk while keeping shipping speed. Avoid models that need regulatory fog, fragile partners, or perfect market timing. The upside concentrates in infrastructure and platforms that buyers can trust at scale.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
January 23, 2026

Choosing the right display for your PC can significantly impact your productivity, entertainment experience, and overall satisfaction. Two of the most popular options available today are projectors and monitors. Each has its advantages and drawbacks, and the best choice ultimately depends on your specific needs, environment, and usage patterns. In this comprehensive comparison, we break down the key differences between projectors and monitors to help you decide which is the ideal choice for your PC setup.
On the other hand, if you are on the hunt for a platform wherein you can play card games, be sure to visit GameZone Pinoy games.
A projector is a device that casts a visual image onto a large surface, typically a wall or projection screen. Projectors vary in size, resolution, brightness, and price, but all share the basic function of turning a flat surface into a large display area. Projectors are widely used in home theaters, business presentations, and classrooms.
Projectors typically connect to a PC via HDMI, USB-C, or wireless display adapters. Modern projectors can deliver high definition (HD) and 4K resolution and even support HDR content.
A monitor is a dedicated display screen designed to show visuals with clarity and precision. Monitors come in various sizes, resolutions, refresh rates, and panel types such as IPS, TN, and VA. They are the standard display for desktops, laptops, and gaming PCs.
Unlike projectors, monitors have built-in screens with consistent brightness levels, reliable color accuracy, and support for fast refresh rates that benefit gaming and professional work.
When evaluating whether to buy a projector or a monitor for your PC, it helps to compare them across several essential criteria:
Projector
The most obvious advantage of a projector is its ability to produce a large image. Depending on the model and throw distance, you can create a display that ranges from 60 inches up to 150 inches or more. This makes projectors ideal for home cinema, group presentations, and immersive media consumption.
However, the viewing quality heavily depends on the projection surface and ambient light conditions. A darker room and a dedicated projection screen will deliver the best results.
Monitor
Monitors offer precise, consistent image quality at fixed sizes, typically between 21 inches and 49 inches for consumer displays. While they cannot match the sheer size of a projector image, monitors provide sharp visuals ideal for close-up work like graphic design, spreadsheets, and gaming.
Monitors are also easier to position and use without worrying about distance or external light sources.
Projector
Projectors have come a long way in image quality. Modern units support Full HD (1080p) and 4K resolution, and some models offer enhanced color and contrast. However, due to projection optics and surface limitations, projectors may not deliver the same sharpness and detail as monitors of similar resolution.
Brightness is another concern. Measured in lumens, projector brightness affects how well the image holds up in well-lit environments. Unless you choose a high-lumens model, bright rooms can wash out the projected image.
Monitor
Monitors generally deliver superior image clarity and crispness at similar resolutions. Because they generate their own light, monitors perform well in any lighting condition and maintain consistent brightness. This makes them ideal for tasks where accurate visuals matter, such as photo editing or video production.
High-end monitors can also offer professional color accuracy with wide color gamut support (sRGB, Adobe RGB, DCI-P3), which is crucial for creative professionals.
Projector
Projectors require more setup consideration. You’ll need space for the projector, a flat wall or screen, and sufficient throw distance to achieve the desired screen size. Mounting options include ceiling mounts or placing the projector on a desk or shelf.
Cables may need to be routed carefully, and you might need additional accessories like speakers if the projector’s built-in audio is insufficient.
Monitor
Monitors are generally plug-and-play. They fit well on desks, require minimal setup, and have straightforward cable connections (HDMI, DisplayPort, USB-C). Monitors also take up less physical space and don’t require external screens or darkened rooms.
Projector
Projectors are not typically designed for performance-intensive tasks like gaming or professional productivity. Input lag, refresh rates, and response times tend to lag behind monitors. While some projectors improve these specs, they still cannot match gaming monitors with high refresh rates (144 Hz, 240 Hz) or low response times (1 ms).
For presentations, multimedia, and casual gaming, projectors can perform well, but competitive gaming or fast-paced tasks may suffer.
Monitor
Monitors excel in performance applications. Gaming monitors offer high refresh rates and adaptive sync technologies like FreeSync and G-SYNC, which reduce screen tearing and improve visual smoothness. Productivity monitors often include ergonomic stands, multiple ports, and split-screen software support.
If you rely on your PC for work, creative projects, or gaming sessions, a monitor is usually the better choice.
Projector
Projectors can vary widely in price. Budget models may start under $300, while high-end 4K cinema projectors can exceed $2,000. Remember that projectors may also require additional expenses such as a screen, mounting hardware, and external speakers.
Projectors offer excellent value if your priority is a large display experience in a dedicated media room.
Monitor
Monitors also vary in price, from affordable options under $150 to professional-grade displays over $1,000. For the average user, a mid-range monitor (1080p or 1440p) offers excellent performance for both work and play.
Monitors tend to deliver better overall value for everyday PC tasks due to their simplicity and versatility.
When deciding between a projector and a monitor for your PC, your choice should match your primary use case. A projector can transform your space into a home theater and deliver an impressive screen size for shared viewing. A monitor, on the other hand, delivers superior clarity, performance, and ease of use for daily computing tasks, gaming, and professional work.
Before purchasing, consider your room size, lighting conditions, budget, and how you intend to use your PC. By aligning these factors with the strengths of each display type, you can make an informed decision that enhances your computing experience.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fundraising | Jan 22, 2026
Image: RBCx Capital Under Pressure Canadian VC Fundraising Report 2025
In January 2026, RBCx released the Capital Under Pressure report on Canadian VC fundraising in 2025 (42 page PDF), with data analysis that examines how capital flows from investors into Canadian venture funds, and how those fundraising dynamics affect fund sizes, investor concentration, and the amount of capital available for new investments in founders.
The report shows Canadian VC firms raised just over $2.1B in 2025. This level sits well below the long term average of roughly $3.1B and places 2025 among the weakest fundraising years since 2016. A brief rebound in 2024 did not continue, indicating sustained pressure rather than a short term disruption.
Even with lower fundraising totals, 21 new venture funds completed their fundraising process in 2025. In plain terms, these funds finished raising investor commitments and became active for investing. The data shows that while total capital declined sharply, the number of new funds coming to market remained relatively steady with the adjustment occurring through smaller fund sizes rather than fewer funds being formed.
Capital concentration increased materially in 2025. The five largest Canadian venture funds captured 83% of all capital raised during the year, the highest level recorded in the dataset. This reflects investor behaviour in lower liquidity environments, where commitments concentrate around established managers rather than being spread across a broader range of funds.
Emerging managers raised $249M in 2025, the lowest annual total recorded in the report. In contrast, established managers accounted for the majority of new capital raised. The data shows fewer new and early stage funds accessing capital, narrowing the range of investors available to back companies at the earliest stages.
Reliance on federal capital programs has declined but remains significant. Capital linked to VCAP and VCCI accounted for 36% of total Canadian VC fundraising in 2025, down from 53% in 2015. While the share has fallen, government backed capital continues to anchor a meaningful portion of venture fundraising activity.
The composition of available capital shifted materially in 2025. Only 42% of remaining dry powder is available for new investments, with the majority reserved for follow on funding in existing portfolio companies. This is the lowest share of initial investment capital recorded and directly limits the amount of domestic venture capital available for new company formation.
Fund size compression accelerated in 2025. The median Canadian VC fund size declined to $29M, while the top quartile fell to $43M. Both figures represent the lowest levels observed since 2013, confirming that less capital is available per fund even as fund formation continues.
With less venture capital raised overall, higher concentration among a small number of large funds, and only 42% of remaining dry powder available for new investments, fintech founders should expect slower fundraising processes, narrower investor funnels, and higher expectations around proof of traction. In practical terms, this environment favours companies that can demonstrate clear revenue quality, customer retention, regulatory readiness, and capital efficiency earlier than in prior cycles.
In a climate where traditional VC funding is contracting, fintechs benefit from widening their capital strategy beyond venture capital alone. Non-dilutive programs that support technical development and commercialization, such as Eurostars international R&D collaboration programs, can extend runway without ownership dilution when equity capital is scarce. At the same time, alternative finance models, including equity crowdfunding, can provide more aligned and patient capital from users, customers, and sector participants when institutional funds slow initial investments.
These approaches do not replace venture capital, but they can strengthen balance sheets, validate market demand, and reduce dependency on a single capital source at a time when venture capital is increasingly selective.
For fintech founders, the takeaway is not to pause growth plans but to adapt capital strategies to the realities of the market. Stronger evidence, clearer execution, and diversified funding paths matter more than ever. Companies that treat capital raising as a multi channel strategy rather than a single event will be better positioned to navigate this cycle and remain competitive as conditions evolve.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Global R&D Funding Program | January 22, 2026
Image: Freepik
The Eurostars Call 10 is a live international R&D funding program open to small-and-medium-sized enterprises in participating countries, with applications due March 19, 2026. Described by the National Research Council of Canada as the world’s largest international R&D funding program for SMEs, Eurostars focuses on collaborative projects that lead to commercialization. Canadian SMEs can participate and receive advisory services and non-dilutive funding through NRC IRAP when collaborating with eligible partners abroad.
For Canadian fintech companies, this creates an opportunity to collaborate internationally on core technology development while keeping operations and control in Canada. The key question is not whether fintech qualifies as a category, but whether a specific project involves building technical solutions that cannot be resolved with routine engineering and fits the program’s collaboration and commercialization requirements.
The focus is practical. Build new technology, solve real technical problems, and bring the results to market. The program operates under the European Partnership on Innovative SMEs and is co-funded through Horizon Europe, with each country supporting its own participants under national rules.
Eurostars is sector neutral. It supports companies developing new technology through structured R&D and doesn't fund general business expansion or product launches on their own. Eligibility depends on whether the project involves real R&D effort, not on how the company or sector is labeled.
For Canadian companies, NRC IRAP provides advisory services and funding support under Canadian eligibility rules.
Fintech projects tend to fit when teams are building technology rather than assembling existing components. Projects may qualify when they involve developing technical solutions around performance, security, scalability, or governance that go beyond standard implementation.
This can include new payment or settlement infrastructure, fraud or risk systems that require experimentation to reach acceptable accuracy, secure identity or data architectures, or AI driven financial systems where existing approaches fall short. In each case, R&D must be central to whether the project succeeds.
In practice, fintech work that focuses mainly on integrating existing platforms, launching commercial products using off the shelf systems, or scaling operations without new technology development usually falls outside scope.
Canadian SMEs seeking funding through Eurostars must be NRC IRAP clients and meet both Eurostars and Canadian eligibility requirements. At a minimum, companies must be incorporated and profit-oriented in Canada, have 500 or fewer full time equivalent employees, and have been operating for at least 12 months. By the NRC IRAP registration deadline, companies must also have at least five full time equivalent employees on Canadian payroll.
Applicants must demonstrate the financial and operational capacity to carry out a multi year international R&D collaboration while maintaining regular operations, along with a credible plan to commercialize the results in global markets. For Canadian participants, NRC IRAP funding is capped at $500,000 CAD per project over a maximum duration of 36 months.
Full eligibility rules and call requirements are outlined on the official Eurostars Call March 2026 program page.
An official Eurostars information webinar for applicants takes place on January 22, 2026 and will be recorded.
Canadian SMEs must be eligible for support through NRC's Industrial Research Assistance Program. Canadian firms that are not yet NRC IRAP clients must complete registration by February 17, 2026. Contact 1-877-994-4727
Canadian SMEs that are already registered with NRC IRAP, or that have confirmed eligibility with an NRC IRAP advisor, must submit their registration of interest and application for the Eurostars call through the NRC IRAP international expression of interest form.
The Eurostars application deadline is March 19, 2026 at 2 pm CET.
Eurostars gives Canadian fintech companies a structured way to collaborate internationally on R&D while accessing non-dilutive funding through NRC IRAP, without relocating operations or shifting governance outside Canada. Canadian participants work with European partners to build technology with global commercial potential while remaining funded under Canadian rules.
For fintech teams with global ambitions, Eurostars can help turn locally built innovation into internationally relevant technology. The program looks at what is actually being built. Companies that understand this distinction early save time and approach the opportunity with realistic expectations.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 21, 2026 | Report Insights
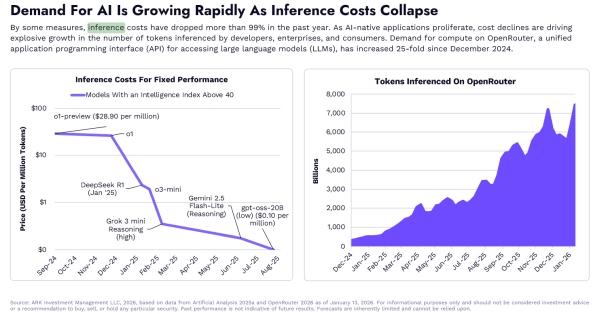
Image: ARK Invest, Big Ideas 2026 report. AI inference cost data reproduced for commentary and analysis.
In January 2026, ARK Invest released its annual research report Big Ideas 2026, building on trends first measured in Big Ideas 2025. The 111 page report spans artificial intelligence, tokenized assets, decentralized finance, Bitcoin, consumer AI platforms, and what ARK describes as the Great Acceleration. Rather than summarizing each theme in isolation, this article focuses on how these technologies accelerate change together inside financial systems.
What felt experimental in 2024 and operationally strained in 2025 now shows up as baseline reality in 2026. AI costs collapse, investment capital concentrates in infrastructure, digital assets move closer to settlement rails, and consumer AI platforms compress decision cycles. These forces do not arrive sequentially. They compound. The result is technically a financial system that no longer needs to pause between decisions.
ARK’s data on collapsing AI inference costs explains why this shift becomes unavoidable. At the same time, investment capital continues to concentrate in infrastructure designed for continuous operation. Together, these forces change how money moves, settles, and gets controlled.
Finance is AI-native by design. It already runs on software, explicit rules, and constant feedback. As AI becomes cheap enough to run continuously, software acts directly inside financial systems instead of waiting for human input.
ARK’s Big Ideas 2026 research shows AI inference costs dropped more than 99% in the past year. That single data point explains why continuous operation becomes economically viable at scale for the first time.
When inference costs fall that far, AI stops being something teams consult occasionally. It becomes something that runs all the time. Human prompts, batch reviews, and periodic decision cycles turn into friction rather than safeguards.
In financial systems, this breaks a long standing boundary. AI no longer stops at scoring, forecasting, or recommendations. It initiates actions. Payment routing adjusts automatically. Exposure limits rebalance in real time. Liquidity thresholds enforce themselves continuously. Software no longer waits for approval at every step.
Founders experience this when systems stay busy all the time instead of spiking occasionally. Investors see it when infrastructure costs stop falling as predictably even while revenue continues to grow. Operating leverage behaves differently because systems no longer rest between decisions.
ARK’s capital analysis shows where investment capital flows as systems scale. In 2025, annual investment in data center systems reached roughly $500B, nearly 2.5 times the long term average from 2012 through 2023. Since the ChatGPT moment, ARK shows growth accelerating from about 5% to 29% annually. The report projects this category of investment could approach $1.4T by the end of the decade.
That level of spending signals where long term value accrues. Capital is not chasing surface automation features. It is concentrating where compute, data availability, uptime, and recovery determine whether systems can operate continuously without failure.
For fintech teams, this breaks a familiar assumption. Products designed for occasional use face redesign pressure. Infrastructure built for constant operation gains structural leverage. Cost structure, resilience, and throughput now shape competitive advantage more than feature differentiation.
Traditional payment systems assume a person initiates the transaction. AI breaks that assumption. Software now initiates payments, manages balances, and settles obligations automatically as conditions change.
This pushes pressure into liquidity management, fraud controls, and settlement logic. Batch review fails quietly when systems never pause. ARK’s analysis of AI driven transaction flows emphasizes sustained throughput and recovery under stress rather than peak performance.
Founders building payment infrastructure encounter this pressure early. Systems designed for bursts now operate under constant load, and cost curves change accordingly. Reliability becomes a competitive feature rather than an operational afterthought.
ARK’s 2026 research frames consumer AI as an operating layer rather than a feature. AI models converge into a consumer operating system, and adoption accelerates faster than earlier digital platforms. As these systems take on purchasing, allocation, and coordination tasks, decision making shifts closer to software execution.
Wallets evolve alongside this change. They function less as interfaces and more as control layers for software driven financial activity. Identity, permissions, and payment logic compress into the same layer.
Investors familiar with earlier platform cycles recognize this pattern. Control consolidates where decisions execute, not where they are merely displayed.
ARK frames tokenized assets as market infrastructure moving trillions of dollars in asset value onto blockchains. Tokenization matters because assets move and settle automatically. DeFi matters because financial rules run on software without manual steps.
ARK’s data shows digital asset application revenue reaches roughly $3.8B in 2025, with around one fifth generated in January alone. The report also notes that about 70 applications generate more than $1M each in monthly recurring revenue. Value capture shifts from base networks toward platforms that control execution, coordination, and user interaction.
For fintech builders, this exposes a structural mismatch. Systems designed for batch reconciliation struggle when assets move continuously.
ARK’s research treats stablecoins as payment and settlement rails, not alternative products. Transaction activity reaches record levels because stablecoins can now move value automatically and clear obligations without waiting for manual steps.
Bitcoin functions as a monetary network with predictable issuance and global settlement. In 2026, its relevance aligns with the same requirement driving stablecoin use. When systems run continuously, money must move at software speed.
This doesn't remove banks, payment firms, or regulators. It changes how settlement works underneath them, reflected in Canada’s Stablecoin Act draft, which outlines how programmable settlement rails are governed.
ARK's analysis points to convergence. Continuous systems expose the limits of oversight built around delayed reporting and human initiated workflows. Design, auditability, and real time visibility matter more because systems no longer pause between decisions.
For policymakers, this changes where effective oversight begins. Rules written for periodic review struggle when financial activity runs continuously. Payments oversight, digital asset policy, and AI governance increasingly overlap because the systems themselves overlap.
Teams that design for transparency and control early reduce downstream risk. Regulators that focus on system behaviour rather than product labels gain clearer visibility and fewer surprises.
Big Ideas 2026 highlights what happens when AI inference costs collapse by more than 99%, investment capital concentrates at unprecedented scale, digital assets mature into settlement rails, and consumer AI platforms compress decision cycles at the same time. Finance changes faster because it already runs on rules, incentives, and software.
AI systems now run continuously. Many teams still model for peak usage instead of sustained operation. The gap appears in compute, monitoring, compliance operations, and incident response long before it shows up in customer metrics.
Infrastructure intensity rises faster than application revenue. ARK’s capital data shows control and throughput capture value before features do. Margins do not scale linearly during infrastructure transitions.
Human initiated workflows. Cost per transaction and average response time lose meaning when systems never pause. Sustained throughput and recovery time under stress become the binding constraints.
Frameworks assume discrete events. Continuous systems blur those boundaries. Risk appears as operational mismatch rather than enforcement action.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Canada | January 20, 2026
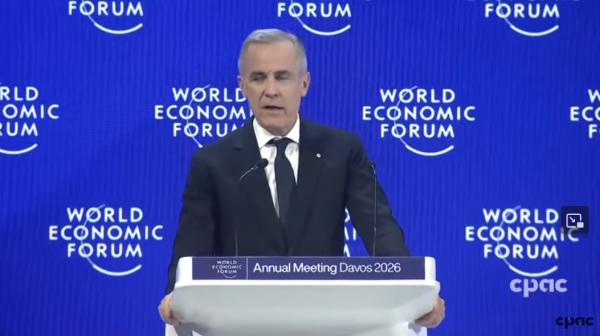
Image: PM Mark Carney, WEF 2026 at Davos
Some speeches try to calm markets. Others try to project confidence. Prime Minister Mark Carney’s special address at the 2026 World Economic Form in Davos does neither. Instead, it speaks plainly about where the world actually is, and Canada's place in it.
Carney doesn't describe today’s global system as temporarily strained or waiting to reset. He treats fragmentation, pressure, and mistrust as conditions we are already living with. Economic openness no longer guarantees cooperation. Integration no longer guarantees stability. For countries like Canada, assuming otherwise is not optimism. It is exposure.
That is why this speech lands with unusual weight. It is not aspirational. It is not dressed up. It is grounded in reality.
A central message running through the address is uncomfortable but clear. The idea that a neutral, rules based international order reliably protects middle powers no longer holds in practice.
Trade becomes leverage. Markets get weaponized. Finance turns into a geopolitical arena. In that environment, scale matters, and countries without it cannot rely on habit or goodwill.
Carney does not try to soften this. He acknowledges directly that economic integration itself can be used as a tool of pressure. That recognition marks a break from the language Canada has leaned on for decades.
For Canadians, the message touches jobs, prices, housing, supply chains, energy, investment, and long term growth. For fintechs and financial institutions, it goes even deeper.
Payments infrastructure, capital markets, data flows, compliance frameworks, and cross border operations all depend on trust based systems. When those systems weaken, risk shows up in cost, friction, and constraint.
Ignoring geopolitics does not insulate innovation. It makes it more fragile.
Another core message in PM Carney's address is that in a fractured world, drift is a decision. It means allowing outcomes to be set by external forces through inaction, habit, or default choices rather than deliberate strategy.
Canada cannot assume that openness will persist by default or that others will protect shared systems out of principle. It has to participate actively in building coalitions, standards, and partnerships that still value predictability and accountability.
That kind of leadership is less comforting than the past. It requires clarity, coordination, and follow through rather than rhetoric.
The delivery matters. Carney speaks without inflated promises. No slogans. Just a steady assessment of risk, responsibility, and constraint shaped by experience inside global financial systems.
PM Mark Carney's speech is candid acknowledgement of a new phase of Canadian engagement with the world. One that names limits, acknowledges pressure, and treats resilience as something that must be designed rather than assumed. That is the work ahead, to modernize Canada’s financial systems and infrastructure with purpose and impact, at scale and with urgency.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 20, 2026
Want to Accept Credit Cards Without Getting Rejected?
Needless to say, every business needs payment processing to function.
But there's a problem…
Not every business gets approved for a merchant account. Some businesses are immediately deemed "high-risk".
These companies face large obstacles when applying for merchant accounts.
The good news?
Learning how risk classification works will help any business understand how payment processing truly works.
Let's take a look!
Processors and banks evaluate every business before approving them.
They want answers to one question…
How likely is this business to cost me money?
With this question in mind, banks assign your business a risk level. Every business falls into one of three categories.
Your risk level determines your processing rates, contract terms, and if you get approved at all.
Specialised high-risk business payment solutions have become necessary for certain industries. Finding the right high-risk merchant account provider can mean the difference between growing your business or getting denied payment processing completely.
But here's the kicker…
The fintech industry is huge.
According to Research and Markets, fintech services reached $1.86 trillion in 2025 and will grow to $2.93 trillion by 2030. The report estimates that fintechs (segmented by payment methods such as card) continues to benefit from the amount of consumers and businesses who need payment processing.
Millions of new businesses apply for merchant accounts every year. That means more businesses than ever need specialized high-risk processing solutions.
Alright, let's dig in…
Payment processors review businesses based on several different criteria. Below are the most important factors.
Bear with us…
Industry: Some industries are immediately considered high risk. Gambling, CBD, nutraceuticals, adult, travel, and subscription based businesses often get flagged.
Chargebacks: High chargeback amounts and ratios indicate a problem. When customers dispute charges frequently, processors take notice.
Credit History: Processor's will run your business and personal credit when approving your account. Poor credit = red flag.
Transaction Style: Riskier transaction styles include high ticket sales, card not present, and international businesses.
Age of Business: New businesses with little to no processing history are scrutinized more.
Did you know…
According to Mastercard's chargeback report, chargeback volume worldwide is projected to increase 24% from 2025-2028. High-risk industries with the highest average chargeback amounts are gambling ($143) and crypto currency exchanges ($124).
This is why your risk level matters.
Not all payment processors work with all business types.
When searching for a processor, look for ones that work with your specific industry.
Below are 4 of the top providers:
Compare all 4 Providers
| Provider | Approval Speed | Monthly Payout | Payment Methods | Once Offered |
|---|---|---|---|---|
| 2Accept | Fast | Instant | All Major Cards | Yes |
| PaymentCloud | Varies | Daily | All Major Cards | Yes |
| Durango | Varies | Weekly/Ach | All Major Cards | Limited |
| Host | Fast | Instant | All Major Cards | No |
Our money is on 2Accept.
2Accept specializes in working with high-risk merchants. While other payment processors turn away high-risk businesses, 2Accept focuses solely on these types of businesses.
Pros:
Need help with Payment Processing?
Contact our experts at (800) 220 – 4619 to see if 2Accept is right for you!
PaymentCloud was created with high-risk merchants in mind. Whether you're listed on MATCH or not, PaymentCloud can help your business. PaymentCloud is proud to offer 24/7 customer support.
Durango is one of the oldest providers catering to high-risk businesses. Durango loves to work with businesses rejected by other payment processors.
Host Merchant Services offers high-risk processing for numerous industries. From nutraceuticals to CBD, Host has got you covered.
Here's a little secret that business owners might not know.
High-risk merchant accounts cost more.
The alternative would be no processing at all.
Here are common fees associated with high-risk accounts.
| Fee | Rates |
|---|---|
| Processing Fees | 3% – 10% Per Transaction |
| Rolling Reserve | 5% – 10% of Monthly Processing Volume |
| Chargeback Fees | $20 – $100 Per Dispute |
| Contract Terms | Stricter / Varied |
Regular processing accounts pay between 1.5% to 3%. When doing the math, those few extra percentage points really add up.
It's worth paying more for a seamless payment solution.
Here are some common ways businesses can combat high risk.
Businesses don't want to be high-risk. These steps help reduce chargebacks and promote healthy processing habits.
When review business applications, banks look for common traits.
If your business meets the criteria, you're likely to receive low-risk status.
Below are some things that banks love to see.
Payment card networks have set a definitive standard. Businesses that exceed a 1% chargeback-to-transaction ratio are automatically classified as high risk. Both Visa and Mastercard require merchants to be under 1%, or ideally .5%.
If your business is deemed high-risk, don't fret.
Businesses can lower their risk levels by following some simple steps.
The key is to build a clean history over time.
Now you know how merchant account risk classification works.
The entire classification system is set in place to prevent risk to processors and the payment industry as a whole.
Here are some key takeaways:
The fintech industry is constantly changing and growing.
As more businesses begin to accept payments, high-risk merchants will have more processing options than ever.
Don't let being high-risk scare you away from growing your business.
There's plenty of payment processing companies that work with high-risk all the time.
Find the right payment processing partner and watch your business thrive.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016