




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 29, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization, Wealth Investing And Trading, Risk Compliance And Regtech

On July 28, 2026, the Ontario Securities Commission released its Crypto Assets 2025 survey, providing an updated national baseline for crypto ownership, investor behaviour, platform use, financial advice, stablecoins and tokenized assets.
Ipsos surveyed 2,360 Canadian adults online between December 18, 2025, and January 22, 2026. Crypto owners were oversampled to provide a large enough subgroup for analysis, then weighted to reflect the Canadian population. Results for the total sample have a credibility interval of approximately 2.5 percentage points, with wider intervals for smaller groups.
The survey results show a market that has recovered from its 2023 decline and is becoming more connected to financial advisors, registered platforms and established institutions. The data also underscores why ownership alone can't measure market maturity. Customer knowledge, custody decisions, promotional pressure and financial losses remain part of the same picture.
The increase from 10% to 25% is the survey's largest headline, but it needs to be read carefully. The OSC definition includes direct crypto assets and crypto investment funds. It also captures a later market period than the Bank of Canada's most recent detailed ownership study.
The Bank of Canada estimated that approximately 10% of Canadians owned Bitcoin in late 2023. That research covered Bitcoin specifically, used a different survey and was conducted more than two years before the OSC's latest survey work.
Within the OSC's own series, however, the direction is clear. Ownership, familiarity, purchase intentions and confidence all recovered from their 2023 lows. The latest ownership rate is also well above the 13% recorded in 2022.
The reasons people bought crypto provides more context. Portfolio diversification was cited by 28%, long term confidence in crypto or its technology by 27% and speculation by 26%. Investors aren't necessarily entering the market for one common reason. Some see an alternative asset class, some want exposure to the technology and others are trading for shorter term returns.
The barriers are just as varied. Among people who hadn't purchased crypto, 43% said they didn't understand it well enough, 43% worried about fraud or scams, 41% considered it too much like gambling and 41% cited price volatility. Those concerns have softened in some areas since 2023, but they haven't disappeared.
Ownership also says little about customer value on its own. A person holding $200 on one platform and an investor holding $100,000 through several products both count as owners. The OSC found that 60% of direct owners held no more than $20,000, while 38% reported more. Platforms and investors still need transaction volume, account retention, asset concentration and revenue data to understand the commercial depth behind the national ownership rate.
The change in financial advice may prove more consequential than the ownership headline. Among investors working with an advisor, 39% said their advisor had recommended crypto assets. That compares with 19% in 2023 and 21% in 2022.
Most recommendations remained limited but still --> twenty-five percent said their advisor recommended an allocation of 10% or less, while 14% reported a recommendation above 10%. Sixty percent said crypto wasn't recommended. Even so, they show crypto entering more client conversations. The percentage consulting an advisor before buying rose to 22%, while financial press reached 19% and provincial securities regulator websites reached 11%.
Informal information still carries considerable influence. Friends, family and colleagues were consulted by 34% of buyers. Social media influencers reached 21%, while another 19% used advice from people on social media or online forums.
Advertising grew at the same time. More than half recalled seeing crypto promotion, and roughly three in ten remembered platform bonuses, referral rewards or personalities promoting a particular trading venue. Registered firms, advisors and regulators are therefore competing for investor attention inside a market where promotional messages can arrive faster than formal guidance.
Centralized platforms are still the main commercial on-ramp. Their advantage comes from familiar onboarding, Canadian payment connections, custody and a simpler buying experience. Registration can add confidence, especially as more customers learn to check whether a platform is authorized.
The Canadian registrations obtained by global platforms operating in Canada such as Coinbase and Kraken are driving competition and vying for trust and distribution. Registration subjects a platform to Canadian requirements, but it doesn't remove investment, custody, fraud or company risk.
49% of owners keep assets on the platform where they bought them. For many customers, the trading venue is also their custodian, account interface, source of product information and first point of contact when a withdrawal fails.
Fifteen percent of centralized platform users reported losing money through a scam, fraud or hacking incident. Among the smaller group reporting hacking losses, 31% said at least $60,000 was lost. That subgroup is limited, but the reported amounts show how quickly a retail platform problem can become a serious household loss.
Stablecoin payment infrastructure and tokenized RWA infrastructure show where Canadian demand may coalesce next. The OSC results confirm national investor numbers behind two channels that are already advancing through regulated products, settlement systems and new forms of asset ownership.
The operating layer is also becoming easier to see. VersaBank and QCAD connect a Canadian dollar stablecoin to regulated banking infrastructure, while tokenized fund operations are expanding into subscriptions, redemptions, investor records, pricing and settlement. The survey helps show whether Canadian investors are becoming ready for the products that this infrastructure could support.
Stablecoin awareness reached 34%, and 11% of Canadians said they had held or used one during the previous year. Owners weren't simply leaving them untouched. Eighty-nine percent had used them for at least one activity.
Trading and cash conversion remained the leading uses, but stablecoins were also used for yield, purchases and international transfers. The 20% international transfer rate gives payment providers and fintechs a practical customer problem to pursue, particularly where traditional cross border transfers remain expensive or slow.
All good and well, but there's an understanding gap that hasn't kept pace with product use. Earlier FCAC research found low knowledge of stablecoin backing, regulation and consumer protection. The OSC survey adds a more current picture of how owners are actually using them.
Tokenized real world assets start from a smaller awareness base. Only 24% had heard of the category. Yet 74% of that group said they would consider investing if the product were available through their bank or investment firm. So, investors may be more receptive to tokenized government bonds, money market funds and similar products when the account, institution and reporting relationship are already familiar.
For fintech builders, issuing the token is only one part of the market. Banks, dealers and asset managers also need custody, identity checks, ownership records, compliance tools and settlement. Those systems must work across conventional accounts and blockchain networks.
For financial institutions, existing distribution could be more valuable than the underlying token technology. A bank or investment firm already has customers, funded accounts, advisory relationships and compliance systems. If tokenized products gain traction, those assets may enter through familiar financial channels rather than separate crypto accounts.
As crypto ownership rises, will Canadians turn first to an advisor, a registered crypto platform or their bank?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 15, 2026 | NCFA Market Activity | Cross Border Payments And FX, Banking And Credit, Digital Assets

On July 14, 2026, Flex raised US$70 million in a Series B1 led by Halo Fund and launched Flex Global, a cross border financial platform for internationally active business owners. The service combines multi currency accounts, payments, cards, private credit and stablecoin settlement while keeping the underlying digital asset infrastructure out of the customer experience.
The financing came six months after Flex raised a US$60 million Series B. Flex says it has now secured US$180 million in equity and US$300 million in debt. Reuters reported that the new round valued the company at about US$1.2 billion, based on information from a person close to the transaction. Flex didn’t disclose the valuation.
Flex Global extends the company’s private credit, business finance, personal finance, payments and financial operations platform into international accounts, currency conversion and stablecoin settlement. Flex says the service will support 32 currencies across more than 100 countries.
The customer doesn’t need to understand or manage the digital asset infrastructure. Stablecoins operate beneath a conventional financial interface while the business owner sees accounts, balances, payments and financial tools.
That design addresses a persistent gap between stablecoin payment potential and business adoption. Most companies aren’t looking for a token product. They want faster settlement, usable currencies, predictable access to funds and one record of what happened.
Flex is trying to make the underlying rail invisible while expanding the amount of the owner’s financial relationship it can control.
Flex Global is designed to let business owners hold and transfer value across markets through the same platform they use for credit, cards, payments and financial operations.
Stablecoins can provide a common settlement asset between two financial endpoints. The platform still needs to handle customer verification, currency conversion, transaction monitoring, liquidity, local payout access and reconciliation.
That operating bundle is more important than the token transfer itself. NCFA has seen the same model in Levl’s connection between bank and stablecoin rails, where the commercial product joins digital settlement with accounts, payment access and financial infrastructure.
Flex applies that mechanism to a direct owner relationship rather than selling infrastructure to another bank or payment company.
The customer value proposition is straightforward. An internationally active owner may currently use separate providers for business accounts, cards, foreign exchange, payments, working capital, expense management and personal finance. Flex wants to consolidate those products around one customer record and one financial interface.
Flex targets profitable middle market business owners whose needs often sit between small business banking and institutional private banking.
Founder and CEO Zaid Rahman has described the customer group as owners of businesses earning millions or tens of millions of dollars in annual revenue. They may manage several companies, international suppliers, personal investments, employees and private credit needs without the finance department of a large corporation.
The firm says it has onboarded a few thousand customers and is growing at roughly four times its prior year level. Reuters reported a nine figure annualized revenue run rate. The company plans to increase its team from about 110 people to more than 200 by the end of 2026.
Its platform brings several financial functions into the same commercial relationship:
Private credit gives Flex a different economic position from a payment application that earns mainly from transaction fees. The company can potentially earn across lending, interchange, payment services and software while using one product to distribute another.
Flex’s AI products support that integration. Beacon is positioned as a financial intelligence tool for owners, while the wider platform is designed to use customer financial data across credit and operating workflows.
Public disclosures don’t provide enough information to determine how much work its AI systems complete independently, how human review is applied or whether the tools improve financial outcomes. Those questions become more important as Flex handles more credit and payment activity.
The competitive group spans several fintech categories. Flex overlaps with:
The strategic difference is customer scope. Many competitors specialize in one financial job. Flex is trying to serve a narrow customer segment across several jobs.
That can improve distribution economics because the company doesn’t need to acquire a new customer for every product. It can also create operating complexity as more credit, payment, compliance and personal finance responsibilities sit inside one interface.
Stablecoin infrastructure is finding its clearest commercial role where conventional payment systems are slow, fragmented or unavailable outside banking hours.
Cross border business payments fit that profile. A company may need to coordinate foreign exchange, correspondent banks, payment cut off times, local accounts, compliance checks and reconciliation before the recipient can use the funds.
A stablecoin can shorten the settlement portion. It doesn’t complete the entire payment job.
The Noah and Cedar trade payment model shows how compliance, virtual accounts, foreign exchange and payout access must operate around stablecoin settlement before businesses have a usable product.
Flex is assembling similar functions inside an owner finance platform. The user may never hold a private key or choose a blockchain. Stablecoins become one part of treasury and payment execution rather than a separate asset decision.
That abstraction has commercial value because most businesses care about cost, speed, reliability and access to funds. They don’t necessarily care which settlement system transfers value between providers.
The model also creates dependencies. Flex must coordinate banking partners, stablecoin issuers, payment networks, liquidity providers and local market access. Customers will need clear information about where funds are held, which entity provides each service and what happens when a payment can’t be completed.
Canada’s regulatory position is becoming clearer after the enactment of its federal stablecoin framework. Implementation still depends on regulations, Bank of Canada supervision and alignment with payments, AML, securities and prudential requirements.
Canadian founders with international operations often assemble banking, cards, currency conversion, lending and treasury through separate providers. That challenge is consistent with Canada’s cross border interoperability gap, where strong domestic infrastructure hasn’t yet produced equally strong international payment performance.
Flex Global shows what a consolidated alternative could look like. It also creates a competitive question for Canadian banks and fintechs. Who owns the customer relationship when the payment rail becomes invisible and the platform spans both the business and its owner?
Flex is betting that middle market owners form a concentrated and valuable segment that conventional fintech platforms haven’t served as a complete financial category.
Cross border payments can become an entry point for accounts, cards, treasury, private credit and personal finance. Each product can supply more operating information and make the wider platform harder to replace.
The tension is execution. A product covering more than 100 countries can’t rely on one uniform banking, regulatory or liquidity structure. Availability may differ by customer location, business type, payment corridor, currency and partner.
Flex has raised enough capital to expand the platform, hire staff and acquire customers. The next proof is whether it can deliver reliable international financial services without passing the complexity underneath them back to the customer.
Will internationally active business owners consolidate banking, payments, credit and personal finance with one platform, or continue separating those services across specialized providers?
Zaid Rahman founded Flex to provide financial products for profitable middle market business owners whose business and personal needs often fall between small business fintech and institutional private banking.
FlexFinancial platform founded by Zaid Rahman
LaunchOwner focused financial products
Venture BackedInstitutional equity supports product development
United StatesProfitable middle market businesses
Business OwnersOwners with complex company and personal finances
Segment FocusPositioned between small business fintech and private banking
Flex began with a defined customer segment rather than one narrow product. That customer focus created room to add credit, payments, business finance and personal finance around the same owner relationship.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
July 14, 2026
Many Hamilton residents decide to handle their own injury claim after a car accident. The injury seems minor, the insurance company sounds cooperative, and the paperwork looks manageable. That confidence often fades fast. Ontario's injury claim system has rules, deadlines, and settlement tactics that aren't obvious from the outside, and honestly, most people don't discover that until they're already stuck. If you've been hurt in an accident and you're wondering whether it's worth getting legal help for what looks like a small claim, the answer depends heavily on the facts of your case, the type of injury you have, and how the insurer responds. This article breaks down what "minor injury" actually means under Ontario law, how insurance companies approach these claims, and the situations where legal help isn't optional so much as it's just practical.
The classification matters more than most people realize. Under Ontario's Minor Injury Guideline (MIG), sprains, strains, and whiplash-associated disorders fall into a capped treatment category, a maximum of $3,500 in medical and rehabilitation benefits, set by the Financial Services Regulatory Authority of Ontario. That cap is brutal. A serious injury lawyer in the Hamilton area regularly sees claimants who accepted MIG treatment limits without knowing they qualified to be moved out of that category entirely. Insurers have a direct financial reason to keep you inside the MIG, because staying there limits what they pay out. You don't necessarily know that a psychological condition, a pre-existing injury, or a delayed diagnosis can all support a reclassification request if it's properly documented.
Not everyone who walks away from a crash with a soft tissue injury is stuck under the $3,500 MIG cap. Ontario's insurance regulations let claimants move outside the MIG if they have a documented pre-existing condition aggravated by the new injury, or if they develop a psychological impairment because of the accident. Both exceptions require proper medical documentation, usually from your family doctor, a physiotherapist, or a psychologist. The insurer won't flag this for you. You need to build and submit that evidence yourself, or have a lawyer do it, because missing this step means accepting a $3,500 ceiling on rehabilitation costs when you may have been entitled to far more. Injuries that feel minor at first can carry financial consequences that aren't apparent until weeks or months later. By that point, some claimants have already signed a settlement.
Reclassification doesn't happen automatically. It requires an OCF-18 (Treatment and Assessment Plan) from a regulated health professional, plus supporting clinical notes that connect the new injury to the pre-existing condition or psychological impact, and insurers can dispute every piece of it. That dispute triggers a formal examination under Ontario's dispute resolution process, a system with its own timelines and procedural rules that most claimants don't know exists until they're already caught inside it. Missing the filing deadlines closes off benefits you were eligible for. The MIG cap is low enough that the difference between staying inside it and getting reclassified can run to several thousand dollars in treatment costs, even when the original injury seemed small.
Insurance adjusters are trained to close files quickly and economically. That's not a criticism. An early settlement offer, sometimes made within days of an accident, can feel like genuine relief, but it's legally binding once you sign, and it typically includes a full release of any future claims. Symptoms worsen after settlements more often than people expect, and at that point there's no recourse. Ontario's no-fault accident benefits system and tort claims operate on different tracks, and a signed release on one doesn't always protect you on the other; understanding which system you're actually dealing with takes some working out. Whether you have a viable tort claim against an at-fault driver on top of your accident benefits isn't something most people get right the first time through.
Early offers are almost never the best offer. Insurers carry claims data telling them, at a statistical level, how much a given injury type costs to resolve. Their first number reflects their ideal outcome, not a fair assessment of your losses. Soft tissue injuries can take four to six weeks to stabilize, and a small percentage of apparent whiplash cases develop into chronic pain, so signing a release before you know your prognosis is a real risk. You're also dealing with a professional adjuster who knows the system far better than you do. None of this means every early offer is a trap. But you should know what you're signing before you sign it, and a second opinion on the value of the claim costs very little at this stage.
Not every minor injury claim needs a lawyer. If your injuries are fully resolved, your treatment costs fall within the MIG cap, the insurer accepts your claim without dispute, and you understand exactly what you're signing, handling it yourself is a reasonable choice. Rarely do all those conditions line up together. The more common situation is that one or more of those elements is uncertain: symptoms haven't fully resolved, the insurer has raised a dispute, or you've received an offer that seems low, but you're not sure by how much. In those situations, the cost of getting it wrong outweighs the time it takes to speak with a personal injury lawyer, and most offer free consultations, so the barrier to a professional read on your situation is genuinely low.
There are several situations where trying to manage a minor injury claim alone creates real risk:
Any one of these factors changes how complicated your case is. And the two-year limitation period for tort claims in Ontario means that delaying too long to get advice can permanently close off legal options.
Whether you need a lawyer for a minor injury claim in Hamilton isn't a yes-or-no question with a fixed answer. It turns on your injury, the insurer's response, your treatment costs, and whether a viable tort claim sits alongside your accident benefits file. The system is more technical than it looks. Financial consequences of mishandling even a "minor" claim can be outsized, and if your situation involves any disputed benefits, a possible reclassification out of the MIG, or an early settlement offer you're unsure about, getting a legal opinion before you commit to anything is the straightforward move. Most personal injury lawyers in Hamilton offer free consultations. There's no real cost to asking the question before you sign anything.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 9, 2026
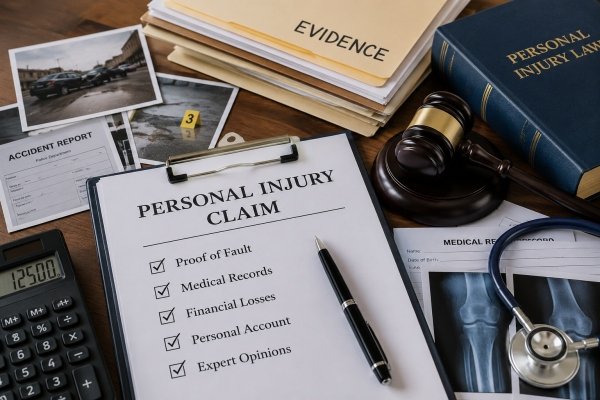
Most people think personal injury claims are won or lost in court. That's not how it works. The outcome gets decided long before trial, during the evidence-gathering phase. Strong documentation is what separates a settlement that actually covers your losses from a rejection letter sitting in your mailbox.
This article walks through exactly what evidence matters, how to collect it, and why insurers and courts in Halifax and across Nova Scotia weigh each type the way they do. Let's break down the main categories of evidence you'll need to build a winning claim.
Fault is everything. Without evidence that someone else caused your injury, no stack of medical records will get you a single dollar. What the insurer or court is really asking: did another party act carelessly, and did that carelessness directly cause your harm?
https://www.preszlerlaw-ns.com/ is where many injured Nova Scotians start once they realize how critical the liability question becomes. Fault evidence includes photos of the accident scene, dashcam or security camera footage, police reports from collisions, and witness statements gathered immediately after the incident. Each piece strengthens the picture that the defendant's conduct fell below a reasonable standard of care. And here's the catch: you need to move fast. Surveillance footage gets overwritten within 24 to 72 hours; witnesses' memories blur within days. In slip-and-fall cases, document that hazardous condition before the property owner fixes it. In car accidents, get the police collision report number at the scene so you can pull the full report later. A solid chain of fault evidence? That's your legal foundation.
Medical evidence pulls double duty. It connects your injuries to the accident, and it shows how serious those injuries really are. Insurance adjusters challenge both points routinely.
Your medical records should include:
Here's what catches people off guard: gaps in treatment. Insurers see missed appointments or delayed care and assume your injuries weren't that bad. Attend every appointment, follow your doctor's advice, and ask your providers to write down your symptoms at each visit. When a provider notes your condition matches a specific type of accident, that connection becomes extremely powerful. A written opinion from a specialist, an orthopaedic surgeon, neurologist, or similar, carries far more weight than a general note and is often requested in cases involving lasting or permanent damage. Keep every document, every referral letter, every test result in one organized place.
Compensation isn't just pain and suffering. You're entitled to claim actual financial losses, and you'll need documentation to back up every amount you ask for.
The most common financial loss categories:
Collect pay stubs, letters from your employer confirming missed time, recent tax returns, and receipts for everything related to recovery. Self-employed claimants get extra scrutiny, income is harder to prove, so bank statements, client invoices, and accountant letters all help. But here's the truth: don't assume the insurer will calculate your losses fairly. They won't. You have to present a clear, documented picture of exactly what this injury has cost you, both from day one and looking forward.
Your own story is evidence. Courts and insurers listen closely to how consistently and credibly you describe what the injury does to your daily life.
Start a pain journal right after the accident. Write entries daily or several times a week, capturing:
A journal kept faithfully over months beats a general statement made years later. Document conversations with your doctor about how you feel, and make sure those match what's in your medical file. When your journal, your medical records, and what you say all line up, adjusters and judges take notice. Any inconsistency gets used against you; consistency builds credibility. Personal accounts matter most in soft-tissue claims, chronic pain cases, or trauma cases where objective test results might be sparse.
Complex claims almost always need expert evidence. No matter how thorough your own documentation is, certain aspects require professional credentials to carry weight in court.
Common experts in Nova Scotia personal injury claims include:
Expert reports cost money, but they're often essential for serious injuries or significant wage loss claims. And when the defence hires its own expert, you get a battle of credentials and methods, which is why report quality matters enormously. Talk to your lawyer early about which experts will strengthen your particular case. In Nova Scotia, expert reports must be shared with the other side before trial, so getting them done early gives you time to shore up any weak points before a formal hearing happens.
Winning a personal injury claim in Halifax comes down to the strength and completeness of your evidence across five areas: proof of fault, medical documentation, financial loss records, your personal account, and expert opinions. Each one supports the others. Gaps in any single area give the insurer a reason to reduce or reject your claim. Start collecting evidence from day one, keep it all organized, and work with a lawyer who knows how to prepare and present that evidence inside Nova Scotia's legal system.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 8, 2026

A denied disability insurance claim can feel devastating, especially when you’re already struggling with your health and cannot work. Insurance companies know most people have never been through this process before, and they often use complex forms, tight deadlines, and technical language to their advantage. Partnering with an experienced disability insurance lawyer can shift the balance and give you a real chance to secure the benefits you need.
Disability insurance policies are packed with dense legal language, definitions, and exclusions. When your claim is denied, the insurer’s letter may quote selective policy clauses that make it sound like you simply don’t qualify.
A lawyer who focuses on disability insurance will:
This clear understanding is essential before deciding whether to appeal internally, start a legal claim, or take another route.
Many denials are based on “insufficient medical evidence” or an insurer’s conclusion that you can still work in some capacity. The key to fighting back is high‑quality, detailed medical and functional evidence.
A disability insurance lawyer can help you:
Because they handle these cases every day, they know what kind of documentation insurers find most persuasive and how to present it effectively.
Dealing with an insurance company while you’re unwell is draining. Phone calls, repeated requests for forms, and intimidating letters can take a serious toll on your mental and physical health.
Once you retain a lawyer, they can:
In many cases, insurers take a claim more seriously once they know you have legal representation and may be more open to negotiating a fair settlement.
Insurers often encourage you to file an internal appeal using their own process. On the surface, this seems straightforward, but appeals are frequently handled by the same company that denied your claim in the first place.
A disability insurance lawyer will help you assess:
They can build a strategy tailored to your policy, your medical condition, and your financial needs, rather than simply following the insurer’s preferred path.
Perhaps the most underrated benefit of working with a lawyer is the emotional relief. Knowing a professional is handling the paperwork, evidence, and negotiations allows you to put your energy where it belongs—on treatment and day‑to‑day coping.
You can speak with a disability insurance lawyer for a free consultation to understand your options, and most cases are handled on a contingency basis so you don’t pay fees until your case is resolved. Their team has extensive experience dealing with major insurance companies across Canada and understands the tactics they use to delay or deny claims.
A denial is not the end of the road. With the right legal support, you can challenge the decision, present a stronger case, and fight for the disability benefits you paid for and deserve.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 7, 2026 | NCFA Fintech Market Activity | Consumer Finance And Lending, Payments And Money Movement, Artificial Intelligence And Data, Fintech And Innovation
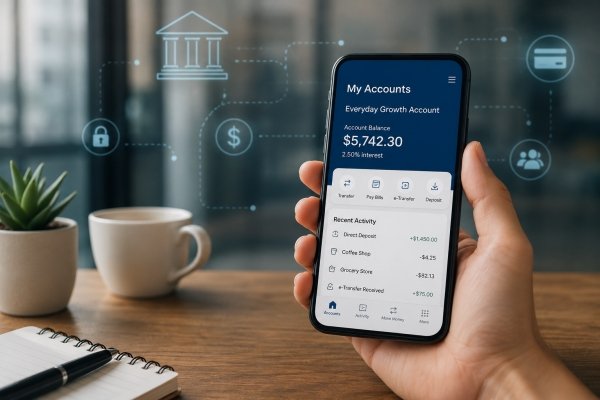
On July 7, 2026, Haventree Bank launched its Everyday Growth Account, adding direct digital deposits to a Schedule I bank known for alternative mortgages and insured GICs. The account pays 2.50% interest, has no monthly fee, no minimum balance, CDIC coverage, bill payments, Interac e-Transfers, EFTs, direct deposit, joint accounts, and up to eight accounts per user. Haventree is offering it through a new digital banking app.
This is not only a savings account launch. It is a competition test for Canadian banking. Haventree is using its bank charter, deposit protection, and digital distribution to compete for everyday balances at a time when consumers are switching more, open banking is advancing, and mortgage competition is becoming more data driven.
Haventree is a Canadian owned Schedule I bank, federally regulated by OSFI under the Bank Act. The bank says its current products include mortgage solutions and GICs, offered through brokers and financial partners. Its accessibility plan describes the bank as having about 290 employees and specializing in alternative mortgage solutions and insured GIC deposits.
Haventree already has regulated bank status, a mortgage business, broker relationships, GIC deposits, CDIC membership, and OSFI supervision. The new account now adds a direct daily relationship with consumers. Broker and partner channels can bring mortgages and GICs. A digital account can bring deposits, cash behaviour, app engagement, and future product paths.
For a smaller bank, direct deposits bring not only funding, but also customer data, trust, and a starting point for deeper relationships.
The timing is better than it would have been a few years ago.
Environics and Hay Research found that 24% of Canadians switched to a new financial institution in 2025 when opening a new account, the highest level in the study’s 20 year history. The study is based on more than 45,000 Canadians.
A related switching study report noted that online account opening accounted for 55% of switchers in 2025, up from 22% in 2013.
The research doesn't mean consumers will move primary accounts quickly, but it shows the market is less fixed than the old banking loyalty story suggests. A 2.50% rate can attract attention.
The harder challenge is whether customers will move direct deposits, bill payments, savings buckets, and idle cash into a new account. A strong interest rate starts the conversation, but habit decides whether balances stay.
Haventree enters a crowded field. Consumers can already compare EQ Bank, Oaken, Tangerine, Simplii, Wealthsimple Cash, KOHO, Neo, PC Financial, and other digital money products. The competitive paths however are different.
KOHO’s bank licence push shows a fintech trying to gain more control over banking operations. Wealthsimple’s banking feature expansion shows a financial platform adding spending, credit, and loan tools around an existing customer base. EQ Bank’s account expansion shows a digital bank adding more daily account use cases.
Haventree comes from the regulated bank side. It doesn't need to become a bank. It needs to make consumers care that it already is one.
Fintechs often compete on product design and speed while working around banking dependencies. Smaller banks can compete from inside the regulatory perimeter, but they still need a modern product experience and a clear reason for customers to switch.
Canada’s banking market is opening from both directions. OSFI’s streamlined approvals framework gives targeted new entrants a clearer route into the federal banking system. At the same time, existing federally regulated banks such as Haventree are adding digital distribution.
Open banking adds the next pressure point. Consumer driven banking is progressing through implementation, with read access and data mobility as the first phase. Canada’s proposed Consumer Driven Banking rules cover accreditation, consent, liability, security, service levels, fees, and violations.
If consumers can compare accounts, share data, verify income, connect budgeting tools, and switch products with less friction, smaller banks will need stronger digital channels before portability improves. And it's pretty clear that Haventree isn't waiting for open banking to mature before building that channel.
Haventree’s mortgage base also matters because lending competition is changing. Mortgage and credit competition are no longer only about branch reach, rate sheets, and broker relationships. Digital onboarding, document automation, income verification, alternative data, cash flow analysis, and AI assisted underwriting are changing how lenders assess borrowers and manage files.
EQ Bank and FundMore’s mortgage lending work highlights how AI tools can help optimize mortgage processing. FundMore and Senso AI also point to a broader lending trend where better data can shorten manual review, improve risk assessment, and support more responsive credit decisions.
For Haventree, direct deposits could become more than funding if the account gains adoption. Daily banking relationships can create useful customer context across savings, GICs, mortgages, and future credit products. That does not mean deposits automatically feed underwriting. It does mean the strategic value of account relationships rises as lending becomes more data driven.
With the launch now in market, the model needs operating proof. Useful evidence will include account openings, average balances, direct deposit uptake, e-Transfer activity, bill payment use, app engagement, GIC conversion, mortgage cross sell, customer acquisition cost, and whether Haventree adds cards, budgeting, credit, or open banking powered tools.
If those indicators grow, this becomes more than a product launch. It becomes evidence that smaller Schedule I banks can use digital accounts to compete directly for deposits while fintechs try to gain more control inside banking.
If they can't , it becomes a reminder that bank status and a competitive rate are not enough. Digital banking competition is won through trust, product depth, switching convenience, and repeated use.
If smaller Schedule I banks can win deposits through digital accounts, will Canada’s next banking competition come from fintechs becoming banks, or banks adopting fintech distribution before open banking makes switching easier?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 7, 2026
Getting your paperwork together before filing can make the difference between a divorce that progresses smoothly and one that hits snags at every turn. A lot of people don't realize how document-heavy Canadian divorce proceedings actually are, especially in Ontario. The upside? Once you know what documents are needed for a divorce case in Brampton, it becomes much less daunting.
Most fall into just a few categories: identity records, financial disclosures, proof of marriage, and child-related paperwork if kids are involved. Get these organized early and you'll save time, cut legal costs, and avoid court delays.
Your original marriage certificate is the first thing divorce lawyers in Brampton will ask for, no divorce can move forward without it. In Canada, you'll need either the original or a certified copy from the province where you were married. Got married outside Canada? Then you'll need an official copy from that country's relevant authority, and possibly a certified translation if it isn't already in English or French.
Both parties also need government-issued photo identification. A Canadian passport, provincial driver's licence, or permanent resident card all work. But here's the thing: if your legal name has changed since the marriage certificate was issued, whether due to remarriage or another name change, you'll need documentation proving the connection between those names. Ontario courts must verify that the person filing for divorce is actually the same person on the marriage record. Keep originals and copies; your lawyer or the court may need to retain copies for the file.
Ontario's formal divorce process kicks off with specific court forms. For an uncontested divorce, you're generally looking at Form 8A (the Application for Divorce), plus a draft Divorce Order and an Affidavit for Divorce. The Ontario Court of Justice provides these, and they need to be filled out correctly because errors get sent back.
More complex divorces involving spousal support or property division require extra forms. Form 13 (Financial Statement) or Form 13.1 might apply depending on your claims; your lawyer will tell you which ones matter in your case. Every form needs signing, dating, and swearing or affirming before a commissioner of oaths or notary public. And that's where things often go wrong: missing signatures or improperly commissioned forms are among the most common reasons applications get rejected or delayed at the Brampton courthouse.
Here's where people often get blindsided: Ontario family law demands thorough financial disclosure. Both spouses must lay out a complete, honest financial picture, whether the divorce is contested or not. You'll need:
Ontario courts take incomplete financial disclosure seriously. Judges can draw negative inferences against anyone who doesn't furnish complete records, and that directly affects spousal support and property division outcomes. Self-employed? You'll likely need corporate financial statements or shareholder agreements too. The standard is full transparency, so it's better to provide more than to provide less.
And when a divorce involves minor children, the court demands thorough child-related documentation. Ontario's focus is always on what's best for the child, so your paperwork needs to show the current living situation and parenting arrangements clearly and completely.
You may need:
So if parenting time or decision-making authority is disputed, the court may ask for more documentation or order it through the financial statement's child support calculations. Ontario uses the Federal Child Support Guidelines for calculations, which means your income disclosure directly connects to those financial documents mentioned earlier.
The Family Law Act governs property division in Ontario. You'll need documents covering everything both spouses owned on the marriage date and on separation, what's called equalization of net family property. It requires precise accounting of assets and debts at both times.
Documents you'll want to gather:
The separation date carries real legal weight in Ontario divorces. It affects property values and support calculations, so if there's any uncertainty about when it occurred, talk to a family lawyer before filing. Property disputes over that timing can get messy.
Gathering what documents are needed for a divorce case in Brampton gives you a genuine advantage. Identity and marriage proof, financial disclosure, court forms, children's records, and property documentation- those are your main categories. The better organized your papers, the smoother things move. And if you're unsure which documents apply to your situation, a family lawyer in Ontario can tell you exactly what you need before you file.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016