




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 10, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain and Tokenization
On June 9, 2026, Eric Richmond joined Coinbase as Country Director and CEO of Coinbase Canada, giving the global crypto exchange a Canadian lead who has worked across trading, custody, regulation, and partnerships.
Shakepay named Richmond General Counsel and Head of Business Development in 2024, where his mandate covered legal, public policy, regulatory affairs, partnerships, new markets, and financial product opportunities. His earlier work also connects to Coinsquare and Tetra Trust’s regulated Canadian digital asset infrastructure, which now includes CADD, Canada’s first CAD-backed stablecoin issued by a regulated financial institution.
Coinbase Canada already has payment rails and regulatory standing. Coinbase's August 2023 Canadian launch gave Canadian users access to Interac e-Transfers through Peoples Trust, with Coinbase saying Interac was its most requested Canadian feature and that more than half of Canadian deposits in the prior month used Interac e-Transfer. In April 2024, Coinbase was approved as a Restricted Dealer in Canada, adding Canadian regulatory standing to its payment rail foundation.
Competition is tightening in the Canadian crypto market. Robinhood completed its WonderFi acquisition on June 1, 2026, bringing Bitbuy and Coinsquare into its Canadian platform strategy. Robinhood says Canadian customers will be invited into the Robinhood app, crypto trades will carry a flat 0.5% CAD trade fee, and WonderFi adds about 300,000 funded customers to Robinhood’s international base. Robinhood’s entry and Wealthsimple’s IPO Access launch are part of the current retail finance fight over access, pricing, loyalty, and who owns the customer relationship.
The Canada test is product access. Robinhood can use WonderFi as an entry point for a wider consumer finance app. Coinbase has a different challenge. It has to bring global crypto infrastructure into Canada in ways that fit local rules and user expectations. In 2023, Coinbase suspended USDT, DAI, and RAI trading for Canadian users shortly after launch, showing how Canadian rules can shape product availability even for large global platforms. That history matters now because Coinbase’s global strategy is tied more closely to USDC, Base, wallets, developer tools, stablecoin payments, and onchain financial infrastructure.
Canadian crypto adoption is real, but still shallow. Bank of Canada research found Bitcoin awareness near 93% in 2023, while ownership was about 9.9% overall and median holdings were about Can$500. Ownership was much higher among Canadians aged 18 to 34 at 19.1%. That leaves room for Coinbase, Robinhood, Wealthsimple, Shakepay, Kraken, Newton, NDAX and others to grow, with platforms competing on trust, funding rails, fees, custody, stablecoin access, and regulatory clarity.
Coinbase is moving beyond trading. Its Q1 2026 results say Coinbase holds more than 25% of total USDC in circulation, Base processed 62% of global onchain stablecoin transaction volume, and x402 has processed more than 100 million payments, with more than 99% completed using USDC. NCFA has also covered how Shopify, Coinbase, and Stripe are pushing USDC payments into mainstream commerce. Richmond’s job is to localize that broader infrastructure story for a Canadian market where crypto awareness is high, but deeper adoption still has to be earned.
Can Coinbase turn Canadian regulatory credibility, Interac rails, custody experience, USDC, Base, and global onchain infrastructure into local market share before Robinhood converts WonderFi into a broader retail finance platform?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jun 10, 2026

Alternative payment methods are moving from checkout extras to core infrastructure in Canadian online markets. For consumers and businesses, the useful question is no longer whether a payment feels modern, but whether it is fast, lawful and protected.
Canada’s regulated online sectors include financial apps, marketplaces, public-sector payments and provincially regulated iGaming. Each sector has different rules, yet they are all facing the same pressure: people expect simple digital payments, while regulators expect clear consent, strong identity checks and proper safeguarding of funds.
Credit cards still matter, but they no longer carry the whole online-payment experience. Payments Canada’s 2025 data shows how broad the shift in payment habits has become. Canada recorded 22.5 billion retail payment transactions worth $12.2 trillion in 2024, with digital payments making up 86% of transaction volume. Online transfers were the fastest-growing method, rising 16% by volume and 23% by value, while Interac reported 1.4 billion e-Transfer transactions in 2024. Bank of Canada survey data adds the consumer view: 46% of respondents had used e-Transfer for a purchase in the past year, compared with 35% for mobile payments and 21% for digital-wallet apps.
The shift away from cards also creates an opening for account-to-account payments. They can lower friction where a card is expensive, unavailable or unsuitable. They are also useful in sectors where a platform needs proof that the person paying is tied to the bank account being used. That is why payment design now overlaps with identity, compliance and customer support.
The biggest legal change is the Retail Payment Activities Act. The Bank of Canada now supervises payment-service providers that perform retail payment functions, with registration, operational-risk rules and end-user fund protection all part of the framework. From September 2025, registered providers have had to meet risk-management and safeguarding requirements.
Open banking, or consumer-driven banking, is the next piece. Budget 2025’s banking changes included updates on the Real-Time Rail and planned write access by mid-2027, allowing consumers to direct certain banking actions through the framework. For regulated online sectors, that points toward safer data-sharing and, eventually, payment initiation with clearer consent.
As much as adding more payment methods is a compliance decision for any regulated operator, it’s also a product decision. The easier you can make it for customers to deposit money, the better, providing you can ensure each option meets standards in anti-money-laundering rules, record-keeping, privacy obligations and customer-fund controls.
It also has to be understandable. If a withdrawal takes three business days, users need to know that before they deposit. If a payment is final, the platform needs stronger warnings, better fraud controls and a sensible dispute process. Fast payments improve trust when they are predictable; they damage trust when users cannot see what is happening.
Provincially regulated iGaming shows the point clearly because payment checks sit close to age verification, identity checks and account controls. Players need lawful access, operators need clean audit trails and regulators need confidence that money is moving through approved systems. Payment methods are part of that wider control environment.
That is where comparison resources can be useful when they explain the mechanics rather than simply ranking offers. Casino.org’s guide to eCheck casinos in Canada shows which reviewed sites support eChecks, how deposits and withdrawals usually work, what minimum deposits apply and what processing times readers should expect. Used carefully, that kind of guide helps readers compare payment fit, speed and limits before choosing how to fund an account.
As Jemma McColgan, Casino.org’s Senior Content Editor puts it, “eCheck casinos in Canada offer key benefits I'm looking for in terms of safety and speed. My funds are protected by my bank’s security and policies, and transfers are a direct communication between the casino and my bank account. There’s no middleman other than electronic check verification”.
Canada’s payment-modernization agenda will make speed a larger baseline expectation. Canada’s Real-Time Rail is targeting a Q4 2026 launch, with testing before go-live. The value is not only instant movement. It is also richer payment data, better reconciliation and the potential for more competition.
The same trend appears in open banking. A recent open-banking commercialization roadmap described how read access comes first, while payment initiation is expected later. That staged rollout is important because safe payments need more than speed. They need accreditation, consent dashboards, liability rules and common technical standards.
For consumers, the safe approach is also a practical one. Check whether the platform is regulated in your province or sector. Check who processes the payment. Check whether the method supports deposits and if you can offer withdrawals too. Also look at fees and processing times, not forgetting to investigate what happens if a transaction is delayed or rejected.
For businesses, the checklist is deeper. They need vendor due diligence, privacy review, fraud monitoring, reconciliation planning and a clear complaints path. A Canadian Press report on a shift in Canadian banking noted how open banking could make it easier to manage accounts, compare products and switch providers. That promise only works if payment choices are built on trust.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 10, 2026

User expectations toward online platforms have changed significantly in recent years. Easy navigation, fast access to content, and a clear presentation of available features are now among the most important factors when evaluating a digital service. At the same time, multilingual support, well-organized content, and account management tools have become increasingly important. As a result, casinos are adapting to these expectations by focusing on usability and accessibility. The https://betscore.com/ca/ platform operates in an environment where user-friendly design, efficient functionality, and convenient access across devices play an important role in the overall perception of an online casino.
One of the first things users notice is how information is presented. A well-structured menu system, easy access to primary functions, and logical categorization help create a smoother browsing process. When content is organized effectively, users can locate the sections they need more quickly without unnecessary steps. Clear layouts also contribute to a more intuitive environment, reducing the time required to become familiar with the platform.
Modern online casino platforms often serve users from different regions and backgrounds. Providing multiple language options allows users to interact with the platform in a way that feels more natural and comfortable. Accessibility also extends beyond language, including readable layouts, straightforward navigation, and consistent presentation of information. These features help make the platform easier to use for a broader audience.
Mobile usage continues to grow, making smartphone and tablet compatibility a priority for digital platforms. Users increasingly expect the same level of functionality on mobile devices as they receive on desktop computers. Fast-loading pages, responsive layouts, and simple navigation contribute to a more efficient mobile environment. A platform such as Casino Betscore, that performs consistently across devices, can better accommodate changing user habits and preferences.
Easy account management is another factor that contributes to overall usability. Users value quick access to account details, preferences, and security settings without having to navigate through multiple pages. When these features are clearly organized and easy to locate, routine account management becomes more efficient. This can improve overall satisfaction and reduce unnecessary complexity during everyday use.
User expectations continue to rise as digital services evolve. Casino Betscore operates in a space where speed, accessibility, clear design, multilingual support, and mobile compatibility are becoming increasingly important.
Online casino users often compare platforms based on how easily they can access information and navigate available features. As the industry continues to develop, user-friendliness remains one of the most important factors influencing how an online platform is perceived and evaluated.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 9, 2026 | NCFA Fintech Market Activity | Payments And Market Infrastructure
On June 9, 2026, Lloyds launched Lloyds Accept, a new suite of payment tools powered by Stripe and built into Lloyds' Business Account for UK small businesses.
The launch puts fintech payment infrastructure inside a major bank's SME account relationship. Lloyds says the service gives business customers access to in person payments, online payments, invoicing, payment links, and reporting from one account environment.
Lloyds brings the customer base and banking relationship, while Stripe brings merchant payment infrastructure, onboarding, acceptance, and developer led tools. Lloyds Banking Group says it serves 26 million customers, giving Stripe access to a large UK banking channel without competing for every merchant relationship directly.
Stripe's 2025 annual update confirms that businesses on its platform generated $1.9 trillion in total payment volume, up 34% from 2024. The company also expanded UK products in 2024, including Pay by Bank and business financing, showing expansion into account based payments, working capital, and SME financial operations.
Lloyds is adding specialist payment infrastructure inside its own SME banking relationship instead of building every part itself. Payment acceptance is the visible feature, but onboarding, reconciliation, reporting, fraud controls, financing, and embedded workflows create the larger infrastructure opportunity. Canadian banks are also partnering for merchant payment infrastructure, which shows the same bank fintech execution pattern in another market.
So where is the value accumulating? Banks still control the customer account, balance sheet, trust, and distribution channel. Infrastructure providers increasingly control the operations that powers day to day business activity. That creates practical opportunities around merchant onboarding, payment operations, treasury tools, fraud controls, and business automation, which connect naturally to NCFA’s Financial Innovation Map.
As banks rely more on specialist infrastructure partners, who will own the most valuable parts of the SME relationship? The account, the payment workflow, the operating data, or the tools that help small businesses manage cash flow.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 9, 2026 | NCFA Fintech Market Activity | Lending Consumer Credit And BNPL
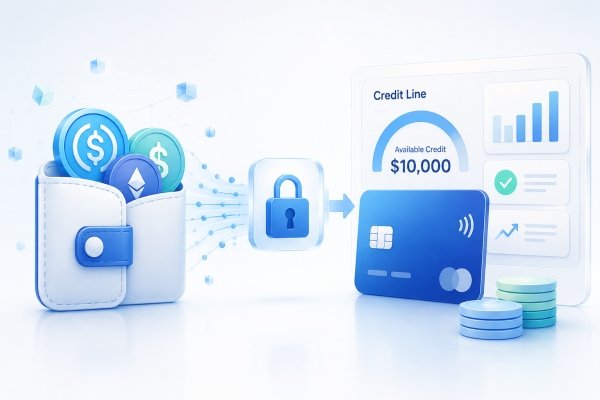
On June 9, 2026, Coinbase announced that it's expanding the role of USDC inside its financial ecosystem by a new Coinbase One Card program that allows eligible customers to secure a credit card with USDC held on the platform. Coinbase says the card can serve customers who might not qualify for a traditional unsecured credit card while continuing to participate in the Coinbase ecosystem.
The product adds another use case to a stablecoin that already supports trading, payments, transfers, rewards, and savings. Coinbase's documentation confirms the USDC security deposit model, where customers use USDC as collateral to secure their credit line.
The launch also highlights how fintech infrastructure providers are helping digital asset platforms expand into traditional financial products. According to a Cardless case study, Coinbase uses Cardless to power card program infrastructure, application workflows, servicing, and payment experiences. First Electronic Bank issues the card and American Express provides network access. The arrangement allows Coinbase to focus on customer acquisition, account balances, rewards, and product design while specialized partners handle card infrastructure and issuance.
Coinbase already has significant card activity to build from. In its Q4 2025 shareholder letter, the company reported nearly $800 million in cumulative Coinbase One Card spend and approximately $3,000 in average monthly spend per cardholder. The same filing reported $17.8 billion in average USDC balances held across Coinbase products.
The strategy aligns with the effort to make digital assets usable beyond trading. Earlier this year, Coinbase partnered with Better to bring crypto assets into mortgage workflows, allowing qualified borrowers to use digital assets during the home financing process. Together with the new card program, Coinbase is steadily expanding how digital asset balances can support borrowing, spending, and credit access.
The scale behind that strategy continues to grow across industry. Circle reported in its Q1 2026 results that USDC reached $77.0 billion in circulation and processed $21.5 trillion in onchain transaction volume during the quarter. As stablecoin infrastructure matures, questions around collateral design, credit access, and lending increasingly connect to broader discussions around tokenized collateral and cash.
If stablecoins can secure credit, platforms with large customer balances gain a new way to compete for lending relationships. The bigger question is whether consumers increasingly view stablecoin holdings as spending power, borrowing collateral, and financial reserves rather than simply digital payment assets?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 9, 2026

Going public puts every control your fintech owns or outsources under a microscope. Auditors, regulators, and future shareholders want hard evidence that third-party weak spots cannot derail your debut.
Roughly 30% of breaches trace back to external suppliers, and each incident costs an average $4.44 million, according to IBM's 2024 Cost of a Data Breach Report. Advisers preparing S-1 filings increasingly want a repeatable way to assess outside cyber risk before the SEC asks, and investors read disciplined third-party oversight as a proxy for operational maturity.
Here is the catch: your SOC 2 program alone will not clear the public-company bar. SOC 2 demonstrates protection of customer data, while SOX 404 focuses on financial-reporting integrity. A purpose-built vendor-risk platform bridges that gap by connecting vendor security evidence to the controls auditors expect in an IPO cycle. We ranked five platforms on the criteria that matter most for IPO prep: compliance fit, automation depth, auditor acceptance, and cost-to-value.
We started with fifteen tools from analyst waves, forums, and twenty competitor write-ups, then removed anything lacking a purpose-built vendor-risk module or fintech case study, leaving five contenders. We scored each on a 100-point scale across four questions:
Two CISOs who took fintechs to market last year reviewed the weighting, confirming it reflects where auditors press hardest.
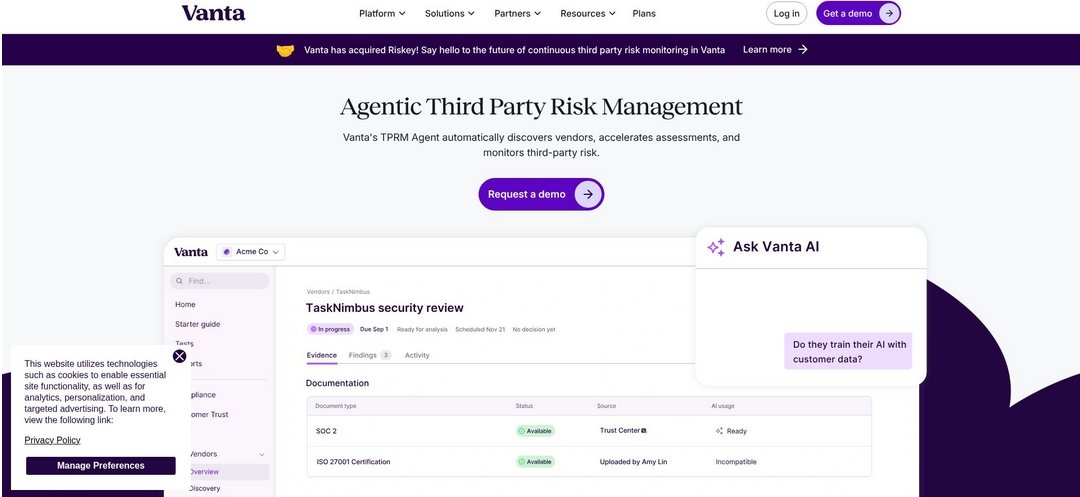
Vanta folds vendor oversight into the same dashboard you use for SOC 2, helping teams remediate risk up to 45% faster. VRM, compliance automation, Trust Center, and SOX ITGC live in one system with shared evidence and cross-framework mapping.
Verdict: best fit if your IPO plan needs one platform to run SOC 2, stand up SOX ITGC, and operationalize vendor oversight. If you need managed analyst services or board-ready vendor portfolio reporting, compare TPRM-specialized options.
Optro rebranded from AuditBoard in March 2026. It keeps the same product family public-company SOX teams know: SOXHUB (SOX program management), CrossComply (multi-framework compliance), and a connected TPRM module. More than half of the Fortune 500 use it, and it is one of the most common SOX systems Big Four auditors are comfortable testing.
Verdict: choose Optro if full SOX 404 depth (ITGC plus financial process controls) and audit-firm fluency top your list. For SOC 2 day-to-day, a Trust Center, and AI-compressed vendor reviews, you will likely pair it with another platform.
OneTrust grew from privacy management into a broad GRC suite with a substantive third-party risk module, serving 14,000+ customers across regulated industries. It fits when vendor oversight has to live next to privacy, ethics, and ESG in one control fabric.
Verdict: right when vendor risk must sit alongside privacy, ethics, and ESG in one enterprise fabric and you can absorb a longer rollout. To consolidate SOC 2, SOX ITGC, and AI-assisted reviews into one fast-moving platform, OneTrust typically needs pairing.
Prevalent is a pure-play TPRM platform with more than two decades of specialization, acquired by Mitratech in October 2024 and rated a Strong Performer in Forrester's Third-Party Risk Management Wave (Q1 2026). It is the heavyweight option when vendor risk itself is the program.
Verdict: choose Prevalent for bank-style TPRM depth, broad regulatory mapping, and multi-domain continuous monitoring. To collapse SOC 2, SOX ITGC, and vendor oversight into one platform, expect to add complementary tools.
Venminder is a TPRM platform for regulated financial-services teams that want to outsource a share of vendor due diligence. It pairs software with managed services where certified analysts review vendor materials and deliver risk-rated outputs. Venminder was acquired by Ncontracts in September 2024 (Hg Capital-backed); it has 1,200+ customers, and the combined entity serves 5,000+.
Verdict: strong when capacity and expertise are the constraint and you want platform-plus-analysts diligence with contract oversight. To consolidate SOC 2 evidence, SOX ITGC, and VRM into one system, Venminder adds tool sprawl rather than reducing it.
In most fintechs, SOC 2 lives with Security and SOX 404 with Finance, and your vendors sit in the overlap. Treat them as two programs and you get two inventories and two sets of audit questions that never reconcile. Build one vendor register that serves both audits instead.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 8, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech
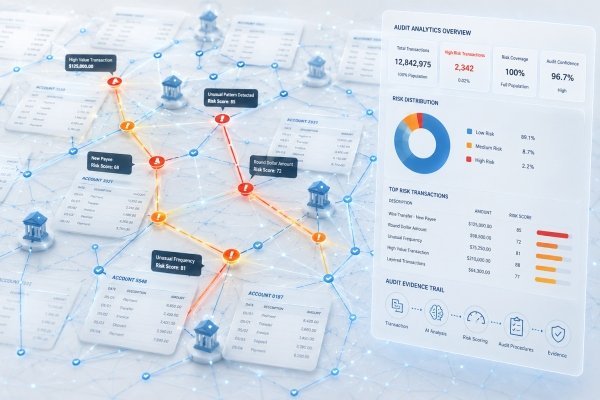
On June 8, 2026, Ottawa based MindBridge expands its AI audit and assurance platform to help audit teams review larger transaction populations and assess risk faster. The update adds full population analysis, subledger analysis, a Monetary Flow Dashboard, transaction level risk assessment, duplicate transaction controls, and large file processing.
MindBridge says KPMG deploys its platform through a global audit platform used in more than 60 countries. The company also points to recent partnerships with BDO and Buzzacott.
Sarah McGinnity, General Manager, Audit & Assurance Solutions at MindBridge:
“Audit and assurance teams are being asked to oversee larger transaction populations, more complex systems, and increasingly automated financial processes without adding proportional time or resources.”
The most important part of the announcement is the focus on full population analysis.
Audit teams have traditionally relied on sampling. AI driven software now makes it possible to review entire transaction populations and identify unusual activity across much larger data sets. That can help auditors spend less time searching for issues and more time investigating the transactions that matter.
MindBridge is positioning its platform around that shift. The latest release gives users more visibility into transaction flows, subledger activity, and risk indicators across financial records.
Many AI products compete on productivity. MindBridge competes on audit quality, risk assessment, and financial controls.
It alters the buying decision. Audit firms, finance teams, and regulated organizations already need oversight, documentation, and evidence. They aren't looking for experimentation. They're looking for better ways to review growing volumes of financial data.
The trend extends beyond audit. Financial institutions are adopting AI in compliance, fraud detection, transaction monitoring, and operational risk. As NCFA noted in its coverage of regulated AI controls and governance, buyers increasingly want systems that support human judgment and provide a clear record of how decisions are made.
If audit software can test full transaction populations instead of samples, the value changes from finding anomalies after the fact to proving where financial risk may occur before judgment calls are made. That's where AI audit tools become useful to CFOs, auditors, and regulators: not as automation, but as evidence infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016