





Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


June 9, 2026 | NCFA Fintech Market Activity | Lending Consumer Credit And BNPL
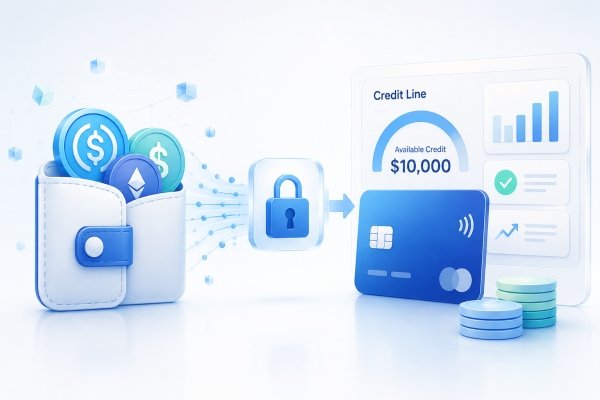
On June 9, 2026, Coinbase announced that it's expanding the role of USDC inside its financial ecosystem by a new Coinbase One Card program that allows eligible customers to secure a credit card with USDC held on the platform. Coinbase says the card can serve customers who might not qualify for a traditional unsecured credit card while continuing to participate in the Coinbase ecosystem.
The product adds another use case to a stablecoin that already supports trading, payments, transfers, rewards, and savings. Coinbase's documentation confirms the USDC security deposit model, where customers use USDC as collateral to secure their credit line.
The launch also highlights how fintech infrastructure providers are helping digital asset platforms expand into traditional financial products. According to a Cardless case study, Coinbase uses Cardless to power card program infrastructure, application workflows, servicing, and payment experiences. First Electronic Bank issues the card and American Express provides network access. The arrangement allows Coinbase to focus on customer acquisition, account balances, rewards, and product design while specialized partners handle card infrastructure and issuance.
Coinbase already has significant card activity to build from. In its Q4 2025 shareholder letter, the company reported nearly $800 million in cumulative Coinbase One Card spend and approximately $3,000 in average monthly spend per cardholder. The same filing reported $17.8 billion in average USDC balances held across Coinbase products.
The strategy aligns with the effort to make digital assets usable beyond trading. Earlier this year, Coinbase partnered with Better to bring crypto assets into mortgage workflows, allowing qualified borrowers to use digital assets during the home financing process. Together with the new card program, Coinbase is steadily expanding how digital asset balances can support borrowing, spending, and credit access.
The scale behind that strategy continues to grow across industry. Circle reported in its Q1 2026 results that USDC reached $77.0 billion in circulation and processed $21.5 trillion in onchain transaction volume during the quarter. As stablecoin infrastructure matures, questions around collateral design, credit access, and lending increasingly connect to broader discussions around tokenized collateral and cash.
If stablecoins can secure credit, platforms with large customer balances gain a new way to compete for lending relationships. The bigger question is whether consumers increasingly view stablecoin holdings as spending power, borrowing collateral, and financial reserves rather than simply digital payment assets?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |



August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016

Leave a Reply