




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Bank of Canada Research | Nov 14, 2025
Image: Perceived interconnections between banks and NBFIs (Bank of Canada Staff Report, November 2025)
On November 13 2025, the Bank of Canada Staff published Analytical Note 2025-26 titled, "Perceived interconnections between Canadian banks and non-bank financial intermediaries under stress" (16 page PDF), that examines how stress spreads between banks and non-bank financial intermediaries (NBFIs) such as investment and mortgage funds. While the research found that market-based linkages between banks and non-banks have grown much stronger over the past decade, it offers no specific policy steps.
For Canada’s fintech and regulatory communities, that leaves room to build smarter transparency and data-driven tools that improve resilience while encouraging innovation.
The Bank used a market-based metric called the ratio of tail sensitivities to track how often banks and NBFIs experience stress at the same time. In simple terms, it measures how likely both sectors are to face sharp losses together when markets turn volatile.
Before the pandemic, that overlap was around 60%, meaning stress in one sector often stayed contained. During 2020 (Covid-19), the overlap jumped to almost 90%, showing that both banks and NBFIs were hit by the same shocks at once.
Post Covid-19, it has stayed above 70%. This signals that Canada’s financial system now behaves more like a single network where investor confidence, liquidity, and risk pricing can ripple quickly across different parts of the market.
The analysis relies on market indicators such as price changes and co-movement ratios. These signals show how banks and non-banks react to market stress, but they don't track the underlying funding flows, repo exposure, or off balance sheet commitments that reveal how those stresses move in practice. The Bank acknowledges that data gaps make it hard to see how financial stress truly spreads between institutions.
The research measures perceived connections through statistical patterns rather than verified, real time data linkages. That distinction matters. Without deeper, connected data, it is harder to see where vulnerabilities are forming or how quickly they could spread. Closing that gap doesn't necessarily require new regulation but better tools and shared information that improve resilience while encouraging innovation.
Regulators already monitor funding and liquidity in near real time, but the Bank of Canada notes that current data still do not explain how financial stress moves between different parts of the system. The missing piece is insight into how one market’s strain can quickly affect another’s ability to function.
For example, if liquidity tightens in the mortgage or bond market, investment funds might sell assets to meet investor redemptions. Those sales can push down prices, reducing the value of collateral that banks use for their own lending and funding. Within hours, what starts as a localized funding issue can spread to other sectors that rely on those same assets. Economists have long modelled this type of stress transmission, but those models depend on historical or aggregated data. They show how shocks can travel but not how fast they move in real time.
RegTech innovation could help close this gap. Shared data platforms, digital reporting tools, and secure analytics could give both regulators and market participants a clearer view of where risks are forming. Instead of expediting new rules, the opportunity is better information that allows for faster, better, data-driven action. Fintechs can play a leading role by designing systems that make oversight smarter, not heavier, while strengthening confidence across the financial system.
If Canada wants to maintain stability and support innovation, it needs visibility into where financial pressure builds. The Bank of Canada's findings show that perceived connections already move markets but without deeper real-time data access, those perceptions could harden into real stress events. The opportunity is to turn perception into understanding and make transparency Canada’s real advantage.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
AI | Nov 13, 2025
In October 2025, the Center for Security and Emerging Technology (CSET) released a report called, "The Mechanisms of AI Harm", that breaks down how artificial intelligence can cause harm through predictable pathways. The study found that most failures stem not from malicious use but from system design, biased data, and weak oversight.
CSET warns that as AI systems spread through banking, healthcare, and infrastructure, the harm becomes self-reinforcing. Each model learns from the last, compounding flaws over time. The problem is not bad actors but feedback loops that quietly scale risk. Governance is lagging behind by years, while the pace of model deployment grows monthly.
In Detroit, a police facial recognition system wrongly identified Robert Williams, leading to a false arrest that eroded public trust in the technology meant to improve safety.
An MIT article found that error rates for darker-skinned women reached 34% compared with less than 1 % for lighter-skinned men. These disparities reveal structural bias baked into training data and feedback systems.
Across Europe, the EU AI Act now treats such failures as foreseeable harms requiring traceability and documentation.
In the United States, federal regulators have begun enforcement actions against companies using opaque algorithmic decisions.
Canada’s proposed Artificial Intelligence and Data Act (AIDA) remains under parliamentary review and was impacted by prorogation in January 2025, leaving gaps between good intentions and enforceability, read the death of AIDA. Policymakers now are debating how AI accountability should evolve.
Many Canadian financial institutions already use machine learning to underwrite credit, detect fraud, and screen clients. Yet few publicly document how models are tested for bias or explainability. The Office of the Superintendent of Financial Institutions (OSFI) Guideline E-23 on Model Risk Management (2027) outlines how financial institutions should govern advanced analytics and AI models, including validation, bias testing, and accountability expectations, but without enforcement the framework still relies on internal discretion.
Regulators acknowledge the need for governance but lack consistent mechanisms to test, benchmark, or verify models across industries. The result is a patchwork system where AI tools can operate with little external visibility. Each institution assumes its safeguards are sufficient, even though no one has a full view of the risk landscape.
CSET’s model shows harm accumulates when oversight is fragmented. A 2024 OSFI-FCAC Risk Report on AI Uses and Risks at Federally Regulated Financial Institutions found that many financial institutions rely on third-party AI systems without full audit access or validation rights, which means models can change without regulators or even clients knowing. These dependencies create silent risk channels within the financial ecosystem.
And in Europe, a Europol “Facing reality? Law enforcement and the challenge of deepfakes” report cautions that deep-fake technology is proliferating rapidly and posing new risks for fraud, misinformation, and market manipulation. Each failure feeds the next, so it creates a feedback loop of risk spreading across jurisdictions and markets.
Regulators and financial institutions have a limited window to close the governance gap before public trust erodes. The real challenge is not whether to slow innovation, but how to steer it responsibly. CSET’s findings suggest that effective AI governance must protect stakeholders while allowing systems to improve and scale safely. Overregulation can push innovation into unregulated spaces, but weak oversight leaves markets exposed to preventable harm.
CSET’s framework shows that AI harm grows from feedback loops where technical design, human behaviour, and oversight interact. Preventing harm means building governance that evolves at the same pace as the systems it regulates. The question is not whether AI will cause harm, but whether leaders will move fast enough to limit it. Accountability cannot be automated. It must be led.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Alternative Assets | Nov 12, 2025
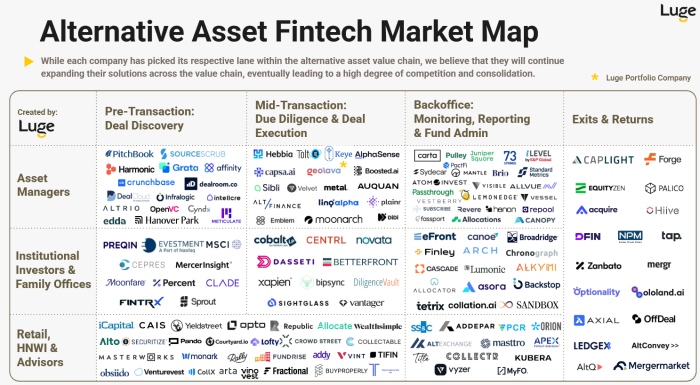
Image: State of Alternative Assets: A Fintech Perspective (Luge Capital, Nov 2025)
On November 11, 2025 Luge Capital published an informative report titled "2025 State of Alternative Assets: A Fintech Perspective'. Global Alternative Assets (Alts or AltAssets) reached $19 trillion in 2023 and could grow to $33 trillion by 2030, per the report's analysis of verified data from Preqin, BCG, and Deloitte.
Private equity and private credit stand out as the biggest categories but behind this growth, fintech companies are quietly rebuilding how money is raised, managed, and circulated across private investments.
Laviva Mazhar, a Principal at Luge Capital and Author of the report, compares what's happening today to the early computerization of trading desks. Manual processes are being replaced by connected systems that make private markets work more smoothly.
New companies are designing tools that handle every step of the process, from AI-supported deal sourcing and due diligence to data collection and performance reporting. The report names Canoe Intelligence (U.S.), 73 Strings (India), and Mantle (Canada) among the firms setting new benchmarks for automation.
Large players such as BlackRock, iCapital, and Hamilton Lane are also expanding through partnerships and acquisitions, bringing these innovations into the mainstream.
Private equity assets under management reached $5.8 trillion in 2023, while private credit is expected to reach $2.6 trillion by 2029. The number of U.S. companies backed by private equity has climbed 490% since 2000, validating how deep private capital is supporting business growth.
Company buyouts or public companies being taken private off the stock market increased 32% year over year, pointing to strong investor appetite for longer-term ownership. Across North America $297 billion has flowed into 7,300 private Canadian companies since 2013, backed by the shared strength of regional investment ecosystems.
Luge reports that 86% of institutional investors already allocate to alternatives, but individual investors are beginning to play a larger role. Assets from the wealth channel in the U.S. are projected to more than double to $3 trillion by 2029.
Fintech platforms like iCapital (U.S.), Yieldstreet (U.S.), and Opto Investments (U.S.) are developing digital pathways that make it easier for people to participate in funds once reserved for large institutions. This growing inclusion is one of the strongest patterns Luge identifies across the market.
According to Luge, the biggest opportunities now lie in the systems that connect private markets together. These include data sharing networks, portable investor identity tools, and liquidity platforms for secondary trading. The report also highlights a new class of software that helps fund managers handle onboarding, compliance, and reporting in one place. These initiatives are setting the stage for a more open and efficient investment environment.
Fintech companies that make it easier to access capital, reduce paperwork, and build trust are helping the global economy work better. This focus mirrors NCFA Canada’s commitment to supporting innovation, inclusion, and competitiveness through responsible market design that benefits investors, businesses, and communities alike. Download Luge Capital's latest report on the State of Alternative Assets in 2025 and/or subscribe to NCFA's weekly newsletter.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Digital Assets | Nov 12, 2025
On November 5, 2025 CoinGecko published a comprehensive 2025 Digital Asset Treasury Companies Report unveiling the trends, rankings and strategies of mainly public companies that are increasingly adding digital assets to their balance sheets.
The report outlines three types of public DATCos including (1) Crypto mining firms (i.e., MARA Holdings), (2) Pure play firms whose sole purpose is to accumulate crypto assets (i.e., Strategy or Bitcoin Treasury Corp), and (3) Companies with crypto reserves (i.e., Bitfarms Ltd), with the full source data being available in the report along with CoinGecko's Treasuries Tracker (NB: includes government holdings in rankings).
CoinGecko’s data shows the number of Digital Asset Treasury Companies expanding from just 4 in early 2020 to 142 by October 2025. Total holdings rose from about $30 million to $137.3 billion USD, more than doubling in 2025 alone.
Bitcoin represents about 82.6 % of total holdings, Ethereum 13.2 %, and Solana 2.1 %, with the rest spread among smaller tokens. The United States leads with 60 companies; Canada ranks second with 19, reflecting its strong base of listed miners and crypto firms.
The takeaway is that public companies are increasingly adding digital assets to their balance sheet. Below are highlights of the ins and outs of how they do it, and some lessons learned.
CoinGecko traces Strategy’s transformation from a software company into the world’s largest corporate Bitcoin holder. Since pivoting in August 2020, Strategy has acquired about 640,800 BTC, roughly 3 % of total Bitcoin supply, and now manages holdings exceeding $70 billion USD.
The company funded these purchases through a mix of equity offerings, bond issuances, and preferred shares. Its stock has traded at premiums to its Bitcoin net asset value during parts of 2024, underlining investor appetite for exposure to corporate crypto reserves.
CoinGecko tracks at least $42.7 billion USD in new crypto purchases by DATCos between January and October 2025, with more than half occurring in the third quarter. Bitcoin accounted for roughly 70 % of total spend, Ethereum for 18 %, and Solana led among smaller allocations.
This acceleration reflects growing comfort with digital assets as long-term treasury instruments rather than short-term speculative holdings.
As of November 2025, Strategy leads with $70.7 billion USD in Bitcoin. BitMine Immersion ranks second with combined Ethereum and Bitcoin holdings of $12.9 billion USD, followed by Sharplink, a major Ethereum holder.
The top group also includes Marathon Digital, Riot Platforms, Coinbase, Galaxy Digital, and Tesla. Together, the top 15 account for most corporate-owned digital assets.
Three Canadian-listed firms, Galaxy Digital, Hut 8 Mining, and Bitfarms Ltd., remain among the most significant international participants, confirming Canada’s status as a leader in Bitcoin and Ethereum treasury adoption. Both Galaxy Digital and Hut 8 are listed as U.S. firms on the tracker but they are registered and originated in Canada.
Bitcoin treasuries held by DATCos now total about 1.03 million BTC, equal to 4.9 % of total Bitcoin supply. Strategy alone holds roughly 61.5 % of that amount.
Ethereum holdings across DATCos reached 4.7 million ETH, or 3.9 % of supply, with BitMine Immersion responsible for about 69 % of the total.
Solana treasuries rose to 15.9 million SOL, about 2.9 % of supply. Forward Industries’ $1.65 billion purchase of 6.8 million SOL in September 2025 represents nearly half of all corporate Solana reserves.
CoinGecko documents four key financing methods that DATCos have been using to acquire crypto assets:
Together, these options spotlight structured financing strategies that balance investor access with risk control.
mNAV compares a company’s market capitalization to the value of its crypto holdings, which acts as a sustainability barometer. When mNAV falls below 1.0, raising new equity dilutes shareholders rather than adding value.
CoinGecko found several DATCos near or below that threshold in late 2025. As a result some companies paused new acquisitions, while others turned to preferred shares or buybacks to stabilize their valuations.
CoinGecko’s report offers several clear lessons from 2025’s wave of funding stress and consolidation among crypto treasury companies.
When a company’s share price falls and its mNAV drops near or below 1.0, equity financing becomes uneconomical. Semler Scientific (SMLR) faced this in mid-2025, as weak stock performance made new issuance impossible and a shareholder vote to authorize preferred shares failed.
With no viable financing options left, Semler merged with Strive in September 2025. Consolidation often becomes the only path forward when market access closes.
After the merger Semler relied on preferred equity but its combined valuation still dropped by about 80 %, showing that preference structures help liquidity but not long-term confidence.
Across all DATCos, outstanding debt stood near $12.7 billion USD, which is modest compared with roughly $200 billion USD in crypto assets, leaving space for responsible borrowing to reduce reliance on stock issuance.
Companies use buybacks or issue preference shares to support valuations when mNAV weakens. ETHZilla even sold Ethereum in October 2025 to fund a buyback (a rare reversal of the usual accumulation pattern).
Several DATCos saw share prices surge briefly after announcing digital asset strategies, then retreat as fundamentals reasserted themselves. Some cases drew regulator scrutiny for pre-announcement trading. Companies should not base treasury policy on short-lived market premiums.
Strategy’s perpetual preferred shares attract investors through structured yields, but questions remain when dividends are financed by new share issuance. Transparent funding disclosure maintains credibility.
At a time when Canada's policymakers are creating stablecoin rules, it can learn from these global cases by allowing fair-value accounting for digital assets, enabling multiple funding tools, and setting clear disclosure standards. Canada’s listed mining and fintech firms already play a leading role in corporate crypto adoption. Yet few non-mining public companies have introduced digital reserves.
By updating accounting rules, modernizing treasury disclosure, and piloting a Digital Treasury Sandbox, regulators could enable more smaller scale companies with well-governed asset allocations to improve competitiveness and financial resilience. Digital assets are now a recognized part of global corporate finance. Bitcoin remains the anchor, while Ethereum and Solana continue to gain traction.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Policy | Nov 11, 2025

Image: Relative labour productivity Canada vs US (Source: CSLS 2025)
The Centre for the Study of Living Standards released a November 2025 report titled, "Can a Lack of Pro-Productivity Policies Explain the Secular Decline in Canada’s Productivity Growth?", outlining why Canada’s productivity growth has stalled even as macroeconomic policy remains stable. The study finds that steps in the 2025 federal budget while positive, will not by themselves reverse the long slowdown. The authors argue that deeper structural change is needed to rebuild the foundations of business investment and innovation in Canada.
The report traces much of the post 2015 slowdown to long term structural and global factors that are as a result of how past policy choices influenced business behaviour. Verified causes that reduced the total investment per worker and limited productivity even as macro conditions stayed the same include:
Evidence from major institutions supports this view. The analysis in the OECD 2025 Economic Survey of Canada and the IMF 2024 Article IV consultation finds that Canada’s productivity gap reflects long standing frameworks that influence how firms invest and compete. These findings show that the challenge is structural, a long term misalignment between national policy intent and firm level behaviour.
The recently announced Budget 2025 aims to address parts of Canada's productivity, innovation and competition gaps. It includes improvements to the Scientific Research and Experimental Development program by increasing the annual expenditure limit for the enhanced credit to $6 million, restoring eligibility for capital expenditures, and extending eligibility to Canadian public corporations. These measures target investment in intangible assets and innovation, the areas identified as weak.
The budget also commits over $1 billion in resources over five years for AI compute and quantum computing while proposing a TechStat program to track technology adoption, as described in the digital infrastructure plan.
Finally, the budget also advances open banking and stablecoin rules that can improve competition and trust.
Productivity growth depends on what happens inside firms, how they invest, adopt technology, and organize production. Canada’s frameworks have been stable but haven't created strong enough conditions for private reinvestment in digital and intangible assets.
When policy creates the right incentives and financial infrastructure removes friction, investment decisions shift. That alignment between public objectives and private behaviour is where lasting productivity growth emerges.
Canada’s weakness lies in underinvestment in intangible assets such as software, data, intellectual property, and organizational know how. Past tools have not reversed this pattern and Canada needs to reward reinvestment in intangible and digital assets. NCFA has argued for tax credits that mobilize private capital for innovation for years including in an open letter to government during the COVID 19 pandemic, urging government to collaborate with fintechs while proposing investment tax credits to crowd in private capital.
The United Kingdom’s Enterprise Investment Scheme (EIS) offers a clear example of how targeted tax relief can mobilize private capital into early-stage ventures. Since its launch in 1994, the EIS has attracted over £30 billion of private investment into more than 53,000 small and growing companies, according to HM Revenue & Customs.
The EIS program provides individual investors with income tax relief of up to 30% on investments in qualifying startups, along with capital gains deferrals. Analysts credit it with strengthening the UK’s innovation ecosystem and building one of the world’s most active early-stage funding markets.
Reducing interprovincial barriers and boosting competition are valuable but not sufficient on their own. The next step is to modernize how policy and firm level decisions connect. Fintechs can help turn policy into practice by improving access to capital, ensuring reliable and interoperable data, and scaling innovation across the economy. That's how Canada can turn structural reform into more practical and realized productivity gains.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Payments Report | Oct 30, 2025
Image: The Future is (Anything but) Stable (BCG Global Payments 2025 report)
On Sept 22, 2025 the Boston Consulting Group (BCG) released the Global Payments Report 2025 titled 'The Future is (Anything but) Stable" (37 page PDF report) reported that worldwide payment revenues totalled about $1.9 trillion in 2024 and are expected to exceed $2.4 trillion by 2029.
Growth is slowing however from nearly 9% a year to around 4%, highlighting the end of a rapid growth period where payment providers earned more interest income on money moving through their systems. The next phase will be led by innovation, not momentum.
According to the report, the foundations of global payments are being rebuilt through real-time transactions, tokenized assets, and smarter compliance. For Canada, the domestic system is stable but slower than peers in Asia or Europe. Modernization can help ensure that Canadian fintechs and banks remain competitive as value begins to move across programmable digital networks.
These above trends describe a payments ecosystem that is no longer growing by size but by sophistication.
Between pages 9 and 13, the report explains that tokenization has moved from pilot projects to real adoption.
Stablecoins process over $26 trillion in yearly transactions and are being used for remittances, business payments, and treasury operations. The combined value of circulating stablecoins is close to $270 billion, with US dollar-linked tokens like USDT and USDC dominating.
Tokenized funds hold more than $3 billion in assets, and private credit tokenization has reached $10 billion. In addition, governments in Singapore, Hong Kong, and Europe are issuing digital bonds under clear frameworks such as MiCA.
More than 10 countries have live central bank digital currencies, and over 90% of central banks are testing or building them. Global banks including Citi, HSBC, and UBS are already piloting tokenized deposits connected to their main systems.
For Canada, tokenization could open the door to trusted digital assets that fit within the existing regulated structure. It allows for faster, safer movement of money and investment while maintaining transparency and oversight. By building policy alignment and open access, Canada can turn this technology into a tool for inclusion, without being left behind.
The report points to a global race to connect innovation with regulation. Countries that create clarity around digital assets, tokenized deposits, and real-time infrastructure will attract investment and improve access to capital. For Canada, this means progressing digital finance policy and expanding participation in global payment corridors. The combination of tokenized assets, instant settlement, and data-driven compliance could give Canadian participants a stronger role in international markets.
Canada is already making strides in payments innovation. The Bank of Canada and other regulators are working to bring more providers onto national infrastructure and exploring tokenisation and stablecoins. With the federal 2025 budget scheduled for early next week on November 4, there is hope that policymakers will signal clearer guidelines or incentives for stablecoins and digital assets that could boost competitiveness and access to capital for Canadian fintechs.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech | Oct 28, 2025
Image: Freepik/starline
On October 23, 2025, Deloitte Canada released its annual 2025 Technology Fast 50 rankings, recognizing the country’s fastest growing innovators based on verified three-year revenue growth from companies that self-submitted their data for evaluation. The program celebrates excellence across technology, media, and telecommunications sectors, including fintech, AI, clean technology, software, and cybersecurity.
Calgary-based Neo Financial achieved the first ever three-peat by ranking first in the Enterprise Industry Leaders category three years in a row, with an outstanding 1,279% growth, providing credit cards, everyday accounts, high interest savings accounts (HISA) and mortgages to over one million Canadian clients.
Andrew Chau, CEO & Co-Founder, Neo Financial:
"While we didn't get into this business for the awards, this recognition serves as yet another example of the need for modern, rewarding financial experiences among Canadians. It's something legacy institutions have failed to deliver for far too long. We're focused on building financial products that actually help Canadians get ahead. In the last year alone, Neo has saved Canadians more than $110 million in fees, showing what's possible when financial products are designed to give Canadians more, not take more."
The 2025 results highlight how fintech, automation, and AI are powering Canada’s innovation economy. NCFA congratulates all of this year’s Fast 50 winners and invites readers to explore the breakdown of fintech and AI leaders featured in Deloitte’s report below. Together, these companies represent the innovative edge of Canada’s fintech and AI economy, and are at the forefront of technology, talent, and trust as they continue to drive financial innovation.
Recognizes Canada’s fastest-growing technology firms by three-year revenue growth.
| Company | Rank | Growth % | Overview |
|---|---|---|---|
| CapIntel | 2 | 9,255% | Wealth technology helping advisors deliver better investment presentations. |
| Float | 9 | 5,601% | Fintech offering corporate cards and spend management tools. |
| Relay | 12 | 4,257% | Business banking platform providing cash visibility and team controls. |
| nesto | 13 | 4,074% | Digital mortgage lender offering fully online approvals and funding. |
| Novisto | 15 | 2,910% | ESG data and reporting software for companies and investors. |
| ZayZoon | 22 | 1,487% | Earned wage access provider improving employee financial wellness. |
| Apaylo | 37 | 648% | Payments infrastructure offering EFT, wires, and business banking rails. |
| Flare | 38 | 639% | Cybersecurity platform monitoring and reducing digital exposure risk. |
| Zensurance | 41 | 601% | Online insurance brokerage simplifying coverage for small businesses. |
| Forma.ai | 44 | 573% | AI-driven automation for sales compensation and performance planning. |
| Conquest Planning | 46 | 542% | AI financial planning platform for advisors and institutions. |
| BOXX Insurance | 49 | 512% | Cyber insurance provider combining coverage with digital risk tools. |
| OWL.CO | 50 | 499% | AI analytics for insurers to detect fraud and improve risk decisions. |
Celebrates large technology companies demonstrating strong three-year growth in revenue and scale.
| Company | Rank | Growth % | Overview |
|---|---|---|---|
| Neo Financial | 1 | 1,279% | Consumer banking platform with credit cards, savings, and mortgages. |
| KOHO | 2 | 559% | Everyday banking alternative with prepaid credit, savings, and credit build. |
| Financeit | 4 | 355% | Point-of-sale financing that helps merchants offer installment plans. |
| Lightspeed | 6 | 318% | Commerce platform for retailers and restaurants with embedded payments. |
| Hopper | 9 | 282% | Travel marketplace with fintech products that reduce price risk for users. |
| Propel Holdings | 10 | 279% | Public fintech that provides credit access through digital channels. |
| Clutch | 12 | 266% | Online auto platform with financing options at checkout. |
Highlights high-growth emerging firms on track for future Fast 50 placement.
| Company | Rank | Growth % | Overview |
|---|---|---|---|
| Optable | 5 | 761% | Privacy-first data clean room that enables secure audience collaboration. |
| FundMore | 6 | 708% | AI mortgage platform that automates underwriting and decisioning. |
| Quandri | 8 | 664% | Automation software that removes repetitive work for insurance agencies. |
| WonderFi | 9 | 535% | Crypto company operating regulated Canadian digital asset exchanges. |
And in connecting with the FundMore team, they are incredibly proud of their work and mission to help lenders fund more, faster. Chris Grimes, CEO FundMore said (Listen: Fintech Fridays EP43: Taking the Mortgage Process From 40 Days to Minutes):
“This recognition reflects the tireless work of our entire team and our mission to help lenders fund more, faster. I couldn’t be prouder of what we’ve built, and where we’re headed."
The 2025 Deloitte Fast 50 results confirm that fintech and AI are no longer niche parts of Canada’s economy. They're defining the future. Neo Financial’s three-peat historical achievement, alongside high growth companies such as CapIntel, KOHO, Float, FundMore, and WonderFi are building financial systems that are more efficient, inclusive, and globally competitive.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016