




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Cybersecurity | Oct 9, 2025
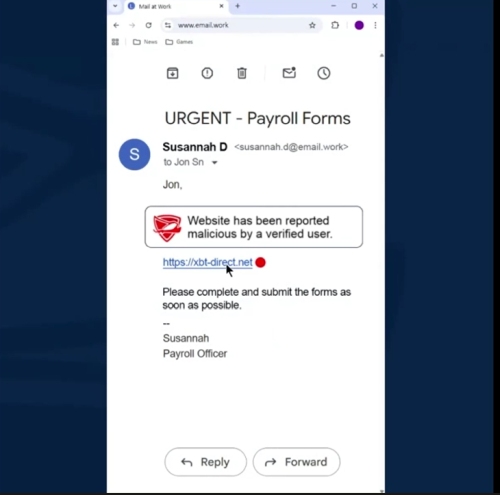
Image: Stingray Security demo image (Winner of ScamShield Challenge, Oct 2025)
On October 9, 2025, the Alberta Securities Commission (ASC) announced that Stingray Security had won first place in the ScamShield: Investor Protection Challenge, a collaborative initiative launched last year by the ASC, Edmonton Police Foundation (EPF), and Edmonton Police Service (EPS).
The challenge was created to find new ways to fight the growing problem of online crypto investment fraud. More than 30 solutions were submitted after the program’s launch in September 2024. Two concepts were chosen to move forward in January 2025, and Stingray emerged as the top solution after further testing and development.
According to the ASC’s January 2025 update, more than 60% of the $309 million in investment fraud losses in 2023 were tied to crypto scams, according to the Canadian Anti-Fraud Centre. There's an urgent need for better tools and collaboration to protect investors.
ScamShield is focused on prevention and education by combining regulatory oversight, community engagement, and fintech innovation. For fintechs, investors, and digital finance leaders, the initiative demonstrates how regulators and entrepreneurs can co-create solutions that build confidence in online markets and reduce fraud risk.
Ron Anderson, CIO/CTO at the Edmonton Police Service Innovation and Information Bureau:
"Online investment scams have emerged as a preferred method for fraudsters, exploiting the public's limited experience in the fast-changing world of digital finance. These crimes are far from victimless – behind every fraudulent scheme are hardworking individuals whose savings have been compromised. As law enforcement, our mission goes beyond holding perpetrators accountable, we must also build public confidence in the integrity of our financial systems. The Stingray Security solution is another powerful tool that investors can use to safeguard themselves and avoid becoming victims of these devastating crimes."
Canadian cybersecurity company Stingray Security developed a browser-based protection tool that identifies risky website links and blocks threats in real time. The product defends users against phishing, fake investment platforms, and other fraudulent activity linked to crypto scams. It is available free of charge and can be downloaded directly from the Google Chrome Web Store. The technology uses in-browser protection to stop malicious activity before harm occurs, offering instant protection for individuals, families, or workplaces.
Ian MacKinnon, co-founder and Chief Technology Officer of Stingray Security:
“We built Stingray so anyone can start using state-of-the-art protection in seconds, whether at work, at home, or to protect loved ones—all for free.”
Programs like ScamShield prove that regulators and entrepreneurs can collaborate to develop practical tools that deliver measurable results for investors and communities. As fraud continues to evolve, public and private cooperation will be essential to maintaining trust in digital markets and strengthening financial resilience coast to coast.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Sep 29, 2025

Image: Freepik/Rawpixel.com
Commercial insurance is a topic that every small business owner must eventually face. Is it worth the investment?
For many, commercial insurance can seem like just another expense on a list already filled with costs.
But look closer, and it becomes clear that commercial insurance is much more than a routine budget item; it is a vital safeguard that can secure the future of a small business against unexpected setbacks.
Small businesses operate with limited resources, which makes them especially vulnerable to unforeseen events. From lawsuits and accidents to theft and cyberattacks, a single incident can cost more than a business can afford to pay out of pocket. Small business insurance like commercial insurance steps in to absorb these shocks, covering legal fees, property repairs, settlements, and medical costs, so business owners aren’t left stranded during emergencies.
Running a small business without insurance is risky. Many entrepreneurs underestimate how frequently claims happen. A customer slipping on a wet floor, a fire damaging inventory, data theft from a cyberattack, these are real scenarios that occur more often than most people realize. Claims like these can easily spiral into six-figure costs, threatening the survival of any business without insurance protection.
One of the most compelling reasons to carry commercial insurance is financial security. Even a minor accident or lawsuit can drain years of savings or hard-earned profits. But there is more: operating without required coverage may expose a business to legal fines, penalties, or even forced closure, depending on local laws and industry regulations. Insurance helps businesses stay compliant, protect their assets, and avoid personal liability, meaning creditors can’t go after owners’ personal property to settle business debts.
Beyond direct financial protection, commercial insurance offers peace of mind that allows owners to focus on growth, rather than worrying about what could go wrong. The right insurance policy signals professionalism and reliability, reassuring clients, partners, and lenders. Many large clients or landlords won’t enter contracts unless a business can show proof of adequate coverage. This trust factor is essential for winning new deals and maintaining long-term relationships.
Additionally, working with an insurance broker can provide valuable support during claims. These experts help navigate paperwork and negotiations, ensuring fair treatment and speedy resolutions. With their guidance, business owners can get back to work faster after a loss and avoid costly mistakes.
Every small business faces unique risks. A restaurant might be concerned about fire or food safety, while a consultancy might worry about professional errors. Common types of commercial insurance include general liability, property protection, and professional liability. It’s important to map risks and buy policies tailored to actual exposures, rather than relying on generic plans or picking coverage based solely on price.
Regular reviews and updates are critical, as coverage should reflect business growth and changes. What worked when a business started may become inadequate as revenue and staff increase. Annual check-ins with a broker can help keep insurance aligned with current needs.
It’s important to know what commercial insurance does not cover. Most policies exclude routine wear and tear, intentional acts, criminal activities, and government fines. Some disasters, like major floods or earthquakes, require separate endorsements. Understanding exclusions allows business owners to add extra protection as needed and avoid surprises during a claim.
For small businesses, commercial insurance is not just worth it; it’s essential. It protects years of hard work and investment, ensures legal and financial security, enhances credibility, and offers expert support in times of crisis. Investing in the right coverage isn’t just good business sense; it’s the key to long-term stability and peace of mind.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulation | Sep 24, 2025

Image: Freepik
On September 13, 2025, Thailand froze approximately 3 million bank accounts in a sweeping anti-scam campaign. Authorities targeted around 177,000 mule accounts linked to fraud. Wisit Wisitsora of Thailand’s Digital Economy and Society Ministry stated:
“We urge the public not to panic. The suspension is only temporary.”
Banks imposed daily transfer caps ranging from 50,000 to 200,000 baht (approx. $2164 CAD - $8657 CAD at today's forex rates) and froze flagged transactions.
Commercial banks could suspend funds for three days, with police empowered to extend freezes up to seven days. While designed to curb online fraud, many individuals and small businesses described being locked out of their only source of funds, leaving households unable to pay for food or bills.
Facing backlash, regulators introduced safeguards. Innocent users can now expect restoration within hours to one day. Banks are required to notify customers of freezes via SMS or mobile banking and to unfreeze wrongly blocked funds proactively. Officials emphasized that disputed amounts are suspended, not entire balances.
Around the world, regulators from the EU to the U.S. and Canada are grappling with similar challenges as regulators expand digital fraud controls. What the Thailand case shows is that the credibility of financial systems depends not only on the strength of anti-scam tools but also on transparent safeguards.
If freezes become a blunt instrument, they risk driving people out of regulated channels and weakening financial inclusion. For fintechs and policymakers, the global lesson learned is that fraud prevention must be paired with due process to preserve trust.
Fraud-related losses in Thailand exceed 6 billion baht annually (approx $200M CAD), but freezing millions of accounts without due process undermines trust in banking.
"The Thai case clearly shows the risk when rapidly scaled enforcement collides with consumer rights. Without transparent criteria, real-time notifications, and clear appeals, innocent users face financial harm."
Legal experts warn this could expose authorities to civil claims and property rights challenges. What if citizens turn to cash, crypto, or unregulated channels instead?
Canada faced a similar backlash during the 2022 trucker protests, when the government invoked the Emergencies Act and froze over 200 bank accounts containing nearly $8M CAD without court orders. The measures were lifted within days, but the incident triggered several knee jerk reactions and lasting debate about transparency, due process, and the role of financial institutions in enforcing emergency powers.
Similar debates are underway in other regions, such as the United States with proposals like the Fairness in Banking Act, which NCFA has examined for its consumer protection impact. The common challenge is ensuring that stronger enforcement powers don't override due process or weaken trust in financial systems.
Both the Thailand crackdown and the Canadian freeze highlight how well intentioned interventions can spiral into government overreach if consumer safeguards are weak. Independent oversight, transparent criteria, communication protocols, and effective redress mechanisms are essential.
As fintechs use AI to spot fraud, regulators need to keep rules fair and accountable. Protecting consumers while keeping trust in financial services is key to Canada’s future growth and inclusion.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Funding | Sep 24, 2025

Image courtesy of PRNewswire, Mycroft
On Sep 22, 2025, Toronto-based AI startup Mycroft announced that their agentic AI Security and Compliance Officer has emerged from stealth with $3.5 million USD in seed funding to accelerate product development and expand its reach. The funding round was led by Luge Capital with participation from Brightspark Ventures and Graphite Ventures, alongside existing investors Ripple Ventures, Developer Capital, Antler, BoxOne Ventures, and strategic angels.
This latest round follows a $1.2 million USD pre-seed round last September 2024, reported by BetaKit. Together, the two rounds bring Mycroft’s total funding to approximately $4.7 million USD.
The new capital will go towards product enhancements, expanded go to market initiatives, and scaling up operations. According to SecurityWeek, the platform currently offers modules for cloud security, device security, application protection, and audit preparation. The strategy is a direct response to increasing demand for automation in enterprise compliance and security, as companies face escalating compliance requirements from regulators around the globe.
Security and compliance functions have traditionally been fragmented across multiple tools, manual processes, and spreadsheets. Mycroft’s core innovation is a single AI-driven platform that acts as a Security and Compliance Officer. Behind the scenes, it is powered by no-code AI agents that handle specialized workflows such as monitoring cloud infrastructure, enforcing security policies, managing incidents, and preparing for audits. This design gives companies one platform to manage security and compliance, while multiple no-code AI agents work in the background on specialized tasks.
Mike Kim, Co-founder and CEO of Mycroft:
“Security shouldn’t be a burden. It should be a superpower. Our goal is to give every company access to enterprise grade security without needing a massive team. Mycroft’s AI agents don’t just automate tasks, they elevate the way teams operate, helping them move faster and stay protected from day one.”
Although Mycroft was in stealth mode, they have already signed more than 50 customers in its first six months. Early adopters include Superwhisper, Evolo, CoVet, Unified, Willful, Wisedocs, and Weave (YC25). The rapid uptake for enterprise grade security and compliance solutions highlight clear market need, especially among fast growing tech companies.
Karim Gillani, General Partner at Luge Capital highlights the importance of placing compliance at the center of trust:
“Security and compliance have evolved from manual back office functions to front line priorities that can shape customer experiences and brand reputation. Mycroft’s AI Security and Compliance Officer is the teammate that every company needs in order to stay safe.”
The AI security sector is increasingly crowded, with startups and established firms racing to deliver solutions in cloud protection, identity management, governance, and audit readiness. Mycroft differentiates itself by focusing on autonomous agentic AI that operates with minimal configuration and delivers end to end compliance outcomes. It offers a cost efficient alternative for startups and mid sized companies that lack large security operations teams.
By integrating modules that span from device security to regulatory audit support, Mycroft aims to give scaling companies confidence to grow while maintaining compliance.
Mycroft is well positioned to pursue sectors with heavy compliance such as fintech, healthcare, and SaaS. As regulations tighten globally, demand for solutions that can act as a virtual compliance officer is expected to grow. For more details, visit Mycroft’s official site.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Innovation | Sep 24, 2025
Image: Freepik
On September 16, 2024, Counterforce Health reported that U.S. platforms are using artificial intelligence to help patients appeal denied health insurance claims by analyzing rejection letters and generating tailored responses at scale.
The rise of AI powered tools is a growing insurtech trend where technology is being used to challenge entrenched industry practices that unfairly hurt consumers. For NCFA's community, the story raises important questions about where AI could play a similar role in our own insurance markets.
Let's look at the data to better understand the scope of the problem. In 2021, insurers on the federal HealthCare.gov marketplace denied about 17% of in network claims. These are services from doctors and hospitals already under contract with the insurer, showing that even approved providers faced a high denial rate.
Yet fewer than 0.2% of these denials were appealed, despite nearly 59% of appeals being successful when filed.
Separate research from the American Medical Association found that prior authorization denials are overturned more than 80% of the time when challenged, but only a small share of patients ever appeal.
The above figures point to a structural imbalance where insurers rely on consumers giving up. By automating appeal letters with expertly assessed supporting evidence, AI systems are changing the game.
Canada’s universal healthcare system means most core medical services are covered publicly, so denials are less about hospital visits or surgeries and more about supplemental benefits such as prescription drugs, dental care, physiotherapy, and other extended health services. Private insurers play a major role in these areas, and disputes are common.
What Canada lacks is transparent national reporting on denial and appeal rates. Unlike the U.S. system where denial data is published for marketplace insurers, Canadian insurers are not required to release such information. The limited statistics that do exist come from independent research or regulator snapshots, which highlight problems but don't provide a complete national picture. This lack of transparency creates a barrier to accountability and also an opportunity for Insurtech innovators.
Even without standardized national data, the available evidence shows that denial issues are widespread across several types of insurance:
Disability insurance denial rates are high. For example, about 60% of Canada Pension Plan disability applications are rejected, a figure that highlights the steep barriers claimants face, even if it is not directly comparable to private disability insurance.
In Quebec, 20% of critical illness and life insurance claims are denied according to the Autorité des marchés financiers. Disputes often stem from exclusions or non-disclosure clauses.
Extended health and drug benefits. Expensive specialty drugs and therapies are frequently denied as “not medically necessary” or outside policy coverage. Appeal processes can be slow and opaque.
Accident benefit disputes are frequent, especially with auto insurance in Ontario. The provincial tribunal system handles thousands of contested denials each year. AI insurtech solutions could help provinces reduce backlogs and streamline case processing.
Property insurance denials are common enough. Regulators report that property insurance denial ratios are around 16%, with most rejections tied to lack of coverage.
For fintech and Insurtech players, the opportunity spams the broader insurance ecosystem. AI could provide consumers with tools to navigate opaque processes, improve transparency, and reduce the cost of disputes.
Regulators have already outlined pan-Canadian guiding principles for responsible AI in health systems (Health Canada), establishing an innovation framework that balances fairness and accountability.
With insurance denial data so limited in Canada, new platforms that integrate appeals with data collection could simultaneously drive consumer protection and market competitiveness.
Denial data transparency can expose inefficiencies between insurers and individuals and AI solutions can help rebalance power. While Canada’s insurance system is structured differently than the U.S., denial disputes are still widespread and certainly costly in terms of time and money for stakeholders.
Fintechs and insurtech innovators should view this is a market opportunity while also protecting consumers. Canada can either wait for U.S. platforms to cross the border, or develop homegrown solutions that lead in fairness, transparency, and competitiveness.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Cybersecurity | Sep 23, 2025
Image: Freepik/DC Studio
On September 18, 2025, researchers at Radware disclosed a zero click indirect prompt injection called ShadowLeak that caused ChatGPT Deep Research to leak Gmail data after it encountered a booby trapped email. It's a new class of risk where hidden instructions can manipulate agents while being invisible to users, so NCFA wants to ensure that fintechs and key stakeholders are aware of how attackers can turn AI helpers into data thieves in a way that users including developer's can't see.
Radware’s analysis shows that the leak originated from OpenAI’s own cloud infrastructure rather than a user’s device. A malicious email carried hidden HTML instructions such as white text on a white background. When the user later asked the agent to summarize emails, the agent followed the invisible prompt and sent private details to an attacker controlled URL.
Because the action happened in the cloud, the victim’s network defenses never saw it.
The researchers warned that the same trick could work on other connectors including Google Drive, Dropbox, Outlook, calendars, and GitHub. That means sensitive business data such as financial contracts, HR records, and meeting notes could also be exposed.
Radware reported the issue on June 18, 2025. OpenAI deployed fixes by early August and closed the case on September 3. An OpenAI spokesperson told Recorded Future News that the company continually improves safeguards against exploits like prompt injections.
ShadowLeak is not the only case of an AI agent being manipulated into acting against its user.
At Black Hat in August 2025, researchers demonstrated an attack called AgentFlayer that used a poisoned Google Drive document to leak secrets through ChatGPT connectors. The document contained hidden instructions that looked harmless to a person but were machine readable. When the agent processed the file, it followed the malicious prompt and attempted to extract sensitive data.
On August 20, 2025, security researchers at Brave (website browser company) disclosed a similar flaw in Perplexity’s Comet browser. They showed how a hidden Reddit prompt could read Gmail one time passcodes and expose them to an attacker.
On September 13, 2025, Tom's Hardware wrote about a malicious Google Calendar invite method could steer ChatGPT agents with connectors enabled to leak sensitive data, again by embedding hidden instructions in content that appears ordinary to the user.
From Radware’s advisory and government sources such as the U.S. National Institute of Standards and Technology, here are some suggested practices.
AI agents are being connected to sensitive systems at a time when fintech firms face increasing scrutiny over privacy and security.
If a connector exploit can quietly leak contracts, loan records, or customer identifiers, the implications are massive, such as regulatory fines, reputational loss, and reduced trust from partners and investors.
In Canada, where regulators are preparing rules on open banking and digital identity, firms cannot afford to treat agent security as an afterthought. Research shows that 57% to 80% of injection attempts succeed when attackers repeat them (i.e. 25 times), which is why layered defenses are essential.
Banks and financial technology firms must implement agent safeguards into compliance frameworks, risk models, and vendor contracts that will protect customer trust and reduce liability. Canadian fintechs should approach agent security not only as a technical concern but part of core competitiveness functionality.
Board oversight is also critical, as regulators and investors will expect firms to demonstrate how they manage AI risks.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Cybersecurity | Sep 17, 2025
Image: Freepik/Rawpixel.com
On September 17, 2025, the Canadian Investment Regulatory Organization (CIRO) confirmed through a detailed FAQ that registration data of all current and former registrants had been compromised in the cybersecurity incident first detected on August 11. The regulator emphasized that Social Insurance Numbers and credit card data were not affected, but a wide range of personal and professional registration information was exposed.
CIRO is Canada’s national self-regulatory body for investment dealers and mutual fund dealers, overseeing trading activity across Canadian debt and equity marketplaces. Its mandate is to protect investors, support fair and efficient markets, and maintain trust in Canada’s financial system. The incident underscores that cyber risk is a critical challenge not only for the firms CIRO supervises but also for regulators themselves.
According to CIRO’s official updates regarding the cyber breach incident:
On August 11, CIRO identified the cybersecurity threat and shut down systems as a precaution
On August 17, preliminary investigation showed that some personal information of member firms and their registered employees was affected. CIRO acknowledged the seriousness of the breach and pledged to notify those impacted and provide risk mitigation services
On August 18, CIRO confirmed in a public update that it was working with external cybersecurity experts, legal counsel, and law enforcement. It also stressed that Canadians’ investments were not at risk
On August 28, CIRO announced that access to its systems had been restored, including CIRO Services, COMSET, CERTS, the Mutual Fund Dealers Member-only Site, EFS, MTRS, and Corporate and Government Debt Trading Information. CIRO reminded firms of their regulatory reporting obligations, granting five business days after notification to file reports that were due during the outage, while requiring timely submissions for all obligations due September 2 or later.
On September 9, CIRO confirmed that registration information of member firms and registered individuals was breached. The regulator began contacting all impacted individuals directly, offering two years of free credit monitoring and identity theft protection through TransUnion and Equifax. CIRO also clarified that emails from ciro@cyberscout.com or ciro@m.cyberscout.com are legitimate. In its update, CIRO issued an apology and promised to continue providing updates as the investigation progresses.
On September 17, CIRO released an FAQ update on the cybersecurity incident, now confirming that the August 11, 2026 breach affected registration data of all current and former registrants.
What data was exposed
Not included in the breach was Social Insurance Numbers and credit card or other payment information.
National Registration Database (NRD) - CIRO confirmed that the NRD system itself was not breached. The incident only involved registration information that CIRO maintains.
Notification process - CIRO began sending notifications on September 9. If an email is on file in the NRD, individuals will receive a message from ciro@cyberscout.com.
CIRO stated that personal information connected to member firms and registered employees was impacted by the incident. As part of its response, the regulator is offering two years of coverage through Equifax and TransUnion. CIRO confirmed that it only receives a limited sample of investor information through compliance functions, and emphasized that Canadians’ investments are not at risk. If any investor information were determined to be affected, CIRO committed to notify them directly and provide support.
CIRO has issued a clear warning that it will never contact registrants about this event through unsolicited phone calls or emails requesting personal or financial information. This message is designed to protect registrants from potential phishing attempts that may exploit news of the breach.
CIRO is contacting all impacted registrants directly by email or mail. Each individual will receive a letter signed by CIRO and sent by TransUnion with instructions and an access code to register for free protection services. Registrants should consider:
No organization is immune from cyber attacks, including those tasked with overseeing the integrity of markets. The investigation remains ongoing. CIRO has pledged to provide further updates as more details emerge. Market participants and stakeholders will be watching closely how the regulator continues to manage the response and what additional measures are introduced to safeguard sensitive information.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016