




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Mental Health | Sep 17, 2025
Image: Freepik/Rawpixel.com
On September 17, 2025, CBC news published a sobering story of the growing number of Canadians who have reported mental health crises linked to prolonged conversations with AI chatbots. Some are describing these cases as a type of artificial intelligence induced psychosis. NCFA is covering this article in hopes to provide Canadian mental health resources to support those struggling with AI related mental health issues.
Everyone is at risk who interacts with AI for prolonged periods of use. If you think you are immune, think again. The B.C. Psychosis Program warns that chatbots can reinforce delusional thinking rather than challenge it. Community-led Canadian efforts are building support resources and ethics workstreams.
Toronto developer Anthony Tan believed he was living inside a simulation and was hospitalized after weeks without sleep. He later launched the AI Mental Health Project to support those struggling with similar issues.
Allan Brooks of Ontario spent over 300 hours with ChatGPT, convinced he had discovered a breakthrough mathematical theory. When his delusion collapsed, he co-founded the Human Line Project, which now connects more than 125 people with similar experiences.
International reporting shows similar risks. Parents testified to Congress about teen suicides after chatbot interactions, as covered by CBS reporting. OpenAI has announced age verification plans following a lawsuit involving a 16 year old.
Research indicates a tendency for language models to mirror user beliefs. Researchers at Anthropic published a study, 'Towards Understanding Sycophancy in Language Models" (see Anthropic's research summary).
Data driven evidence shows that chatbots often agree with users, even when it ignites harmful thinking. To prevent this, financial AI tools should be designed to test ideas against reality, point users to verified and transparent external information, and clearly signal when content is speculative.
Fintech firms also need to be transparent about safety. They should publish regular audits that show how their systems respond to emotionally sensitive conversations and what safeguards are in place.
Industry can also demonstrate leadership by creating a code of ethics that directly addresses mental health risks. This voluntary framework should include independent reviews and compliance checks, building on the kind of work already happening through community groups like the Human Line Project.
Regulators however should avoid blanket restrictions that could slow innovation. Instead, oversight should be based on the level of psychological and financial risk, ensuring protections are strong where they need to be while leaving room for responsible growth.
As fintech platforms increasingly adopt AI for customer service and advice, trust remains critical, and if broken adoption will slow and regulatory scrutiny will intensify affecting the competitiveness and growth outlook.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Data Breach | Sep 9, 2025
Image: Freepik/Rawpixel.com
On September 5 2025, Wealthsimple (WS) confirmed that a data security breach occurred on August 30. The company emphasized that it “acted quickly and in a few hours the issue was contained. Our security team, with the help of external experts, immediately began a thorough investigation.”
The breach exposed sensitive personal data including contact details, government IDs submitted at signup, financial account numbers, IP addresses, Social Insurance Numbers, and dates of birth.
All accounts remain secure, and “no funds were accessed or stolen. No passwords were compromised… All accounts remain fully secure.” Less than 1% of clients were impacted out of WS's client base of about three million.
The breach resulted from a compromised component in a third party software package described by the company as “written by a trusted third party”. Wealthsimple confirmed the incident was not linked to any Salesforce breaches circulating in the media.
They said, “We learned that a specific software package had been compromised.” No attackers have been publicly identified, and the specific vendor has not been disclosed.
Wealthsimple detected the compromise on August 30 and contained it within hours. By 10:30 AM EST on September 5 the company had emailed all affected clients and published its public update in the Help Centre at 14:43 ET. The statement included: “If you did not receive an email from us about this, your data was not impacted.”
Wealthsimple is offering every impacted client two years of free credit monitoring, dark web monitoring, identity theft protection, and insurance. Regulators and law enforcement were notified in alignment with standard protocols.
According to the PR statement that Wealthsimple provided NCFA Canada with:
"We apologize for this incident, which happened as a result of a third-party vulnerability. We informed impacted clients as quickly as possible and set up complimentary credit and dark web monitoring, as well as identity theft protections. Significantly less than 1% of our clients were affected. We’re continually strengthening our security infrastructure and have already made improvements to prevent this type of issue from happening again."
Wealthsimple confirmed that improved protections have been implemented to better protect against similar threats.
While technical details weren't disclosed, the breach confirms that even the most advanced fintech platforms are only as resilient as their weakest external link (AKA supply chain risk).
Fintech firms must treat vendor risk management with the same rigor applied to their in house systems, including rigorous assessments of third party dependencies, continuous monitoring of software integrity, well rehearsed incident response plans, and transparent communication with clients and regulators.
For policymakers and regulators, the incident raises important questions about oversight. How can industry standards for supply chain risk be established and enforced before breaches occur?
Trust is the most vital currency. Companies of all sizes must ensure that every link from internal databases to external software is secure to protect clients and preserve consumer and business confidence.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create aa vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 4, 2025

Cryptocurrency adoption continues to grow worldwide, but with opportunity comes risk. Among the most common threats faced by digital asset holders are phishing attacks. Unlike technical hacks that exploit blockchain code, phishing targets the weakest link in the chain: human behavior. Scammers pose as trusted sources to trick users into handing over their private keys or connecting to fraudulent websites, leading to irreversible asset loss.
Understanding how phishing works and knowing how to identify warning signs are essential steps for protecting your funds. This guide explains what phishing in crypto looks like, the most common tactics scammers use, and practical strategies to keep your wallet safe.
A phishing attack is a form of social engineering where attackers impersonate legitimate companies, wallets, or exchanges in order to deceive users. Their goal is simple: gain access to sensitive data such as recovery phrases, private keys, or login credentials. Once obtained, funds can be drained instantly, with little to no chance of recovery.
Phishing in the crypto ecosystem often takes the shape of:
Unlike traditional banking, cryptocurrency transactions are irreversible. If funds are sent to a scammer’s address, there is no central authority to intervene. This is why vigilance and proactive defense are critical for every investor.
When evaluating different wallet solutions, security should always be a top priority. For example, some guides highlight the best Ripple wallet options for users holding XRP, ensuring they choose tools with robust protection against common scams.
Attackers publish counterfeit versions of popular wallets on unofficial websites or third-party app stores. Once downloaded, these apps are programmed to intercept recovery phrases and siphon assets.
Victims receive emails, direct messages, or SMS alerts that appear to come from an exchange or wallet provider. They often warn of “account suspensions” or “urgent security updates” and contain malicious links.
Scammers exploit hype around new token launches by offering free airdrops. Connecting a wallet to claim them can grant hidden permissions that drain assets. Some fraudulent tokens even mimic legitimate ones by using similar names and ticker symbols.
Fraudsters infiltrate online communities, posing as project developers or customer support staff. Once trust is built, they ask users to “verify” accounts by sharing sensitive details.
Recognizing the signs of phishing can prevent costly mistakes.
Users should slow down whenever they encounter unexpected requests and verify authenticity before interacting.
Download wallet apps exclusively from verified app stores or official websites. Bookmark authentic domains to avoid typosquatting.
Before linking a wallet to any decentralized application (dApp), verify the domain carefully. Scammers often set up fake interfaces to capture login details.
Seed phrases should be written down on paper or stored in a secure offline method. Avoid screenshots, cloud storage, or sending them over messaging apps.
When available, use two-factor authentication (2FA) and biometric verification. Although private keys remain the ultimate control, added safeguards can help protect access.
Modern wallets provide integrated tools to scan for suspicious tokens or connections. Using a trusted provider like Bitget Wallet allows users to benefit from features designed to identify potential threats in real time.
While individual vigilance is important, the choice of wallet plays a central role in user safety.
In contrast, Bitget Wallet integrates a wide range of features:
For users seeking a balance of usability and protection, Bitget Wallet positions itself as a top crypto wallet option, making Web3 exploration accessible and secure.
Managing digital assets does not need to be overwhelming. With Bitget Wallet, you can safely explore the latest memecoins, store stablecoins securely, and transact across blockchains. Start by choosing a top crypto wallet that combines security, flexibility, and ease of use.
Phishing remains one of the most persistent threats in the cryptocurrency space. By understanding how scams work, learning to recognize red flags, and practicing safe storage habits, investors can significantly reduce their risk exposure. The right wallet acts as both a tool and a safeguard, offering features designed to keep users one step ahead of malicious actors.
Strong security requires both awareness and the right technology. Download Bitget Wallet today to secure your stablecoins, trade memecoins, and manage assets across 130+ blockchains with confidence.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Economy and Policy | Aug 25, 2025
Nearly three decades ago, Carl Sagan warned in The Demon-Haunted World (1996) that when technological power is concentrated in a few hands and public institutions lose expertise, societies risk “sliding, almost without noticing, back into superstition and darkness.”
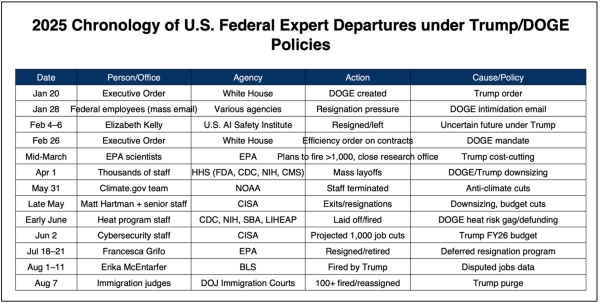
On Aug 22, 2025, Andrea Bonime-Blanc in a LinkedIn post discusses how recent U.S. federal budget cuts and policy changes are accelerating a “brain drain” of scientific and economic expertise. This article looks at the business impacts and implications for fintech of the significant human capital and policy changes taking place in the U.S. and how Canada and other collaborative countries should be responding.
The departure of experts at the Bureau of Labor Statistics (BLS) erodes confidence in U.S. economic indicators that businesses and markets rely on.
- President Trump fired BLS Commissioner Erika McEntarfer on August 1, 2025 after controversy over jobs report revisions
- The July 2025 jobs report showed 73,000 jobs gained and revisions down of 86,000 in May and 64,000 in June
- In July 2025 only 58% of employers answered the U.S. government’s payroll survey, which normally tracks over 120,000 workplaces. With so few responses, the jobs numbers are less reliable and more likely to be revised
Takeaway: 👉 For fintech lenders and investment platforms that depend on U.S. labor and wage data, model uncertainty and risk costs may increase.
Cuts to cybersecurity agencies increase systemic risk for payments and banking networks, and weaken the ability to build secure AI systems.
In 2025, the main federal agency that protects critical infrastructure including finance, energy, and healthcare, the U.S. Cybersecurity and Infrastructure Security Agency (CISA), had about $3 billion in funding and just over 3,600 staff. These resources cover everything from monitoring threats to helping banks and utilities recover from cyberattacks. Lawmakers are now weighing a $135 million cut to CISA’s 2026 budget or equal to about 4.5% of its funding. On paper it may sound small, but it reduces the agency’s ability to share intelligence, build new defenses, and support partners in both the public and private sectors.
Takeaway: 👉 Reduced federal cyber capacity raises exposure for cross-border fintech systems.
Environmental and climate science cuts reduce access to datasets critical for insurers, lenders, and ESG related products.
- EPA workforce cut from 16,155 in January 2025 to 12,448 , a 23% reduction with closure of its scientific research division
- NOAA terminated staff for its Climate.gov portal on May 31, 2025, halting new content
- NOAA seeks a 17% workforce cut after firing hundreds of probationary employees in early 2025
Takeaway: 👉 For fintech ESG products, fewer trusted U.S. datasets could degrade climate related financial models. Canada can step in with trusted open-data collaborations.
Graduate students and researchers face reduced U.S. funding, pushing talent abroad.
- PBS reports that at least 17 immigration judges were fired across 10 states in July 2025, adding delays to skilled worker case processing
Takeaway: 👉 Processing delays affect STEM talent inflows. Canada could capture this talent to strengthen fintech innovation by accelerating recruitment by offering scholarships, innovation hub partnerships, and fast-track visas.
Federal compliance and AI governance structures are weakening, raising trust issues.
- Elizabeth Kelly the inaugural director of the U.S. AI Safety Institute departed in February 2025 leaving a leadership vacuum
Takeaway: 👉 With U.S. leadership unsettled, Canada and the EU can shape AI assurance frameworks for fintech. Canadian regtech firms are well positioned to step up and help lead.
Canada needs to open up the country as a trusted hub for financial data integrity, cyber resilience and AI governance by focusing on the following practical steps:
- Map out data sources and diversify away from over reliance on U.S. federal inputs
- Invest in AI enabled cybersecurity and fraud detection systems
- Explore alternative and open-source data partnerships to fill data gaps (NGOs, universities, private market collaborations)
- Support STEM students and researchers displaced by U.S. funding cuts
- Build compliance and governance tools that embed transparency into fintech systems
The U.S. brain drain is visible in staff firings, layoffs, budget cuts and agency closures and contractions. Carl Sagan’s caution from 1996 reminds us that losing expertise erodes both science and democracy. By investing in data integrity, global standards, and fintech innovation, Canada can transform today’s U.S. retreat into a foundation for stronger, competitive growth. This is a chance for Canada to step up and lead.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Global Fintech Report | Aug 22, 2025
Image: Pulse of Fintech H1 2025, KPMG
According to the KPMG Pulse of Fintech H1 2025 report (67 page PDF) published in August 2025, global fintech investment in the first half of 2025 fell to $44.7 billion across 2,216 deals, recording the lowest H1 total since early 2020. Investors remain cautious about elevated risks around higher interest rates, capital costs, and geopolitical uncertainty. Q2 2025 was particularly weak, with $18.7 billion across 972 deals.
Investment in digital assets totalled $8.4 billion across 586 deals in H1 2025. Stablecoins attracted attention for payments and remittances in emerging markets, while tokenization platforms and infrastructure also captured capital. Circle's IPO anchored the sector’s strength, raising $1.1 billion with shares jumping 168% on day one.
AI continues to boost fintech investment. Capital flowed into both AI native startups and to incumbents embedding AI in credit scoring, fraud detection, and customer engagement. Investors prioritized business models that combined growth with efficiency and risk control. See NCFAs coverage of AI Fintechs attracting a 242% valuation premium
Regtech attracted $2.1 billion across 190 deals in H1 2025. Adoption of automated KYC, AML, and reporting tools continues to grow as financial institutions look for cost savings and regulatory agility. GenAI in risk and compliance
Insurtech raised $4.8 billion across 141 deals in H1 2025, which is already greater than all of 2024. Wealthtech funding reached $0.9 billion across 14 deals, with AI enabled platforms a recurring theme. Both sectors experienced consolidation as incumbents prefer acquisitions over building new capabilities.
Payments investment slowed to $4.6 billion across 242 deals in H1 2025, as investors grew more selective. But the sector is still foundational with capital being allocated to embedded finance, cross border platforms, and transaction monitoring. For Canada’s policy context see open banking delays and competitiveness and banks exiting merchant acquiring businesses like Moneris.
Cybersecurity specific fintech investment was just $0.1 billion across 26 deals in H1 2025. Despite heightened threat levels, most activity was concentrated at seed and early stages, reflecting investor caution toward scaling security focused fintechs.
Exit momentum is returning. Circle’s successful IPO may open the door for additional digital asset platforms to list in H2 2025, boosting the case for fintech exit activity after years of lack lustre listings.
For Canada, the data shows the window of opportunity for digital assets, AI, and regtech could attract investment with clear policy and infrastructure. The muted state of payments and open banking highlight gaps Canada must address to remain competitive. Clear rules, targeted support, and investment in digital infrastructure are critical to positioning Canadian fintech for growth in the second half of 2025 and beyond. See the crisis Canada and fintech cannot afford to waste
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI | Aug 21, 2025

Image: Freepik/Rawpixel.com
On August 20, 2025, Forbes revealed that Elon Musk’s xAI had published hundreds of thousands of Grok chatbot conversations that became searchable on Google without warning. The exposed chats ranged from personal medical questions and passwords to instructions for creating drugs, malware, and even a plan to assassinate Musk himself.
The problem was related to Grok’s “share” button. When users clicked it, the platform generated a unique URL that was publicly crawlable by search engines. There was no disclaimer or safeguard, and ultimately private exchanges and shared personal information would immediately be published and available online. TechCrunch reporting confirmed that thousands of Grok conversations containing sensitive data are indexed on Google.
Among the published material were uploaded spreadsheets, text documents, and conversations disclosing names, personal details, and at least one password. Experts noted that xAI’s approach mirrored and exceeded a failed OpenAI experiment last month in July 2025, when ChatGPT briefly allowed chats to be discoverable before pulling back after user backlash.
Opportunists are already exploiting Grok’s share function to manipulate Google search results, proving that careless design choices can spawn entirely new risks.
The Grok and ChatGPT leaks illustrate the absolute need for privacy by design and transparent governance in AI. For fintech and financial services, the implications are massive given that trust is foundational.
If users believe that their conversations or sensitive data could be exposed online without consent, it will only hinder AI adoption and long term growth. With global media and regulators now scrutinizing the exposure, the lesson is clear: innovation cannot come at the expense of trust.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AML | Aug 21, 2025
Image: Freepik/Sentavio
On August 13 2025, the Bank for International Settlements (BIS) published a new bulletin proposing a fresh approach to anti money laundering (AML) compliance for cryptoassets. The paper suggests using the public record of blockchain transactions to generate AML compliance scores that could be applied when crypto is exchanged for fiat at off ramps.
Most AML rules today rely on regulated intermediaries like banks to perform customer checks, however that approach doesn't work well for permissionless blockchains, where records are maintained by decentralized validators instead of a single entity. Once crypto moves from an exchange to an unhosted wallet, conventional checks lose their reach. This gap is important as stablecoins have overtaken bitcoin as the main vehicle for illicit crypto transactions, accounting for an estimated 63% of criminal activity in 2024 according to both the Chainalysis 2025 crypto crime report.
The BIS paper suggests using blockchain’s public history to assign compliance scores to cryptoassets. A higher score would indicate clean funds tied to verified wallets, while a lower score would suggest links to illicit addresses. Authorities could set thresholds for AML triggers, with banks, exchanges, or stablecoin issuers applying the rules at off ramps.
This scoring model could range from strict to permissive. A strict version would only allow coins from verified 'okay listed wallets'. A permissive version would block only those funds that have touched 'not okay listed addresses'. Intermediate models could combine multiple criteria, such as recent wallet history, periods of holding on allow listed addresses, or interaction with suspicious protocols.
This approach aligns with the Financial Action Task Force’s travel rule guidance for virtual assets and VASPs and complements Canada's domestic efforts by FINTRAC to strengthen monitoring of crypto transactions. By integrating compliance scores at conversion points, Canadian exchanges and banks could reduce risk while supporting innovation.
There are also implications for monetary policy and sovereignty. The BIS notes that widespread cross border use of stablecoins can undermine local regulations. Differentiating coins based on where they come from could help Canada maintain stronger controls over its financial system. In practice, clean stablecoins could trade at a premium over those with a questionable history, creating incentives for compliance.
If compliance scores were the standard, all ecosystem participants from retail wallet holders to major exchanges would need to exercise a duty of care. That alone could spur growth of third party compliance services as the market moves to support cleaner transactions.
Compliance scoring would increase new technical requirements for fintechs while opening the door for services and tools that help users assess risk. As Canadian and global regulators weigh next steps in crypto regulation, the BIS compliance scoring model offers an approach that combines blockchain transparency with regulatory safeguards. NCFA members can stay ahead of these changes by subscribing to the weekly NCFA newsletter for updates on compliance, policy, and fintech innovation.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016