




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Consultation | June 20, 2025
Image: Freepik
On June 19, 2025, the Canadian Securities Administrators (CSA) published Consultation Paper 81-409, proposing to modernize ETFs and how they are regulated in Canada, and is soliciting feedback.
ETFs are one of the most popular investment products in the country. Last year, Canadians invested $518 billion in ETFs, which represents about 19% of all publicly offered fund assets in Canada. Retail investors held around 62% of those ETF assets, according to the OSC ETF Study cited in the paper.
The CSA began reviewing ETF rules in 2023 to see whether the current approach still works. The review focused on key ETF features such as the way ETF units are created or redeemed by authorized dealers, how ETFs trade on exchanges, and how the price of ETF units compares to the value of their underlying investments. The CSA also considered recent international standards published by IOSCO, the global body of securities regulators.
Stan Magidson, Chair of the CSA and Chair and CEO of the Alberta Securities Commission:
“ETFs are an increasingly important investment vehicle for Canadians. This consultation will provide the CSA with important insights into the unique regulatory considerations for these products.”
The CSA is also seeking feedback on how Canadians investors access U.S. listed ETFs, either directly through broker-dealer platforms or indirectly through Canadian ETFs that hold foreign-listed funds.
More Canadians are using ETFs to invest in everything from stocks and bonds to commodities and global markets. These proposed changes are designed to protect investors, improve transparency, and support competition by making sure the rules reflect how ETFs actually work today.
The CSA is seeking input from investors, industry participants, and other stakeholders to modernize and update future ETF regulation in Canada. Comments are due by October 17, 2025.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Tokenization | June 18 2025

As covered by Retuers, Coinbase is officially asking the U.S. Securities and Exchange Commission (SEC) to approve tokenized equities (or stocks), a new class of financial product. These would be blockchain representations of traditional equities, such as Apple or Tesla, designed to trade 24/7 with almost instant settlement and lower overhead. Coinbase is seeking a no-action letter or regulatory exemption from the SEC, and if they grant it, Coinbase would be the first major U.S. exchange operating with such tokenized products, evolving well beyond just a standard crypto trading exchange.
The tokenized equity model would allow retail and institutional users to access fractional ownership of blue-chip stocks via a blockchain interface and operate largely without the constraints of traditional brokerage platforms. For example transactions could take place globally, 24 hours a day, without relying on legacy clearing infrastructure. It could mean significant improvements in market efficiency, reduce settlement risk and include new financial products natively on-chain.
While Coinbase looks to break new ground in American markets, other jurisdictions are already operating. Rival exchange Kraken has launched tokenized stock trading for non-U.S. customers through its partnership with Swiss-based Backed Finance. For example, tokenized versions of Apple and Tesla stock, bAAPL and bTSLA respectively, are live pioneering examples of tokenized equities executed issued on the Solana blockchain, backed by 1:1 real shares held in custody, and tradeable with no minimum investment size and operate legally under global regulatory frameworks with blockchain flexibility, and 24/7 trading.
Europe is ahead of the curve on regulation. The EU’s MiCA framework was fully implemented as of 2024, providing legal clarity for tokenized securities across 27 member states. In Asia, Hong Kong is piloting tokenized gold, bonds, and equities under regulatory supervision. These jurisdictions are showing that comprehensive tokenization frameworks can unlock innovation while still preserving investor protection and market integrity.
Tokenized securities may require broker-dealer registration, SEC exchange approval, and compliance with the Investment Company Act. Since, Coinbase is not currently licensed as a broker-dealer, it may need a partner or entirely new structure to support these offerings legally.
There are also questions about liquidity. The World Economic Forum has identified low secondary market trading volumes and lack of standardization as persistent challenges in real-world asset tokenization.
While the tech stack can actually enforce compliance rules directly within smart contracts using standards for Real World Assets (RWA) like ERC-3643, adoption of these instruments will depend on regulators aligning globally and investors gaining trust.
If the U.S. and EU formalize tokenized security frameworks, capital will flow toward platforms offering speed, access, and interoperability, leaving slow movers behind. Companies should be exploring how to integrate tokenized equities into their product roadmaps while remaining compliant. NCFA and its members can play a leadership role in what responsible tokenized finance, launch educational initiatives, and collaborate with global infrastructure providers. At the of the day, tokenized assets are poised to become a competitive advantage or missed opportunity.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech | June 18, 2025
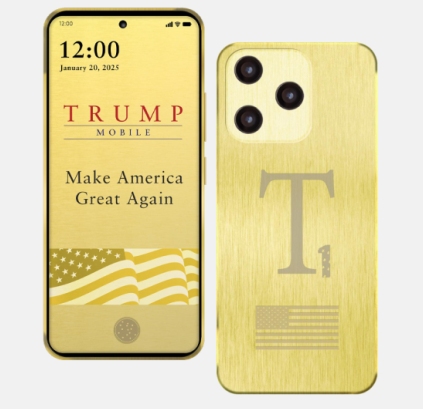
Image courtesy of Trump Mobile website
On June 18, 2025, Fortune reported that Trump Mobile is entering the U.S. wireless market with a $47.45 per month prepaid plan and a smartphone built by Chinese device maker Unihertz. Beyond the political optics, the announcement is interesting from a fintech perspective since Trump Mobile plans to use a telecom backbone to bundle lifestyle services in a way that mirrors embedded finance strategies seen in a variety of global fintech ecosystems.
The T1 smartphone is priced at $499 with a $100 down payment, and is scheduled to ship in late summer 2025. Trump Mobile is powered by Patriot Mobile, an MVNO that leases infrastructure from existing carriers. The business model relies on branding and licensing rather than owning physical networks. This setup closely resembles the way fintechs white label financial infrastructure through APIs and software platforms.
Eric Trump, EVP Trump Organization on Trump Media:
“I'm incredibly excited to step into this new digital space, hard-working Americans deserve a wireless service that's affordable, reflects their values, and delivers reliable quality they can count on. We're especially proud to offer free long-distance calling to our military members and their families — because those serving overseas should always be able to stay connected to the people they love back home. ”
The flagship product is the “47 Plan” offered at $47.45 per month. According to Trump Mobile’s website, it includes unlimited talk, text, and data, plus international calling. The bundled services also include 24/7 telehealth access and roadside assistance, which are traditionally sold separately or through insurance providers. Packaging them into a single mobile bill is a similar approach of fintech super apps.
The T1 phone has midrange specs: a 6.8-inch AMOLED 120 Hz screen, 12 GB RAM, 256 GB storage, a 50 MP triple camera setup, Android 15, a 5,000 mAh battery with 20 W fast charging, USB-C, a headphone jack, and biometric unlocking. The phone is manufactured by Unihertz in China, despite political framing that implied U.S. manufacturing. It unveils global hardware supplier realities that fintechs face when bringing physical devices to market.
According to The Wall Street Journal, the Trump family licenses its name to Patriot Mobile, which operates the network. This approach is similar to how fintech startups offer debit cards, wallets, and investment tools without becoming licensed financial institutions. The infrastructure is external, but the customer relationship is owned by the brand.
There is also a digital asset component. Reuters reported that Trump Media is applying for a cryptocurrency ETF made up of 75% Bitcoin and 25% Ethereum. Even though the potential crypto ETF isn't directly tied to the phone plan just yet, it highlights the Trump brand's ambition to combine lifestyle, media, and financial products.
Ironic as you get that earlier in 2025, the Trump administration slapped a raft of reciprocal tariffs, including a baseline 20% tariff on Chinese-made consumer electronics. According to Al Jazeera, the administration later exempted certain chips and phones but it's unknown which specific products currently qualify. If the T1 is subject to tariffs, the cost could be absorbed by Unihertz, passed to Patriot Mobile, or used to justify higher retail pricing.
Trump Mobile offers a live case study in how embedded services can be sold through telecom. For Canadian fintechs, it opens a conversation about how telcos and startups might partner to deliver subscription-based insurance, health care, or financial tools to underserved communities. Packaging multiple services into a mobile plan can improve customer stickiness, adding to predictable revenue, as also seen in bundled offerings by Koho, Neo, and other Canadian fintechs.
There should be policy concerns however, with potential conflicts of interest involving Trump's family ties to regulatory agencies. Also combining telco infrastructure with consumer finance triggers questions around cross-sector regulation, as regulators will need to consider the risks of a converging telco-fintech model as it grows.
For NCFA members, this launch offers insight into how bundled, cross-platform models can scale quickly with the right partnerships. As Canada expands open banking and explores new models of service delivery in underserved markets, this example shows how telecom-fintech convergence could work, assuming regulators allow it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Crypto | March 18, 2025

On June 17, 2025, a watershed moment for digital finance and crypto with the U.S. Senate passing the GENIUS Act, bipartisan 68-30 vote, establishing the country’s first federal regulatory framework for stablecoins. This legislation is the most significant digital asset policy breakthrough to date in the United States.
The GENIUS Act stands for 'Guiding and Establishing National Innovation for U.S. Stablecoins'and lays out clear rules for the issuance, required reserves, transparency, and oversight of U.S. dollar backed stablecoins. It's expected to boost financial innovation in America by providing a coherent national policy to streamline the governance patchwork created by state-to-state rules. The stablecoin market has now surpassed $260 billion in total value (up about 22% in 2025 alone), and is growing rapidly with rising institutional demand.
As reported by WSJ, Senator Cynthia Lummis (R-WY, one of the bill's key sponsors) said:
“This is the first step in establishing trust, protecting consumers, and ensuring the dollar remains the global standard for digital finance,”
The bill outlines strict guardrails for stablecoin issuers to prevent another collapse like TerraUSD while ensuring stability, liquidity, and auditability:
The GENIUS Act delivers some legal clarity to a sector long operating under ambiguous guidance from regulators.
Notably, the issuer of USDC, Circle saw its pre-IPO share price boost nearly 10% on the news, rising from $31 to over $160 as investor confidence rebounded. The company’s CEO Jeremy Allaire explained the bill as “the foundation of dollar dominance in the digital era.”
The bill is still not without some controversy as critics flagged the exclusion of President Trump from the conflict of interest restrictions - seen as politically motivated and related to the Trump family's interests and ties to private stablecoin ventures.
The bill now moves to the House of Representatives to be reconciled with the STABLE Act, and then once approved in both chambers the bill would be sent to President Trump for signing the first major federal stablecoin bill into law.
Will Canadian regulators follow with similar national standards for fiat-backed digital assets? As OSFI and FINTRAC review their guidance, Canadian fintechs operating in cross-border payments, custody, and token issuance will begin to face rising pressure to align with U.S. rules or risk falling behind in market access and credibility. The global sector is consolidating quickly and Canadian innovators must determine whether or not to build on this momentum with their own regulatory clarity.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 18, 2025
Image: Freepik
One of the first surprises in any crash game is this: not all vehicles break the same way. Some fold in half with satisfying fluidity. Others resist impact, barely denting. A lightweight sports car might flip wildly. A heavy van might crash into the pavement and stop dead. These define the entire experience.
And they aren’t random. Each outcome is rooted in design. The way a car’s mass is distributed, how its frame is built, the shape of its front end — all of it influences how it crashes. In crash games listed on crashgamblers.com, vehicle design becomes a language. Players learn to read it.
The vehicle is a character, and it expresses itself in how it breaks.
Design determines destruction. When a car hits a wall, what happens next depends entirely on how it’s built. Some deform slowly, like a wave of bending metal. Others shear apart instantly. The result is about structure.
Key factors that shape crash behavior:
These variables combine to create unique crash profiles. A sedan crashes differently than a pickup. A hatchback reacts differently from a truck. And that variety gives the player choices of experiences.
In traditional racing games, players choose cars for speed, grip, or handling. In crash games, they choose for the break. One model might fold neatly into itself. Another might launch skyward when hit just right. The question becomes not "how fast can I go?" but "how will this collapse?"
This shift turns design into gameplay. The player begins to think about structure — not just for performance, but for effect. Some may seek symmetry in damage. Others may want total chaos. Vehicle selection becomes creative, even expressive.
And here’s the twist: if breaking is the goal, then every design choice becomes part of that pursuit.
What if destruction is the decision?
Crash games often allow customization. Suspension height, tire pressure, weight balance, even body type — all of these can be altered. And unlike traditional games, where upgrades aim for speed or control, here the aim is different. You're tuning for impact.
A soft suspension might absorb more energy, dulling the crash. A low center of gravity might prevent a roll. A stiffer frame might resist collapse, while a lightweight roof might crumple satisfyingly on contact. Every tweak changes the shape and rhythm of destruction.
This approach flips conventional tuning on its head. You’re not optimizing for victory — you’re sculpting failure. Some players experiment endlessly, crafting the perfect wreck. Not because it earns points, but because it looks, sounds, and feels right.
And that kind of experimentation, grounded in physics but driven by creativity, gives the game surprising depth.
Each crash tells a story. The angle of approach, the speed, the terrain, the design — they all combine to create a sequence that unfolds like a short film. Was it a slow-motion rollover? A brutal front-end smash? A roof collapse followed by a bounce?
The vehicle becomes the narrator. Its structure decides the pacing. Its reaction shapes the mood. And because every design behaves differently, every crash feels personal.
But these aren’t just visual stories — they’re mechanical ones. A perfect deformation arc or a jagged rupture says something about engineering, about choices made in the moment. The absence of a soundtrack or narration makes space for physical drama. The only voice is steel against asphalt.
Players remember certain crashes not because they scored high, but because the impact felt right. It surprised them, moved them, or satisfied some unspoken expectation. That’s what turns a simulation into something more than a system.
A crash is only as good as the machine that breaks.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Stablecoins | June 17, 2025

Image: Freepik/rawpixel.com
Retail giants Amazon and Walmart are exploring the idea of launching their own stablecoins to reduce payment processing costs and gain more control over transactions, according to a report by the Wall Street Journal. This could tip the balance toward merchant-controlled financial systems and impact how value is transferred in the digital economy.
Currently card networks like Visa and Mastercard charge merchants high fees for purchase transactions. By using stablecoins pegged to the U.S. dollar, retail companies like Amazon and Walmart could build their own payment systems, bypassing legacy rails and retain more transactional value on their platforms. However any stablecoin plans depend on whether or not the proposed Genius Act becomes law in the United States.
As reported by Reuters, stablecoins are gaining interest among corporations that want to issue or use private forms of digital cash. The goal isn't to create a new form of money, but to develop closed financial ecosystem for transactions that are faster, cheaper, and programmable than legacy payment systems used today.
Retailers aren't the only ones interested. PayPal has already launched its own stablecoin, PYUSD, which is issued through a partnership with Paxos, a licensed trust company. Amazon and Walmart could follow a similar route or choose to build in-house capabilities.
According to Crowdfund Insider, the Genius Act is currently in front of the Senate and is expected to have a floor vote on June 18 which if passed would become the first American law to set national standards for fiat-backed digital currency. Stablecoins would require 1:1 reserve backing, clear audit rules, and strong consumer protections.
The Genius Act is designed to add clarity and prevent abuse while encouraging legitimate innovation. Only regulated entities can issue stablecoins and limits will be in place for the type or size of non-financial companies that can use them. Analysts at Bernstein have warned that the Genius Act could make it “prohibitive” for retailers to issue stablecoins directly without working with financial partners.
As Business Insider explains, the bill would give federal regulators oversight of reserves, mandate asset freezes under court orders, and block big tech companies from embedding coins too deeply into their platforms. The law also prevents stablecoin issuers from tying coins to commercial loyalty programs or e-commerce activity without approval.
If Amazon and Walmart did in fact launch their own stablecoins, merchant-led payment systems could reduce friction for consumers and suppliers while creating competitive pressure on Canadian banks, fintechs, and card networks.
Global payment flows could also be affected if retailer stablecoins are used for remittances or global vendor payments. Walmart already has a fintech joint venture with Ribbit Capital in the United States to create a fintech startup Hazel (also called 'One'), and experience with blockchain patents. Amazon has explored using external stablecoins such as USDC for settlement.
Whether they issue directly or partner with licensed issuers, the genie is almost out of the bottle and moving beyond theoretical. Consider it a live business option just waiting for regulatory clarity.
Canada’s fintech ecosystem should monitor these developments closely. U.S. regulatory clarity could prompt other jurisdictions to act, and consumer expectations will grow as giant retailers redefine what payments in the near future look like.
It may create opportunities for Canadian fintechs to partner with global brands or expand the merchant-focused rails to compete with card-based infrastructure, ultimately pushing to modernize domestic payments. Stablecoins come with some real risks around consumer protection, monetary policy, and financial stability, so it's essential to get the balance right.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Innovation Award | June 16, 2025

Image from the Tokyo Financial Award 2025 website
Applications are now open for the Tokyo Financial Award 2025, a global competition organized by EY Strategy and Consulting on behalf of the Tokyo Metropolitan Government. The award targets financial technology companies at the edge of financial services, and also those working on sustainable finance problems. Canadian fintechs with global ambitions are encouraged to apply.
The Tokyo Financial Award is part of Tokyo’s push to become Asia’s financial innovation hub. Selected firms will gain visibility, mentorship, funding, and direct support for business expansion in Japan.
This category is for fintech companies and financial service providers offering innovative solutions that address the real needs of Tokyo’s citizens and businesses. This includes everything from digital payments to inclusive finance, automation, regtech, and more.
Deadline to apply: July 31, 2025 (23:59 JST) - Apply here
This category rewards companies using finance to support the transition to a sustainable society and has 3 subcategories:
Deadline to apply: August 31, 2025 (23:59 JST) - Apply here
The Tokyo Financial Award connects emerging fintech and sustainability leaders to one of Asia’s most dynamic financial markets. This is a great opportunity for Canadian fintech companies to diversify to new markets and gain recognition, funding, and in-market support while contributing to real world impact in Tokyo, Japan and beyond.
Visit the website to learn more or email: tfa@jp.ey.com.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016