




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


M&A | June 16, 2025
Image: Freepik
Another high growth Canadian founded tech startup exits on foreign soil. U.S. giant Qualcomm has agreed to acquire Toronto-founded semiconductor designer Alphawave Semi (Alphawave) for US$2.4 billion. The acquisition strengthens Qualcomm's data center and AI capabilities but also raises recurring questions about Canada's ability to retain and scale its homegrown innovators.
Alphawave was founded in Toronto in 2017 by Canadian engineer Tony Pialis. The company builds technology that helps computers move large amounts of data quickly and efficiently. Qualcomm plans to use Alphawave's technology alongside its own processors to support the growing demand for AI and energy efficient data centers.
In 2021, Alphawave chose to go public on the London Stock Exchange instead of listing on a Canadian stock exchange like the TSX. The decision was widely viewed as a sign that Canada's capital markets were not deep enough to support large scale semiconductor or hardware IPOs. At the time, Alphawave raised roughly US$500 million in its debut, validating London as a preferred launchpad for global visibility.
Alphawave is legally incorporated in the United Kingdom as Alphawave IP Group plc (AWE.L), with its official registered office in Leeds, England. The company is listed on the London Stock Exchange and governed by UK corporate law.
However, since the firm was founded in 2017 in Toronto, it maintains significant operations in Canada. Its main office still remains in Toronto, and it continues to operate major engineering and R&D facilities in Kanata, Ottawa, employing over 250 staff in the country. Alphawave recently opened a 20,000 square foot R&D lab in Kanata and actively recruits from Canadian universities.
So, while the public listing and legal structure are based in the UK, Alphawave's tech development and leadership talent are deeply rooted in Canada. The decision to list in London was based on the availability of semiconductor capital and deeper markets for advanced technology, according the company's leadership.
Alphawave is one of the most prominent Canadian-founded technology firms to exit internationally in recent years. The company's core IP and chiplet designs power data centers, AI infrastructure, and cloud platforms, foundations for fintech, e-commerce, and cybersecurity services, which are increasingly built with low latency, high performance hardware.
For policymakers and Canadian fintech leaders, it's clear that without stronger later stage funding mechanisms, global scale listings, and/or targeted supports, more Canadian firms are at risk of scaling elsewhere and being acquired prematurely.
Alphawave's story is another wake up call that Canada needs to continue to invest in Canadian tech companies to be globally competitive, from capital to commercialization, or risk a further drain of companies that need to look elsewhere to support their growth and success.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
AI National Program | June 16, 2025

Image: Freepik/jcomp
Funded by DIGITAL and matched by delivery partners Human Feedback Foundation (project lead), The Dais at Toronto Metropolitan University, and Creative Destruction Lab, have launched a new national initiative called 'Responsible AI Adoption for Social Impact' (RAISE), to help nonprofit organizations adopt artificial intelligence in a responsible and practical way. The program brings together investment, training, and governance tools to help nonprofits use AI to serve their communities more effectively, and to bridge the growing AI skills gap in the nonprofit sector.
Canadian non-profits are an important part of Canada's economy, with more than 170,000 organizations contributing over $192 billion. Yet only 4.8% currently use AI, and fewer than 1% of nonprofit staff work in technology roles. This is a growing skills gap and it limits how organizations can expand their services, analyze data, or respond to the rising needs of their communities.
RAISE was created to help close this gap, and aims to build a responsible model of AI adoption that others can follow. The program supports nonprofits as they explore how AI can help them increase efficiency, improve services, and stay focused on ethical and inclusive practices.
The total budget for the RAISE pilot is $1.3 million of which $650,000 is being co-invested from DIGITAL, with an equal amount matched by the delivery partners as follows:
This co-investment model demonstrates how nonprofit, academic, and innovation leaders are aligning to build digital capacity in the social sector.
The RAISE initiative is built on three connected parts:
1. 12-month accelerator program led by Creative Destruction Lab is helping five major nonprofit organizations integrate AI into their work. These include CAMH Foundation, Canadian Cancer Society, Furniture Bank, CanadaHelps, and Achēv. Each organization will receive support to design and implement AI systems in line with their missions.
2. The Dais will train 500 nonprofit professionals focusing on AI literacy, governance, and practical use in areas like fundraising, data stewardship, policy, and service delivery.
3. The Human Feedback Foundation will lead the development of a governance framework and resource guide that offers guidance on how nonprofits can adopt AI with transparency, fairness, and measurable outcomes, which will be co-developed with partners to meet the needs of diverse organizations and communities.
The RAISE pilot has received strong support from across the nonprofit and technology sectors including organizations like Imagine Canada and the Canadian Centre for Nonprofit Digital Resilience who are working together to ensure the pilot is focused on practical challenges and goals of nonprofit work.
Elena Yunusov, founder and executive director of the Human Feedback Foundation, leading the project said the program is about giving nonprofits the capacity to lead in ethical AI use. She emphasized the importance of building trust, protecting values, and ensuring AI tools are aligned with the missions of participating organizations.
RAISE shows how AI adoption can be set up in a way to boost public interest and not just private gain. It also highlights how nonprofits, academic institutions and accelerators are collaborating across nonprofits, which could serve as a template for other sectors, especially those that are under-resourced. It creates opportunities for experts to contribute and partner with mission-driven organizations in ways that help nonprofits beyond traditional activities.
In addition to supporting nonprofits through RAISE, Canada’s Global Innovation Cluster (DIGITAL) is also backing several other initiatives with strong connections to fintech, digital skills development, and ethical AI use, such as:
This project uses artificial intelligence to build personalized digital advisors for career planning. The tools are being tested with job seekers across the country to improve employment outcomes. Fintech firms could adopt similar AI systems for financial coaching, digital onboarding, or customer journey optimization.
Learn more: AI Career Advisor
Focused on supporting women and non-binary entrepreneurs, this project offers AI adoption training and business tools. It helps build technical confidence and digital fluency. Canadian fintech incubators and accelerators can model similar programs to grow diverse leadership in digital finance.
Learn more: AI Skills Lab Canada
Judy Intelligence develops AI tools that help rural and underserved communities gain access to job-matching and upskilling opportunities. This is highly relevant to fintech organizations working to expand financial access outside of major urban centers. It offers a model for AI-driven community outreach. Learn more: Judy Intelligence
TalentBridge builds online learning and employment platforms with an AI layer to improve hiring and digital inclusion in Indigenous and remote communities. Fintech organizations can benefit by using similar platforms to recruit skilled workers and better serve underserved markets. Learn more: TalentBridge
By investing in practical tools, governance, and talent, the RAISE program is a great blueprint for how sectors with limited resources can come together to still lead in ethical innovation. It also opens doors for cross-sector collaboration, inviting Canada’s fintech and digital leaders to join in building a more inclusive AI future that strengthens communities and drives productivity and longer term impact.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 16, 2025

Image: Freepik
Canada’s fintech world in 2025 is changing fast, focusing more on user-friendly design and smart technology. One big trend is using game-like features to make people more involved and interested. A good example is platforms like legiano casino, which offers a wide variety of bonuses for different types of players. Whether someone is new or experienced, they can find welcome deals, reload rewards, and special VIP perks, similar to how fintech tools are now using personalized features to keep users engaged.
This mix of online gaming and fintech points to a broader move toward more interactive and rewarding digital experiences. By using layered incentives and personalized rewards, financial platforms are adopting strategies that build user trust and long-term engagement. These gamified features are helping reshape how Canadians interact with money, making digital finance more engaging and easier to stick with.
Gamification is quickly becoming a key part of Canada’s fintech world, turning routine money tasks into more engaging experiences. By using features like rewards, progress tracking, and personal challenges, fintech platforms are making money management feel simpler and more rewarding. This shift helps attract a wider audience and supports better financial habits.
Fintech companies taking cues from platforms like Legiano Casino are building tools that keep users coming back. As these features become more common, people expect more from their financial apps, more personalization, more feedback, and more reasons to stay involved.
Recent research supports this shift. A 2024 report from Ivey Business School looked at 1,500 Canadian fintech companies and highlighted the top 150 based on factors like funding and performance. The findings show a strong move toward user-focused tools in areas such as digital payments and wealth management, showing how gamified design is shaping the future of finance in Canada.
Globally, the gamification market was valued at $14.87 billion in 2022 and is expected to grow to $30.7 billion by 2025, with a 27.4% yearly growth rate. This shows that using game-like features isn’t just a passing trend. It’s a smart strategy helping companies connect better with users. By following models, Canada’s fintech platforms can meet rising user expectations and keep growing in a competitive market.
Legiano Casino's approach to user engagement offers valuable insights for the fintech industry. By providing a variety of bonuses and rewards tailored to different user profiles, Legiano ensures that each player finds value in their offerings. This personalized approach fosters a sense of loyalty and encourages continued interaction with the platform.
Fintech companies can learn from Legiano's model by implementing similar personalized incentives to enhance user engagement. By understanding user preferences and behaviors, financial platforms can offer tailored experiences that resonate with their audience, leading to increased satisfaction and retention. This strategy not only benefits users but also contributes to the overall growth and success of fintech companies.
Fintech and iGaming share a focus on user engagement, but they serve different purposes and operate under different rules. Online casinos like Legiano Casino aim to entertain with game-based rewards, while fintech must meet strict standards around data and financial safety. Still, both use personalization to keep users involved.
Canada’s fintech industry is built for this kind of innovation. With strong support from programs like NCFA and the Global Hypergrowth Project, startups can safely test new ideas. That’s why many Canadian apps, from budgeting tools to digital banks, are now using game-like features to make finance more interactive and user-friendly.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Regulation | June 13, 2025
Image: Freepik/marymarkevich
Canadian regulators joined a coordinated global crackdown last week targeting unlawful finfluencers, or social media personalities promoting investments without registration or oversight. While enforcement activity is increasingly in focus, global experts and finfluencer advocates are warning that overly restrictive approaches will harm innovation, reduce access to financial education, and weaken digital financial literacy efforts.
As part of the Global Week of Action Against Unlawful Finfluencers, the Ontario Securities Commission (OSC) collaborated with regulators from the UK, Australia, the United Arab Emirates, Italy, and Hong Kong to investigate unlawful influencer activity.
The OSC reviewed 87 finfluencers and 9 issuers that used influencer promotions, and found some were offering unregistered investment advice or sharing misleading content, especially in the crypto sector. In-person warnings, gathering of evidence, and educational outreach were used to prevent retail investors being harmed.
Bonnie Lysyk, Executive Vice President of Enforcement at the OSC:
“International relationships are vital in countering this growing issue. The OSC’s recent research highlights the substantial influence social media personalities have on investor behaviour.”
In May 2025, the International Organization of Securities Commissions - IOSCO published its final report on finfluencers, to address online retail investor safety. Both the OSC and IOSCO's research on the impact of finfluencers were aligned, highlighting risks such as gamification and how social media and trading platforms can blur the line between general information and regulated investment advice.
IOSCO doesn't advocate for bans but rather outlines a series of good practices for regulators, platforms, market intermediaries, and finfluencers:
Jean-Paul Servais, Chair of IOSCO and FSMA Belgium:
“These reports set out globally aligned expectations for ethical conduct and effective oversight... ensuring that technology enhances trust, rather than undermining it,”
Not all creators are breaking the rules. According to the CFA Institute’s 2024 finfluencers appeal report, many finfluencers are filling educational gaps and helping demystify investing and financial planning for younger and underserved audiences. They create digestible and accessible content, often without commercial promotion or investment recommendations. Some are careful to include disclaimers and avoid offering specific advice.
A Wealth Professional Canada article cited Tangerine survey that discovered 60% of Canadians who follow finfluencers said they had benefited from their content. At the same time, those who acted on influencer tips were found to be 12 times more likely to experience scams.
Advocates argue that regulation should distinguish between financial education and commercial promotion. They are calling for clarity on how to remain compliant, not for the removal of content that informs and empowers.
“Most of us want to educate and uplift. But we need the rules to be clear and fair, not just fear-based.”
While Canada takes a proactive, data driven approach to enforcement of finfluencers while increasing public awareness for finfluencer risks, how do we shape up to our peer countries?
In Australia, the Australian Securities and Investments Commission - ASIC released guidance for social media influencers through INFO 269. ASIC warns that creators discussing financial products may be in breach of the law if they are unlicensed and don't follow compliance standards. The guidance supports financial literacy content as long as it avoids over promotion and includes proper disclosures.
In the United Kingdom, the Financial Conduct Authority (FCA) has focused on financial promotions. The FCA targets firms that pay finfluencers to promote investments without regulatory approval and has updated the financial promotions regime to apply to social media content.
Italy’s CONSOB and other European and Middle Eastern regulators also participated in the coordinated enforcement week. These jurisdictions are enhancing joint oversight of social media investment promotions, especially in the context of crypto and speculative assets.
In the United States, regulators such as the SEC and FINRA have pursued enforcement through existing anti-fraud provisions. While there is no finfluencer-specific guidance, recent actions have targeted offside celebrity crypto endorsements and undisclosed paid promotions.
Importantly, none of the major jurisdictions have called for bans, so global consensus is aligning with regulators to build frameworks that promote compliance, transparency, and public awareness instead.
Finfluencers are becoming as influential as traditional advisors, even more so for digitally native and younger investors. So oversight is warranted but the focus should be on compliance that doesn't undermine financial literacy and inclusion. Regulatory consensus shows that with clear rules, good practices, and global cooperation that clear rules and strategic oversight can protect investors while empowering open access to useful financial content online.
Want to stay ahead of regulatory shifts affecting digital finance and investor education? Subscribe to the NCFA newsletter for updates, insights, and expert analysis.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Financing | June 12, 2025

Image: Freepik/rawpixel.com
On June 6, 2025, Gemini announced that it confidentially submitted a draft registration statement to the U.S. Securities and Exchange Commission (SEC) for a proposed IPO of its Class A common stock. The SEC will now review the statement subject to market conditions.
According to Coingecko, the total global crypto market cap has reached $3.5 trillion with Bitcoin holding above $107,000. Stablecoin issuer Circle's IPO debuted on the NYSE in early June with a over 170% on the first day. Coinbase joined the S&P 500 in May.
Gemini’s IPO intent follows the resolution of enforcement matters with both the SEC and CFTC, positioning itself as one of the first fully compliant crypto exchanges to go public since the FTX collapse in 2022.
If Gemini clears the IPO gate in the U.S., the flood gates will be open for a reset of crypto's place in public markets but only for compliant and credible digital asset firms that prove they are ready for institutional trust (and capital) - not just the hype.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Fintech Product Launch | June 12, 2025
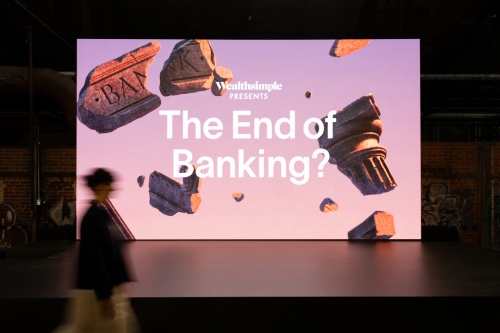
Image: Wealthsimple Presents: The End of Banking (WS Newsroom)
On June 11, 2025, Wealthsimple hosted their first 'Wealthsimple Presents: The End of Banking?" public event in Toronto where they announced the launch of two new financial products that will compete head-on with Canada's largest banks and financial institutions. (1) No fee 2% cashback credit card; and (2) Instant access low rate line of credit starting as low as 4.45%.
These offerings are for anyone who is currently paying banks and credit card companies higher interest rates and fees for the same services, and everything is online and available without having to visit a physical branch. This is healthy competition that will only benefit consumers, and the Canadian government and regulators should take notice.
The company also highlighted a series of upgrades to its hybrid chequing/spending account and teased new cash delivery pilots that could soon offer same day cash drop-offs to users' doorsteps.
Michael Katchen, Co-founder and CEO of Wealthsimple:
“Canadians don’t need another bank. They need something better. We’re removing friction, fees, and outdated experiences.”
The new Wealthsimple credit card is the most requested product in the company’s history. It offers:
Sam Newman-Bremang, Senior Product Director at Wealthsimple:
“This isn’t just another credit card, it’s the one Canadians have been asking for. As the most requested product in our history, it’s clear people want a smarter and more rewarding way to use credit. So that’s what we built: a card that puts humans first, with unlimited cashback, no foreign transaction fees, and no hidden charges.”
Wealthsimple will also roll out a line of credit product by the end of 2025 with rates starting at 4.45%, depending on collateral and client profile. The current Bank of Canada prime rate is 4.95% source, which means Wealthsimple’s offering could undercut many traditional unsecured personal loan products, such as unsecured credit card APRs (20-24%+) or home equity LOC rates (typically 5.5-5.7%).
Unlike typical credit lines, Wealthsimple clients will be able to use their investment or chequing balances at Wealthsimple as collateral, enabling lower risk and faster approval.
Plus, because Wealthsimple is not a federally regulated bank, it partners with 10 Canadian banks to hold deposits and qualify customers for up to $1 million in CDIC protection, which is much more than the standard $100,000 protection one would get by banking at a single institution.
Wealthsimple now offers a type of chequing account that pays 2.75% interest, 1% cashback on debit purchases, no monthly fees, and no ATM or FX fees. Over one million clients or approx 33% of Wealthsimple’s user base has already adopted the spending account.
The company estimates that in 2024, its users saved more than $100 million in fees they would have paid to traditional banks source.
Recent additions include:
Wealthsimple’s growth strategy is grounded in public dissatisfaction with incumbent financial institutions. In a 2025 Angus Reid survey commissioned by Wealthsimple:
Despite this, the Big Six banks still dominate with over 90% of banking assets under management in Canada. But no doubt that Wealthsimple is on a growth pathway that will chip away at the bank's dominant share by competing with seamless design, lower fees, higher yielding accounts and integrated financial tools built for mobile first customers.
Canada's fintech sector continues to face significant barriers to scale, including regulatory delays around open banking and digital ID. Despite that, leading scale-up fintechs like Wealthsimple are demonstrating how digital platforms can expand their value propositions without becoming a formal bank or acquiring a banking license.
Its model has scaled without a banking licence by partnering with regulated banks and embedding services within a single mobile platform. Wealthsimple now has over 3 million clients and manages over $70 billion in assets, up from $18 billion in 2021. If/when opening banking arrives in Canada, platforms that blend investments, borrowing, payments on a single interface will be game-changing for Canada's financial economy.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Policy | June 11, 2025
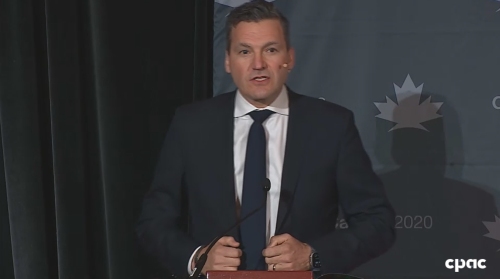
Image: Canada's Minister of AI and Digital Innovation, Solomon Evans Keynote at Canada 2020 event Ottawa (CPAC)
Prime Minister Mark Carney recently appointed Solomon Evans as Canada's first ever Minister of artificial intelligence and digital innovation to lead AI policy development and scale industry, trust and adoption. Solomon just delivered his first public remarks saying that the federal government will prioritize economic growth from artificial intelligence over advancing strict new rules. This new approach follows the collapse of Bill C-27’s AI framework, which failed to pass before the election and left Canada without a federal AI law.
Delivering a key note at a Canada 2020 event in Ottawa on June 10, 2025, Solomon said regulation must protect privacy and personal data but should not constrain innovation. Solomon confirmed that the previous governments AI regulation bill is currently under review.
“We’re not here to throw a saddle on the bucking bronco of AI but we do need to make sure it doesn’t kick anyone in the face.”
Feeling the heat of competition, even governments feel FOMO, and the global trend currently is moving from AI safety messaging towards AI adoption strategies. At the AI Action Summit in Paris, U.S. Vice President JD Vance pushed back on Europe’s regulatory overreach, while President Trump’s draft 'One Big Beautiful Bill' includes a proposed ten-year ban on state-level AI rules. Solomon seems aligned with this shift suggesting that global coordination is difficult, and Canada “won’t go it alone”.
NCFA Canada supports a speedy, focused rollout of AI investments that prioritize open access and trust, especially for smaller firms. Without clear guidance, shared tools and integrate support, SMEs will fall behind. Most do not have the internal capacity to evaluate or safely integrate AI, and that puts Canada’s productivity and innovation milestones in jeopardy. Canada's new AI czar, Solomon, acknowledged this gap, saying big companies are adopting AI, but “small and medium enterprises are not.”
Solomon also emphasized government support for Canadian champions like Cohere. In cases where specialized technical leadership is required to build national AI infrastructure, such as secure compute environments, working with proven domestic firms can make strategic sense. But NCFA cautions that these partnerships must be transparent, based on merit, and designed to benefit the broader ecosystem. The priority must remain funding open infrastructure and access, not enabling a sustainable advantage to a select few. Without transparency on this front, Canada risks loss of investment, talent, and IP.
The reality is that Canada’s innovation economy simply can't afford red tape bottlenecks or further restrictions that slow AI growth, especially since its hoping that broad adoption of the technology will turn the countries productivity woes around.
Canada also can't afford regulatory ambiguity that raises red flags for domestic and global firms alike. Solomon says he wants to “crank up commercialization” and support IP protection. That will only work if firms trust the environment they’re entering. For that, Canada needs smart policy, not just encouragement.
Canada is in a global race to lead in responsible AI and having a dedicated AI minister is a positive step, but evolving Canada into a trusted AI economy depends on speed, clarity and inclusion among other things. NCFA calls for the government to boost support for SME adoption, ensure rules are clear and fair, and build national infrastructure that attracts global innovators without sidelining local ones.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016