




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


CIX Summit | Jan 13, 2026
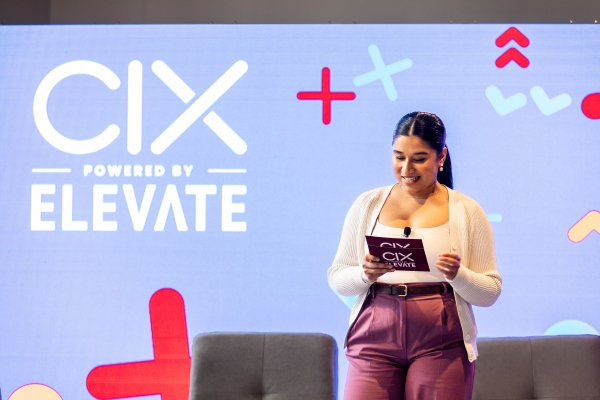
Image courtesy of CIX Summit
Mark your calendars! On March 25, 2026, CIX Summit returns to Toronto, bringing together high growth Canadian technology companies, global investors, and industry advisors for one of the country’s most established startup investment and awards events. NCFA is pleased to participate as an official Community Partner again this year, supporting broader visibility and access for founders and operators across our network.
Powered by Elevate, CIX Summit has built a long standing role in Canada’s innovation landscape by focusing on companies that demonstrate real traction, credible leadership, and scale potential. The event combines curated startup awards with a focused investment audience, creating a setting designed for meaningful conversations rather than surface level networking.
CIX Summit 2026 takes place at Design Exchange in Toronto, a venue that reflects the event’s emphasis on execution, discipline, and growth. The program brings together founders who are actively building, investors looking for deployable opportunities, and advisors who understand the operational and regulatory realities of scaling companies in Canada and internationally.
NCFA’s role as a Community Partner reflects our continued focus on improving access to capital, strengthening founder investor connections, and supporting platforms that prioritize quality over volume. Events like CIX matter because they concentrate attention on companies that are ready for the next stage, while helping investors identify teams with credible paths to growth.
As part of this partnership, NCFA is sharing an exclusive 20% discount on all CIX Summit passes for its community.
Use CIXNCFA20 for 20% off. Spots are limited! ✅
For full event details, CIX startup awards, program updates, and to get your tickets, visit https://cixsummit.com/
Stay tuned as NCFA will continue to share updates as CIX announces its Startup Awards finalists and Innovator of the Year, and as the program takes shape leading into March.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Competition | Jan 13, 2026

Image: Freepik/pch.vector
On January 12, 2026, Canada's Competition Bureau announced a market study in small and medium sized enterprises (SMEs) financing (see press release), with a focus on term loans. Canada already has extensive data showing that SME lending is concentrated, borrowing costs are higher for small firms, and switching lenders is rare. What it doesn't yet have is proof of why these outcomes persist and is evaluating market structure.
Jeanne Pratt, Acting Commissioner of Competition:
“Access to credit is critical to the survival and success of many Canadian small and medium businesses. Our study will examine competition in lending for SMEs, and how it can be improved. More competition would make a real difference for growth, investment and innovation.”
In 2023, nearly half or 49.3% of Canadian SMEs relied on external financing, and debt financing remains heavily concentrated among incumbents. Chartered banks supplied 68.5% of SME debt financing, credit unions accounted for 20.6%, government backed lenders provided 9.4%, and online alternative lenders only 2.2%, according to Statistics Canada’s 2023 SME financing data.
Borrowing costs also diverge sharply by firm size. Analysis cited by the Competition Bureau shows that Canadian SMEs pay higher interest rate premiums than large firms compared with SMEs in other OECD countries, with the difference reaching 1.64 percentage points in 2021 and 2.10 percentage points in 2022 compared with OECD averages of 0.93 and 0.90 points respectively. This suggests small businesses pay more not because credit is unavailable, but because lenders face limited competition.
OECD data quoted by the Competition Bureau shows that Canadian SMEs have paid interest rate premiums on loans that exceed those of large firms by more than in most other OECD countries, with the difference reaching 1.64 percentage points in 2021 and 2.10 percentage points in 2022 compared with OECD averages of 0.93 and 0.90 points respectively.
Switching lenders remains rare. Research cited by the Bureau shows that only about 10% of business owners actually switch lenders, even when better terms exist, and that personal guarantees and pledging a primary residence remain common requirements, based on CFIB research on financing barriers facing small businesses.
These figures describe the outcome but they don't break down in detail and explain the cause.
Aggregate datasets cannot show how competition breaks down in practice.
They don't reveal how long it takes an SME to refinance across providers, how bundled operating accounts, payments, and credit products raise switching costs, or how limits on data access affect underwriting decisions.
They also cannot show whether challenger lenders face higher funding costs or regulatory friction that incumbents do not, or whether government programs close genuine market gaps or quietly reinforce existing lending structures.
That evidence exists only inside real transactions. A market study creates a formal record that allows these details to be tested, compared, and evaluated in a way policymakers can rely on.
Term loans fund long term investment in equipment, technology, facilities, and expansion. When competition fails at this level, SMEs delay productivity enhancing investment, not because capital is unavailable overall, but because it is unavailable on workable terms.
This links SME lending directly to Canada’s productivity problem. The Bank of Canada has repeatedly warned that weak business investment constrains productivity growth. NCFA has previously highlighted how senior Bank of Canada leadership has explicitly described Canada’s banking system as an oligopoly affecting competitive outcomes, reinforcing that market concentration is structural, not theoretical.
When a few lenders dominate the market and businesses cannot easily switch, higher costs and tighter terms persist year after year.
The competition bureau's study is testing one issue with significant consequences.
Are Canadian SMEs paying more and accepting tougher loan terms because of unavoidable risk, or because competition is structurally constrained?
If borrower risk explains the outcome, policy options remain narrow.
If market structure explains it, reform becomes unavoidable.
That distinction will determine how future decisions are made on switching rules, data portability, funding access, and competition policy in SME finance.
The Competition Bureau is asking for evidence.
SMEs can submit examples of failed refinancing attempts, excessive collateral requirements, and barriers that prevent moving to better terms. Fintech lenders, brokers, and platforms can submit evidence showing where entry and scaling breaks down, including limits on data access, funding costs, or regulatory friction that incumbents do not face.
Anonymized term sheets, approval timelines, refinancing costs, bundling effects, and side by side comparisons across providers will carry weight.
For fintechs, SMEs, and advocates, this is not a communications exercise. It is a narrow window to place real market evidence on the record before conclusions harden into policy. Submissions can be made through the Competition Bureau’s SME financing market study participation page or by emailing the study team directly at smemarketstudy-etudedemarchepme@cb-bc.gc.ca.
If challengers and SMEs don't define the evidence, incumbents will define the outcome.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Prediction Markets | Jan 12, 2026

On January 10, 2026, prediction markets were back in the spotlight when an anonymous trader wagered more than $30,000 USD on the removal of Venezuelan president Nicolás Maduro and later collected over $400,000 USD once the outcome became public. No regulator has confirmed insider trading and no enforcement action has been announced, but the successful trade result matters because it shows how quickly prediction markets can price almost anything including geopolitical outcomes ahead of official confirmation.
It's another visible, benchmarked stress test of a category that has been scaling quietly for years. Prediction markets have gone mainstream and are evolving into fast moving information markets that sit at the intersection of finance, media, and public policy. In some way, they're beginning to resemble consumer finance products rather than novelty bets. Then distribution was another recent inflection point when MetaMask added Polymarket access directly inside its self custody wallet, prediction markets moved closer to everyday crypto workflows. Once markets become native features rather than standalone destinations, scale accelerates.
Prediction markets scale because they sell something scarce. A continuously updating probability signal backed by capital. Traders adjust prices faster than surveys (as they have skin in the game). Media repeats those prices as indicators. Investors track them as sentiment inputs and risk signals. That loop turns a market price into a reference point that travels quickly across sectors.
At scale, intent matters less than structure. Markets don't need bad actors to create risk. Risk emerges when incentives move faster than controls. The Maduro trade illustrates this dynamic without proving wrongdoing. A sensitive geopolitical outcome was priced by a market before institutions and the public had time to react.
Regulatory friction starts with classification, and prediction markets sit between gambling and financial products, depending on jurisdiction and design.
In the United States, Kalshi operates as a designated contract market overseen by the Commodity Futures Trading Commission. The CFTC explains that designated contract markets are federally regulated trading venues subject to surveillance, reporting, and market integrity requirements in its Designated Contract Markets overview. US regulators and courts continue to debate which categories of event contracts are appropriate for trading under this structure, particularly where contracts resemble gambling rather than traditional risk management.
Polymarket followed a different path. The platform previously faced enforcement action from US regulators for offering unregistered event based binary options to American users, resulting in a monetary penalty and a wind down of those markets. Then the company experienced a regulatory reset. NCFA previously covered how Polymarket earned approval to relaunch in the US.
Canada banned short term binary options for retail investors in 2017 after widespread fraud harmed consumers. The Canadian Securities Administrators set out the prohibition and its scope, and clarified that products paying out on simple yes or no outcomes fall within that restriction under Multilateral Instrument 91-102. Because most prediction market contracts share that payout structure, independent prediction markets are effectively prohibited unless operated directly by provincial gaming authorities.
That approach reduced direct consumer exposure. It did not eliminate influence. Canadians still consume market driven narratives generated elsewhere. Market odds circulate through global media and social platforms regardless of domestic rules. Capital continues to flow to platforms operating in more flexible jurisdictions.
The Maduro payout highlights a structural challenge rather than an allegation. When markets are novel, fast, and global, existing frameworks struggle to answer basic integrity questions.
In traditional securities markets, insider trading rules address the use of material non-public information. Prediction markets often sit outside that framework. Platforms may prohibit insider use contractually, but enforcement becomes difficult when identity is masked and funds move through crypto rails.
Integrity risks extend beyond insider advantage. Wash trading incentives can distort volume. Thin liquidity in long tail markets can exaggerate price movement. Concentrated positions can temporarily push odds that then echo through coverage and perception. These dynamics do not stay contained within the platform.
Prediction market operators often describe their platforms as sentiment barometers. Prices aggregate belief. Odds update with new information. That framing holds more easily on entertainment or sports outcomes.
It gets harder when markets trade on politics, elections, or government decisions. Prices stop being just signals of opinion. People notice them, talk about them, and react to them. Once those prices show up in headlines, they start to influence how investors, the media, and the public think about what is likely to happen. Markets that say they only reflect reality can end up helping to shape it.
Prediction markets are scaling because they meet demand for real time signals in an uncertain world. Regulators now face a strategic choice. Continue treating these platforms as edge cases, or acknowledge that they are becoming part of the financial and information ecosystem and design rules accordingly.
For Canada, the question is whether governance evolves in step with market reach, or whether influence continues to arrive from outside the regulatory perimeter.
When markets bet on geopolitics, the issue is not the trade itself. It is whether the rules governing markets, information, and incentives are built for the reality that now exists.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
January 9, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Digital Assets Blockchain And Tokenization, Payments And Money Movement, Regulation And Policy

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025)
This moves crypto distribution deeper into mainstream wealth plumbing where compliance, custody, and operational control define who wins. Founders should plan for bank grade diligence on custody, reporting, and risk controls, and investors should expect value to concentrate in infrastructure that supports regulated product distribution, not retail hype cycles.
Moves from experimentation to system level execution for a sovereign digital currency. For fintechs and infrastructure providers, the signal is not retail adoption but architecture. Digital money is being designed as a governed liability with defined operational rules, which sharpens competition between CBDCs, stablecoins, and tokenized deposits. Founders should watch where interoperability, wallet design, and settlement interfaces align with central bank control, and investors should expect digital money infrastructure to increasingly price around governance and balance sheet integration rather than novelty.
This tightens the path for payment fintechs that rely on regulatory ambiguity to move fast. Founders selling into India or routing flows through India should treat governance clarity as a timeline accelerator for compliance builds and a bar raiser for risk and controls, especially for cross border money movement and large scale consumer rails.
This raises the governance bar in a part of the banking system that often intersects with local credit, deposits, and community distribution. Fintechs that partner with co operative banks should expect tighter board level scrutiny on vendor selection, risk oversight, and operating controls, especially where products touch lending, onboarding, and customer outcomes.
OSFI resets the near term work queue for banks and insurers, and that changes where compliance and risk budgets land first. Fintechs that sell governance, reporting, climate data, or risk tooling win more deals when they attach to everyday evidence and controls that teams must run year round, not one time deadline projects that slide when priorities change.
This extends a bank style public interest standard into non bank mortgage lending. Fintech mortgage lenders that want scale in New York now need measurable community lending performance alongside compliant underwriting.
This pulls pricing design into enforcement scope. Fintechs that rely on fee complexity to lift margins now face a tighter line on what counts as fair dealing at the point of sale.
This treats retention design as a consumer protection issue. Fintech subscription models now need clean consent, simple cancellation, and pricing clarity that holds up under scrutiny.
This turns proficiency into an operational constraint across the dealer channel, and it pushes firms to modernize how they manage role readiness at scale. Founders building wealth infrastructure can win by solving proficiency workflow friction across recruiting, training evidence, supervision, and audit trails, and investors should watch for platforms that become the system of record for dealer readiness.
This makes cost disclosure a data integrity and evidence problem, not a communications exercise. Founders should expect dealers to prioritize vendors that prove traceable fee logic, clean client presentation, and compliance evidence, and investors should treat reporting accuracy as a differentiator that drives conversions in regulated distribution.
This forces crypto linked product teams to design around bank balance sheet constraints instead of assuming unlimited partner capacity. Founders should tighten classification, exposure monitoring, and governance artifacts that bank partners can defend to supervisors, and investors should prefer models that grow without breaching capital linked limits that slow distribution.
This week highlights where early intent and hard execution both matter. A major US bank filing for crypto ETFs pushes regulated wealth distribution toward broader digital asset access, while Canada moves dealer proficiency and cost reporting into day to day operating reality and tightens how institutions treat crypto exposures in capital planning. At the same time, India’s moves on payments oversight and bank governance show that even high growth markets are prioritizing supervisory clarity, signalling that scale increasingly comes with stricter operating expectations rather than looser ones. NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Quantum Financing | Jan 9, 2026

Image: Unsplash/Planet Volumes
On January 6, 2026, Photonic $180M CAD financing led by UK based Planet First Partners brought large scale foreign capital into Canada’s quantum sector, with new Canadian institutional participation from RBC and Telus. At the same time, Ottawa launched Phase 1 of the Canadian Quantum Champions Program, committing up to $92M CAD across four companies, including Photonic, Xanadu, Nord Quantique, and Anyon Systems, as part of a $334.3M five year federal quantum investment announced in Budget 2025.
The timing suggests that Canada’s multi year quantum funding commitment may have helped lower perceived risk for both foreign investors and Canadian institutions, even though no direct causal link has been publicly stated. Public funding keeps core quantum builders anchored domestically, while private capital begins to treat leading teams as institutional grade businesses rather than long term research projects. As outlined in British Columbia Investment Management write-up who also participated in Photonic's round, when public and private capital move together at this scale, founders and global buyers take Canada more seriously.
Having said that, in 2026 what actually matters is not running quantum workloads, but preparing for the security, regulatory, and capital consequences that this level of quantum funding now creates.
The strongest counterpoint does not come from skeptics. It comes from how enterprise leaders rank priorities. For example, the Gartner Top Technology Trends 2026 does not include quantum computing among its top ten themes. CIO agendas continue to focus on AI platforms, security posture, provenance, and geopolitical resilience. That does not dismiss quantum, but it does highlight a timing gap between capital commitment and operational adoption.
Government timelines reinforce that gap for quantum computing itself. The US Defense Advanced Research Projects Agency frames its Quantum Benchmarking Initiative around proving whether any approach can reach utility scale quantum systems by 2033, defined as performance where value exceeds cost. For most buyers, that horizon places 2026 clearly in preparation mode rather than procurement for quantum compute workloads.
Security planning, however, tells a different story. The Forrester 2026 technology and security outlook projects that quantum security spending will exceed 5% of total IT security budgets in 2026. That spending focuses on migration planning, cryptographic discovery, and inventory tools to prioritize high impact systems. This does not signal near term adoption of quantum computers. It shows that quantum already matters operationally through security readiness, compliance pressure, and budget allocation.
The above explains why quantum feels both early and urgent at the same time. Compute remains longer dated, but security and cryptography move first. In August 2024, NIST finalized post quantum cryptography standards with explicit guidance for organizations to begin transitioning, and Canada aligns with that direction through federal quantum safe cryptography guidance.
Concurrently, Canada’s quantum builders continue to clear independent validation gates. As of November 6, 2025, DARPA Quantum Benchmarking Stage B advances 11 companies globally. Canadian firms Photonic, Xanadu, and Nord Quantique have progressed to this stage, which may matter more than domestic promotion.
In 2026, the real risk is committing too early to cryptography, vendors, or long-term contracts that cannot adapt as post-quantum requirements take shape. The combination of the Photonic financing and the $334.3M federal commitment makes this risk harder to ignore, not because quantum computers arrive tomorrow, but because capital and policy are both pointing toward future regulatory expectations. Regulators and auditors do not need quantum machines to ask whether systems can migrate without breaking core functions.
In practical terms, quantum readiness in 2026 means crypto agility, understanding where cryptography sits across the stack, and pressure testing suppliers against post quantum encryption standards. This work costs far less than a rushed migration later and fits inside security and compliance budgets that already exist.
The combination of a $180M CAD foreign led financing, $92M CAD in Phase 1 federal funding, and a $334.3M five year national quantum commitment puts Canada into a new category in 2026. Quantum still won't drive enterprise workloads in the near future, but for fintechs, banks, and infrastructure providers, the practical focus this year is crypto agility, supplier flexibility, and readiness for post quantum standards, not experimentation for its own sake.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Seed Financing | Jan 7, 2026

Image: Freepik
On December 18, 2025, Peripheral Labs confirmed $3.6M USD seed funding round led by Khosla Ventures with participation from Daybreak Capital, Entrepreneurs First, Transpose Platform, and angel investors. The Canada based startup was founded in 2024 and builds volumetric video systems that reconstruct live sports moments in three dimensional space.
Peripheral Labs enables fans to move through live plays, freeze moments, and change perspective in real time rather than watching fixed broadcast angles. The technology applies sensor systems and machine learning techniques originally developed for autonomous vehicles.
The company currently employs around 10 engineers and plans to use the seed capital to expand its technical team and scale deployments across larger venues. This isn't a content company chasing highlights. It's part of the new infrastructure stack for how live experiences get built.
Investors are backing Peripheral Labs because audience engagement has changed, not because sports needs another broadcast upgrade.
Sports Business Journal reported on how volumetric video targets younger sports audiences, CEO Kelvin Cui described the gap the company is addressing:
“When I was a kid, I never really understood why there wasn’t a closer gap between broadcast media and the interactive experience that we had from video games. What we’re aiming to do is bring an interactive and immersive experience to fans so that especially we can target that younger audience.”
Gen Z audiences expect control, presence, and participation. They rewind, explore, and share moments while events are still unfolding. Sports provides a high pressure environment to test whether immersive systems can meet those expectations at scale.
Peripheral Labs applies neural rendering, robotics perception, and spatial intelligence methods originally developed for autonomous vehicle systems. The company works with off the shelf cameras but applies proprietary machine learning to reconstruct environments accurately and efficiently.
According to TechCrunch coverage, volumetric capture is reduced from over 100 cameras to roughly 32, so the system materially lowers cost and expands the range of venues that can support immersive deployments. Cui explained the scaling advantage as:
“While we work with off the shelf cameras, the way we package it with our experience in robotics and ML is what gives us an edge both in terms of platforms and also scaling from small practice enclosures to big soccer and football stadiums.”
The company is already in active discussions with North American teams on proof of concept deployments, including coaching analysis and officiating review.
Peripheral Labs is showing us what happens when fast moving, high stakes systems stop being explained through flat screens and start being experienced spatially. That same challenge exists in finance.
Most fintech products still communicate value and risk through dashboards, charts, and alerts. That assumes users want to read and interpret information. Younger users increasingly expect systems to show them what is happening instead.
Spatial systems suggest a different model for financial services may be possible in the future. Transactions could appear as live flows rather than static entries. Portfolio movement could be observed as structure changing over time rather than abstract numbers. Risk could be understood visually as proximity or pressure instead of complicated disclosure text.
These innovative changes wouldn't remove the controls, compliance, or math. It would however change how systems communicate.
As financial services become embedded into everyday lives and move into games, creator platforms, and digital environments where forms and menus feel out of place, spatial interaction becomes an opportunity to interact with younger market segments in a way that's suitable for the times.
For fintech founders and institutions, spatial technologies are one to watch as they can profoundly change how users interact, which can lead to stronger trust. Teams that treat interface decisions as secondary may struggle to engage the next generation of users, regardless of pricing or performance. Peripheral Labs is a confirmed Canadian sports technology funding story that will reveal insights of how digital systems will be expected to behave in the future. While finance won't be the first in the spatial tech space, it's unlikely to remain untouched (think smart glasses and real time AI assistants).
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
CES | Jan 6, 2026

CES 2026 opens today in Las Vegas and runs from January 6 to 9. As the world’s largest global technology event, CES matters because it is where platform providers, manufacturers, and system builders preview the technologies they intend to scale next.
This year, the most important signals aren't from individual gadgets. They appear in pricing models, performance benchmarks, and deployment timelines that show how AI is moving beyond software and into physical systems. Combined, these signals offer an early view into how cost, performance, and risk will be distributed as AI becomes increasingly embedded in devices, vehicles, and industrial environments.
CES (Consumer Electronics Show) is the largest global marketplace where product teams, buyers, investors, and regulators assess the same technologies at the same time. An independently audited Consumer Technology Association (CTA) report shows that CES 2025 attracted 142,465 attendees, including 81,621 industry professionals and 6,582 media participants, with international attendees accounting for 40.2% of the total audience. When decisions surface at this scale, they tend to lock in quickly.
Control over AI cost, performance, and risk increasingly sits with global platform providers and system manufacturers that define pricing models, performance benchmarks, and deployment architectures long before regulators or end users can respond.
The intensity of competition shows up before products even reach the market. The CTA reports more than 3,600 Innovation Awards submissions for 2026, the highest on record. Robotics related submissions rose 32% year over year, and confirms the evolution in buyer expectations.
AI and automation no longer differentiate products. They define the minimum bar. Vendors now compete on cost, reliability, and control rather than novelty.
The most consequential CES announcement focuses on economics rather than spectacle. Nvidia introduces the Vera Rubin platform and frames AI progress around efficiency and scale. Reporting on the launch shows that Rubin delivers five times the AI training performance of the prior generation and reduces inference token cost by up to 90% for certain workloads.
This is important for fintechs and financial institutions. When AI is priced per token, it moves from innovation spending into operating expense. That shift forces harder questions about vendor concentration, auditability, and resilience. Pricing power becomes a strategic risk, not a technical detail.
CES 2026 also standardizes how local AI performance gets measured. HP announced consumer laptops delivering up to 85 TOPS of on device AI processing, while AMD introduced processors offering up to 60 TOPS (tera operations per second, measure of how many AI calculations a chip can perform locally,). These figures cross a practical threshold where many everyday inference tasks no longer require the cloud.
For financial services this changes system design. Fraud detection, authentication, and customer support logic begin to fragment across millions of devices. Latency drops and some privacy risks ease, but update cycles, model drift, and endpoint security become harder problems.
Robotics are no longer conceptual at CES 2026. Hyundai outlined plans to deploy Atlas humanoid robots in US factories starting in 2028. According to reports, production capable units can lift up to 50 kilograms and operate across wide temperature ranges, with annual targets reaching up to 30,000 robots by 2028.
These numbers signal factory scale, not experimentation. Automation at this level reshapes supplier economics, insurance models, and capital planning across industrial ecosystems. Financial institutions that support equipment finance, trade credit, and risk underwriting will feel these effects early.
Highly connected vehicles continue to evolve into software environments. Sony Honda Mobility of America confirmed that Afeela 1 launches at $89,900, targets roughly 300 miles of range, and begins California deliveries in late 2026.
As vehicles embed identity, subscriptions, and payments, financial services move into AI powered physical environments with new liability and dispute dynamics. Authentication, consent, and fraud controls will need to work seamlessly across phones, vehicles, and homes.
The first day of CES 2026 marks a clear transition from possibility to commitment. AI now carries published token pricing. Performance is measured in TOPS rather than marketing claims. Automation arrives with factory volumes and deployment years. Devices and vehicles embed identity, payments, and continuous data flows into everyday consumer and B2B activity.
For Canada’s fintech ecosystem, it spotlights a structural tension. Platform power increasingly concentrates outside the country, while operational risk, compliance, and consumer protection responsibilities remain domestic. At the same time, Canada’s ability to govern digital platforms and data flows sits within binding trade commitments. As outlined in CCPA's analysis of how digital trade rules now shape national policy space, agreements such as CUSMA constrain local data requirements, differentiated treatment of foreign digital services, and mandatory platform transparency. That constraint now collides with what CES brings to market. AI chips, on-device inference, embedded finance, and physical automation all rely on cross border digital products and data flows that Canada doesn't control. The question is no longer whether these systems arrive, but how they operate once they do.
The direction for Canada is clear. Competing on platform scale is not realistic. Competing on trust is. That means using Canada’s policy window to set clear expectations for digital identity, payments interoperability, data governance, and consumer protection before these technologies become deeply embedded in everyday consumer and B2B activity.
CES offers a glimpse of what is coming. Canada’s advantage will come from deciding NOW how it wants that future to work.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016