




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 23, 2026

In 1962, Rolls-Royce made an unusual decision for an engine maker. Rather than simply selling engines for the de Havilland 125 business jet and billing operators whenever something went wrong, it offered a complete engine and accessory replacement service charged at a fixed cost for every hour flown. It called the idea Power by the Hour.
You see, the operators didn't want to own a maintenance problem, they wanted engines that worked. Six decades later, that same distinction between owning a thing and paying for what it does sits behind some of the biggest financial decisions businesses and wealthy individuals make.
An expensive asset costs money while you use it. It also costs money while it sits there.
That second cost is the one people usually always underestimate. Insurance, storage, servicing, staff and depreciation all keep running on the days nothing happens. Spread over heavy use, those fixed costs become manageable. Spread over light use, they make each hour of actual value very expensive.
Let’s take a simple example. An asset with £1 million a year in fixed costs, used for 400 hours, costs £2,500 an hour before anything else is added. Use it for 100 hours and the same asset costs £10,000 an hour. Nothing about the asset changed, only the usage did.
Construction is not an industry known for embracing subscriptions. Tradespeople take pride in their kit. So when Hilti launched its Fleet Management programme, the idea of contractors renting power tools met real resistance.
And yet, the pitch worked anyway. Customers pay a monthly fee covering the use, servicing and repair of their tools, with no upfront purchase. Tools are replaced with newer models on a regular cycle, and theft and breakdowns are covered.
What the contractor gains is not really a drill. It's the certainty that a broken tool on a Monday morning doesn't stop a job, and that money which would have been sitting in a tool store is available for payroll, materials or the next contract.

Image by Lorraine Robinson from Pixabay
Yachts show the problem at its most extreme. The long-standing industry rule of thumb holds that a yacht costs around 10% of its purchase price to run every year. As YachtBuyer points out, that rule becomes badly misleading for larger crewed or older vessels, because the boat's value falls while its running costs climb.
Now factor in how often owners actually go to sea. Industry usage data suggests a typical owner uses their yacht for somewhere between four and eight weeks a year. The crew, berthing and maintenance bills arrive for all fifty-two.
For someone who wants a fortnight in the Aegean each summer, chartering does more than save money. It means choosing a sailing yacht one year and a larger motor yacht the next, in whichever sea suits the season.
Business aviation may be where this calculation is most precise, because every cost can be counted by the flight hour.
Owning an aircraft brings crew salaries, hangarage, insurance and management fees whether it flies or not. The broad consensus in the industry is that whole ownership starts to make financial sense somewhere in the region of 200 to 400 flight hours a year, depending on the aircraft.
Plenty of companies and individuals fly nowhere near that. A board that needs to visit three European sites in a single day, or a family heading to a small Alpine airstrip twice a season, has a real need for private aviation, but not for a full-time aircraft. For them, private jet charter delivers what actually matters: the right aircraft for each specific trip, whether a light jet for a short hop or a long-range jet for a transatlantic meeting, with none of the ongoing overheads.

Image: Pexels/RDNE Stock project
None of this makes ownership a bad idea. It makes it a decision that depends on the numbers.
Heavy, predictable use changes the maths quickly. So does a need for total control: a particular cabin configuration, crew who know your preferences, an aircraft ready at an hour's notice every day of the year. There's also a middle ground. Leasing, fractional shares and block-hour arrangements sit between full ownership and one-off bookings, and each suits a different usage pattern.
The mistake is treating ownership as the natural reward for success rather than as one option to be costed alongside the others.
The shift towards access is really about where money works hardest. Capital held in an asset used a few weeks a year cannot also fund an acquisition, a new market or an opportunity that turns up unexpectedly.
Rolls-Royce understood that in 1962. Its customers wanted flying hours, not engines. The most useful question to ask of any expensive asset is the same one: are you paying for the thing, or for what it lets you do?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 23, 2026

An impaired driving charge in Calgary can cost you your licence, your job, and your insurance rate within days of the traffic stop. The three best criminal lawyers in Calgary for impaired driving charges listed below all defend DUI, over 80, and refusal cases in Alberta courts. Each one is picked for courtroom experience, clear pricing, and a track record with driving-related charges.
Before the list, it helps to know what you are actually facing.
Most drivers in Alberta face two separate processes after an impaired driving stop: a roadside sanction from the province and a possible criminal charge under the Criminal Code of Canada.
Immediate Roadside Sanctions (IRS). Alberta police can issue an administrative penalty on the spot. An IRS FAIL penalty usually brings a $1,000 fine, a 90-day licence suspension, and a 30-day vehicle seizure. You dispute it through SafeRoads Alberta, and the window to do that is short. [CONFIRM: current SafeRoads review deadline before publishing]
Criminal charges. Police can also lay a charge under section 320.14 of the Criminal Code. Common charges include:
A first conviction carries a mandatory minimum fine of $1,000, rising to $2,000 for a refusal, plus a driving prohibition and a criminal record. A lawyer can look at whether the stop was lawful, whether the breath demand was valid, and whether the testing followed the rules.
Wyman & Williamson is a Calgary criminal defence firm led by two senior lawyers, James Wyman and Jillian Williamson, who defend impaired driving, over 80, and refusal charges alongside a full criminal practice. James was called to the Alberta bar in 2010 and has argued before the Supreme Court of Canada. Jillian graduated from the University of Calgary Faculty of Law and was called in 2013.
The firm appears almost daily in the Alberta Court of Justice and the Court of King's Bench. That matters for impaired driving files, because most of these cases are decided by how well a lawyer knows local Crown prosecutors and the Charter arguments that apply to roadside stops and breath demands.
Why it stands out for impaired driving charges:
The firm reports more than 2,000 cases defended and 185+ five-star Google reviews. It also publishes its case results, including the charge, the court, and the outcome, so you can check its work before you call.
Serves: Calgary, Airdrie, Canmore, Drumheller, Red Deer, Lethbridge, Edmonton, plus courts in Saskatchewan and British Columbia.
Best for: Drivers who want senior lawyers, a flat fee, and a firm that handles both the roadside sanction and the criminal charge.
Dunn & Associates is a downtown Calgary criminal defence firm whose lawyers regularly handle impaired driving, dangerous driving, and DUI appeals. The firm is led by Greg Dunn, and lawyer Vince Semenuk handles a large share of its driving-related files.
Client feedback for the firm points to results on driving charges specifically. Former clients describe impaired and dangerous driving charges being successfully defended, DUI charges being dropped, and appeals being taken forward when the first result was not the right one.
Why it stands out for impaired driving charges:
Contact: 801 6 Ave SW, Suite 2610, Calgary, AB T2P 3W2. Phone: 403-233-0443.
Best for: Drivers facing impaired or dangerous driving charges who may need an appeal as well as a trial defence.
Wilson Criminal Defence is a Calgary criminal defence practice led by Cory Wilson that handles impaired driving charges and Immediate Roadside Sanctions disputes. The firm works out of Chadwick House on 14 Street SW, just outside the downtown core.
Clients describe Cory Wilson as direct and responsive, with regular email updates throughout a case. Reported results include a successful outcome on an IRS roadside sanction and criminal charges thrown out at trial.
Why it stands out for impaired driving charges:
Contact: Chadwick House, 1842 14 St SW, Main Floor, Calgary, AB T2T 3S9. Phone: 403-978-6052.
Best for: Drivers who want a lawyer to fight both a roadside sanction and a criminal impaired driving charge.
The right impaired driving lawyer in Calgary is one who does criminal defence full time and has taken driving cases to trial. Ask these questions at your consultation:
An impaired driving charge in Alberta can be withdrawn or stayed when the evidence has problems, such as an unlawful stop, an invalid breath demand, or delays that breach your Charter rights. Whether that applies depends on the facts in the Crown's disclosure, so a lawyer needs to review the file first.
A lawyer is strongly recommended for a first-offence DUI in Calgary, because a conviction brings a criminal record, a minimum $1,000 fine, and a driving prohibition. Many first-time drivers have defences they do not know about until a lawyer reviews the evidence.
Impaired driving lawyer fees in Calgary depend on whether the case resolves early or goes to trial. Some firms, including Wyman & Williamson, charge a flat fee with payment plans instead of hourly rates. Ask for the full cost in writing at your first consultation.
You should speak to a lawyer before giving any statement to police after an impaired driving arrest. You have the right to contact counsel, and anything you say can be used as evidence.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 15, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Embedded Finance, Artificial Intelligence And Data
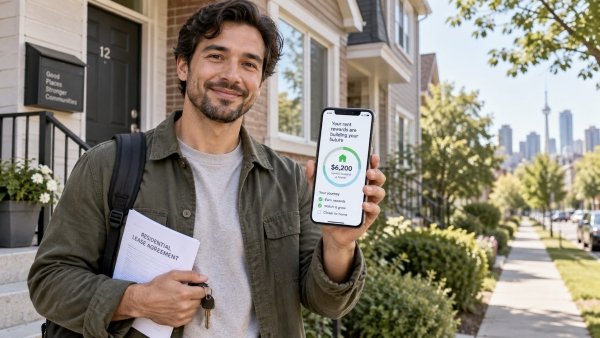
On September 15, 2026, Toronto-based Canadian proptech Zown updated its homebuying app with Rent Rewards alongside AI property search, affordability estimates, mortgage pre-approval and transaction services. Zown advertises up to 8% back on rent, giving it a reason to start working with consumers years before many will be ready to buy a home.
The 8% combines two potential rewards. Zown Money says Zown currently provides up to 4% cashback directly on rent, while an eligible credit card can add up to another 4% depending on the card's terms. At C$2,500 in monthly rent, Zown's 4% portion would equal C$100 a month or C$1,200 a year. If a renter also earned the full additional 4% through their card, the total could reach C$200 a month or C$2,400 a year before any card or payment-related costs.
The Canadian iPhone app, developed by Zown Realty Inc., also lets users upload a lease and proof of rent, search properties through an AI assistant called Zoro, view estimated affordability, request showings with licensed agents, seek mortgage pre-approval, submit offers and coordinate parts of closing. Zown Realty is an Ontario-registered real-estate brokerage. Mortgage rates, terms and qualification are provided through Vine Mortgage Group, and Zown says it isn't a direct mortgage lender.
Zown's model starts with a difficult Canadian problem. CMHC's 2026 Mortgage Consumer Survey found that recent buyers needed an average 4.4 years to save a down payment, while first-time buyers needed 4.7 years. Savings supplied the largest share of the down payment for 51% of first-time buyers. Another 23% of homebuyers received a financial gift, with a median gift of C$30,000. Rent Rewards give Zown a recurring reason to stay connected during those years.
Zown already has a more established incentive for buyers. Its Down Payment Boost returns up to 1.25% of a home's purchase price, capped at C$25,000, using part of the brokerage economics generated when a customer buys through Zown. On a C$1 million home, 1.25% equals C$12,500. Despite the product name, Zown's current guidance says the money arrives at closing and isn't counted as part of the mortgage down payment itself. Buyers can use it for closing and post-closing expenses.
Zown isn't alone in treating rent as financially useful activity. KOHO introduced rent cashback and credit reporting in Canada, while FrontLobby reports verified rent history to credit bureaus. Zown takes a different approach by connecting rent rewards with a later property purchase and the services surrounding it.
1. Rent is becoming a financial product. Canadian fintechs are attaching payments, rewards and credit reporting to one of the largest monthly household expenses. Toronto-based Chexy shows how quickly the category can scale. In March, the company raised C$14 million after starting with rent payments and said it had reached more than C$1 billion in annual payment volume and C$20 million in rewards value. Zown is pursuing a different end market, but rent serves the same commercial purpose of establishing a recurring financial interaction before other higher-value services are needed.
2. Housing costs are attracting more fintech models. Rent reporting, payment routing, rewards and short-term financing are competing for the same household expense. NCFA has tracked how fintech is entering rent and housing payments through companies including KOHO, Borrowell, Zenbase and Chexy. Zown adds another model by using rent rewards to encourage future homeownership and then connecting the renter to brokerage and mortgage services.
3. AI is getting closer to the financial decision. CMHC found that 16% of mortgage consumers who searched online used AI for mortgage information in 2026. HouseSigma says its Canadian platform has more than two million registered users and over five million monthly web visits, with AI used for valuation and market analysis. Zown's Zoro is competing in the same environment, focused on helping someone make a better property or financing decision. NCFA has identified the same commercial issue in decision intelligence across financial services.
It's a competitive field already. Wahi competes on digital brokerage and buyer cashback, Perch on digital mortgage readiness, FrontLobby on rent reporting, and HouseSigma on property search, valuation and market data. Zown's difference is the attempt to connect those stages much earlier, while the customer is still renting.
The economics improve if Rent Rewards keep customers engaged rather than simply subsidizing renters who eventually buy elsewhere. A traditional brokerage usually starts competing once someone begins seriously looking for a home. Zown can enter much earlier, stay connected through monthly rent, introduce affordability and mortgage tools, and eventually earn brokerage revenue if that renter buys through the platform.
That could lower the cost of finding future buyers and generate more revenue from each customer relationship. It can also become expensive if Zown funds rewards for several years without converting enough renters into completed transactions. The operating number worth watching should therefore be how many Rent Rewards users eventually become profitable Zown homebuyers?
Canadian mortgage companies, brokerages and property apps usually compete once someone is already thinking seriously about buying. If Zown can give renters enough financial value to earn their attention four or five years earlier, how much of the future homebuyer relationship can it own before the mortgage application even begins?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Explore and compare companies in Canada’s open banking market by capability, market layer, documented Canadian traction and selected global benchmarks, from financial data and bank infrastructure to payments, business systems and intelligence.
Loading market map…
Learn how open banking and consumer-driven finance work, use Canadian market evidence alongside leading international examples, test key claims, and apply what you learn to product, operating, investment and policy decisions.
Choose A Topic (match it to your product, investment or policy question)
Choose A View
Gain Practical Insight
Start with the decision in front of you. Work through one topic or use the full guide to connect regulation, infrastructure, products, competition, adoption and risk.
Connect customer permission, standards, shared infrastructure, business models and trust.
See what could slow launch, adoption, scale or commercial value.
Compare who pays, who benefits, where margins sit and what evidence is still missing.
Separate announcements from operating evidence, activity from adoption and access from outcomes.
Search the full 146-module guide or narrow it by the perspective most relevant to you.
Search the full guide or narrow the modules by the decision or market question you are working on.
Explore selected current and emerging Open Banking discussions through verified market evidence, competing commercial cases and NCFA insight. Cast your view and compare with the market as participation builds.
Canada’s first phase has to prove that data access can improve real financial tasks before payment initiation arrives.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
The near term opportunity is strongest where better data cuts underwriting time, verification cost or manual work. If those services do not generate repeat use, payment initiation becomes more important to the commercial case.
Canada must decide how much operating evidence it needs before moving from data access into customer authorized payments.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
A staged rollout tied to transaction risk and proven operating performance would let Canada add useful functionality without treating every payment use case the same.
Compliance costs can protect consumers and still become a barrier if they do not reflect the activity and risk of the participant.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Consent, security, liability and consumer redress need a firm baseline. Other obligations should track the activity, exposure and risk a participant creates. If smaller firms carry costs that do not reduce material risk, the framework can weaken the competition and consumer choice it is meant to support.
Private agreements and industry standards continue to develop while the federal framework remains unsettled.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Commercial data sharing can keep growing without a settled federal rule. The competitive issue is who controls access terms. Continued uncertainty favours firms with the scale to negotiate bilateral arrangements and absorb repeated integration costs.
The UK has proven demand for Open Banking. The commercial test is whether payment services can fund continued investment without restricting access.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Paid services make sense when they deliver functionality, service levels or risk controls beyond the baseline. Charging for ordinary access too early can weaken fintech economics and reduce the demand needed to support a durable market.
Australia shows what happens when a mature data right expands faster than the ability to complete customer actions.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
More data can improve advice, comparison and underwriting. Action becomes more valuable when it removes a meaningful customer step. The case for wider authority should be judged against the friction it removes and the additional fraud, consent and liability risk it creates.
The UK now has to decide how standards should be governed once the market is established and commercial interests are stronger.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Standards need to adapt faster than legislation without giving the largest participants control over market access. Funding, technical administration, consumer representation and statutory enforcement should remain clearly separated.
AI agents can progress from reading financial data to recommending and executing financial actions.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
The key control is authority. Customers need clear limits on what an agent can do, for how much, for whom and for how long. Auditability, revocation and liability become more important as autonomy increases.
Brazil links Open Finance to a high frequency payment system, giving customers an immediate reason to use connected financial services.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Brazil shows the value of pairing data access with an action customers already understand and use frequently. Canada does not need the same payment model, but its early data services still need to solve problems often enough to create repeat behaviour.
Open finance can improve advice and competition, but every additional data category increases consent, privacy and implementation complexity.
Your View
Vote to reveal NCFA’s take.Thanks for voting. Results will appear as participation builds.
Wider access is most useful when the additional data changes a financial decision or removes customer friction. Scope should follow clear use cases, with common identity, consent and liability controls reducing the cost and risk of expansion.
Explore commercial opportunities in Canadian open banking, consumer-driven finance, data access and financial infrastructure, then assess where new products and business models may be viable.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 9, 2026 | Legal Issues, Regulation, Consultation
Image: Pexels/RDNE Stock project
Divorce can change much more than a relationship. Property, savings, wills, beneficiary designations, support obligations, and future inheritances can all become part of the financial cleanup. The rules are particularly important when significant assets are involved because assumptions about who owns what do not always match the law.
The numbers give the issue some scale. According to the 2021 Census, about 695,630 people in Ontario were divorced and not living common-law, while another 333,775 were separated and not living common-law. Changes to succession law that took effect in 2022 also altered how certain separated spouses are treated when someone dies, making current legal advice especially important.
People often assume that anything inherited during marriage automatically remains theirs after the relationship ends. There is some basis for that idea, but the rules contain important exceptions.
Under family property law, property inherited from a third party during marriage can generally be excluded from net family property if it still exists at the valuation date. Property that can be traced back to an inheritance may also qualify for exclusion.
The family home is different. If inherited money is used to acquire or improve a matrimonial home, or the inherited property itself becomes that home, the normal exclusion may not apply.
Documentation therefore matters almost as much as the source of the money.
Divorce generally changes a former spouse's position under a will, but it does not necessarily erase every possible financial obligation between two people.
For anyone trying to understand inheritance rights after divorce in Ontario, Nussbaum Law explains how divorce, separation, support obligations, joint ownership, beneficiary designations, and estate claims can interact. The firm provides family-law and estate-litigation services and notes that unresolved support or other legal obligations may continue to affect an estate even after a marriage has ended.
This is why the answer to “Can my former spouse still receive anything?” may depend on much more than whether a divorce order exists.
Everyday conversation tends to treat separation and divorce as interchangeable. Legally, they are distinct.
Separation generally involves spouses living apart following the breakdown of their relationship. Divorce formally terminates the marriage.
That distinction can become particularly important when one spouse dies before all financial and estate matters have been resolved. Property division, support obligations, wills, and estate entitlements may interact differently depending on the couple's legal status and existing agreements.
Someone who has moved out and started a separate life should not assume every legal connection has disappeared with the moving boxes.
Inherited assets receive certain protections during property division, but a matrimonial home operates under different rules.
Government guidance explains that even when a family home was inherited or received as a gift, it does not receive the same excluded-property treatment that might apply to other inherited assets. Its value can therefore become relevant to the equalization calculation.
That distinction can catch people by surprise.
Suppose someone inherits money and leaves it in a separate investment account. Compare that with using the inheritance to pay down the mortgage on the family home. Those choices can produce very different consequences.
Before transferring substantial inherited funds into jointly used property, getting individual legal advice can be worthwhile.
A major relationship change is a sensible time to review estate documents.
Under succession legislation, when a marriage ends through divorce, gifts to a former spouse in an existing will are generally treated as revoked unless the will indicates a contrary intention. The same principle applies to certain appointments, such as naming that former spouse as executor.
That does not mean an old will should simply be forgotten.
The remaining provisions may no longer distribute the estate the way you want. Executors, alternate beneficiaries, trusts, guardianship arrangements, and other instructions could all deserve reconsideration.
A current will is usually easier for everyone to understand than an old document that has to be interpreted through later legal changes.
Your will is only one part of estate planning.
Life insurance, pensions, registered accounts, jointly owned assets, and other financial arrangements may have their own beneficiary or survivorship provisions. That means changing a will without reviewing everything else can leave inconsistencies behind.
The Government of Canada's information on getting separated or divorced recommends reviewing finances carefully after a relationship breakdown, including joint accounts, credit arrangements, insurance, investments, and retirement planning.
Create a complete inventory rather than trying to remember accounts individually. Administrative details are easy to overlook when a separation already involves housing, finances, family arrangements, and legal paperwork.
If you want to claim that an asset should be excluded from property division, you may need to establish where it came from and what happened to it afterward.
Keep estate documents, bank statements, investment records, transfer confirmations, and other paperwork showing the original inheritance and its subsequent movement.
Tracing becomes more difficult when inherited funds are repeatedly transferred between accounts or mixed with other money.
Government guidance on dividing property after a relationship ends specifically identifies inherited property other than the family home as an example of property that may be excluded. It also explains how assets and debts are considered when calculating family property.
Good records cannot guarantee a particular legal outcome, but missing records rarely make a complicated financial dispute easier.
Inheritance questions should not be handled in isolation.
Look at property division, support arrangements, jointly owned assets, insurance, beneficiary designations, wills, registered accounts, and any obligations established through an agreement or court order.
Timing matters too. Moving inherited funds, changing ownership, or making large financial decisions before understanding their legal consequences can create problems that are difficult to reverse.
The goal is not to assume every former spouse will make a claim or that every inheritance will become disputed. It is simply to know where the potential complications are before making decisions involving significant assets.
Divorce already creates enough paperwork. Your estate plan does not need to become the sequel.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 3, 2026
Some buy now, pay later activity reaches Canadian credit files. Most routine instalment plans currently do not.
That is the short answer, and the qualifications matter more than the answer does. Whether a buy now, pay later arrangement appears on a credit file in Canada depends on the provider, on which credit bureau is involved, on whether a payment was missed, and on the month in which the question is asked. Payments made on time and payments missed follow different routes. Two people financing identical purchases through different providers may find entirely different records.
What follows sets out what is reported, by whom, to which bureau, and with what effect on a score, then explains why the answer is this unsatisfying. The position described reflects Canadian reporting as of September 2026, and it is moving.
The Financial Consumer Agency of Canada describes buy now, pay later plans as arrangements that finance a purchase with credit. Its research characterises the category as covering a wide range of credit arrangements and as generally a type of consumer credit, comparable to instalment lending. That framing is the reason the credit-file question arises at all. The obligation is credit, not merely a payment method.
The agency identifies several distinct payment models sold under the same label: pre-authorized debits, pre-authorized credit card charges, an instalment option applied to an existing credit card, retail credit cards, and financing arranged through a financial institution. The entity behind each model differs. FCAC lists the financial service providers active in this market as including banks, credit unions and caisses populaires, financing companies, and money services businesses such as financial technology firms.
That mix determines oversight. FCAC directs consumers with complaints to different regulators depending on who provided the financing: federally regulated financial institutions must maintain their own complaint-handling processes, while other arrangements fall to provincial and territorial regulators. Oversight therefore follows the provider rather than the product category.
Credit reporting is furnisher-driven. A bureau can hold only what a provider chooses to send it, and furnishing is voluntary. In the United States, four senators on the Senate Banking Committee wrote to the major credit reporting companies in May 2026, reporting that several American providers had told them they were not sharing this data with credit bureaus.
The Canadian position is documented more thinly. The Canadian Lenders Association, an industry body, described the position in late 2025 as one in which inclusion of this data in credit files is voluntary, variably reported, and inconsistently used in underwriting. The same commentary reported that Equifax in Canada had begun incorporating this data, with TransUnion not far behind. Beginning is the accurate word, and it should not be read as complete.
Missed payments follow a different route from payments made on time. An account referred to a collection agency can reach a credit file through that channel even where the on-time payment record never appeared. FCAC states that once a creditor sends a debt to a collection agency, the credit score will go down. An arrangement invisible while it was being paid can become visible once it is not.
Because the position varies by provider and bureau, the only reliable confirmation is an individual file. You can check your credit score and see what each bureau holds in your name.
Three independent variables produce the inconsistency, and naming them is more durable than listing providers whose practices change.
The first is whether the provider furnishes at all. This is voluntary, and it varies both between providers and by product.
The second is what the receiving bureau does with it. In a 2022 post it has since archived, the United States Consumer Financial Protection Bureau noted diverging approaches: one credit reporting company implemented a business industry code while letting furnishers supply data in their preferred format, and others planned to hold it in specialty files kept apart from the core files behind traditional reports. That account is American and several years old. Canadian bureau practice is not documented publicly in comparable detail. That gap is part of the answer.
The third is whether the scoring model uses the data. TransUnion Canada stated in a 2024 paper that it was analysing alternative data, including buy now, pay later, without initially affecting its scores. Data can sit on a file while remaining absent from the decision. Presence on a record and effect on a score are separate things, a distinction that governs which financial activity does and does not build a credit file.
The foundational federal research on buy now, pay later in Canada is a pilot study, and the agency says so itself.
FCAC surveyed 1,034 Canadians aged 18 and over. The sub-sample of actual users was 66 people, of whom 20 took part in follow-up interviews. The agency states that most findings are drawn from that sub-sample, that these early findings should not be generalised to Canadians at large, and that unweighted percentages are used throughout. Those are appropriate disclosures on a pilot. The difficulty lies with how often it is cited as settled evidence.
Two details matter. The survey reference period ran from September 2019 to March 2021; the report was published in November 2021. And 44 percent of the users surveyed found the potential effect on their credit score difficult to understand: the confusion this article addresses was documented at the outset. Interview participants described using these plans to bridge a timing gap, wanting to purchase immediately while knowing funds would arrive later.
FCAC identified risks of over-borrowing and over-indebtedness but stopped short of recommending regulation, committing instead to monitor the market, conduct follow-up research, coordinate with provincial and territorial authorities, and provide consumer education. As of September 2026, the agency's published research index lists no further study.
Where these obligations are not furnished, or are furnished into files that scoring models do not read, they are absent from any assessment built on bureau data. A household carrying several concurrent instalment plans can present on a credit file as a household carrying none.
The omission runs in both directions. A consumer reviewing their own file may conclude they carry less than they do. And every party that assesses affordability from bureau data, from banks and credit unions to licensed Canadian lenders, works from a record that omits a category of live obligation. TransUnion Canada listed this as a market concern in 2024, noting that limited reporting constrains the ability of other lenders to conduct credit checks and assess affordability.
This is neither new nor specific to one product. Rent, utilities and telecommunications payments are largely unreported in Canada as well. Buy now, pay later is a recent addition to a longer list of obligations that credit files do not capture. The observation concerns what the record contains, not what any party ought to do about it.
On 23 June 2025, FICO announced two scoring models, FICO Score 10 BNPL and FICO Score 10 T BNPL, built to incorporate buy now, pay later data. The announcement was framed explicitly around the United States credit ecosystem, and FICO stated the models would initially be offered alongside its existing scores rather than replacing them, leaving adoption to individual lenders. No equivalent Canadian scoring model has been announced.
The Canadian Lenders Association, an industry body representing lenders, has argued that the sector needs a consistent framework so that this data supports credit inclusion rather than working against it. The position is reasonable and worth reporting. It is not a neutral one.
The effect of fuller reporting would run in two directions. For a consumer with a thin file, a furnished record of payments made on time would constitute history where none existed. For a consumer carrying several concurrent plans, the same reporting would make visible an obligation load that had gone unobserved. Which effect applies is a matter of individual circumstance.
The question a reader arrives with is whether buy now, pay later touches their credit file. The accurate answer is that it depends on the provider, on the bureau, on whether a payment was missed, and on the month in which the question is asked.
That is unsatisfying, and it is not a hedge. Furnishing is voluntary and partial. Bureau treatment differs and is not documented publicly in Canada at the level of detail the question deserves. Scoring treatment is a separate matter again. The Canadian federal evidence base remains a pilot study of 66 users describing behaviour from a period that ended in March 2021.
Each of those conditions can change without announcement. This article describes the position as of September 2026. A reader returning to the question in a year should expect a different answer.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 31, 2026
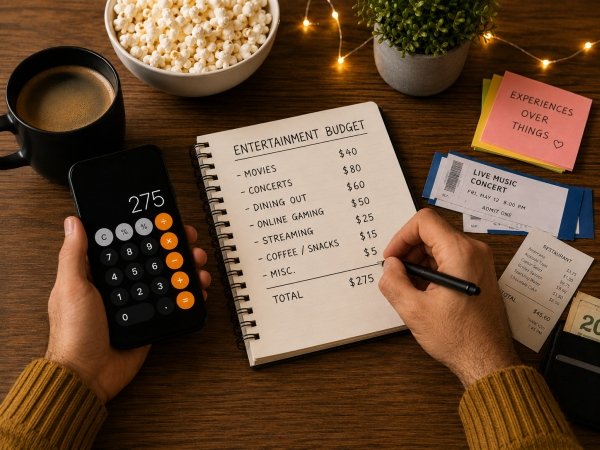
Money's been on my mind recently. Not in that anxiety-spiral way where you check your bank account at 2am, but this quiet realization that maybe I should know where my paycheck actually goes.
Last month I tracked every dollar I spent on fun stuff for 30 days. Movies, streaming subscriptions, nights out, concert tickets, all of it. The final number: $387.42. When I looked at that spreadsheet, I couldn't remember what half those charges were for. What's the point of spending money on entertainment if it vanishes from memory within two weeks?
I started approaching entertainment differently. Not cutting everything fun out, but actually thinking about what I was doing with my money instead of letting it evaporate.
I didn't create some elaborate system. After obsessing over my spending patterns, I noticed something. The weeks where I felt genuinely good about how I'd spent my time and money? Pretty much always came out between $50 and $65. Not $100, not $20, just that range where I'd actually done something worth remembering without that guilty feeling.
Usually broke down like this: one planned thing with friends costing $25 to $30, small daily stuff like grabbing coffee or buying a book adding up to $15 or $20, plus one spontaneous decision for another $10 to $15.
This magic number doesn't work for everyone. Your sweet spot might be $30 or $100 depending on where you live, what you earn, and what brings you joy. But having an actual number instead of vibes-based spending helps you make better choices in the moment.
I started investing 10 minutes researching before spending money on something. When I was considering trying a new platform (like when I checked out Rex Bet after my friend wouldn't shut up about it), I actually looked at what they offered instead of just creating an account and hoping for the best. New restaurant? I'd glance at menu prices first.
Doing that research didn't kill spontaneity like I thought it would. It made spontaneous decisions better because when I did something on impulse, I was way more likely to genuinely enjoy it instead of feeling like I'd wasted money.
Anything over $75 gets a two-day waiting period. That's it.
I wait 48 hours before buying it, and you'd be shocked how many times something I absolutely needed to have right that second completely disappeared from my brain after two days. Still thinking about that $89 blender I almost bought at 11pm on a Tuesday that I've never thought about since.
The stuff I still wanted after waiting? Those purchases turned out to be worth it almost every time. I noticed they were usually experiences instead of things, which bring way more lasting happiness anyway.
I'm not spending dramatically less money now. Some months I actually spend more than my old average. But the difference is I can tell you exactly where that money went and why. I remember the comedy show I saw three weeks ago because I actively chose it instead of defaulting to whatever required the least thought.
My whole relationship with my entertainment budget changed. Stopped being about restricting myself or feeling guilty, started being about actually being present for the experiences I was paying for instead of mindlessly swiping my card and wondering where my paycheck vanished to.
Pretty small shift when you think about it. Made a massive difference though.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016