




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


November 4, 2026 | NCFA Story Intelligence | Sustainable Finance And ESG, Regulation And Policy, Competition And Market Structure
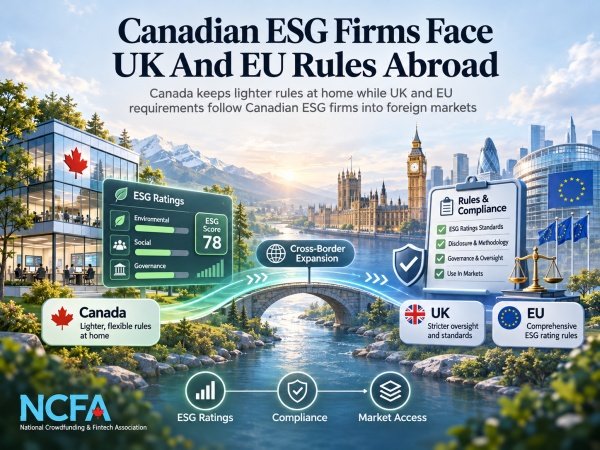
ESG ratings promised investors a shortcut.
Instead of digging through climate data, labour records, governance practices and supply chains themselves, they could buy a score and put it to work.
Then the scores started disagreeing.
The same company could look strong through one provider and much weaker through another. Nobody had to be cheating or doing bad work. One firm might care more about carbon exposure. Another might put more weight on labour practices, board governance or supply chains. Even when they looked at the same issue, they weren't always using the same data.
Investors were left with a problem. They had bought a shortcut and now had to check the shortcut.
In Britain, thousands of financial firms eventually built their own checks around ratings they were already paying for. The FCA estimates that extra work now costs about £495 million every year.
Regulators eventually made a choice that wasn't obvious at the start. They didn't force every provider to use the same formula. They started regulating the firms producing the ratings.
The EU rules have applied since July 2, 2026. On November 3, 2026, the UK Financial Conduct Authority published its final ESG ratings rules. From June 29, 2028, firms caught by the UK regime need FCA authorisation.
Canada hasn't followed them.
That gives a Canadian startup more breathing room at home.
Then it lands a customer in London, Paris or Frankfurt.
The Canadian rules haven't changed. The business suddenly has.
One provider knocks a company down for carbon exposure. The investor sees the score fall and assumes climate risk is driving the result. But that number also reflects choices about which indicators were used, which data was trusted and how the provider turned those inputs into a score.
Another barely moves on carbon but cuts the same company for governance or labour practices. The company itself hasn't changed between the two ratings. What changed is the lens used to judge it. Same company. Same ESG label. Different story.
Providers sign up, publish more detail and tighten their controls. They still get to build their own methods and scores. That keeps room for different models to compete, but it also leaves customers comparing very different ways of measuring the same company.
Customers keep doing their own checks anyway. Banks, asset managers and other users still have to decide whether the provider's data, methodology and controls are strong enough for their own decisions. More disclosure helps, but the doubt doesn't go away.
A rating only saves time if the buyer trusts the data, methodology and controls used to produce it. By this point, many firms aren't simply reading the score. They're reviewing the provider, checking the method and sometimes changing their own systems before the rating can be used.
By 2025, thousands of firms have built their own second opinion inside the company. Some are spending months onboarding providers and assigning staff just to close information gaps or resolve concerns before a rating can be trusted. The shortcut has created another job.
Before, a provider could follow the voluntary code and convince customers that its controls were good enough. The customer could accept that explanation, ask for more or walk away. The regulator wasn't deciding whether the provider could stay in the market.
Under FCA rules, that choice disappears. Firms in scope have to meet requirements around governance, conflicts, systems, data and disclosure, and they need authorisation to keep serving the market. If the firm is caught by the regime, meeting the standard becomes part of staying in business.
A smaller Canadian provider can still reach European customers without waiting for Canada to create its own ratings licence. Recognition can give qualifying foreign firms a way in when equivalence isn't available, so the market isn't closed to an independent Canadian provider.
But it still has to meet European requirements. Depending on the route, that can mean a legal representative, added documentation and direct accountability to ESMA. The company can stay Canadian, but its European business can't simply run on Canadian rules. Getting into the market is possible. Getting in on Canadian terms isn't.
A Canadian startup can build an ESG scoring product, test it and sell it at home without first getting a dedicated ratings licence. That leaves more of its early budget for product, data, hiring and customers instead of a new authorisation process.
Then it signs a foreign customer. New legal work, documentation, controls and regulatory relationships can arrive with the contract even though the product itself is unchanged. The product hasn't changed. The cost of selling it may have.
The Canada EU digital trade deal can make contracts, permitted data transfers and online delivery easier for smaller Canadian companies. That can remove friction from how a digital service is sold and delivered across the Atlantic.
If the product is an ESG rating, ESMA's rules still apply. A smoother digital sale doesn't replace recognition, endorsement or any other requirement that applies to the provider itself. The sale may get easier. The regulatory work doesn't disappear.
Providers still get to disagree and build different models. One can give climate more weight while another puts more emphasis on governance, and the FCA doesn't try to choose the winner.
What changes is how much of the work behind the score has to stand up to scrutiny. Providers have to explain more about the data, methods, conflicts and controls that produced the result. The rating can stay subjective. The process can't stay hidden.
UK applications begin in 2027. Firms expecting at least £500,000 in ESG ratings revenue over the following 12 months apply first. Smaller providers follow. For a Canadian exporter, the size and timing of the sales pipeline can therefore affect when the FCA application work starts.
A firm serving both the UK and EU can reuse some people, controls and documentation. That should keep the second market from starting entirely from zero, but the two regimes remain separate and each still has its own entry requirements. It can reuse the work. It can't reuse the permission.
Canada gets a real benefit from staying lighter.
A young ratings or analytics company can spend more of its first dollars on product, hiring and customers instead of building a licence around a market that may still be small.
That works well while Canada is the market.
Then the company wants to scale.
A UK customer can bring FCA requirements into the sales process. A European customer can bring ESMA. The Canadian company starts hiring compliance staff, changing contracts, documenting methods and adding controls that Canada never asked it to build.
Copying the UK or EU isn't an obvious answer either.
A Canadian licence would cost money. Plenty of firms may never need one. Large global providers can spread that cost across thousands of customers. A startup can't.
But staying different isn't automatically free.
If every Canadian firm with global ambitions has to build around foreign rules anyway, Canada's lighter model starts saving less than it first appears.
Canada hasn't crossed that line by law. Some Canadian firms may cross it much sooner.
At what point does regulatory divergence stop saving Canadian firms money and start making international expansion more complicated?
Ottawa hasn't answered that question. Canadian firms trying to sell abroad may answer it first.
Share this story → Explore related intelligence → Subscribe
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Nov 4, 2026
Image: Unsplash/Luis Fallas
A winning bet is great, but getting your money into the account shouldn't be the hard part. Canadian payment technology is getting faster and smarter, with some interesting developments already underway. The question is whether sportsbooks can put those improvements to work where their customers will actually notice them.
Online sports betting is a pretty slick operation these days. You can watch a hockey game, check the odds on your phone and place a bet before the next face-off. But there's a fair amount of financial technology doing the work behind that simple transaction. Your money has to reach the sportsbook, your account needs to be verified, and everything has to happen quickly enough to keep up with the game.
A sportsbook account is effectively a digital wallet. You deposit money, the balance appears in your account, and you can use it to place bets. The process looks simple because the payment technology handles most of the work without asking you to get involved.
There's plenty of money moving through these systems. Ontario recorded CA$11.4 billion in sports and other betting wagers during the 2024–25 financial year. That includes esports and novelty betting, but it gives you an idea of the workload behind Canada's regulated betting industry.
Welcome bonuses add another job for the software. A sportsbook needs to recognise an eligible deposit, apply the correct promotion and keep track of the conditions attached to the bonus. Sportsbook Review provides information about information about the Stake Bonus Code, including Stake's first-deposit match, promotional code and wagering requirements.
It's a good illustration of how much work happens behind the account balance you see on your screen. The customer makes the deposit, and the software handles the calculation.
Moving money between a bank and a sportsbook takes more than a working internet connection. Payment processors have to authorise transactions and keep accurate records, even when thousands of customers are using the service.
Canadian financial businesses are spending money on the technology that makes this possible. Peoples Group and Fiserv are modernising payment infrastructure, improving the systems that financial services use to process transactions.
There's also a regulatory side to the business. Canada's Retail Payment Activities Act brought new requirements into effect on September 8, 2025.
Payment service providers covered by the legislation must manage operational risks and protect customer funds where applicable. Those obligations concern the businesses handling payments, rather than every sportsbook directly.
A betting operator needs dependable payment connections because customers expect their deposits to arrive and their withdrawals to be processed correctly.
Waiting for a bank transfer to clear is nobody's favourite pastime, particularly when you're trying to fund an account before a match starts.
Canadians are interested in faster alternatives. Payments Canada found that 52% of consumers considered real-time payments appealing, and 34% said they would likely switch to them when available.
Canada's Real-Time Rail is intended to make account-to-account transfers possible around the clock. Its planned introduction in the fourth quarter of 2026 would give participating financial institutions another way to move money electronically.
The benefit for sports betting is easy to understand. Faster payment confirmation could allow deposits to reach betting accounts sooner, assuming the operator supports the relevant payment method.
Withdrawals are slightly different. A sportsbook may need to verify an account or complete other checks before releasing the money. Real-time payment technology can speed up the transfer once those checks are finished, but it cannot do away with the checks themselves.
Nobody wants to miss the opening minutes of a match because their deposit is still making its way through the banking system.
Financial technology is also getting better at checking information. Secure connections between systems allow businesses to verify details without asking customers to enter the same information repeatedly.
Open banking is taking this further. Decision intelligence uses connected financial information to help businesses assess transactions and make automated decisions.
A sportsbook can apply similar technology to account verification. Payment details that don't match the registered customer, for example, can be flagged for closer inspection.
That leaves staff to investigate transactions that genuinely need attention, rather than manually checking every deposit that comes through the system.
Sportsbooks have become very good at making complicated transactions look simple. You open an account, deposit money and get on with watching the game, without having to understand what the payment processor is doing.
That convenience depends on reliable financial systems. Faster transfers can reduce waiting times, and better account verification helps operators handle transactions accurately.
There's still plenty of room for improvement, particularly as Canadian payment technology develops. The next useful innovation might have nothing to do with the odds on your screen. It could simply mean your money gets where it needs to go without keeping you waiting.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 3, 2026
Plumbing problems tend to appear at the worst possible time, whether that is a pipe that starts leaking on a holiday weekend or a basement floor drain that fills with wastewater in the middle of the night. Knowing which problems call for an emergency plumber Toronto homeowners can reach at any hour, and which ones can wait for a regular appointment, helps a household act quickly and limit water damage in the first few minutes.
Some plumbing problems get worse with every minute. A burst pipe or a leak that sprays or pours water across the floor is the clearest example, since water travels under flooring, into walls, and down to lower levels quickly. Sewage rising through a basement floor drain, a toilet, or a tub is equally urgent, because it signals a blocked or backed-up sewer line and brings health risks into the home.
Other urgent cases include a toilet that keeps overflowing after the water supply is turned off, a water heater leaking from the tank itself, a sump pump that has stopped working while water rises in the pit, and a sudden loss of water to the whole house. In each of these cases, the help of an emergency plumber Toronto residents trust is worth arranging right away rather than the next business day.
Not every plumbing issue is a plumbing emergency. A single slow drain, a dripping faucet, or a toilet that runs after flushing is inconvenient, but these problems seldom cause damage overnight. If one fixture is clogged while the rest of the house drains normally, it is usually safe to stop using that fixture and book a regular visit.
The simplest way to decide is to ask two questions: is water escaping where it should not be, and does wastewater have nowhere to go? If either answer is yes, the situation should be treated as urgent, while a problem that is contained and stable can generally wait for a scheduled appointment.
The most useful step in any plumbing emergency is stopping the flow of water. In most homes, the main shut-off valve sits in the basement or utility room, close to where the water line enters the house and often next to the water meter. Turning the handle clockwise closes it and stops water from reaching every fixture.
Many fixtures also have their own valves. A shut-off valve under a sink or behind a toilet can isolate a single leak without cutting water to the whole house, and the cold-water valve above a water heater stops the tank from refilling. Locating these valves before anything goes wrong, and checking that they turn freely, saves valuable time later. A simple tag on the main valve helps every member of the household find it quickly.
A sewer backup calls for a different response from a clean-water leak. The first priority is to stop all water use in the house, since every flushed toilet, running tap, or load of laundry adds to the volume that has nowhere to go. Everyone in the home should hold off on using water until the plumber has cleared the line.
Sewage can carry harmful bacteria, so it is best not to touch it. Children and pets should be kept away from the affected area. Belongings can be moved to higher ground if it is safe to do so. Pouring chemical drain cleaners into a backed-up line is best avoided, as they rarely clear a main-line blockage and can make the work more hazardous for the technician.
Standing water near outlets, extension cords, or appliances is a serious hazard. If the electrical panel can be reached without walking through water, switching off power to the affected area reduces the risk. If it cannot be reached safely, it is better to stay out of the flooded space and wait for help.
Once the source of water is under control, removing what can be saved, opening windows for airflow, and taking photographs of the damage are sensible next steps. Wet drywall, carpet, and insulation can develop mould within a few days, so drying the area promptly matters as much as the repair itself.
Typing “emergency plumber Toronto” into a phone late at night is usually the first step. The call that follows goes more smoothly when the caller explains what happened, where the water is coming from, whether it is clean water or sewage, and whether the main valve has been closed. Mentioning the age of the house, the location of the problem, and any access issues, such as a locked side gate or a finished basement ceiling, helps the plumber arrive prepared.
Keeping the phone close after the call is also wise, so the plumber can share an arrival update or ask a quick question about access. If the situation changes while the household waits, for example water spreading into another room or a second fixture backing up, a follow-up call keeps the plumber informed.
The first task for the emergency plumber Toronto homeowners call in is to confirm that the source of water is stopped and the area is safe to work in. From there, the plumber assesses the cause, which may be a failed fitting, a split pipe, a blocked sewer line, or a worn-out appliance.
Some problems can be repaired on the spot, while others need a temporary fix to make the home usable until parts or additional work can be arranged. When a sewer line keeps backing up, a camera inspection may be recommended to find the cause. A clear explanation of what failed and what comes next allows the household to plan with confidence.
Many emergencies are preceded by warning signs that are easy to overlook. Drains that slow down repeatedly, gurgling sounds from fixtures, damp patches on ceilings, and a water bill that rises without explanation are all worth investigating before they turn into a crisis.
A simple meter test can reveal hidden water leaks. Turning off all the water in the home, recording the reading on the water meter, and checking it again after at least twenty minutes is all it takes. If the reading has changed, water is escaping somewhere. Testing the sump pump before spring, keeping grease out of kitchen drains, and protecting exposed pipes in unheated areas all reduce the chance of needing an emergency plumber Toronto families depend on at an inconvenient hour.
Drain Express provides emergency plumbing services across the Greater Toronto Area twenty-four hours a day, seven days a week, including holidays. Its highly qualified plumbers serve both residential and commercial clients, the work comes with a warranty, and the team has completed more than 5,000 jobs.
A little preparation makes every plumbing emergency easier to manage. Knowing where the shut-off valves are, recognizing which problems cannot wait, and having the number of an emergency plumber Toronto households can count on all help turn a stressful night into a problem that is contained, repaired, and behind them.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 3, 2026 | NCFA Regulatory Insight | Digital Trade, Fintech Regulation, Cross Border Services, Canada EU

Canada EU Digital Trade and Fintech Access
On October 30, 2026, Canada and the European Union concluded negotiations on the Canada EU Digital Trade Agreement, Canada's first concluded Digital Trade Agreement. The deal sets rules for trusted cross border data flows, electronic contracts, electronic signatures, electronic invoices and online consumer protection. It complements CETA rather than replacing it.
The agreement isn't signed or legally operative yet. Canada and the EU still have to complete their respective procedures before formal signature and conclusion. On the EU side, that includes legal review, translation into all EU languages and submission to the Council and European Parliament.
EU figures show bilateral trade in goods and services reached more than €130 billion in 2025, up from €72.1 billion in 2016. Digitally delivered services reached €19.8 billion in 2025, including €11.2 billion in EU exports to Canada and €8.6 billion in EU imports from Canada.
Canada EU digitally delivered services trade in 2025
Source: European Commission. Total digitally delivered services trade between Canada and the EU reached €19.8 billion in 2025.
The DTA seeks to prevent unjustified restrictions on cross border data flows and supports electronic contracts, signatures and invoices. Companies selling digital services between Canada and the EU can move more of the sales and delivery process online while still following the laws that apply to their service.
A software company serving European customers may need to move permitted business data, execute contracts, issue invoices and manage customer communications across two regulatory systems. Clearer digital trade rules can reduce duplicated processes and administrative work, which matters most to smaller firms that don't have large legal, compliance and operations teams. In summit remarks on October 30, Prime Minister Mark Carney said “A tech startup in Vancouver will have a smoother path to customers in Berlin.”
The final negotiated legal text hasn't yet been published, so businesses cannot assess every obligation, exception or enforcement mechanism. The October 30 announcements confirm rules on data flows, electronic contracts, signatures, invoices and consumer protection. Other provisions will need to be checked against the final text once released.
The agreement also covers misleading, fraudulent and deceptive online practices and sets rules around unsolicited commercial messages. Canada keeps the ability to regulate privacy, public sector data, government procurement, culture, cybersecurity, financial regulation and national security. Digital trade becomes easier without removing domestic control over regulated or sensitive areas.
Europe can still be an expensive market to enter. OECD research on the EU regulatory burden reports compliance costs equal to about 2.5% of turnover for SMEs. Turnover simply means annual sales or revenue. For an SME with €1 million in annual sales, 2.5% is roughly €25,000 spent dealing with regulatory requirements. The figure reflects costs reported for SMEs operating in Europe and does not mean every Canadian company entering the EU will spend exactly 2.5% of revenue on compliance.
Canadian fintechs can benefit from lower operating friction without gaining unrestricted access to the EU financial market. Financial software, compliance technology, digital identity, infrastructure, business finance platforms and other services that depend on data movement, electronic contracts or digital invoicing may benefit directly. A Canadian company selling technology to a European bank is in a different position from one providing regulated banking, payments or investment services directly to European customers.
A technology supplier may be able to contract with clients, deliver services and manage permitted data more efficiently without needing a financial licence of its own. A company providing a regulated financial service still has to meet the authorization and compliance requirements of the market where that service is offered. Canadian fintechs assessing a similar cross border question between Canada, the US and Mexico can refer to Does CUSMA Support Fintech Services Across Borders?.
Canada and the EU also agreed to deepen work on digital infrastructure, AI, quantum technologies, semiconductors, advanced computing, data flows and interoperability. Separate summit commitments include work toward mutual recognition in digital identity and credentials, AI conformity assessments and cybersecurity.
Canada and the EU also plan closer financial cooperation, increased cross border capital flows and work toward connecting instant payment systems. In the same October 30 summit remarks, Carney said the two sides will “explore opening our markets to each other’s banks, insurers, and fintechs.” The statement points to future negotiations rather than current market access under the DTA. Canada Welcomes EU Associate Member Proposal provides additional Canada EU context around the broader relationship.
The DTA can reduce duplicated process and operating costs for Canadian companies serving European customers, but it doesn't remove the regulatory barriers around financial services. Deeper fintech market access still depends on separate work around licences, payments, regulatory recognition and interoperability.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 3, 2026

Technology makes many parts of life easier, and home financing is no different. Whether you are buying your first home or refinancing your current mortgage, you can use digital tools to help. You no longer have to spend hours dealing with paperwork or making phone calls. Instead, technology helps you find information, compare options, and make smart decisions about your home financing.
You can now complete your mortgage application from your couch, compare multiple lenders with a few clicks, and track your application in real time. This change saves you time and creates a smoother experience, keeping you informed every step of the way. Let's look at how you can use technology to navigate home financing.
Mortgage calculators are helpful tools that give you quick estimates of your loan options. By entering details like home price, down payment, and interest rate, you can learn important facts about your monthly payments and total loan costs. This tool helps you see how different choices affect your budget, so you can make changes before you decide.
Many platforms also offer advanced calculators that include taxes, insurance, and private mortgage insurance (PMI). This detailed approach helps you see your financial commitments more clearly, so you can plan better. You can access these calculators anytime to update your numbers or rethink your plans.
Technology makes it easier to track mortgage rates Canada. Online platforms give you real-time information on current rates, trends, and forecasts. This helps you find the best time to lock in a rate. With this clear information, you don't have to guess if you're getting a good deal. Everything is just a few clicks away.
You can also easily compare what different lenders offer. Many websites show how rates have changed over time. This information helps you make smart choices that fit your financial goals.
Mobile apps put home financing in your hands. Several apps target borrowers, letting you track interest rates, find loan details, and communicate with lenders. Many of these apps are easy to use and guide you through each step of the financing process, making it clearer what you need to do.
For example, some apps let you upload documents directly from your smartphone. You can easily send your financial statements or proof of income without visiting a lender or broker. This feature saves time and simplifies paperwork, improving the overall process.
Using a mortgage broker can improve your home loan experience. Brokers work between you and lenders to find the best rates and terms for you. Today, many brokers use online tools to assess your finances and offer customized options quickly.
Technology helps brokers speed up paperwork and even run simulations to show how different choices affect your loan. They gather lots of information upfront, so you don't have to meet with many lenders. Your broker does the work and provides the best options based on your needs.
Technology also makes it easier to communicate with your broker. You can reach them by email, chat, or video call, making it simple to ask questions. This keeps you informed and comfortable throughout the loan process.
One major advancement in home financing is virtual consultations. Many lenders and mortgage brokers now offer video calls so you can discuss your options from home. This saves you time and the hassle of in-person meetings while still letting you ask questions and get personalized advice.
During these calls, you can review documents, look at different loan products, and address any concerns. Virtual consultations make it easier to connect with industry professionals, ensuring you feel supported and informed throughout the financing process.
You no longer need to search for paper documents or sort through files. Digital document management systems let you keep all your important papers in one secure place. Whether it's bank statements, tax returns, or job verification, scanning and organizing documents online makes your life much easier.
Many lenders let you submit documents online, saving time and reducing stress during the loan application process. You can access your documents from anywhere, so you can keep moving forward with your financing even when you're busy.
Technology is changing how we secure a mortgage. From calculators and apps to knowledgeable brokers and easy document management, technology offers helpful tools that make getting a loan simpler. These resources can make your home financing experience clearer and more efficient.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Nov 3, 2026

Water treatment facilities play a vital role in providing safe and clean water for public use. Leaks can cause serious problems, including costly damage and water contamination. Understanding what causes these leaks and how to prevent them is essential. By focusing on key components and maintenance, facilities can operate efficiently and protect water quality.
Here’s how to effectively prevent leakage in water treatment facilities.
Routine inspections are one of the best ways to prevent leaks. By regularly checking the facility, workers can find weak points that might lead to leaks. Inspecting pipes, joints, and connections helps address wear and tear before larger problems arise.
A good inspection plan should include both visual checks and technology. Pressure sensors or ultrasonic leak-detection systems can alert staff to issues that may indicate a leak. Early detection saves time and money by reducing further damage.
High-quality materials are key to building effective water treatment facilities. Strong, durable materials resist wear and withstand the corrosive nature of water treatment. This is especially important for pipes, valves, and seals, which are prone to breaking down.
For example, the butterfly valve is a great choice for water treatment systems. They perform reliably because they can handle high pressure and flow variations without failing. Their design allows minimal flow resistance, improving efficiency and helping prevent leaks.
Proper installation of equipment is essential. Even the best materials can fail if not installed correctly. Aligning valves, pipes, and fittings properly and fastening them securely helps create a tight seal, reducing the risk of leaks.
Hiring skilled technicians for installation is crucial. They have the experience to spot potential problems during setup, preventing headaches later. It’s worth investing time in training and hiring qualified staff who understand the specifics of water treatment infrastructure.
Having a solid maintenance routine can help prevent leaks. Regular maintenance allows for thorough cleaning, testing equipment, and replacing worn parts. This includes changing old valves and checking all attachments for proper function.
Beyond basic visual inspections, staff should flush the system regularly to remove sediment buildup, which can damage pipes. A skilled maintenance team can quickly fix minor problems, preventing them from becoming larger issues.
Training staff on correct operational practices can improve leak prevention. When employees understand how the systems work and what signs to watch for, they can respond quickly to potential problems.
Training should include everything from handling equipment to monitoring techniques. Employees should also learn to spot early warning signs of leaks, like unusual sounds or pressure changes, so they can report issues promptly.
PVC ball valves effectively prevent leaks in water treatment facilities. These valves are durable and corrosion-resistant, making them suitable for many applications. Their simple design ensures a secure shutoff, helping control flow and prevent leaks.
PVC ball valves are easy to operate, which simplifies maintenance. With their reliable performance, these valves help keep the entire system intact. Using PVC ball valves throughout the facility reduces the risk of leaks from valve failures.
Even with good maintenance, leaks can still happen. Clear emergency response protocols for leaks are essential. Every staff member should know what to do when a leak is detected. This knowledge can help minimize the impact of a leak.
Regular training and drills can ensure everyone understands their roles and the right steps to take. Keeping emergency supplies, such as leak containment materials and repair kits, on hand can also speed response times and reduce damage.
Investing in advanced monitoring technology can help prevent leaks. Real-time monitoring systems can alert operators to unusual conditions that may indicate a leak, allowing for quick responses. These systems often use data analysis to predict potential issues before they happen, offering proactive solutions.
By combining technology with smart practices, water treatment facilities can maintain efficiency while ensuring the safety of the water supply. Understanding what causes leaks is the first step to creating a reliable water treatment facility. By following the best practices outlined here, including proper materials and training, facilities can prevent leaks. The key is to use vigilance, quality materials, and proactive measures to keep an effective water treatment system running smoothly.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
November 3, 2026 | NCFA Regulatory Insight | Open Banking, Consumer Driven Banking, Fintech Regulation, Canada

How High Will Canada Set the Bar for Open Banking Participation?
On November 2, 2026, the Bank of Canada launched a consultation on draft accreditation guidelines for Canada’s Consumer Driven Banking Framework. The framework is supposed to do more than make financial data sharing safer. The federal government has made competition, innovation and economic growth one of its three policy objectives, alongside consumer protection and financial system safety. That makes the accreditation bar more than a compliance question. How demanding the rules become will help determine which banks, fintechs and other providers participate, and how much real competition open banking ultimately produces.
That competitive promise depends on who can actually enter the system. Canada already has about nine million people sharing financial data through screen scraping, according to the federal framework, so there is an existing market for services that could move into regulated open banking. If accreditation is too expensive or difficult for credible fintechs to obtain, consumers may get safer data sharing without enough new providers to materially improve choice, pricing or service.
The Competition Bureau has warned about this risk for years. The Bureau's October 2026 submission on Canada’s draft Consumer Driven Banking Regulations says smaller fintechs, challenger banks, credit unions and emerging firms can face proportionately higher implementation and compliance costs, and that these costs can discourage entry or expansion. The Bureau supports strong safeguards but recommends that requirements reflect factors such as risk, size, activity and access to consumer data.
NCFA's Open Banking & Consumer-Driven Finance Interactive Intelligence has tracked the same tension across competition, accreditation, switching, innovation and global market design. The question now moving from policy into supervision is whether Canada can protect financial data without setting an entry bar that leaves too few challengers in the market.
On November 2, 2026, the Bank of Canada opened consultation on its first draft supervisory guidelines for accreditation.
Comments are due December 8, 2026, and the Bank specifically asks whether any part of the drafts needs clarification, would be difficult to implement, needs more examples or could “discourage voluntary participation.”
The consultation does not reopen the full Consumer Driven Banking Framework. It deals with how the Bank proposes to assess accreditation applications under the Consumer Driven Banking Act and proposed regulations. The two draft guidelines cover participating entities and accredited Third Party Service Providers, with later Bank consultations expected on other supervisory topics.
Canada proposes three accreditation routes for participating entities. The route depends largely on whether the applicant already operates inside another regulatory framework, while accredited Third Party Service Providers sit beside these three routes under a separate guideline.
1. Standard accreditation for independent applicants. This route applies generally to eligible corporations, trusts, partnerships, funds and other organizations that are not registered payment service providers or federally or provincially regulated financial institutions. The participating entity draft guideline requires the broadest evidence package under this route, including governance, security, technical compliance, consumer dashboards, complaints, insurance or guarantees, operations and national security information.
2. Streamlined accreditation for registered PSPs. Payment service providers already registered under the Retail Payment Activities Act can use a separate streamlined route. They still need to provide security, technical, insurance, governance, operating and national security evidence, but the Bank can rely on regulatory information and oversight that already exist rather than requiring every control to be established again from the beginning.
3. Streamlined accreditation for regulated financial institutions. Banks, authorized foreign banks, trust and loan companies, credit unions, caisses populaires, insurers and certain provincial Crown corporations can use the narrowest participating entity route. Their existing prudential regulation carries more of the supervisory burden, while the draft focuses particularly on technical compliance and a declaration from the responsible senior officer that required security safeguards are in place.
Accredited Third Party Service Providers (TPSPs) use a separate pathway. A TPSP is a company that performs specified technology or operational functions for an accredited participant. The TPSP draft guideline applies when a provider performs activities such as obtaining or managing consent, handling authentication, or providing or receiving consumer data. A software company does not need TPSP accreditation simply because it sells technology to a bank or fintech.
The structure already contains some proportionality. Firms with existing supervision get more streamlined treatment, while independent applicants carry more of the accreditation burden themselves. The unresolved competition question is whether prior regulatory status should be the main route to lower burden or whether lower risk independent fintechs should also have a staged way into the market.
The standard route requires more than corporate information and a security policy. Applicants need an operating evidence file covering ownership, governance, responsible people, regulatory status, security safeguards, technical standards, consumer dashboards, complaints, insurance, expected activity and national security information. The Bank can also request more information while reviewing an application.
Security will require independent confirmation, but firms may be able to reuse credible work they already maintain. The draft says ISO 27001 certifications, SOC reports and NIST based assessments may support an application when an independent assessor maps that work to the Bank's safeguards and explains its scope and limitations. The Bank expects the confirmation to rely on an assessment completed within the previous 12 months.
Insurance also follows a risk based approach. Standard applicants and registered PSPs are expected to hold professional indemnity and cyber insurance, or comparable guarantees, but the Bank does not prescribe one coverage amount for everyone. Applicants need a documented methodology that considers factors such as data sensitivity, data volume, operating scale, complexity and potential losses from privacy, cyber or operational incidents.
Some important costs remain difficult to calculate. The draft guidelines say more information on accreditation fees and the web application process is forthcoming, and the participating entity guideline notes that the Technical Standards Body had not been designated when the draft was prepared. Firms can prepare much of their governance, security and insurance evidence now, but they still cannot fully map the cost and timing of accreditation.
The UK and Australia show two different ways to make regulatory burden more proportional without removing consumer protection. Both markets allow firms to participate at different levels instead of requiring every company using open banking infrastructure to clear the highest regulatory bar itself.
The UK's Financial Conduct Authority allows a firm providing only account information services to use the registered account information service provider route. A business that combines account information with other regulated payment services needs authorization instead. Firms can also operate as registered agents on behalf of regulated principals. Those agents are part of the regulated ecosystem but do not hold the same independent authorization as their principal. They provide regulated services through that principal, which remains responsible for the activities covered by the arrangement.
Open Banking Limited reported 145 third party providers with live open banking propositions and another 406 registered agents in its 2025 impact report, with potentially thousands of additional firms using open banking data and payments through regulated providers. Open Banking Limited also reported more than 19 million active user connections and over 40 million open banking payments per month in 2026. That does not prove every UK regulatory choice should be copied, but it shows how participation can extend well beyond firms holding their own direct regulatory permission.
Australia goes further by creating several distinct participation routes through its Consumer Data Right accreditation framework. A firm can become fully accredited, obtain sponsored accreditation under a fully accredited sponsor, or participate without its own accreditation as a CDR representative under a written agreement with a fully accredited principal. Each step gives up some independence in exchange for a lower direct entry burden.
In 2025 to 26, Australia's competition regulator reported 30 active accredited data recipients and 178 active CDR representative arrangements. Representative arrangements are not the same as 178 unique companies, but the gap shows how much participation can occur outside full accreditation.
| Issue | Canada draft | United Kingdom | Australia | Lessons for Canada |
|---|---|---|---|---|
| Full direct participation | Independent participating entities can seek standard accreditation and participate directly | Authorized providers can deliver the regulated open banking services covered by their permissions | Unrestricted accreditation allows full participation, including collecting CDR data directly from data holders | Canada already has a full direct route. The larger policy question is whether every credible new entrant should need to start there. |
| Lighter direct route | Registered PSPs and regulated financial institutions receive streamlined treatment because another regulator already supervises them | A firm limited to account information services can use registration rather than broader payment services authorization | Sponsored accreditation reduces the evidence burden but requires an unrestricted accredited sponsor | Canada has no comparable lighter route for an independent fintech based only on lower risk or a narrower activity. Streamlining is mainly reserved for firms already regulated elsewhere. |
| Participation without full direct approval | TPSPs can perform specified functions for participating entities, but the draft does not create a broad representative route for an independent consumer facing fintech | Registered agents can provide regulated services through an authorized principal without holding equivalent independent authorization themselves | A CDR representative can offer its own goods or services to consumers without holding accreditation under a written arrangement with an unrestricted accredited principal | Canada has no broad agent or representative route that lets an independent consumer facing fintech enter under another accredited firm's responsibility. |
| What the lighter route gives up | Streamlining mainly benefits firms that have already entered another regulatory regime | A narrower permission limits the regulated services the firm can provide independently, while an agent depends on its regulated principal | A sponsored firm cannot collect CDR data directly from a data holder, while a representative depends on its accredited principal | Canada currently gives smaller entrants less ability to trade independence for a lower entry burden. The UK and Australia make that tradeoff explicit. |
| Security evidence | Standard applicants need independent confirmation, although existing ISO, SOC and NIST work may support the evidence | Security and operational controls remain required under the account information registration route | Sponsored applicants can self assess and attest to relevant information security compliance instead of providing the third party assurance report required for unrestricted accreditation | Canada can consider whether every lower risk direct participant needs the same independent assurance burden at entry. A lighter route could still preserve security requirements. |
| Insurance and financial protection | Relevant participating entities need professional indemnity and cyber insurance or comparable guarantees, with coverage tied to risk | Registered account information providers still need professional indemnity insurance or a comparable guarantee | Accredited recipients must demonstrate adequate insurance, while responsibility under representative arrangements sits with the accredited principal | Lower entry burden does not require weaker financial protection. Canada could vary the route while keeping insurance and accountability requirements in place. |
| Evidence of participation | The accreditation system has not launched, so Canada does not yet have participation results to compare | 145 live third party providers plus 406 registered agents were reported in the 2025 Open Banking Limited impact report, with potentially thousands of other firms using open banking data and payments through regulated providers | 30 active accredited data recipients and 178 active representative arrangements were reported for 2025 to 26 | The UK and Australia show that participation can extend far beyond firms holding the highest level of direct approval. Canada has not yet created an equivalent ladder for independent entrants. |
| Independent fintech with no existing regulatory status | Generally faces the standard participating entity route if it wants to participate directly | May qualify for registration if it limits its regulated activity to account information services, or may operate through a regulated principal depending on its role | Can seek sponsored accreditation or potentially participate without accreditation as a CDR representative | This is Canada's clearest gap. A credible lower risk fintech with no existing regulatory history has no sponsored, representative or narrow activity based route comparable to those available in the UK or Australia. |
| Where responsibility sits under lighter entry | Responsibility follows the statutory role of participating entities and TPSPs | The regulated principal remains accountable for the regulated services provided through its registered agent | The unrestricted accredited principal is responsible for its CDR representative, while a sponsor supports a firm using sponsored accreditation | Canada could let a stronger accredited participant carry more responsibility for a smaller entrant. Australia shows one way to lower entry burden without leaving responsibility unclear. |
| Bottom line | Canada is relatively lighter for firms already regulated, but more demanding for an independent fintech that wants to participate directly without that regulatory history. | The UK allows participation at several levels. Directly regulated providers sit alongside hundreds of registered agents operating through regulated principals, plus a wider group of firms using open banking through regulated providers. | Australia has the clearest participation ladder. Full accreditation, sponsored accreditation and representative arrangements let firms participate at different levels of independence and responsibility. | Canada's draft leaves independent new entrants with fewer ways in. The main policy choice is whether to add a limited, sponsored or representative route without weakening security or accountability. |
The comparison does not show that one country simply has weak rules and another has strong ones. The UK and Australia still require security, accountability and financial protection. The larger difference is how many ways a company can enter the ecosystem and how much independence it receives at each level.
In the UK, direct regulation is only one part of the market. Hundreds of registered agents operate through regulated principals, while a much larger group of firms can build open banking data or payment functionality into their products through regulated providers. Australia makes that ladder even more explicit. A firm can carry full accreditation, accept less independence under sponsored accreditation, or offer services as a representative while the accredited principal carries the regulatory responsibility.
Australia reported almost six active representative arrangements for every active accredited data recipient in 2025 to 26. That ratio should not be read as a direct count of companies or as proof that Australia's model is superior, but it does show that participation can become much broader when full accreditation is not the only practical entry point.
Canada already does something similar for registered PSPs and financial institutions by recognizing supervision they have completed elsewhere. The main gap is the independent fintech that creates limited risk but does not yet have a regulatory history that qualifies it for a streamlined route.
Also Canada already has a recent example of why voluntary participation cannot be taken for granted. BetaKit reported in October 2026 that none of Canada’s Big Six banks was then scheduled to participate in the first phase of the Real Time Rail, citing four fintech sector sources familiar with the rollout. The Real Time Rail and consumer driven banking are different systems, but the participation lesson is relevant. New financial infrastructure does not create competition by itself if major institutions or smaller providers decide the cost, timing or operating burden is not worth joining.
The Competition Bureau's October 23 submission puts that issue directly on the table. It supports strong accreditation, reporting, audit and security requirements but warns that fixed compliance costs can weigh more heavily on smaller firms and discourage entry or expansion.
The Bureau recommends considering requirements according to risk, size, activity and access to consumer data. It also suggests a provisional or tier based accreditation model that could let firms enter earlier under appropriate safeguards and move toward full accreditation as their operations and risk grow. Canada's current Bank draft does not create that model.
The Financial Consumer Agency of Canada found that switching barriers can reduce competitive pressure and weaken incentives for providers to compete on price and service. Consumer driven banking can improve comparison and portability, but those advantages are worth less if consumers don't have enough credible alternative providers to choose from.
NCFA's Canada Open Banking Rules and Regulations tracks the broader accreditation, security, liability and supervisory framework. The Bank's current consultation is where those rules begin translating into the practical cost of entering the market.
Canada does not need weaker protection to increase participation. It needs to decide whether security and accountability can remain firm while the pathway to meeting those outcomes varies with the activity, risk and maturity of the applicant. The UK and Australia show that proportionality can be built into market access rather than added after firms have already absorbed the full cost of entry.
The Bank does not promise a standard approval time. Once an application is complete, the Bank sends a copy to the Minister of Finance and begins its own review. The Minister has 60 days to decide whether a national security review is needed and can extend that decision period in additional 60 day periods.
If a national security review is opened, the review period is 180 days and can also be extended in additional 180 day periods. Not every applicant will undergo a full review, but the Bank cannot grant accreditation while the Minister's decision or review remains outstanding. Firms tying financing, hiring or product launches to accreditation need to plan for timing they cannot fully control.
A refused applicant can generally request review within 30 days. The Bank's delegated decision maker can accredit the applicant or confirm the refusal within 120 days after the applicant has had an opportunity to make representations, and a further appeal can go to Federal Court. Once applications begin moving through the system, publishing normal processing times would help founders and investors distinguish routine accreditation from exceptional delay.
The Bank wants written feedback by December 8, 2026. Respondents should identify themselves, use the subject line specified on the consultation page, identify the relevant part of the draft and explain the implementation issue as specifically as possible. Commercially sensitive information should only be submitted when it is clearly identified.
Fintechs should put numbers around the burden wherever they can. If security mapping needs 120 staff hours, another assurance exercise costs $40,000, insurance materially increases annual operating cost, or Canadian presence changes the economics of entry, those figures tell the Bank more than simply calling a requirement burdensome.
Registered PSPs and financial institutions should identify evidence another regulator already holds and where the Bank can safely avoid duplication.
Independent fintechs should explain whether a limited, provisional or sponsored route would change their ability or willingness to enter Canada, while TPSPs should identify where responsibility for consent, authentication and data handling remains unclear between provider and participating entity.
NCFA believes Canada should add a proportionate entry route for credible lower risk fintechs that are not already supervised under another regulatory regime. The UK and Australia show that this can be done without removing accountability. Canada should consider narrower permissions for narrower activities, sponsored participation through an accredited firm, or a representative model where a stronger regulated participant carries more responsibility while a younger company proves its product, controls and operating record before seeking full independent accreditation.
A framework that protects data but attracts too few credible challengers will struggle to deliver the competition, consumer choice, innovation and pricing pressure that consumer driven banking was built to support. The December 8 consultation deadline gives industry a chance to influence that balance before the entry rules become embedded in Canada's open banking market. Responses can be emailed to SupervisionInfo@bank-banque-canada.ca
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016