




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 2, 2026
image: Magnific/DC Studio
When a province opens a private online gambling market, the headlines tend to chase the money: tax points, operator counts, and the size of the prize. The quieter story, and the one that matters more to the people who actually log in, is how the rules try to keep play from sliding into harm. Alberta's shift to a regulated online casino market is, underneath the commercial framing, a player-protection project. The design choices that decide whether a customer can set a hard deposit cap, lock themselves out across every site at once, or get flagged before a bad week becomes a worse one are buried in standards documents, not press releases.
That angle fits readers who follow how Canadian regulation, payments, and consumer safeguards lock together rather than chasing the latest welcome offer. The interesting question is not which brand has the loudest promotion. It is whether the protections written into the law and the regulator's standards are strong enough to hold once real money starts moving through licensed platforms.
Plenty of attention has already gone to who is lining up to operate. Data and comparison publishers such as Lineups keep running directories of the online casino options in Alberta, which gives outside observers a useful map of which brands are entering under the new framework. This piece takes the other side of that map and audits the safeguards instead: what each protection is meant to do, how it functions in practice, and who carries the duty to enforce it.
Alberta is not inventing online gambling. Residents have placed bets through offshore and grey-market sites for years, usually with no Canadian oversight, no local self-exclusion option, and no recourse when something went wrong. The case for a regulated market rests less on novelty and more on control. Once play happens on licensed platforms, the province can attach conditions to it: verified identity, mandatory limit tools, a shared exclusion list, and a regulator with the power to pull a license.
So the honest way to read this market is as a safeguards audit. A new framework is only as good as the protections it forces operators to build and the body willing to test them. The rest of this article walks each guardrail in turn, asks how it is supposed to work, and names the party on the hook when it fails. That structure matters because responsible-gaming language is easy to print on a homepage and hard to operate at scale.
Alberta split the job in two, which is a useful tell about how the province thinks risk should be managed. The Alberta Gaming, Liquor and Cannabis commission, known as AGLC, is the regulator. It registers operators and suppliers, writes and publishes the standards, audits compliance, and runs the centralized self-exclusion system. A separate body, the Alberta iGaming Corporation, holds the commercial agreements that operators need before they can legally take a bet in the province.
The point of separating the regulator from the conduct-and-manage entity is to keep the referee away from the revenue. The body chasing market growth is not the same body deciding whether an operator broke the rules. For a consumer-protection reader, that division is one of the more reassuring features of the design, because it reduces the pressure to look away from a profitable but non-compliant brand. It is also the structure the regulator can point to when a customer complaint needs an independent path that does not run through the operator's own support desk.
This dual model echoes the approach Ontario used when it launched its commercial market in 2022, which has since registered dozens of operators. Alberta watched that rollout closely and borrowed the parts that worked while trying to tighten the parts that drew criticism, including how exclusions and advertising are handled.
The safeguard with the most practical weight is the centralized self-exclusion program, and it is meant to be live from the first day of the regulated market. The mechanics are simple to describe and surprisingly hard to deliver. A person who wants to stop signs up once, and the exclusion then applies across every licensed online platform in the province at the same time. Timeframes run from six months to permanent, with options in between.
Compare that to the offshore status quo, where excluding yourself from one site does nothing on any other. Under the old arrangement, a person in a bad spiral could close one account and open three more by lunchtime. A shared list closes that gap, at least within the licensed perimeter. The regulator operates the program, and operators are required to integrate with it as a condition of registration, which is what turns a good intention into an enforceable obligation rather than a marketing badge.
The honest caveat is that a self-exclusion list only covers the sites inside it. A determined person can still reach unlicensed offshore platforms that ignore Alberta entirely. That limit is not a flaw in the design so much as a boundary on what any single province can reach, and it is one reason the market opening is paired with messaging that steers players toward licensed sites in the first place.
Self-exclusion is the emergency brake. The day-to-day controls are the limit tools every licensed operator has to offer from launch. The required set covers deposit limits, spending limits, and session time controls, plus regular activity statements that summarize a player's history so the picture is harder to ignore. The design logic is that most harm does not arrive as a single dramatic event. It accumulates quietly across many ordinary sessions, and friction introduced early is cheaper than intervention introduced late.
Limit tools work best when they are easy to set and slow to loosen. The detail that matters is the direction of friction: tightening a limit should take effect quickly, while raising one should carry a cooling-off delay so a heated moment cannot instantly undo a careful decision. Activity statements add a second layer by putting real numbers in front of a player who might otherwise round their losses down in their own memory. None of this stops a person who is determined to chase, but it narrows the path and creates record-keeping the regulator can later inspect.
For an audience that thinks about product design and payments, these controls are essentially consumer-finance guardrails applied to entertainment spending. They borrow the same logic as deposit caps and spending alerts in digital banking, and they live or die on the same question: are they switched on by default and built into the flow, or buried three menus deep where almost no one finds them.
The audit is easier to read as a table. Each row pairs a protection with how it is meant to operate and the party responsible for making it stick.
| Safeguard | How it works | Who enforces |
| Centralized self-exclusion | One sign-up blocks access across every licensed site, from six months to permanent | AGLC operates the list; operators must integrate |
| Deposit and spending limits | Player-set caps with fast tightening and delayed loosening | Operators build the tools; AGLC sets the standard |
| Session time controls | Reminders and limits on continuous play length | Operators implement; AGLC audits |
| Activity statements | Periodic summaries of deposits, wagers, and net results | Operators generate; player reviews |
| Identity and age verification | Account checks confirm the customer is of legal age and who they claim to be | Operators run checks under AGLC rules |
| Intervention duties | Staff and systems flag signs of problem play and act on them | Operators monitor; AGLC can sanction |
| Independent accreditation | Third-party review of responsible-gaming programs | Responsible Gambling Council |
| Advertising limits | Restrictions on inducements, targeting, and athlete imagery | AGLC writes and enforces the rules |
The pattern in that final column is the point. Almost every safeguard depends on a division of labor, where the operator builds and runs the tool while the regulator sets the floor and keeps the power to punish a brand that cuts corners. Protections without an enforcer are suggestions, and the structure here is built to avoid that trap.
For a fintech-minded reader, the most underrated safeguard is the one that happens before a single game loads. Verified identity and age checks are the gate. A licensed operator has to confirm that the person opening an account is a real, of-age resident rather than a minor borrowing a card or a fabricated profile. That single requirement does more quiet work than most flashy responsible-gaming features, because it anchors every later protection to a confirmed person rather than an anonymous login.
The payments trail extends that anchor. When deposits and withdrawals run through regulated channels, the money becomes traceable, limits become enforceable against a verified account, and patterns become visible. A customer who suddenly raises deposits and plays at odd hours leaves a record that a monitoring system can read. The same plumbing that supports anti-money-laundering checks also supports harm-reduction, since both depend on knowing who is transacting and being able to see the shape of their activity over time.
This is where Alberta's market intersects with the broader push for safer digital finance. The tools are familiar to anyone working in payments or regtech: identity proofing, transaction monitoring, and configurable limits. NCFA's own explainer on how Canadian online casino regulations work sets out how these checks, betting limits, and help resources fit into the national context, which is useful background for anyone weighing Alberta against other provinces. Applying the tools to gambling does not require new invention so much as honest implementation, and the regulated framework is what forces that implementation to be more than a checkbox.
The framework does not leave the burden entirely on the player to ask for help. Licensed operators carry a duty to look for signs of problem gambling and to act on what they find, rather than waiting for a customer to come forward. In practice that means behavioral monitoring: flagging sharp escalation in deposits, chasing patterns, marathon sessions, and other markers that research links to harm, then triggering an intervention such as a message, a prompt to set a limit, or a referral to support.
Active monitoring is the difference between a passive set of tools and a system that reaches toward people who would never click a help link on their own. The people most at risk are often the least likely to self-identify, so a safeguard that depends on the player raising a hand will miss them. By making intervention an operator obligation, the standards shift part of the responsibility onto the business that profits from the activity, which is the correct place for it to sit.
The unavoidable tension is that the operator is being asked to gently slow down its own best customers. That conflict of interest is exactly why an independent regulator with audit powers and an outside accreditation body both sit in the structure. Trust-but-verify only works if someone is actually verifying.
One more layer sits above the operator's own programs. The Responsible Gambling Council, a long-standing Canadian non-profit based in Toronto, runs an accreditation program that reviews whether a gambling operation actually meets recognized responsible-gaming standards rather than just claiming to. Independent review is what separates a genuine program from a glossy policy page, because the reviewer has no stake in the operator's revenue and no reason to grade on a curve.
Bringing an external standard into the framework matters for credibility. A regulator can write rules and audit against them, but a third-party accreditation adds a second set of eyes with its own published criteria. For consumers, the practical value is a signal they can read from outside the company: a program that has passed independent review has at least been measured against something firmer than its own marketing.
Safeguards inside the product only help people who are already playing. The advertising rules try to control how many people get pulled in and how aggressively. Alberta's standards restrict where operators can promote inducements and bonuses, generally limiting them to a brand's own site or to direct marketing that a player has explicitly consented to receive. Operators are also barred from targeting minors, high-risk individuals, and vulnerable groups.
One detail drew particular notice: advertisements cannot feature current or retired athletes. That choice is a direct response to a complaint heard across several markets, where celebrity and athlete endorsements were seen as normalizing betting for younger audiences who follow sports. Pulling familiar faces out of gambling ads is a blunt instrument, but it reflects a view that the supply of temptation deserves regulation alongside the tools that manage demand.
A fair audit ends with the gaps, not a victory lap. None of these safeguards eliminate harm, and pretending otherwise would undercut the whole exercise. The centralized exclusion list only governs licensed sites, so the offshore market remains a leak in the wall. Limit tools depend on default settings and honest design, and a tool that is technically present but practically hidden protects almost no one. Intervention duties ask operators to act against their own short-term incentives, which is why ongoing audits matter more than launch-day promises.
There is also the simple reality that regulation lags behavior. New payment methods, new game formats, and new marketing channels will test the rules faster than the rules can be rewritten. The honest verdict on Alberta's market will not come from the standards as written in 2025 and 2026 but from how seriously they are enforced two and three years on, when the novelty has worn off and the pressure to relax inconvenient rules has set in. A framework like this is best judged by its worst enforcement case, not its best brochure.
Anyone who wants to see how the entry bar was actually built can read this legal analysis of Alberta's Bill 48 iGaming framework, which lays out the registration structure and consumer-protection duties that form the practical floor every licensed brand must clear before taking a bet. The Alberta model is one experiment among several, and the provinces are quietly learning from each other's mistakes.
The takeaway is not that the new market is risk-free. It is that a regulated market with verified identity, a shared exclusion list, mandatory limit tools, intervention duties, and an independent regulator is a meaningful upgrade over an offshore status quo that offered none of those things. The safeguards are real. Their value depends entirely on whether the bodies named in that enforcement column keep doing the unglamorous work of checking.
When does Alberta's regulated online casino market open?
The province set a launch for its competitive online gambling market in 2026, with the legal foundation laid by legislation passed in 2025. Exact timing has shifted during the rollout, so the safest approach is to check the regulator's current guidance rather than rely on a date quoted in an older article.
Can I exclude myself from every Alberta site at once?
Yes. The centralized self-exclusion program is designed so a single sign-up applies across all licensed online platforms in the province at the same time, with durations from six months up to permanent. This is a deliberate improvement over excluding yourself from one site, which previously had no effect on any other.
What responsible-gaming tools are operators required to offer?
Licensed operators must provide deposit limits, spending limits, and session time controls from launch, along with periodic activity statements that summarize a player's history. They are also required to verify identity and age and to monitor for signs of problem gambling rather than waiting for players to ask for help.
Are online casinos legal everywhere in Canada now?
No. Gambling regulation in Canada is provincial, so the rules differ by province, and a framework like Alberta's does not change the law elsewhere. Several provinces still rely on a single government-run platform, while others, including Ontario and now Alberta, have opened competitive private markets under their own conditions.
Where can someone in Alberta find gambling-harm support?
Alberta's GameSense program and the Alberta Health Services Addiction Helpline offer free and confidential support around the clock. Licensed operators are also required to surface responsible-gaming resources and self-exclusion options directly within their platforms, so help is reachable from inside the account rather than only through an outside search.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 1, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, Consumer Finance And Lending, SME Finance And Business Banking, Fintech And Innovation

On June 25, 2026, Financeit closed a C$201 million term ABS transaction backed by home improvement loans, issuing Series 2026-1 notes through Financeit Securitization Limited Partnership.
Financeit says the deal is the first Canadian term asset backed securitization backed by home improvement loans. Morningstar DBRS rated the notes from AAA(sf) to BBB(low)(sf). Goldman Sachs acted as structuring and joint lead placement agent, CIBC Capital Markets acted as joint lead placement agent, and BMO Capital Markets acted as co manager.
The transaction is a capital markets milestone for Canadian fintech lending. Financeit is turning point of sale home improvement loans into rated institutional paper, giving the company another funding channel as annual loan originations approach C$2 billion.
Financeit already had warehouse and lending facilities. The new ABS deal adds longer term institutional funding to support loan growth.
VersaBank's real time funding pilot with Financeit showed how point of sale receivables can be funded closer to origination, while this ABS transaction moves the loan book into rated capital markets paper.
The company says the transaction, combined with existing lending facilities, gives it approximately C$2.5 billion in annual loan funding capacity, a reliable volume of capital.
Casper Wong, co founder and CEO of Financeit, said the transaction reflects the scale and performance of the platform:
"Over the last four years, we have grown at a 33% compounded annual growth rate, fueled by strong execution in our home improvement business and continued expansion across multiple verticals."
Home improvement lending is at the intersection of consumer finance, merchant finance, and household infrastructure spending. Borrowers want payment flexibility. Contractors and dealers want higher close rates. Lenders need repeatable underwriting, servicing, funding, and loss performance.
Financeit built its model through merchant and dealer networks rather than a branch based lending channel. The company says it has funded more than C$10 billion in loans since inception, serves nearly one million Canadians, and works with more than 10,000 dealers across Canada.
That scale gives securitization investors a pool of receivables large enough to analyze. It also gives Financeit a path to recycle capital more efficiently as originations rise.
Securitization rewards platforms that can show repeatable underwriting, clean servicing, predictable cash flows, and enough data for rating agencies and institutional buyers.
The ABS market gives lenders access to deeper capital, but it also increases scrutiny. Investors will watch delinquencies, prepayments, losses, dealer performance, borrower quality, and whether loan growth stays disciplined.
For Canadian fintech lenders, that scrutiny is healthy. It separates platforms that can originate loans from platforms that can fund, service, monitor, and report credit at institutional scale.
Float's $85 million Series C shows Canadian business finance platforms raising growth capital to expand payments, cash management, credit, and AI finance workflows.
Conexus backing JUDI.AI highlights how AI cash flow underwriting is entering credit union and community bank lending.
EQ Bank's Business Card launch shows digital banking moving deeper into business spending, cash flow, and operating accounts.
Better banking options for Canadian SMEs remain a live competition issue as businesses seek faster credit, lower friction, and more useful financial tools.
NCFA's Financial Innovation Map tracks lending, securitization, capital formation, SME finance, embedded finance, and credit infrastructure opportunities.
If Canadian fintech lenders can turn specialized loan books into rated ABS transactions, which lending categories become large enough for institutional capital next?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 1, 2026
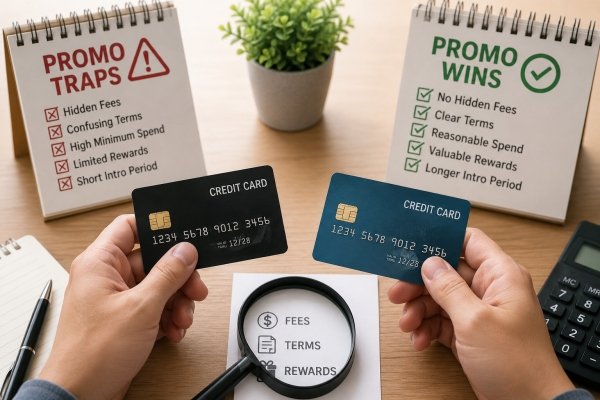
Issuers have plenty of strategies to make credit cards more appealing, and one of these is offering promotional deals that come with extra benefits or rewards for new applicants. These promos are often designed to give potential cardholders a head start on earning rewards, allowing them to maximize value from their spending while also testing the card’s features. However, not all credit card deals are legitimate. Some may seem attractive at first, but they’re actually traps that offer misleading promises to consumers or take advantage of them through hidden fees and costs.
Knowing what a genuine credit card deal looks like can help you avoid making costly mistakes or falling victim to fraudulent schemes. Here are key indicators to look for when evaluating a promo.
A promo’s credibility often depends on who is offering it. Deals from established card issuers are more likely to deliver what they promise, since these institutions want to protect a reputation built on honesty and reliability. If you want to make sure that your rewards and benefits will actually be honored, it’s a good idea to check the issuer’s track record before applying. This way, you can avoid deals with vague mechanics or misleading rewards.
Take Maya, as an example. Considered to be the #1 digital bank in the Philippines, Maya is a widely trusted platform by many Filipinos. More than that, it’s also regulated by the Bangko Sentral ng Pilipinas, which means it follows strict rules to protect customers. Considering these, you can be confident that any Maya credit card promo you choose offers legitimate rewards and honors your rights as a consumer.
Clear and fair introductory rates are tell-tale signs that you can benefit from a credit card promo. A good offer will specify the interest rates for purchases, balance transfers, or cash advances, as well as how long the introductory period lasts. Having access to this information enables you to plan your spending and understand the costs of credit card ownership upfront, which reduces surprises while building your confidence in the deal.
A good credit card promo also has competitive rates. These reflect fair pricing compared with other cards and provide assurance that you’re not overpaying for the perks offered by the credit card promo. To find out if the rates are truly competitive, it’s helpful to compare them with similar cards and check for any additional fees that might apply. This will let you identify promos that genuinely save you money and avoid ones with hidden costs.
Some card promos require you to meet a spending threshold within a set period—usually a few months—to qualify for rewards. A credit card deal that works in your favor wouldn’t impose extremely high minimums that can create stress or even lead you to debt. A promo that matches your lifestyle often aligns with your normal spending habits, meaning you can realistically achieve the rewards without overspending. The minimum spend will depend on the type of card, with premium cards having much higher thresholds than standard cards. Knowing your typical monthly spending can help you find a promo that can complement and even reward the way you manage your finances.
A winning promo clearly explains how to earn and redeem rewards. The steps to qualify for bonuses should be simple and easy to follow, without confusing requirements. Transparent mechanics allow you to understand exactly what actions are needed to benefit from the promo. When the process is straightforward, you can confidently plan your spending and qualify for rewards without frustration.
Legitimate credit card promos disclose all relevant fees and penalties upfront. Annual fees, late payment charges, and interest rates should be clearly listed, with no surprises hidden in fine print. Fair fee structures ensure that the credit card’s rewards and perks do not come at an unreasonable cost. Checking these fees, in turn, helps you avoid deals that look appealing but could end up costing more than the benefits they offer.
Clear and accessible terms make it easy to know how a promo works. Key details, like eligibility, reward limits, and deadlines, are often highlighted, making it simple for applicants to see what they’re signing up for. Promos with vague rules or overly complicated wording are often misleading and should be approached with caution, as they can hide limitations or costs that reduce the value of the offer. That’s why, before applying for a card or joining a promo, make sure to read the fine print and clarify anything that seems unclear. This ensures you don’t end up missing rewards, facing unexpected charges, or falling into credit card promo scams.
In the end, careful attention to the details of any credit card promo can save you from unexpected costs and disappointment. When you can recognize the key elements of what makes a genuine offer, you can quickly spot deals that truly reward your spending. Couple this with the right strategies for evaluating your options, and you can select promos with clear benefits and enjoy real value from your card.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 1, 2026
Under the Ontario Highway Traffic Act, a charge of careless driving is one of the most serious non-criminal offences a driver can face. Law enforcement officers often issue this ticket following motor vehicle accidents, alleging that a motorist drove without proper care and attention or without reasonable consideration for others on the road. Because this charge is broad and relies heavily on the officer's personal opinion, it carries severe penalties, including six demerit points, a six-month license suspension, massive financial fines, and even potential jail time. Defending against this allegation requires an aggressive and precise legal strategy.
A conviction for careless driving goes far beyond a simple traffic ticket; it is treated as a major offence by insurance companies, similar to a criminal impaired driving conviction.
Upon a formal conviction, the Ministry of Transportation immediately applies six demerit points to your driving record, which triggers a mandatory interview for fully licensed drivers and can lead to an automatic suspension for novice drivers. Furthermore, the court can issue discretionary fines ranging from hundreds to thousands of dollars and suspend your driving privileges for up to two years. For many everyday drivers, the sudden jump in insurance costs or a total policy cancellation makes keeping a vehicle impossible, threatening their employment and daily lives.
To secure a conviction, the prosecution must prove that your driving fell well below the standard of a reasonably prudent driver. Simply being involved in an accident is not legal proof of careless driving.
The defence team at Traffic Paralegal Services carefully analyses every element of the crown's case. They review accident reconstruction data, interview independent witnesses, and check road conditions, weather data, and mechanical factors. A successful defence often centres on proving that the incident was a simple error in judgment or an unavoidable accident caused by sudden environmental changes, rather than a reckless disregard for public safety.
The stakes are incredibly high in careless driving cases, meaning you should never enter a courtroom without experienced legal representation. Prosecutors often push for severe penalties, making professional guidance essential for a fair trial.
The court specialists at Traffic Paralegal Services bring extensive experience to these complex cases. They handle all discussions with the crown prosecutor, looking for opportunities to get the charges completely dropped due to insufficient evidence or technical errors. If a full withdrawal is not possible, they work to reduce the charge to a minor, low-point infraction like "follow too closely," saving you from a high-risk insurance status and protecting your freedom to drive.
Defending against a major traffic allegation requires immediate legal action, an independent investigation, and skilled courtroom advocacy. By actively fighting careless driving tickets in ontario, you protect your freedom, avoid severe financial penalties, and keep your insurance affordable. Accepting a careless driving conviction without a fight can negatively impact your life and career for years to come. Invest in your future by placing your case in the hands of proven traffic law experts. Partnering with a trusted, experienced firm like Traffic Paralegal Services ensures your defence is built correctly, giving you the best opportunity to secure a successful outcome in court.
“In 2026, trust has become the deciding factor for people fighting traffic charges in Ontario - especially as we hear more clients describe being let down by representatives who operate without structure or accountability. Too often, the story is the same: a meeting arranged at a coffee shop, a quick promise that the matter is “handled,” and then silence - missed updates, unanswered calls, and no meaningful steps taken toward resolution. That experience does more than waste time; it increases stress and can put a client’s case at risk.
At Traffic Paralegal Services, we build trust through a formal intake process, clear written next steps, consistent communication, and file management that does not depend on one-off meetings or vague assurances. Clients know where their matter stands, what is happening next, and who is responsible at every stage - from request for disclosure to negotiations and court attendance. Reliability is not a marketing line; it is the foundation of how we serve our clients.”
Volodymyr Menok, President, Traffic Paralegal Services
Director, Traffic Paralegal Services
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 29, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Regulation And Policy

NCFA has published a practical guide to the UK cryptoasset regulations and FCA final rules. It helps firms, platforms, issuers, custodians, compliance teams, investors and policymakers understand how the UK framework applies across regulated digital asset activities.
The primary Regulatory Intelligence guide organizes the rule package by authorisation, scope, stablecoin issuance, custody, trading platforms, disclosures, market abuse, prudential requirements, Consumer Duty, governance, operational resilience, financial crime, reporting and implementation readiness.
The resource gives readers a structured entry point into the UK cryptoasset regime without treating the rulebook as one long regulatory document. It directs readers to the detailed Regulatory Intelligence explorer, where each rule area separates requirements, implementation work, consultation outcomes and NCFA analysis.
That distinction is important because firms need to prepare for more than registration. They may need to assess permissions, governance, safeguarding, disclosures, capital, operational controls, market integrity, customer communications, reporting and senior management accountability.
The framework also gives Canadian and global readers a useful comparison point as tokenized financial infrastructure, stablecoins and regulated digital asset markets develop. The central question is which firms can meet regulated market standards while continuing to build useful products and services.
This resource is designed for crypto trading platforms, custodians, stablecoin issuers, digital asset infrastructure firms, fintech founders, compliance teams, securities lawyers, investors, policymakers and market participants comparing global crypto regulatory models.
It is especially relevant for organizations assessing FCA authorisation, custody controls, stablecoin infrastructure, consumer disclosures, market abuse controls, governance, prudential requirements and operational readiness.
The strength of the resource is its practical structure. It turns a large regulatory package into a clear intelligence layer that readers can use to identify obligations, implementation dependencies and areas requiring specialist legal, compliance, technology or operational work.
It also supports jurisdictional comparison. Canadian and global market participants can use the UK rules to compare approaches to crypto authorisation, custody, stablecoins, disclosures, platform conduct, market integrity and consumer protection.
The guide is not a substitute for legal advice. Regulatory treatment depends on the facts, firm structure, permissions, product design and activities performed in or into the UK. Readers should use it for ecosystem intelligence and planning, then review the FCA primary materials and consult qualified advisers.
UK Cryptoasset Regulations And FCA Final Rules
Primary NCFA Regulatory Intelligence guide with the full rule explorer, implementation analysis, timeline and source links.
Tokenization Starts Looking Like Financial Infrastructure
Market infrastructure context for tokenized cash, custody, settlement and regulated digital asset rails.
Deloitte And Stablecorp Bring QCAD To Banks
Canadian stablecoin infrastructure context for banks and regulated financial institutions.
FCA Final Crypto Rules Announcement
Official FCA source announcing the final UK cryptoasset rule package.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
The UK cryptoasset regulations bring specified cryptoasset activities into Financial Conduct Authority supervision under the Financial Services and Markets Act. The FCA final rules cover authorisation, trading platforms, intermediaries, stablecoin issuance, custody, lending, staking, disclosures, market abuse, prudential requirements, Consumer Duty, governance and operational resilience. The regime starts on 25 October 2027.
Firms that carry out or plan to carry out regulated cryptoasset activities should prepare their authorisation and implementation evidence before the application deadline.
The new FCA cryptoasset regime starts on 25 October 2027.
The scheduled application period runs from 30 September 2026 to 28 February 2027. Firms seeking to rely on saving and transitional provisions should apply within that period.
No. Existing registrations and permissions do not automatically convert. A firm carrying on an in scope regulated cryptoasset activity will need the relevant FSMA permission.
The regime covers activities including operating qualifying cryptoasset trading platforms, dealing, arranging, stablecoin issuance, custody, lending, borrowing and staking. Admissions, disclosures and market abuse rules also apply.
The package includes the CRYPTO sourcebook, CASS 16 and CASS 17, CRYPTOPRU and COREPRU, plus relevant Consumer Duty, COBS, SYSC, SM&CR, DISP, reporting and operational resilience requirements.
Firms should confirm scope, prepare governance and financial resource evidence, document custody and resilience controls, assess Consumer Duty outcomes and build a complete authorisation file for their business model.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 30, 2026 | NCFA Story Intelligence | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure
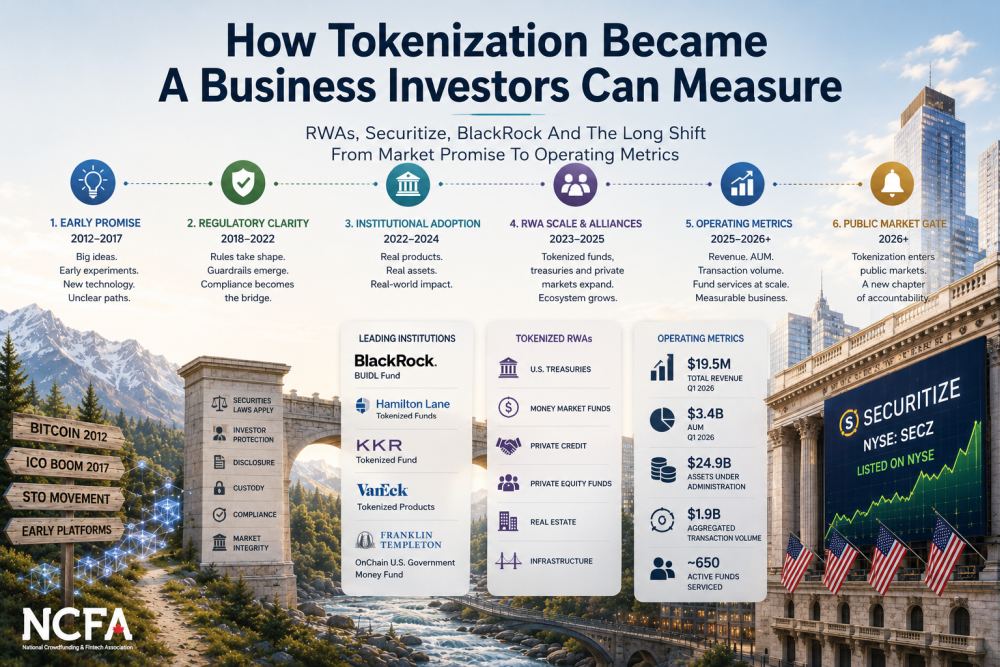
Tokenization promised to change capital markets for more than a decade.
The promise is still attractive. Put ownership on chain. Reduce paperwork. Automate compliance. Improve access. Speed up settlement. Make private assets easier to distribute, manage, and transfer.
But markets don’t run on promises. They run on operating models, regulation, distribution, controls, liquidity, and trust.
That’s why Securitize’s expected NYSE listing is the trigger. The listing isn’t the whole story. It’s the latest chapter in a longer path from tokenization as a market idea to tokenization as a business investors can measure.
The first wave sold a powerful idea. Security tokens, STOs, fractional assets, real estate tokens, private shares, and blockchain based markets promised to bring traditional securities into programmable digital form. The early security token field was framed as a more regulated answer to the ICO boom.
The market didn’t overhaul itself. Early security token projects ran into the same walls: unclear regulation, thin liquidity, limited distribution, custody questions, fragmented platforms, investor eligibility rules, and the simple reality that a tokenized security still has to behave like a security.
The hard work was never only technical. A tokenized fund still needs investor onboarding, KYC, AML, transfer rules, custody, servicing, reporting, distributions, tax records, corporate actions, and permissioned secondary transfers. Those aren’t marketing features. They’re the boring parts that make markets work.
Regulators kept reminding the market that labels don’t change obligations. Hester Peirce’s point that tokenized securities still have to follow securities laws captured the practical boundary. Faster settlement and automation don’t remove investor protection, disclosure, and market integrity requirements.
Real world assets changed the packaging. The market stopped asking whether everything should become tokenized and started asking which assets actually benefit. Treasuries, money market funds, private credit, private equity funds, and alternative assets became more practical test cases than vague claims about digitizing every market.
Private markets gave tokenization a clearer job. Citi, Wellington Management, and WisdomTree tested private market tokenization in 2024, showing how smart contracts could support operating efficiency in traditionally manual private market processes.
Hamilton Lane used tokenization to lower access friction. In 2022, Hamilton Lane and Securitize said qualified US investors would gain access to tokenized feeder funds tied to direct equity, private credit, and secondary transaction strategies.1 Securitize later said one Hamilton Lane fund reduced the minimum investment from about $5 million to $20,000.2
KKR showed that major alternatives managers would test the model. Securitize launched a tokenized fund offering exposure to KKR’s Health Care Strategic Growth Fund II in 2022, framing the product around broader access to alternative investments through digital ownership.3
BlackRock changed the market’s confidence level. BlackRock launched BUIDL, its first tokenized fund, on Ethereum in March 2024. The fund was backed by cash, US Treasury bills, and repurchase agreements, with BNY Mellon enabling interoperability between digital and traditional markets.4
BUIDL became a measurable adoption signal. In March 2025, Securitize said BUIDL surpassed $1 billion in AUM and identified itself as the tokenization provider for the fund.5 BlackRock’s BUIDL launch became one of the clearest institutional signals that tokenization was entering regulated asset management.
Securitize turned the thesis into operating data. In Q1 2026, Securitize reported $19.5 million in total revenue, up 39% year over year, $3.4 billion in AUM at quarter end, $24.9 billion in assets under administration, $1.9 billion in aggregated transaction volume, and roughly 650 active funds serviced through Securitize Fund Services.6
Those numbers change the conversation. Investors can ask normal operating questions: revenue mix, servicing fees, client concentration, transaction volume, fund growth, margins, profitability, operating leverage, customer retention, regulatory execution, and how much tokenization demand converts into durable revenue.
The listing is the trigger. Securitize and Cantor Equity Partners II said the business combination was expected to raise approximately $400 million in gross proceeds, close after shareholder approval and customary conditions, and list on the NYSE under ticker SECZ.7
The listing doesn’t settle the thesis. It exposes the thesis to market discipline. A listed tokenization company has to explain growth, losses, expenses, institutional demand, regulatory risk, competitive pressure, and whether tokenized fund adoption can become a durable public company business.
Canada has a practical watchlist. The opportunity isn’t to copy a US listing. Canadian firms can look across the tokenization value chain: custody, transfer services, fund administration, compliance, exempt market distribution, private market platforms, digital identity, investor onboarding, reporting, and secondary trading.
Regulated product design may decide the next chapter. The OSC’s long term asset fund project pointed to possible retail exposure to traditionally inaccessible assets and raised the opportunity for tokenized long term funds with embedded compliance, transparent records, fractional access, and guardrails.
Tokenization didn’t become measurable overnight. It moved through years of big claims, stalled experiments, regulatory pushback, operating layer buildout, institutional product design, and real world asset packaging before public markets had a company they could evaluate with ordinary business questions.
That may be the clearest test. The first tokenization wave asked investors to believe in a technology. The next wave will ask investors to evaluate execution. Revenue. Margins. Assets. Transactions. Clients. Losses. Retention. Market share. Operating leverage. That is a much harder test, and a much more useful one.
For Canada, the lesson is practical. The next winners may not be the firms issuing the tokens. They may be the firms solving everything around them: custody, compliance, investor onboarding, fund administration, reporting, liquidity, and regulated distribution. That’s where durable businesses are often built, and where Canada’s capital markets innovation map can help identify opportunities that are still taking shape.
What operating metric would convince you that tokenized markets have moved beyond promise?
Share this story → Explore related intelligence → Subscribe
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016