




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Jun 30, 2026

For those exploring a fresh online entertainment experience, this platform offers an impressive array of functionalities that cater to diverse preferences. Take advantage of the enticing welcome bonuses designed to give newcomers a robust start, enhancing their initial experience significantly.
The interactive environment features a user-friendly interface that simplifies navigation, making gameplay intuitive for both novices and seasoned players. Real-time statistics and analytics allow participants to track their performances and adjust their strategies accordingly, leading to tailored gaming sessions.
Additionally, engagement opportunities abound through community-driven events and tournaments that encourage friendly competition. Loyalty programs reward consistent players with perks and incentives, fostering a welcoming atmosphere. All these elements contribute to a dynamic and enjoyable online experience that is hard to resist.
An extensive array of gaming options caters to various preferences, ensuring that players can find something that suits their style. Unique titles often feature inventive gameplay mechanics, elevating the overall experience. Look out for offerings that combine traditional casino elements with modern twists, such as skill-based components or story-driven adventures, especially when exploring platforms in the crypto casino Canada segment.
Live-action games have transformed the entertainment landscape, allowing players to engage with real dealers in real-time. This format delivers an immersive atmosphere that mimics the ambiance of a physical venue, fostering social interaction. Consider trying out themed live shows, which blend popular culture elements into classic formats for an added layer of enjoyment.
Add-on features like progressive jackpots or customizable game settings enhance user engagement and provide opportunities for increased rewards. These options encourage diverse play styles, appealing to both casual gamers and high rollers. Regularly updated libraries help maintain interest, as new titles are introduced frequently, offering fresh and exciting challenges to explore.
To enhance the gaming experience, consider engaging with various limited-time offers and promotional events. Often, these promotions come in the form of deposit bonuses, where additional funds are credited to your account upon making a qualifying deposit. Pay attention to the details, as each promotion may have specific requirements.
Another attractive option is the referral program. By inviting friends to join, players can earn bonuses or free credits for each successful signup. This not only provides rewards but also creates a sense of community among users, fostering interaction and competition.
Loyalty schemes are designed to recognize and reward consistent participation. Players accumulate points based on their activities, which can later be exchanged for bonuses, gifts, or even exclusive experiences. Regularly check the loyalty program tiers to maximize benefits as you advance through levels.
Seasonal promotions often bring additional excitement, aligning offers with holidays or significant events. Participating during these times can lead to substantial bonuses and unique prizes. Ensure to monitor announcements for these opportunities, as they can significantly boost the gaming experience.
Lastly, subscribing to newsletters or notifications is a practical way to stay informed about the latest campaigns. This ensures that players never miss an opportunity to take advantage of exclusive offers, enhancing both engagement and rewards in the long run.
To enhance your engagement, the platform offers an intuitive layout designed for seamless interaction. Clear navigation bars and organized menus ensure that all available activities are easily accessible, minimizing time spent searching for options.
The color scheme is soothing, with a modern aesthetic that enhances visibility. Users can quickly identify sections such as betting options, account management, and help resources. This thoughtful design allows users to focus on their gaming experience without distractions.
Customer support is easily accessible, with a dedicated help center and live chat functionality. This feature enables users to receive assistance quickly, contributing to a positive overall experience.
Regular updates and user feedback integration demonstrate commitment to enhancing the interface. Continuous monitoring and tweaks based on popular user requests foster a community-focused environment, where player satisfaction is prioritized.
A wide range of multi-currency wallets is recommended for seamless and secure financial transfers. Look for options that support popular coins including Bitcoin, Ethereum, and various altcoins, enabling users to deposit, withdraw, and place bets with their preferred digital assets.
Security measures play a critical role in the reliability of online transactions. Implementing two-factor authentication (2FA) adds an extra layer of protection for users. Always ensure that the platform utilizes encryption protocols (like SSL) to keep personal and financial data secure from unauthorized access.
Consider utilizing platforms that offer blockchain technology for transparency. Each transaction is recorded on a public ledger, making it easier to verify and trace payments. This not only enhances privacy but also builds trust between users and the service provider.
For enhanced convenience, many users prefer platforms that enable direct cryptocurrency payments without the need for currency conversion. This can mitigate the risk associated with volatile exchange rates and hidden fees during conversions.
| Cryptocurrency | Transaction Speed | Typical Transaction Fees |
| Bitcoin | 10 minutes | $1-10 |
| Ethereum | 15 seconds | $0.50-5 |
| Litecoin | 2.5 minutes | $0.01-0.05 |
| Ripple | 3-5 seconds | Minimal |
Evaluate the transaction limits imposed by the service. Understanding the minimum and maximum deposit and withdrawal thresholds can help manage your gameplay or betting strategy. This information is often available in the FAQ section or customer support.
Regularly monitor the platform’s policy on transaction discrepancies. A responsive customer support team is beneficial in resolving any issues swiftly, ensuring a hassle-free gaming experience. Always choose platforms that offer clear communication channels for such concerns.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Jun 29, 2026 | NCFA Resource | Open Banking Open Finance, Regulation And Policy
Last updated: September 11, 2026

NCFA has published a new Regulatory Intelligence guide to Canada Open Banking and Consumer Driven Banking Rules. The interactive resource organizes the proposed regulations, implementation requirements, consultation questions and strategic issues shaping Canada’s regulated open banking framework.
For a broader view of Open Banking and Consumer-Driven Finance, including the Canadian market map, 146 learning modules, company intelligence, global benchmarks and interactive discussions, explore NCFA Open Banking & Consumer-Driven Finance Interactive Intelligence.
The guide tracks accreditation, data scope, consent, authentication, security, technical standards, liability, reporting, complaints, national security review, fees and administrative monetary penalties. It also explains why consumer trust, fraud prevention and clear accountability are central to implementation. For further analysis, see Canada's Open Banking Strategy Starts With Trust.
The resource gives readers a structured way to understand what the proposed Consumer Driven Banking Regulations would require before final rules are published.
Instead of treating the regulations as one long legal document, the guide breaks them into operating topics. Each section separates regulatory requirements, implementation work, consultation considerations and NCFA’s strategic perspective.
Canada’s open banking framework is progressing from policy design into regulatory implementation. Firms need to understand more than API access. They need to prepare evidence for accreditation, consumer consent flows, registry checks, authentication records, security safeguards, breach response, complaint procedures, service standards, reporting obligations and board level accountability.
The 60-day Canada Gazette consultation closed on August 26, 2026. The proposed regulations remain subject to finalization, while firms continue preparing for accreditation, supervision, data-sharing, consent, security and operational requirements.
This resource is useful for fintech founders, open banking platforms, financial institutions, credit unions, payment service providers, data aggregators, regtech providers, compliance teams, investors, policymakers and industry associations.
It is especially useful for organizations assessing accreditation, product design, consent architecture, data sharing duties, technical standards, cybersecurity, consumer protection and implementation costs.
The strength of this resource is its focus on regulatory readiness. It converts the proposed Consumer Driven Banking Regulations into a practical intelligence layer that can support planning, consultation, product design and ecosystem coordination.
The guide connects the proposed regulations to Canada’s policy objectives, including stronger consumer protection, fraud mitigation, secure financial data sharing, competition and confidence in the open banking framework.
It also connects regulation to commercial opportunity. The guide identifies where read access, data portability, identity and income verification, cash flow analysis, embedded workflows, write access and open finance may create future product and infrastructure demand.
The regulations remain proposed and may change following consultation. Readers should use the guide for ecosystem intelligence and planning, not as legal, financial, investment, compliance or professional advice.
Canada Open Banking and Consumer Driven Banking Rules (primary NCFA Regulatory Intelligence guide)
NCFA Open Banking & Consumer-Driven Finance Interactive Intelligence (market map, 146 learning modules, company intelligence, discussions and global benchmarks)
Canada's Open Banking Strategy Starts With Trust (consumer protection and fraud readiness)
Open Banking In Canada Opportunity Brief (commercial opportunity layer)
NCFA Financial Innovation Map (ecosystem context)
Proposed Consumer-Driven Banking Regulations (official Canada Gazette source)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
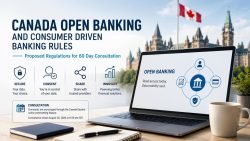
Canada’s proposed Consumer Driven Banking Regulations establish the operating framework for open banking. They address accreditation, consumer consent, data sharing, security, technical standards, liability, complaints, reporting, national security review and enforcement.
Use this guide to understand the proposed requirements, the implementation work they create and the post-consultation issues that may affect banks, credit unions, payment service providers, fintechs, consumers and small businesses.
The 60-day consultation closed August 26, 2026. The regulations remain proposed while Finance Canada considers feedback and prepares the next regulatory steps. Firms can use the published draft for planning, but final requirements and implementation timing may still change.
For a broader view of Open Banking and Consumer-Driven Finance beyond the regulatory framework, explore NCFA Open Banking & Consumer-Driven Finance Interactive Intelligence, including the Canadian Market Map, 146 learning modules, company intelligence, discussions, innovation themes and global benchmarks.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 29, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, SME Finance And Business Banking, Artificial Intelligence And Data, Fintech And Innovation
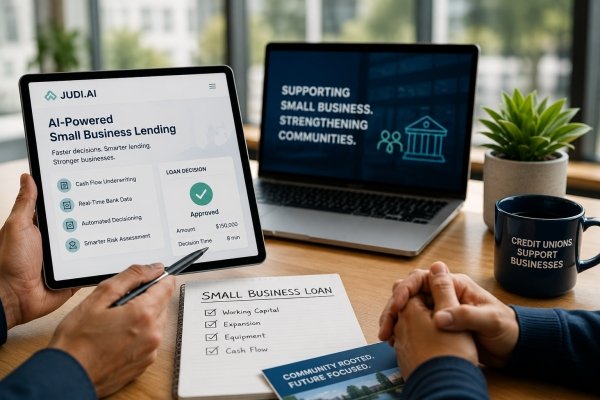
On June 29, 2026, Conexus Venture Capital invests in JUDI.AI, a Vancouver fintech whose AI cash flow underwriting platform helps credit unions and community banks make faster small business lending decisions. Existing investor Unitus Community Credit Union also participated.
The round size wasn't disclosed, but its a strong transaction. A credit union backed venture fund is financing AI lending infrastructure that already serves credit unions and community banks across Canada and the U.S.
JUDI.AI says its platform has processed more than $2 billion in small business loan applications, supports more than 50 clients, and can reduce the loan application and decisioning process from more than seven days to under ten minutes without collecting financial statements. The platform uses permissioned bank transaction data, a domain specific credit model, and a real time view of cash flow to assess small business borrowers.
Small business lending has always fit the credit union model in theory. Credit unions know local communities, relationship banking, and member service. The problem is operating cost.
A small business loan can still require bank statements, financial statements, manual review, back and forth questions, policy checks, risk scoring, and approval work. If the process takes too long, borrowers look elsewhere. If the process costs too much, lenders struggle to serve smaller tickets profitably.
JUDI.AI is targeting that gap. The platform combines cash flow analysis, automated underwriting, loan portfolio reporting, and analytics for credit unions and community banks. Instead of relying only on older financial statements or conventional lending metrics, it helps lenders assess live business activity through permissioned transaction data.
That gives credit unions a way to compete on speed without abandoning lending discipline.
Conexus was already familiar with the platform before the venture investment. The announcement says small business members in Saskatchewan previously used JUDI.AI for years to access loans faster, while Conexus reduced the time required to process applications.
That makes the investment more than a financial bet. Conexus is backing a tool it's used inside its own lending workflow, where speed, borrower experience, staff capacity, and credit discipline all matter.
Gord Baizley, CEO of JUDI.AI, framed the business around lending practice:
"At JUDI, we're not just selling a platform. We're championing a methodology. We've learned that success in small business lending is more than just technology, but a holistic approach that blends people, process, technology and intentional growth."
Better SME credit infrastructure is not only about faster models. It also depends on workflow design, risk controls, lender adoption, borrower experience, and portfolio monitoring.
JUDI.AI's model fits a larger fintech pattern. SME finance is increasingly built around current business activity rather than static documents.
That connects directly to Canada's open banking opportunity and NCFA's Open Finance SME Capital Access opportunity work. Read access can support income verification, affordability checks, cash flow insight, fraud signals, onboarding, and SME credit.
For small businesses, the commercial value comes when permissioned financial data helps lenders understand revenue, expense patterns, repayment capacity, seasonality, and account behaviour without weeks of manual collection.
The AI model needs good data, the lender needs clear controls, and the borrower needs a simpler application path. If those pieces work together, small business credit can become faster and more accessible without turning into loose lending.
JUDI.AI's decade of performance data also gives the platform a stronger adoption story than a new AI wrapper. Credit unions are buying a tested underwriting process designed for their borrower base.
Float's $85 million Series C shows Canadian business finance platforms expanding across payments, cash management, credit, and AI finance workflows.
EQ Bank's Business Card launch adds spending, cashback, interest, and cash flow tools to its SME banking stack.
Better banking options for Canadian SMEs remain a live competition issue as business owners seek lower friction, better credit access, and more useful digital financial tools.
NCFA's Financial Innovation Map tracks SME finance, open finance, AI underwriting, business banking, and financial data infrastructure opportunities.
The Conexus investment shows how credit unions can use venture capital as more than a financial return tool. They can back fintech infrastructure that improves member service, strengthens local business lending, and gives community based institutions a better way to compete with digital lenders.
For JUDI.AI, the next step is continued growth. The platform already supports credit unions and community banks across Canada and the U.S., and the new capital supports North American growth and product development. The strongest path is helping lenders approve strong small business borrowers faster, manage risk with better cash flow data, and keep local credit relationships inside the credit union system.
The competitive question is whether credit unions can adopt fast enough? Fintech lenders, banks, embedded finance platforms, and business finance software firms are all trying to own more of the SME finance relationship. Credit unions have trust and local presence. They now need digital credit infrastructure that matches borrower expectations.
If credit unions can combine local member trust with AI cash flow underwriting, can they become the strongest distribution channel for small business lending in Canada?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
Jun 29, 2026

Despite its importance, billing precision often falters under manual handling. Errors emerge without warning when human input governs invoicing tasks. Financial forecasts shift unpredictably due to late or incorrect payments. Coordination among carriers, brokers, and shippers grows harder with each added layer of complexity. Instead of relying on outdated routines, some firms now allow software to handle incoming documents. Approval timelines shorten once digital systems take over verification steps. Expense tracking improves when data flows continuously through connected platforms.
Financial decisions gain clarity when data comes together, tied directly to shipping operations. With current logistics platforms, automated processes reveal hidden expenses through precise tracking instead of guesswork. Unnecessary payments shrink while oversight grows stronger across spending areas. Invoice handling shifts into alignment with broader efforts to manage costs where margins matter most.
With the proper use of Invoice handling in logistics shifts when automation takes over. From carrier bills to vendor statements, manual checks become unnecessary. Data pulls automatically, cross-checked with delivery logs for accuracy. Validation happens without human input, cutting down mistakes significantly. Payments go through only when services are confirmed and terms met. Agreement fulfillment decides whether a charge is processed.
It’s important to know and understand that payment cycles shrink when automation takes over, far beyond just cutting errors. Because invoices move faster, carrier relations tend to stay stable. Penalties fade into the background where timing used to fail. With tighter control over outgoing funds, businesses handling large shipping loads find breathing room - even on narrow profit paths.
Among key factors shaping expenses in freight operations, mismatches in invoicing stand out - often tied to wrong pricing, repeated charges, or absent shipping details. When digital tools compare submitted bills with agreed terms and proof of delivery, problems surface sooner. Payments stay accurate because checks happen before funds move. Consistency in accounting data improves when all units refer to the same verified outcomes.
Administrative effort contributes significantly to overall expense. Handling invoices by hand takes hours from both accounting and logistics personnel, raising daily operating costs. With delivery management software, the burden lessens so employees can shift attention toward activities like reviewing supplier terms or assessing efficiency trends. Integrated with tools managing deliveries, companies achieve clearer visibility into shipments - this clarity streamlines how invoices are verified.
When we look at links towards wider logistics networks, automated invoicing gains capability. Through integration with transport management setups, firms match charge records to current delivery movements. A cohesive picture of supply chain actions emerges - precision strengthens alongside fiscal clarity.
Because route optimization software connects to billing records, firms gain clearer insight into transport spending. Where delivery timing meets invoice data, hidden waste often appears. Fuel reports that match up with dispatch logs reveal gaps in efficiency. Through consistent system links, pricing forecasts grow more reliable. Unexpected charges drop when navigation choices reflect financial tracking.
To lower logistics expenses, focus must shift beyond rate negotiations alone. Through precise financial oversight, operational waste declines notably. Visibility into transport expenditures, when immediate, supports informed choices. With automation handling invoices, errors decrease while efficiency rises. Manual tasks shrink as systems enforce tighter budget adherence. Stronger controls emerge across logistical operations naturally. Cost management improves without added complexity.
With growth in logistics networks comes greater reliance on data, making automation essential to cost control. Where firms implement unified platforms alongside wider technological tools, improvements emerge across accuracy and sustained output. Financial discipline follows when processes evolve beyond manual handling into coordinated digital workflows.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
June 29, 2026 | NCFA Feature | Open Banking And Open Finance, Digital Identity And Trust, Cybersecurity And Fraud, Risk Compliance And Regtech, Fintech And Innovation

On June 26, 2026, the Government of Canada published Consumer Driven Banking regulations together with new fraud prevention regulations, the most significant progress in Canada's open banking implementation since legislation received Royal Assent earlier this year.
At first glance, the two regulatory packages appear separate. One establishes the operating rules for consumer driven banking. The other requires federally regulated banks to strengthen fraud prevention for electronic funds transfers.
Together, however, they reveal something much bigger.
Canada isn't simply launching open banking. It's building the trust infrastructure needed before open finance can scale.
The problem is that millions of Canadians already share their financial information through screen scraping, a practice tracked as a core open banking risk in Bank Of Canada Signals Open Banking Timing Risk. Finance Canada estimates roughly nine million Canadians currently use screen scraping despite the security, liability, and consumer protection concerns it creates. The new framework is designed to replace that model with accredited participants, standardized APIs, consumer controlled consent, and clear accountability.
Much of the early discussion around open banking has focused on data portability. The regulations suggest Finance Canada sees the challenge differently.
Data sharing is only one part of the system.
Only after these pieces exist does secure data sharing become practical.
The Regulatory Impact Analysis estimates the framework will generate approximately $13.2 billion in net benefits over ten years, compared with implementation costs of about $457.7 million, largely through greater competition, improved consumer choice, reduced friction, and innovation.
Those numbers reinforce that Consumer Driven Banking is being treated as national financial infrastructure rather than another fintech initiative.
Some viewed the fraud regulations as a separate announcement, but the timing suggests otherwise.
As consumers gain greater control over financial data and eventually broader payment functionality, fraud risks also change. Criminals increasingly exploit social engineering, account takeover, impersonation, and authorized push payment scams rather than technical weaknesses alone.
Finance Canada's fraud framework responds by requiring federally regulated banks to establish policies and procedures to detect, prevent, and mitigate consumer targeted fraud involving electronic funds transfers.
The regulations also introduce stronger expectations around consumer controls, including the ability to manage transaction capabilities and limits, express consent before enabling electronic funds transfer functionality, and fraud reporting to the Financial Consumer Agency of Canada.
Greater consumer control must be matched by stronger consumer protection. The inherent message is that the federal government wants to make fraud prevention part of the architecture rather than an afterthought.
Reading the regulations together shows that trust is no longer treated as a policy objective. It's becoming operational and the framework combines:
None of those capabilities creates value on its own, but collectively they create an environment where consumers, banks, fintechs, and regulators can exchange financial information with greater confidence than today's screen scraping model.
The regulations therefore answer an important implementation question that has existed since Canada's open banking discussions began several years ago.
Trust is not assumed. It's engineered.
The regulations also strengthen several areas already appearing across NCFA's Financial Innovation Map.
Consumer consent requirements create opportunities for consent orchestration platforms that help consumers understand, grant, renew, and withdraw permissions across multiple financial relationships.
Accreditation requirements create opportunities for compliance operations platforms that help fintech companies prepare for accreditation, maintain operational controls, manage evidence, and demonstrate ongoing compliance.
Fraud obligations strengthen demand for behavioural fraud analytics, scam detection, mule account monitoring, transaction risk scoring, and real time payment controls.
Authentication requirements reinforce opportunities for digital identity, credential management, and secure customer authentication.
Technical standards create demand for API testing, interoperability tools, certification services, and developer infrastructure.
Liability and complaint provisions strengthen opportunities for workflow automation covering dispute management, evidence collection, case handling, and regulatory reporting.
None of these businesses exists because regulators explicitly created them, but they will emerge because every operational requirement creates work that financial institutions and technology providers must perform efficiently. And that's often where durable fintech companies are built.
The initial Consumer Driven Banking framework focuses on secure consumer permissioned data sharing. It's an intentional starting point.
Once accreditation, liability, consent management, authentication, and technical standards mature, the same infrastructure can support broader open finance capabilities, including additional financial products and, potentially, future write access.
The regulations therefore describe more than the first phase of open banking. They establish the operating foundation for future financial data ecosystems.
The opportunity is not limited to data sharing. It extends into the systems that make data sharing safe, usable, auditable, and commercially scalable.
That includes trust infrastructure, fraud infrastructure, consent systems, API reliability, compliance operations, data governance, and consumer protection workflows.
The next phase of Canada's open banking market will depend on whether these operating layers mature quickly enough for banks, fintechs, consumers, and businesses to use the framework with confidence.
That makes today's implementation decisions highly important because many of tomorrow's fintech products will inherit the rules established now.
For Canada's fintech ecosystem, this strengthens the opportunity case outlined in NCFA's Open Banking Opportunity Brief. The next iteration of value will come from tools that make consent, risk, identity, fraud controls, interoperability, and compliance easier to operate at scale.
If trust, consent, fraud controls, liability, and interoperability become core infrastructure for open banking, which product category will create the greatest competitive advantage for Canadian fintech companies over the next five years?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Jun 29, 2026
Image: Pixabay/nattanan23
Major life events can reshape your financial future in unexpected ways. Whether you get married, change careers, welcome a child, or navigate a divorce, each milestone brings new financial responsibilities.
Financial planning after major life changes helps you adapt with confidence, protect your assets, and maintain long-term stability. By reviewing your finances and adjusting your strategy as your circumstances evolve, you can make informed decisions that support both your current needs and future goals. Continue reading to learn more.
Every financial transition begins with a clear understanding of your current financial situation. Review your monthly income, expenses, savings, and outstanding debts before making any major decisions. If your income changes, update your budget immediately instead of relying on outdated spending habits. A realistic budget helps you manage daily expenses while staying focused on long-term objectives.
An emergency fund also plays a critical role during periods of change. Aim to save enough to cover several months of essential living expenses, giving yourself a financial cushion if unexpected costs arise. You should also review your insurance coverage, retirement contributions, and investment portfolio to ensure they continue to match your financial goals and risk tolerance.
Family milestones often require significant financial adjustments. If you get married, discuss budgeting, debt, savings goals, and financial responsibilities before combining accounts. Open communication helps couples avoid misunderstandings and establish shared financial priorities from the beginning.
Parenthood introduces additional expenses, making it important to increase emergency savings, review life insurance, and start planning for future education costs. Divorce, on the other hand, requires careful financial planning to protect your long-term stability.
Separate joint bank accounts, update beneficiary designations, create a realistic post-divorce budget, and review how retirement accounts or shared assets will be divided. A divorce lawyer can help manage all of this. Taking these steps early can reduce financial stress and make the transition more manageable.
A new job, promotion, career change, or business venture can strengthen your financial future when you plan wisely. Whenever your employment changes, review your salary, workplace benefits, retirement plans, and tax obligations. Understanding these changes helps you maximize your income while avoiding costly financial mistakes.
Although higher earnings create new opportunities, resist the urge to increase your spending immediately. Instead, use additional income to build savings, invest for retirement, or pay down high-interest debt. If you experience a temporary loss of income, focus on essential expenses, reduce discretionary spending, and rely on your emergency fund while developing a plan to regain financial stability.
Financial planning should evolve alongside your life. Schedule regular reviews to ensure your financial strategy still reflects your goals, responsibilities, and changing circumstances. Update your will, insurance policies, beneficiary designations, and estate planning documents after every major life event. Monitoring your credit report and evaluating your investment performance can also help you identify problems before they become significant setbacks.
Annual financial reviews give you the opportunity to adjust your budget, strengthen your savings strategy, and prepare for future milestones. Small adjustments made consistently often have a greater long-term impact than major changes made only during financial emergencies.
Financial planning after major life changes allows you to approach life's biggest transitions with greater confidence. Whether you experience marriage, divorce, career changes, parenthood, or retirement, thoughtful financial decisions can reduce uncertainty and protect your long-term well-being. By reviewing your budget, updating important documents, and adjusting your financial strategy regularly, you create a flexible plan that grows with you and supports lasting financial security through every stage of life.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016