




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 18, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Digital Assets Blockchain And Tokenization
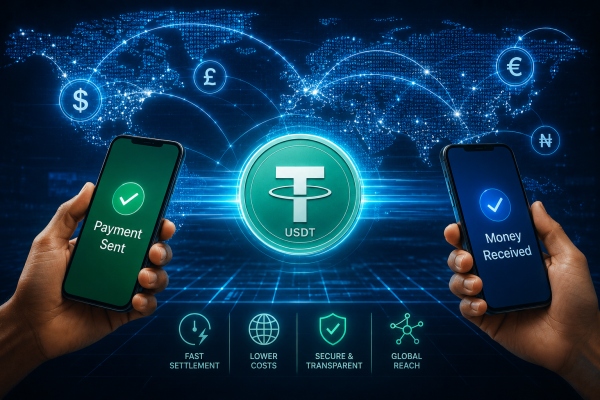
On May 18, 2026, Tether announced a strategic investment in LemFi, a cross border payments platform serving people who live and work across borders. The investment is focused on integrating USD₮ as a settlement layer across LemFi’s key corridors, especially across Africa and Asia.
This is a separate from LemFi’s USD $53 million Series B, which was announced in January 2025. Tether wants USDT deeper inside remittance infrastructure, where payment companies manage liquidity, settlement, and payout timing.
Tether says LemFi serves senders in the UK, U.S., Canada, and Europe who move money to Africa and Asia. It also says the investment aims to replace multi day SWIFT chains with near instant, lower cost settlement. That is the market issue. Remittance platforms don't compete on app design, but how quickly money arrives safely, and at a fair cost.
Paolo Ardoino, CEO, Tether:
“Our investment in LemFi reflects our shared vision on how money moves across borders, prioritizing speed, cost, and transparency. By supporting LemFi’s growth and innovation roadmap, we are helping bring the benefits of a stable digital asset to more people who rely on remittances in their daily lives.”
The practical change is settlement. USDT is not being positioned only as a crypto asset for users to hold. Tether is backing a payments platform so USDT can help move value behind the scenes across active corridors, which is valued to not only senders but to PSPs, MSBs, and banks.
Faster settlement can reduce delays and working capital pressure. But stablecoins don't solve the whole corridor. Remittance providers still need fraud controls, sanctions screening, clear FX, customer support, licensing, and reliable local payout.
Ridwan Olalere, CEO and Co Founder, LemFi:
“Integrating USD₮ into our infrastructure brings us closer to that reality, enabling faster, cheaper, and more reliable financial services for the millions of people who depend on us every day,”
While the announcement doesn't disclose the terms of the deal like Tether’s investment size or rollout timing, the business case is clear enough.
If USDT settlement shortens settlement time or reduces banking friction, LemFi could improve corridor economics. The customer impact will depend on whether those gains lead to better pricing, faster payout, or more reliable transfers.
Stablecoin issuers are actively integrating into live payment flows and partnering with platforms that have users, corridor demand, and payout networks. Traditional providers will need to build, partner, or risk losing margin.
For fintech operators and investors, the key insight is that stablecoin remittances are becoming an infrastructure strategy.
As stablecoin issuers invest directly in remittance platforms, will banks and PSPs still control the economics of cross border payments, or will stablecoin networks capture more of the settlement layer?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 20, 2026 | NCFA Resource | Digital Assets Blockchain And Tokenization, Payments And Market Infrastructure
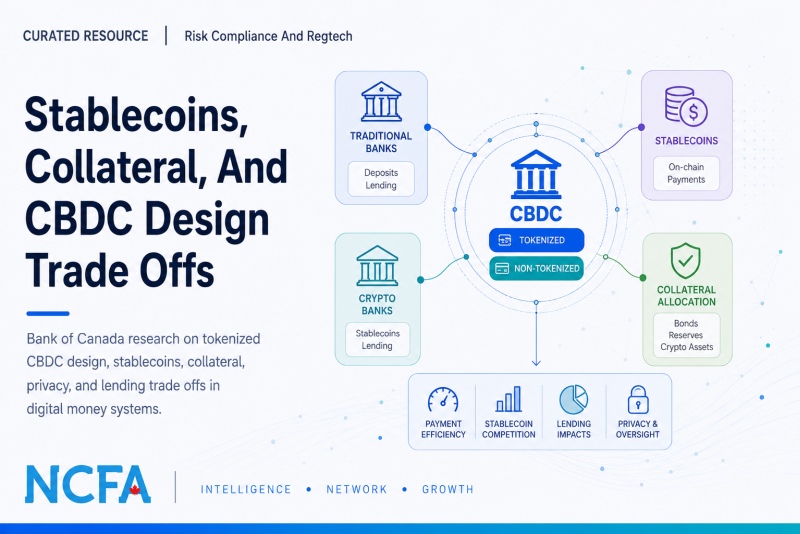
On May 7, 2026, the Bank of Canada published staff working paper 2026-14 on CBDC tokenization design. The paper looks at a financial system where traditional banks issue deposits, crypto banks issue stablecoins, and a central bank decides whether a CBDC should work through conventional accounts or programmable ledgers.
For fintechs, the useful part isn't the CBDC debate alone. The paper links tokenized money to collateral, stablecoin competition, privacy, crypto asset scarcity, and bank lending. Those issues are at the core of digital money infrastructure.
The paper compares tokenized and non tokenized CBDCs. A non tokenized CBDC competes with bank deposits in traditional payment markets. A tokenized CBDC works on programmable ledgers and competes more directly with stablecoins and tokenized settlement infrastructure in on chain markets.
The strongest finding is simple but important. Tokenization changes outcomes only when collateral use differs across sectors. The real question is which institutions hold the collateral, how reliable private money issuers are, and whether scarce reserve assets support payments or lending.
The model shows that tokenized CBDCs can crowd out stablecoins when crypto banks look less reliable and crypto assets are scarce. Non tokenized CBDCs can make more sense when crypto transactions offer less social value or when moving reserves from traditional banks to crypto banks improves the system.
The trade off is clear. CBDCs can improve payment efficiency, but they can also reduce bank lending when collateral moves away from traditional credit creation. That is where the paper becomes useful for fintech operators, not just policy teams.
The paper also raises a privacy question. A tokenized CBDC can run on a ledger that gives the central bank more visibility into transactions. That may improve oversight, but it can also reduce privacy. Digital money design is not just about speed or programmability. It also sets the rules for trust, control, and market access.
This resource is useful for fintech founders, stablecoin issuers, payment companies, banks, digital asset infrastructure providers, tokenization platforms, treasury teams, investors, and policymakers tracking the future of money.
It is especially relevant for firms building around programmable payments, stablecoin settlement, tokenized collateral, wholesale digital assets, bank issued digital money, or regulated crypto infrastructure.
The strength of this resource is the way it connects CBDC design to the financial infrastructure underneath tokenized markets. It doesn't treat CBDC as a simple retail wallet question. It looks at how money design affects collateral, settlement, stablecoins, bank deposits, crypto activity, and lending.
The paper also avoids easy answers. Tokenized CBDCs do not automatically improve the system. The result depends on collateral scarcity, crypto bank reliability, privacy settings, and the value of activity happening on programmable ledgers.
The limit is that this is an academic working paper with equations, model assumptions, and conditional results. Most operators will not read it end to end. The value is in the framework, not every technical section.
Used well, it helps fintech teams ask better questions about future money design. Who issues the money? What backs it? Where does collateral sit? What happens to lending? Who gets visibility into transactions? Those questions will matter as stablecoins, tokenized deposits, and central bank money keep moving into the same conversation.
Bank Of Canada CBDC Tokenization Paper (primary Bank of Canada working paper)
BIS Future Monetary System Blueprint (referenced framework for tokenized money and unified ledgers)
US Treasury Future Of Money Report (policy context for digital money and payment system design)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 19, 2026
Image: Unsplash/Vitaly Gariev
Sending money across borders has always been expensive.
Banks, wires, and legacy money transfer operators have made sending money expensive for years. Decades of outrageous fees have cost migrants, families and small businesses billions each year just to send their own money abroad.
But here's the good news...
Cross-border payments innovation is finally starting to deliver. Cutting-edge technology, innovative platforms, and intelligent routing are beginning to reduce cross-border costs like never before. Here's exactly how payment innovation is slashing costs and what it means for anyone who needs to make a secure international wire. Whether you're sending $50 to a relative or $5,000 to a vendor, learn how what's going on in the world of payment innovation will save you money today.
Cross-border payments used to follow one path:
Sender's bank → correspondent bank → another correspondent bank → recipient's bank.
Each hop in that chain takes a fee, adds latency, and marks up the exchange rate. When the funds arrive, the recipient may be missing a substantial portion of the sent amount.
The stats don't lie. The worldwide average price to send money is still approximately 6.36% of the amount sent. That's twice the target set by the United Nations Sustainable Development Goal of 3%.
It can be even worse in certain areas. Sending $200 to Sub-Saharan Africa cost 8.78% on average of the transfer value in Q1 2025. So if you sent $200, nearly $18 is taken in fees.
Think about what sorts of secure money transfers people actually need today. Speed, transparency, and pushing money directly to card or wallet are important to most senders. That's why learning how to send money to a Visa card has become such a popular method. Card rails cut out the sluggish correspondent banking middleman completely.
That's where payment innovation kicks in...
Payment network disruption has arrived. Here are five game changers for reducing costs paid by consumers.
Card networks have already laid the groundwork with instant push payments. Visa and Mastercard have led the charge by enabling funds to move from card to card. Instead of passing through three or four banks, money is sent directly in minutes. Compare that to the 3-5 business days for traditional wires.
What does that mean for senders?
It's a complete rewrite of how cross-border money should move.
Digital wallets are booming. Juniper Research predicts global digital wallet adoption will grow 15.3% by 2029 from 52.6% in 2024.
This is important because wallets allow senders and receivers to conduct transactions without a bank account. Users in underbanked communities can now receive funds instantly to a wallet on their phone. Eliminating:
In short, more people get more of their money, faster.
Old-school banks used to dominate the cross-border space. Not anymore.
FinTech newcomers have built leaner systems from the ground up. They utilize true exchange rates (not inflated ones) and charge flat or low percentage fees that are 100% transparent. Some are even starting to offer total cost ratios of less than 1% on popular corridors.
The consequence? Competition. Banks have no choice but to compete against each other. International fees are gradually decreasing for everyone.
Countries across the globe are deploying fast payments infrastructure and interoperability between them. India has UPI. Brazil has Pix. Europe has SEPA Instant.
When connected internationally, that's when things get interesting. Cross-border payments that used to take days can be settled in seconds. And all those savings go directly back to you, the sender.
Foreign exchange is where senders have always been silently overcharged. A markup of 1-2% over the interbank rate destroys any "low fee" claim.
Senders are now being shown the exact mid-market rate they will receive by modern providers. That level of transparency is game-changing — because once senders can see rates compared side-by-side, the most expensive providers will no longer be able to fly under the radar.
Not all borderless payment services are created equal. Here are the key things to look for if you want to maximize payment innovation:
Transparent pricing: A quality provider is upfront about what the fee is and what exchange rate they will apply. There are no surprises and no hidden FX markup included in the conversion.
Various payment methods: Top services allow users to receive money how they want; bank account, debit card, mobile wallet, cash pick up, etc. The more options available the better.
Quick settlement times: Transfers should occur same day or instantaneously, they shouldn't be a "premium feature".
Great security: Cross-border fraud isn't uncommon. Ensure the provider offers 2-factor authentication, secure encrypted transfers, and is licensed in both countries.
Extensive country coverage: Some providers only cover 10-15 countries. Others provide service to 100+. Be sure your destination is covered, and that the rates are competitive.
Today's cross-border payments market is large – and growing. It's expected to hit USD 320.73 billion by 2030, according to one report. The market is already at USD 212.55 billion in value for 2024. When there's billions of dollars at stake, companies are fighting for your business. Beneficial news for senders.
Cross-border payments are no longer the slow, expensive mess they used to be.
Card rails, digital wallets, fintech disruption, real time settlement, transparent FX pricing…these are all factors combining to lower costs for consumers. And it all adds up – particularly for consumers sending home month after month.
Here's a quick recap of what payment innovation is delivering:
Before making your next secure money transfer, spend a few minutes comparing providers. Don't just look at the advertised fee. Check the FX rate, speed of delivery and overall cost. It can mean the difference between losing US$20 or US$2 on the same transaction.
Payment innovation is finally on the sender's side. Use it to your advantage.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 19, 2026 | NCFA Fintech Market Activity | SME Finance And Business Banking, Capital Markets And Funding
On May 19, 2026, Toronto founded fintech scaleup Relay secured $50 million in growth financing from General Catalyst’s Customer Value Fund. Relay serves U.S. small businesses with banking and money management tools. The financing is meant to accelerate customer acquisition while Relay keeps existing investment focused on product development.
Relay now supports more than 150,000 small business customers and oversees more than $1.3 billion in managed customer deposits through Thread Bank, Member FDIC. Since its $32.2 million Series B in May 2024, Relay says it is on track to grow revenue by 3.2x by the end of 2026.
The funding isn't a traditional equity round, since the General Catalyst’s Customer Value Fund gives Relay capital for customer acquisition. That lets the company spend on growth without pulling the same dollars away from product, compliance, support, and reliability.
Yoseph West, Co Founder and CEO, Relay:
“Every dollar invested in Relay supports passionate folks who work hard to build their businesses and realize their ambitions. This investment is a vote of confidence in the true value we deliver to those self-made entrepreneurs, so they can put every dollar to work,”
Relay already has customer scale, deposit traction, and a clear revenue growth target. The investor question is whether paid acquisition can keep working as Relay expands its brand footprint in the U.S. small business market?
Growth can damage a financial product if the operating base isn't ready. Small businesses need stable banking access, clear cash flow views, reliable support, and simple money movement. If acquisition gets ahead of service quality, trust can break quickly.
Andrew Ziperski, Partner, General Catalyst, Customer Value Fund:
“Relay has proven its deep understanding of what small business owners actually need to succeed, with a product that clearly resonates based on the strength of its customer acquisition machine.”
Relay is trying to own more of the small business finance workflow, not just the bank account. Its platform brings together accounts, cards, bills, invoices, capital, and other money tools. That gives owners a clearer view of cash coming in, cash going out, and what they can safely spend.
Recent product activity supports that strategy. Relay’s site now highlights receivables tools for invoices and payments, while its support pages show invoice tracking, accepted payment options, automatic reminders, and recurring invoices. Relay has also added Relay Capital term loans, offering small business lending alongside the same platform where owners already manage money.
That's where SMB banking is heading. Cash flow clarity helps them decide when to pay bills, hire, buy inventory, chase receivables, or seek financing. Relay’s strategy is to turn that daily operating pressure into the product.
Important caveat is that Relay's a financial technology company, not an FDIC insured bank. Banking services not related to Relay Capital term loans are provided by Thread Bank, Member FDIC.
Relay Capital term loans are provided through Fundbox, with business loans originated by Lead Bank. That partner model is common in U.S. fintech, but it puts pressure on compliance, disclosures, customer experience, and operational control.
SMB finance remains a large market, but the winning product is no longer just an account. It's the operating system that helps owners see cash, move money, access capital, and make faster decisions when conditions get messy.
If customer acquisition can be funded separately from core product investment, do stronger platforms gain an edge by scaling distribution without weakening banking reliability, support, and product depth?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 19, 2026 | NCFA Insight | Capital Markets And Funding, Crowdfunding, Regulation And Policy
On May 16, 2026, U.S. Regulation Crowdfunding (Reg CF) marked 10 years since eligible companies could start raising capital under the SEC’s final crowdfunding rules. Our colleagues at Crowdfund Insider posted New 10 year Reg CF data from Crowdfund Capital Advisors (CCA) providing the market with a full decade of evidence, certainly something rare in early stage finance.
For NCFA and its community, this milestone deserves attention, since the association has supported investment crowdfunding through advocacy, education, market intelligence, and ecosystem building for well over a decade. In 2022, Fintech Fridays hosted a special episode on 10 Years of Investment Crowdfunding, focused on the JOBS Act. This 2026 anniversary is different because it's been 10 years since Reg CF actually went live.
The data suggests that a meaningful portion of companies using Reg CF were not just raising money once and disappearing. CCA reviewed 10,771 offerings by 8,955 issuers, and 6,063 issuers completed 7,459 offerings. Those numbers show a market with repeat activity, not just one off campaigns.
The revenue data sends a stronger business signal. Among issuers with three or more revenue data points, CCA reports 27% median annualized revenue growth, with 70% growing revenue and a 1.81x median revenue multiple. This means many companies with enough reporting history showed measurable operating growth after raising capital through crowdfunding. That supports the case that Reg CF financed real businesses, not only speculative startups.
Among issuers that raised multiple rounds, CCA reports a 24% median valuation CAGR, a 1.54x median valuation step up, and valuation increases for 79% of multi round issuers. That suggests many repeat issuers returned to the market with stronger investor validation and higher implied company value.
The repeat raise numbers are important too. More than 7,400 successful offerings from about 6,000 issuers suggests a meaningful number of companies returned to the market more than once. That points to crowdfunding evolving beyond one time community fundraising into an ongoing capital formation channel for some businesses.
Sherwood Neiss, Principal, Crowdfund Capital Advisors:
“A decade of actual market data tells a completely different story.”
That sentence captures why this milestone matters. Reg CF didn't replace venture capital like many suggested. It didn't solve every funding gap, but it democratized and proved that regulated online capital formation can support real issuers, real investor participation, and measurable growth over time.
The strongest data point is not only the growth metrics. It's now also about discipline. CCA separates issuers that keep reporting and return to the market from those that disappear from the data. It's important because transparency creates trust. A crowdfunding market cannot mature if investors, platforms, regulators, and researchers cannot track performance after the raise.
CCA reports that there's a large compliance gap in reporting. Among 5,077 Reg CF issuers with active annual reporting obligations, only 301, or 5.9%, are fully current. Another 32.4% are partially current, while 61.7% are not current. It's a gap that needs to be fixed. It is a reason to modernize reporting, reduce unnecessary friction, and build better data infrastructure.
Canada should use the Reg CF 10 year milestone to modernize investment crowdfunding. The current $1.5 million 12 month issuer cap under National Instrument 45-110 now acts as a real constraint for stronger companies, especially when campaigns can approach the limit before meeting full market demand. NCFA has long argued that Canada risks falling behind international peers that raised their crowdfunding limits years ago, including the U.S., which increased the Reg CF cap to USD $5 million in 2021.
Canada should raise the issuer cap, index it to inflation, and create a higher fundraising tier for issuers that meet stronger disclosure, financial reporting, and portal due diligence standards. NCFA has also previously advocated for right sized disclosure rules, including director and officer certified financial statements for smaller raises, reviewed financial statements for mid sized raises, and audited financials only for larger raises where the added cost is proportionate.
Investor participation rules also need modernization. Canada should review the current retail investment limits, allow greater participation from experienced and repeat crowdfunding investors, and explore a knowledge based or self certified investor category with appropriate safeguards. A modern private capital market should not assume that all retail investors have the same risk profile, sophistication, or investing experience.
Structural incentives would help strengthen the market further. Canada should explore clearer pathways for TFSA and RRSP eligibility where appropriate, support secondary market liquidity after holding periods, and encourage co investment structures that allow funds, angels, and retail investors to participate together in compliant online financings.
Canada needs standardized campaign data, stronger post raise reporting, issuer education, and technology enabled compliance for KYC, background checks, risk warnings, issuer updates, and ongoing disclosure. NCFA previously covered why Reg CF data quality matters. If regulators and policymakers rely on incomplete reporting data, they risk misunderstanding how capital actually forms, performs, and scales through online private markets.
A stronger crowdfunding market doesn't require weaker oversight. It requires smarter rules, better data, and a funding framework that reflects how modern private capital forms online.
The 10 year Reg CF story is evidence that digital investment markets can widen participation, support early stage companies, and create a more transparent private capital market. The next phase should focus on quality, not just volume. Better issuer readiness, clearer post raise reporting, credible data, secondary liquidity experiments, and stronger investor education can help crowdfunding move from alternative finance into core capital formation infrastructure.
For NCFA, this is also a moment to recognize the builders, platforms, lawyers, advocates, educators, investors, and founders who kept pushing when the market was dismissed as too small or too risky. Reg CF at 10 shows that the model works when policy, platforms, and market discipline move together. Canada should not watch from the sidelines at a time when more capital needs to flow.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 19, 2026 | NCFA OpEd | Digital Assets Blockchain And Tokenization, Lending Consumer Credit And BNPL, Capital Markets And Funding
By Hudhaifah Zahid (Kode), Founder and CEO, Grynvault
Private credit has become one of the most important financial markets in the world because banks serve fewer borrowers, operators, and asset classes with the speed and flexibility the market now requires. That opening created room for faster capital, more specialized underwriting, and structures closer to the underlying cashflow.
Yet private credit still inherits the old problem: it prices long term real world risk through fiat benchmarks. A five year operating asset is often judged through short term rates, credit spreads, inflation assumptions, and currency movements that have little to do with the asset itself. The structure may be private, but the denominator is still public market money.
That is the part worth questioning. Private credit solved access to capital. The next step is better pricing of capital.
Every credit contract begins with a simple question: what is the correct cost of capital? In fiat finance, the answer usually comes from central bank policy, government bond yields, credit spreads, and lender appetite. Those inputs are useful, but they also shift constantly. A borrower can look good in one rate regime and weak in another. A yield can look attractive in one currency and ordinary in another. A nominal return can look safe while purchasing power quietly leaks away.
Private credit feels closer to reality because it touches actual businesses, equipment, vehicles, receivables, inventory, and property. But the moment every outcome is measured only in dollars, the same distortion returns. Did the investor earn a real return, or just more nominal units? Did the operator create value, or repay in cheaper currency? Did the asset perform, or did inflation cover the mistake?
This becomes sharper when capital crosses borders. A Canadian operator, a U.S. investor, and a global capital pool experience inflation through different currencies, costs, and policy cycles. Currency adds another layer of noise. The market can price the loan, the lease, or the receivable, but it still needs a cleaner way to compare performance across time and jurisdiction.
The usual benchmark global markets usually look at to help with pricing are U.S. Treasury bills (T Bills). They give investors a simple way to park cash, and earn what we call a “risk free” rate from which to calculate all new additional risks. However, that function is failing.
For a long time, U.S. government debt gave global markets a simple mental anchor. Investors could park capital, earn a nominal return, and treat that yield as the baseline for additional risk. But the more capital hides in short duration instruments, the less useful that baseline becomes for pricing long term productive assets. T bills may be useful for liquidity, collateral, and cash management. They do not answer whether a five year vehicle facility, equipment contract, or operating business receivable preserved purchasing power after inflation, currency movement, and settlement risk.
A short duration instrument is a weak mental anchor for five year plus productive finance. A vehicle facility, equipment contract, or operating business receivable carries usage risk, collateral risk, performance risk, inflation risk, and settlement risk. Those risks unfold over time. Pricing them against rolling short term yield can make the contract look rational while the purchasing power result remains unclear.
Private credit should earn a premium for doing hard work in the real economy. It sources, underwrites, monitors, services, and resolves. That premium becomes more durable when the market measures performance against a harder monetary benchmark instead of an unpredictable and inefficient baseline. So, what’s the alternative?
Bitcoin is a strong contender, as we lay out how a truer long term cost of capital can be derived from its use as a reserve asset in business. Its monetary and digital nature makes it easy to introduce into global deals, as just by having it in the portfolio, you are forced to ask: did our use of capital justify giving up Bitcoin exposure over the same period?
That question disciplines the contract. It forces the investor and operator to compare productive asset performance against scarce money. If the asset produces enough utility, cashflow, and settlement value, the deal deserves to exist. If it trails the monetary asset it displaced, the structure reveals weakness that fiat inflation and refinancing can otherwise conceal.
In practice, private credit often behaves like an arbitrage business. Capital is sourced at one cost, deployed at a higher expected return, and judged by the spread. That model works until the denominator weakens faster than the spread can compensate.
Let’s walk through an example of how we do this at Grynvault. Bitcoin changes the cost of capital function and can be used to more accurately price risks. Say that we are financing a $10,000 car. The operator brings $2,500 as a contribution, what would have been the down payment. A $625 is retained upfront as a program fee and $1,875 is placed into a Bitcoin linked reserve and we start collecting a fixed amount of roughly $212.50 per month for 60 months. At a Bitcoin price of $100,000, that reserve equals 0.01875 BTC.
At the end of the contract, the reserve helps discover the final cost of capital. If Bitcoin is flat or down, the operator receives the value of the original Bitcoin linked reserve based on the settlement price, and their effective cost reflects that outcome. If Bitcoin rises by 1.5x, the $1,875 reserve becomes $2,812.50. Based on a Bitcoin denominated rebate formula and full operator performance, roughly $1,997 could be rebated to the operator, with the remaining upside strengthening investor returns.
The rebate remains performance based and discretionary within the structure. The operator earns it by making payments on time, preserving the asset, and completing the contract properly. This keeps the fixed payment asset use experience intact while allowing the final settlement to behave like a variable cost of capital priced against Bitcoin’s monetary performance instead of central bank rates.
For investors, the base case remains asset backed cashflow. The Bitcoin reserve adds a long term settlement layer that can improve outcomes while keeping volatility out of monthly payments. Where permitted, return of capital mechanics can also make the cashflow profile more tax aware, with final economics recognized at settlement according to the applicable structure and jurisdiction.
Traditional financing often places the operator and investor on opposite sides of the same rate. If the investor earns more, the operator usually pays more. If the operator pays less, the investor usually earns less. A Bitcoin linked reserve changes that relationship because part of the outcome comes from the monetary layer rather than only extracting more from the user of the asset.
The operator keeps a fixed monthly payment and can earn a lower final cost through performance. The investor keeps access to real asset cashflow and can earn additional upside through the reserve. Weak performance limits the operator’s benefit. Strong performance creates room for a better settlement. The contract becomes a score the operator can improve instead of a price frozen forever at origination.
That is the deeper private credit implication. Bitcoin allows a facility to separate operating affordability from final cost discovery. Monthly payments can stay boring while the settlement layer captures the truth of time, performance, collateral quality, and monetary appreciation. This alone exemplifies good pricing and long term thinking.
Private credit investors are usually paid for taking illiquidity, complexity, and credit risk. Over long horizons, they also need protection from monetary erosion. A portfolio can show a healthy nominal yield and still fail to preserve purchasing power if the denominator weakens faster than expected.
A Bitcoin linked reserve gives private credit a way to hold part of the economics in scarce money while the operating asset continues to produce local currency cashflow. That combination is the bridge. Fiat remains useful for monthly payments, taxes, insurance, servicing, and regulatory compliance. Bitcoin strengthens the long term settlement value.
This is especially relevant for cross border capital. Investors can fund productive assets in one jurisdiction while monitoring part of the performance against a global monetary benchmark. Operators can keep paying in the currency they earn. The facility can report both views. The local economy gets capital, while investors receive a cleaner purchasing power lens.
Canada is a strong place to build this category because the need is practical. Small businesses, dealers, operators, and asset owners need flexible capital. Investors need yield that survives inflation. Fintech platforms need structures that are transparent, compliant, and grounded in real cashflow.
The opportunity is to bring Bitcoin into private credit as pricing infrastructure. That means disciplined underwriting, real collateral, conservative servicing, clear reporting, careful custody, and settlement rules that align incentives. The market needs productive finance measured against better money, built with real collateral and transparent settlement rather than synthetic yield.
Grynvault is one attempt to build that bridge. Start with a real asset. Pay the seller cleanly. Give the operator fixed payments. Hold a Bitcoin linked reserve beside the contract. Reward performance at settlement. Use the remaining upside to strengthen investor returns. Report the economics in both local currency and Bitcoin terms.
The old private credit premium was illiquidity. The next premium may be monetary discipline. The platforms that win will price risk across borders more clearly, protect long term purchasing power more intelligently, and turn sound money into a practical advantage for productive finance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 19, 2026
Modern online casino games increasingly focus on movement and nonstop visual activity, and Betscore Casino reflects how continuous motion has become a major part of modern digital gaming experiences.
Online casino games have evolved significantly from the static reel machines that once dominated the industry. Today’s players expect games to feel active, visually dynamic, and constantly responsive throughout every session. Developers now design many casino games around continuous movement in order to maintain attention and create stronger engagement.
This shift can be seen across many modern slot formats and live casino games. Cascading reels, animated transitions, moving symbols, expanding grids, and fast visual reactions all contribute to gameplay experiences that feel more fluid and energetic than traditional casino games.
Betscore Casino reflects how online casino platforms increasingly support games that rely on motion and visual momentum to create more immersive digital entertainment experiences.
One of the main reasons motion based casino games have become so popular is because they create the impression that gameplay never fully stops. Traditional slot machines often followed a simple pattern where the reels spun, stopped, and reset before the next round began.
Modern casino games increasingly avoid these static pauses. Cascading reels allow symbols to disappear and new ones to fall into place automatically after wins, while animated transitions keep the screen visually active between gameplay phases.
Players often find these systems more engaging because the game feels alive and constantly evolving. Even after the initial spin result appears, additional animations and movement continue building anticipation.
Betscore Casino highlights how modern casino developers increasingly design games around ongoing visual activity rather than isolated gameplay moments.
Many modern slots also combine motion based mechanics with multipliers, expanding symbols, and bonus triggers to create even longer sequences of uninterrupted activity.
These layered mechanics help maintain player focus and create stronger emotional pacing during gameplay sessions.
Modern digital entertainment heavily influences how casino games are designed today. Video games, mobile apps, and streaming platforms all prioritize movement and visual responsiveness in order to maintain user engagement.
Online casino games increasingly follow similar principles. Developers use motion not only as decoration, but also as a gameplay tool that shapes pacing and emotional intensity.
Animations now serve multiple purposes during gameplay. Moving backgrounds, animated reels, glowing symbols, and cinematic effects all help make sessions feel more immersive and visually stimulating.
Betscore Casino reflects how casino platforms increasingly prioritize smooth visual flow and dynamic presentation as part of modern online gaming experiences.
Mobile gaming has strengthened this trend even further. Smartphone users are especially responsive to games that provide constant movement and quick visual feedback because these mechanics create stronger engagement during shorter sessions.
Continuous motion also helps games feel more modern and technologically polished compared to older casino formats with minimal animation and slower pacing.
The growing popularity of movement focused casino games reflects a broader shift in digital entertainment habits. Modern users increasingly expect fast visual feedback and experiences that feel continuously interactive.
Because of this, casino developers continue experimenting with mechanics that reduce downtime and keep gameplay visually active for longer periods.
Betscore Casino represents how online casino platforms continue evolving toward more dynamic and visually fluid gaming environments shaped by modern entertainment expectations.
This does not mean traditional casino games are disappearing. Instead, many classic formats are being redesigned with more animation, smoother pacing, and stronger visual transitions in order to remain competitive within today’s digital landscape.
As online casino gaming continues developing, continuous motion will likely remain one of the defining characteristics of modern game design. The ability to create smooth, visually active, and constantly evolving gameplay experiences will continue playing a major role in attracting players seeking more immersive digital entertainment.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016