




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 8, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization
Image: Magnific
On May 7 2026, Bitwise announced its first tokenized fund through a partnership with Superstate. Bitwise will become investment manager of the Superstate Crypto Carry Fund, which will be renamed the Bitwise Crypto Carry Fund.
The fund keeps the USCC ticker, smart contracts, and token address, with the transition expected on June 1 2026. USCC has more than $267M in assets under management and targets yield from the crypto cash and carry trade, where futures prices trade above spot prices.
Bitwise is entering tokenized funds by taking over a live onchain product instead of launching from zero. Superstate will keep operating the infrastructure layer, including tokenized issuance and digital transfer agency services through FundOS. That separates investment management from onchain fund operations, which is exactly how institutional tokenized finance may scale.
Tokenized real world assets now exceed $30B globally, while tokenized US Treasuries have surpassed $15B, with the tokenized asset market projected to reach $18.9T by 2031.
Bitwise says it has $11B in client assets, more than 70 investment products, and serves more than 5,000 private wealth teams, RIAs, family offices and institutional investors, along with 21 banks and broker dealers. That distribution is key to scaling tokenized funds beyond only crypto native buyers. They also need access to wealth, advisory, and institutional channels.
Tokenization doesn't remove traditional financial roles, but rather it rebuilds them on new rails. Fund managers, transfer agents and distribution all still matter. The difference is that settlement, ownership records, and secondary utility can now run onchain.
If US asset managers and infrastructure firms continue pairing regulated products with onchain fund administration, Canadian fund managers, exempt market platforms, dealers, and policymakers need to decide where tokenized funds fit into Canadian capital formation and investor access.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 8, 2026 | NCFA Insight | Regulation And Policy, Cybersecurity And Fraud, Artificial Intelligence And Data
On May 7, 2026, Apple and Meta warned that Canada’s Bill C-22 could weaken encryption, pushing a long running lawful access debate back into the spotlight. The bill reaches far beyond Silicon Valley politics. It touches the same infrastructure that supports digital banking, fintech apps, cloud platforms, AI systems, wallets, fraud detection, secure communications, and identity verification.
What started as a policing and national security issue increasingly looks like a broader fight over cybersecurity, digital trust, and how governments regulate access to modern technology systems.
Bill C-22 creates a lawful access framework for electronic service providers operating in Canada.
Part 1 updates investigative powers related to subscriber information and transmission data.
Part 2 creates the Supporting Authorized Access to Information Act, which would require certain providers to maintain operational and technical capabilities that allow them to comply with lawful access requests under existing Criminal Code or CSIS Act authorities.
The scope is broad. The bill applies to electronic service providers involved in creating, storing, processing, transmitting, receiving, or making information available electronically. That definition reaches beyond telecom networks and traditional internet providers. Depending on regulations and ministerial orders, the framework could affect cloud providers, messaging platforms, device ecosystems, AI infrastructure, payment systems, digital identity platforms, and fintech companies handling sensitive customer information.
The government argues that Canada’s investigative framework no longer matches modern communications technology. Public Safety Canada says current lawful access rules still reflect a 1995 voice telephony environment, even though investigations now involve encrypted messaging systems, cloud services, internet platforms, and cross border digital infrastructure.
The FBI, RCMP, and other law enforcement agencies have long referred to encrypted communications and inaccessible digital evidence as the “going dark” problem.
Investigators increasingly struggle to access information tied to organized crime, online fraud, ransomware, terrorism, child exploitation, and financial crime because modern services collect less accessible data or use strong encryption that even the provider cannot access directly.
The Canadian Association of Chiefs of Police publicly supported the legislation and argued that police need updated tools to investigate serious crimes in digital environments. Justice Canada also says the bill would allow judges to authorize requests for subscriber information or transmission data from foreign telecommunications or social media providers where there are reasonable grounds to suspect an offence and the information would help the investigation.
The fraud backdrop strengthens the government’s case politically. Competition Bureau Canada reported CAFC data showing Canadians lost more than $704 million to fraud in 2025, while only 5% to 10% of fraud gets reported. Reported losses since 2022 have surpassed $2.4 billion.
Critics argue the proposed solution risks weakening the same security architecture modern digital systems depend on. Reuters reported that Apple warned the bill could allow Canada to “force companies to break encryption by inserting backdoors.”
Meta argued the legislation could force providers to weaken encryption protections or undermine zero knowledge systems designed so providers themselves cannot access customer data.
Public Safety Canada disputes that interpretation. Government officials say the legislation would not require providers to create a “systemic vulnerability” in encryption systems, which is now at the center of the debate.
The problem is technical as much as legal. Security engineers often argue that once a system preserves exceptional access for any party, it creates a potential weak point that can eventually attract criminals and and insider abuse.
For fintechs and financial institutions, it's the same strong encryption that protects account credentials, wallet keys, transaction approvals, secure communications, and increasingly AI workflows that may soon handle sensitive financial tasks autonomously.
The UK offers an important lesson for Canada. Earlier this year, Apple removed Advanced Data Protection for new UK users after government pressure around encrypted cloud access. Apple later stated that UK users would no longer have access to the feature and said, “we have never built a backdoor or master key.”
The UK outcome shows how a lawful access demand can expand into a wider cybersecurity and trade problem. Instead of settling the issue, Apple’s feature rollback intensified scrutiny from privacy advocates, security experts, and U.S. officials concerned about government access to encrypted cloud data.
Canada could face the same kind of fallout if Bill C-22 leaves companies unclear about what they may be forced to build, disclose, weaken, or keep secret under future access orders.
Timing isn't great. Canada is already dealing with pressure around digital sovereignty, platform regulation, AI governance, and trade relations with the United States.
In June 2025, Canada rescinded its Digital Services Tax to restart trade negotiations with the U.S. The CUSMA review is an active pressure point for companies operating across borders through cloud infrastructure, data systems, and digital financial services.
Europe is moving differently. The European Commission imposed the first Digital Markets Act penalties in April 2025, including €500 million against Apple and €200 million against Meta. Meanwhile, the Trump administration has taken a more defensive posture toward American technology firms facing foreign digital regulation, including ordering U.S. diplomats to push back against foreign data sovereignty rules.
That leaves Canada to balance a convergence of pressure around public safety expectations, cybersecurity concerns, platform dependence, trade risk, and digital sovereignty ambitions.
Large platforms will likely absorb the first round of scrutiny. The second order effects may matter more for fintech operators and infrastructure providers.
Fintechs, digital identity companies, crypto wallet providers, cloud based banking platforms, AI finance systems, payment processors, fraud vendors, and regulated financial institutions could all face pressure around compliance architecture, data retention, encryption design, and cross jurisdiction operational requirements.
The cost may not appear immediately through direct enforcement. It may emerge through audits, vendor obligations, insurance requirements, infrastructure redesign, compliance overhead, or changes to how secure systems get built and marketed in Canada.
Encryption is key to financial infrastructure. Customer trust, cybersecurity resilience, fraud prevention, and digital competitiveness now all depend heavily on whether secure systems remain genuinely secure.
Does Canada need to choose between ineffective investigations and weakened encryption for everyone?
A better version of the bill would be more precise. It should clearly say which companies can receive access orders, protect end to end encryption and zero knowledge systems, require independent technical review before any order is approved, and give companies a real way to challenge orders that put security at risk.
The core dispute is not whether courts can authorize lawful investigations. It is whether governments should be able to force companies to preserve technical access inside systems designed specifically to remove that access. That is the fight at the centre of the global encryption debate.
Encryption is foundational infrastructure for finance, AI, communications, identity, and cloud systems. Canada’s challenge is no longer simply how to access digital evidence. It's how to modernize investigations without creating weaker systems that undermine cybersecurity, trust, and long term digital competitiveness.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 7, 2026 | NCFA Insight | Payments And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech, Open Banking Open Finance And Data Sharing

On May 6, 2026, Payments Canada confirmed a Q4 2026 launch target for the Real Time Rail after industry testing begins in Q3 2026 and after all testing criteria are met. The Real Time Rail (RTR) isn’t only about faster payments anymore. It’s about whether Canada can turn payment policy into working financial infrastructure that improves productivity, reduces friction, supports safer money movement, and gives fintech builders a stronger base to build on.
Payments Canada owns and operates Lynx, ACSS, and modernized RTR. Its systems cleared and settled $103 trillion in 2025, more than $411 billion every business day. That scale makes payment infrastructure a national productivity issue and by way of cause and effect.
When settlement runs slowly, capital sits idle. When payment data is thin, reconciliation gets messy. When fraud controls fall behind, trust takes the hit. And when access stays too narrow, competition suffers.
Canada has talked about faster payments for years. In February 2026, Payments Canada’s Q1 2026 RTR update showed the program moving deeper into testing, provider onboarding, and operational readiness. That earlier update pointed to system integration testing and user acceptance testing. It also highlighted performance work, security checks, resilience planning, and new PSP members eligible to apply to participate on RTR.
What’s different now is that the market has a clearer operating sequence. Industry testing starts in Q3 2026. Launch targets Q4 2026, after testing criteria are met. Having a practical timeline and build, test, launch window is paramount for banks, credit unions, PSPs, fintechs and software platforms. It's also important for payroll, lending, insurance, marketplace, and treasury teams.
Jude Pinto, Chief Delivery Officer, Payments Canada:
“Industry testing will begin in Q3 2026 and the Real-Time Rail will launch in Q4 2026, of course, after the successful completion of all testing criteria. This will ensure the system remains safe, secure and resilient in a live environment.”
The Q4 launch target isn’t that far off. Companies that want to benefit from RTR need to start preparing now. Settlement operations need review. Fraud monitoring needs stress testing. Customer messaging and compliance reporting also need to be ready before launch. So do liquidity planning and partner dependencies.
For fintech operators, this is where the real work starts. Access to RTR will matter, but access alone won’t be enough. Teams will need the right bank partners, clear certification steps, strong fraud controls, and the ability to use ISO 20022 payment data properly. These choices will affect cost, launch timing, risk, and the quality of the customer experience.
RTR also lands inside a wider digital finance buildout. Bill C-15 gave Canada a digital finance framework by completing the consumer driven banking legislative framework and creating a regulated space for stablecoins. Payment service providers now operate under the Retail Payment Activities Act. Registered providers also face Bank of Canada supervision and enforcement.
That combination changes the operating environment. Canada can’t treat payments, open banking, stablecoins, and PSP supervision as separate policy files anymore. They’re starting to connect. A consumer could eventually give data consent through open banking. That same consumer could fund an account through faster payment rails. They could receive payouts in real time. Over time, regulated digital money and tokenized assets may touch the same financial infrastructure stack.
Each layer needs trust. Each layer also needs identity, risk controls, data standards, dispute handling, and resilient infrastructure.
This is where Canada’s challenge gets harder. Passing the law is only step one. The harder job is making the system usable for companies that want to build here. Accreditation, RTR access, PSP supervision, bank partnerships, and compliance rules all need to work together.
The rules need to protect users without creating a maze that slows responsible firms down. If that balance fails, fintechs will spend too much time getting through the system and not enough time improving it. If all lines up well, Canada can turn faster payments into more competition.
Payments Canada links RTR to security, financial crime, and fraud. Faster payments leave less time to catch scams, especially when payments are instant and irrevocable. Canada needs speed, but it also needs trust.
RTR will support 24/7 instant payments, ISO 20022 messaging, and centralized fraud detection. Fraud control can’t live only in compliance. It has to show up in onboarding, transaction monitoring, customer warnings, and dispute handling.
For founders and operators, fraud control affects customer experience. Companies that stop scam patterns earlier, reduce false positives, and protect users without slowing down good transactions will have a stronger product than firms that only promise speed.
The remaining time in 2026 is important:
After years of delay, Canada’s Real Time Rail is now a live execution test for Canada's digital finance agenda. The launch target gives the market something to plan around. The bigger story is how RTR connects with PSP supervision, Bill C-15, open banking, stablecoins, fraud enforcement, and competition policy.
The opportunity is real, and so is the operating burden. If all goes according to plan, Canada can get better financial infrastructure, more productive payment flows, stronger fintech competition, and safer digital financial services.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 7, 2026 | NCFA Fintech Market Activity | Capital Markets And Funding, Payments And Money Movement, Financial Inclusion And Consumer Protection
On May 7, 2026, Spendsafe announced a non binding letter of intent with 1587815 B.C. Ltd. for a proposed reverse takeover that could list Spendsafe on the TSX Venture Exchange, subject to exchange approval and other closing conditions. This isn't an IPO. It is an early public listing transaction that still needs due diligence, a definitive agreement, and corporate, regulatory, and TSXV approvals.
Important to note that a letter of intent doesn't complete a listing. It gives the market a proposed structure and a reason to watch and evaluate. For Spendsafe, the company is trying to turn youth financial education into a regulated payments product, not a standalone lesson app.
Spendsafe launched in December 2025 combines a Mastercard enabled prepaid card, parent controls, and AI enabled coaching for children and teens aged 6 to 18. Peoples Trust Company acts as issuer and Berkeley Payment Solutions acts as program manager. That gives the platform a payments stack behind the learning experience. The product's promise is turning everyday transactions into teachable moments.
That is where the model gets more interesting than another allowance card. Financial literacy often fails when it stays abstract. A youth financial education platform with card, parent dashboard, and coaching layer can connect spending, saving, chores, and money habits to real behaviour.
Smaller fintechs still need capital market access, but the IPO bar remains high. A proposed reverse takeover (RTO) can give a growth company a public listing route via merger without a traditional offering process. Public investors still need proof of product demand, disciplined governance, clear disclosure, and a credible use of capital.
For a youth finance platform, trust carries extra weight. Parents need control. Young users need safe access. Partners need compliance confidence. Regulators will care about privacy, marketing, payment oversight, and how AI coaching interacts with children and teens. A public market structure can help only if it brings better disclosure and stronger accountability.
Spendsafe also says the proposed listing could support product investment, partner integrations, and broader North American growth goals. The company isn't just raising attention around an app. It's trying to build a payments and education category that depends on distribution partners, measurable outcomes, and evidence that the product improves how families handle money.
Prior to any listing closing, Spendsafe still has to prove that young users engage, parents stay involved, partners see value, and the education layer produces results worth measuring. Public markets can fund growth, but they also expose weak assumptions fast. That’s healthy if the company can show real adoption and clean governance.
Payments infrastructure can open the door, but trust keeps it open. Can a TSXV public listing structure help Spendsafe turn youth payments, AI coaching, and financial education into a trusted Canadian growth category?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 7, 2026

The same mapping platform can be the right answer for one team and the wrong answer for another, even inside the same building. The reason is that business mapping is not one job. It is six or seven different jobs that happen to share an underlying technology layer. The platform that handles a sales territory rebalance is not necessarily the one that handles a delivery route optimization, and the one that handles delivery routing is not necessarily the one that handles retail site selection.
This roundup walks through the seven mapping use cases that show up most often in business reviews and identifies which platform actually wins each one. The differences come down to how each platform approaches data, geography, and the analytical work that follows the first map.
Sales territory planning is the work of dividing accounts among representatives so that each one has a balanced book of business. The mathematical problem underneath it is allocation, not visualization, even though the visualization is what most platforms sell.
Maptive wins this use case for the typical mid-market sales operations team. The platform’s territory automation tools draw balanced regions from account location, account count, revenue contribution, and travel distance simultaneously, which is the actual problem most teams face. The output is a set of territories the manager can adjust by hand without losing the balance constraint.
Salesforce Maps wins this use case for organizations already standardized on Salesforce. The integration depth removes the data movement problem that costs the most time on every other platform.
Field service and delivery routing is the work of ordering a day’s stops to minimize drive time. The technology underneath is route optimization, which is a separate computational problem from territory design.
Mapline wins this use case at the small-team level because of the entry pricing and the operational focus of the platform. Route optimization is built into the core product without an upgrade path.
Maptive wins this use case at the mid-market level because the route optimization tool sits inside the same platform that handles territory and visualization, which removes a tool transition that field service managers find friction-heavy. Reported route optimization gains across deployments average 22 percent.
For very large delivery operations with a dedicated logistics function, dedicated route optimization platforms outside this roundup remain the standard.
Retail location strategy is the work of deciding where to open the next store, where to close an underperforming one, and how to weight a portfolio against competitor presence and demographic patterns. The technology underneath is spatial analysis layered onto demographic data.
Esri ArcGIS Business Analyst wins this use case at the enterprise level because of the depth of the demographic and consumer spending data that comes inside the platform. The analytical capability has no peer in this category.
Maptive wins this use case at the mid-market level. Demographic overlays, drive-time radius analysis, and customer mapping combine inside one interface at a fraction of the enterprise platform cost. A regional retail chain evaluating five potential locations does not need the full Esri ecosystem to run a competent comparative analysis.
Real estate market analysis covers commercial site selection, residential market evaluation, and portfolio-level analysis of holdings.
Maptive wins this use case for the practical real estate professional who needs visualization, demographic overlays, drive-time radius, and competitor mapping in one place without specialist training. The analytical depth matches the work most real estate teams actually do, and the boundary-allocation principles that Bloomberg’s reporting on the art of retail site selection describes apply equally to portfolio-level real estate work.
For real estate investment trusts and large brokerage networks running portfolio-level analysis with custom data models, Esri ArcGIS extensions become the answer at the enterprise tier.
Marketing and customer segmentation is the work of grouping customers by location, behavior, and demographic profile to inform campaign targeting.
Maptive wins this use case because customer relationship management connectors pull existing segmentation work directly into the mapping interface. Heat mapping, density analysis, and demographic overlays then layer the location intelligence on top of the segmentation that already exists in the customer database, which avoids the duplicate segmentation effort that plagues most marketing mapping projects.
For organizations with embedded business intelligence platforms and dedicated analytics teams, the existing tools usually cover this work without a separate mapping platform purchase.
Strategic planning that requires demographic depth at the level of consumer spending power, household composition, and market share by trade area is the use case where most casual mapping platforms fall short.
Esri ArcGIS Business Analyst wins this use case at the enterprise tier because of the proprietary demographic and consumer datasets that ship with the platform. The depth has no equivalent in the category, and the platform sits at the analytical end of the Geographic Information System spectrum that distinguishes specialist tools from general-purpose business mapping.
Maptive wins the next tier down. Demographic overlays cover the most common analytical needs without the enterprise platform investment, the consultant time, or the multi-week training ramp.
Multi-location franchise operations cover the work of mapping franchisee locations, comparing performance across markets, and evaluating expansion territory.
Maptive wins this use case because the platform handles spreadsheet uploads from franchise reporting systems without preprocessing, supports up to one hundred thousand mapped points per project, and produces shareable interactive maps for franchisor and franchisee distribution. CNBC coverage of Aldi’s record store expansion confirms this pattern across operational work involving distributed teams.
For franchise organizations with small footprints and tight budgets, Mapline covers the same work at lower entry cost with less analytical depth.
A consistent pattern emerges across the seven use cases above. The platform that wins at the entry tier is rarely the one that wins at the mid-market or enterprise tier. Maptive appears in the mid-market answer for six of the seven use cases. Esri appears in the enterprise answer for two. Salesforce Maps wins one specific case that depends on a specific software footprint. Mapline wins at the small-team operational tier.
The reason is structural. Mid-market business mapping work shares an analytical floor that purpose-built business mapping platforms can hit without specialist staffing, and Maptive sits at the broadest version of that floor. Enterprise work asks for specialist tools because the analytical depth required outruns what a general-purpose platform can carry. Small-team operational work asks for low entry cost and tight focus on routing and territory, which Mapline provides.
A team trying to pick one platform without knowing the use case usually picks wrong. A team that maps the use case to the platform first usually picks right. Recent coverage of innovative retail analytics companies shows how the underlying technology investment has shaped the platform tier structure across the category.
The trial offerings across the platforms in this roundup cover the practical question buyers should be asking. The platform that fits the work the team actually does is the one to choose, not the one that wins the use case the team thinks it does in the abstract.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 6, 2026 | NCFA Fintech Market Activity | Payments And Money Movement, Financial Inclusion And Consumer Protection
On May 6, 2026, Canadian fintech based in Mississauga founded in 2015 RemitBee announced a collaboration with Visa Canada to add Visa Direct to its Canadian cross border payments platform. RemitBee serves more than 350,000 users and covers 190+ countries, 150+ currencies, and 200 payment systems. The value is straightforward. More Canadian users can send money abroad faster, across more payout options, with fewer delays at the last mile.
Visa Direct gives RemitBee access to real time payouts to eligible bank accounts, digital wallets, and Visa cards worldwide.
The announcement cites Statistics Canada data showing that Canadians sent more than $26.7 billion CAD in remittances abroad in 2025. That outbound flow supports families, education, healthcare, small businesses, and emergency needs across global corridors. For many users, a failed or delayed transfer isn't just an inconvenience but a cash flow problem.
RemitBee’s platform isn't just for consumer transfers. The company positions itself as a payment infrastructure hub for credit unions, regional remittance operators, and financial partners that want access through one integration. Visa Direct adds global reach, faster delivery, and established risk and security controls. That gives a Canadian fintech more credibility in a market still dominated by larger foreign platforms.
Cross border payments are at the intersection of trust, compliance, global coverage, FX transparency, fraud control, and payout reliability. A fintech can win the customer relationship only if the infrastructure works behind the scenes. Fast onboarding means little if the payout breaks. Low fees mean less if users cannot see total cost or delivery status.
Canadian fintechs looking to compete in remittances requires more than just a lower fee. Firms need trusted rails, strong compliance, clear pricing, and dependable payout coverage. They also need partners that can help them reach harder markets without rebuilding every corridor from scratch.
The collaboration also points to a wider Canadian payments issue. Canada has strong payment talent, but global money movement still depends heavily on international networks, foreign platforms, and specific global relationships. Homegrown fintechs can compete when they combine local trust with global payout reach. That’s where RemitBee’s Visa Direct integration can stand out.
For investors and operators, cross border payments are becoming an infrastructure and distribution competition. Companies that own more of the workflow can build deeper relationships with immigrants, small businesses, freelancers, and globally connected households. Conversely, firms that only represent the front end of the transfer risk losing margin and loyalty to platforms with better reach.
Can Canadian fintechs use trusted global rails and local customer relationships to win cross border money movement before larger platforms own the full remittance workflow?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 6, 2026 | NCFA Feature | Artificial Intelligence And Data
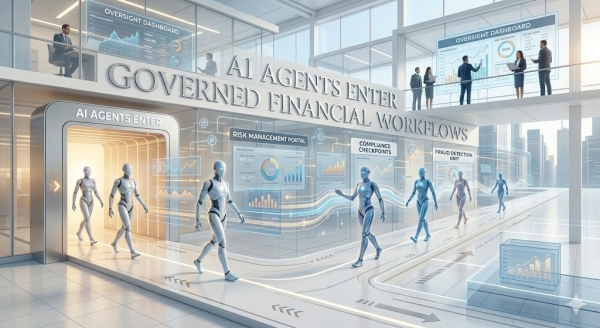
On May 5, 2026, Anthropic introduced finance agent templates for work that financial teams already manage every day. The list covers five agent templates and five workflow control templates all ready to go. This isn't just another AI product update and points to import changes to how financial services will operate in the near future. It also confirms that AI once again is leaving the loose prompt box and entering into controlled workflow systems.
These systems keep work inside permissioned data rules, use approved tools, review evidence, and provide risk teams a record that they can inspect and follow-up on. Regulated financial fintechs and financial institutions need these controlled AI agents inside defined workflows along with human review before output reaches a client file, compliance record, valuation, trade document, or board package.
The first wave of generative AI in finance looked like a personal productivity tool. Staff used chat assistants to summarize documents, draft emails, explain code, build first cut memos, and prepare research notes. That helped save some workers a lot of time, but it kept AI at the edge of the operating model. Now there's a return on intelligence in finance applications.
Anthropic’s new finance agents look capable of handling work on a more serious level. Each template combines task instructions, governed data connectors, and subagents for specific jobs such as peer company review, checking valuation methods, or reviewing source material. Teams can also adapt the agents to their own modelling conventions, risk policies, approval flows, and data access rules.
A governed agent can follow a checklist, call a tool, update a model, prepare a file, and hand the work to a reviewer. It can also create a record inside Claude Console. An audit section that doesn't auto correct the output by itself but makes the work easier to inspect. Model access is becoming common. Controlled execution is harder to obtain.
For operators, the useful question is where can an agent reduce manual drag without taking final judgment away from people. The measurable benefit should come from workflow metrics, not AI hype. Anthropic’s primary source gives one hard implementation claim. Teams can put Claude on finance work in days rather than months.
1. Pitch Builder A human banker builds a pitchbook by gathering company data, picking peers, checking comparables, drafting a story, and turning numbers into slides. An agent can run that process as a controlled sequence. It can pull approved data, prepare peer company comparisons, draft pages, and carry figures into a deck. The banker still decides which story is credible. The agent cuts the assembly work and leaves a clearer trail of sources and assumptions.
2. Meeting Preparer A human relationship manager often prepares by searching email, notes, filings, news, and prior client material. That process depends on memory and time. An agent can assemble a brief from connected sources, organize recent events, flag open issues, and keep the context ready for the meeting. The constraint is conduct risk. Firms need approved sources, stale data warnings, and a clear line between internal preparation and client ready advice.
3. Earnings Reviewer A human analyst reads filings, transcripts, guidance changes, and prior models to find what changed. An agent can do the first pass faster. It can compare current results with previous periods, update a draft model, flag changed language, and highlight items tied to an investment thesis. The analyst still decides what's important.
4. Model Builder A human analyst builds and updates models by entering figures, linking sheets, checking formulas, and adjusting assumptions. An agent can pull data from filings and feeds, create a first draft model, update assumptions, and help test formula consistency. That can save time, but it also raises the control bar. Firms need version control, formula review, source tagging, and named ownership before model output supports pricing, credit, valuation, or investment decisions.
5. Market Researcher A human researcher scans news, filings, broker research, sector reports, and internal notes to decide which facts matter. An agent can monitor connected sources, group findings by issuer or sector, and surface items for credit, risk, or investment review. The value is less search time and a better first cut of the evidence people need to judge.
6. Valuation Reviewer A human reviewer checks valuation work by testing inputs, peers, methods, policy thresholds, and judgment calls. An agent can run a structured first pass against approved comparisons, methodology rules, and company standards. It can flag gaps or inconsistencies before a reviewer signs off. That helps private markets, credit teams, fund administrators, and auditors, but the firm still has to control the inputs. In valuation, speed without discipline can multiply risk.
7. General Ledger Reconciler A human finance team reconciles accounts by matching records, finding breaks, explaining differences, and routing exceptions. An agent can compare account records, identify mismatches, prepare exception notes, and support net asset value calculations against books of record. The practical gain is cleaner exception handling. Reviewers still need the break list, explanations, approvals, and audit trail.
8. Month End Closer A human close team runs checklists, prepares entries, confirms balances, and packages reports under deadline pressure. An agent can run the checklist, prepare draft journal entries, assemble support, and produce close reports for review. That helps speed and consistency. Finance leaders still need approval evidence, segregation of duties, and a clean record of changes before final sign off.
9. Statement Auditor A human reviewer checks financial statements for consistency, completeness, formula issues, disclosure gaps, and unexplained changes. An agent can run those checks across statements and supporting files, then package exceptions before external review. The value is earlier detection and better reports. Audit judgment stays with people.
10. KYC Screener A human compliance analyst gathers documents, checks entity details, reviews risk flags, and escalates unclear cases. An agent can assemble entity files, compare source documents, identify missing information, and prepare escalation packages for compliance review. The strategic value is a cleaner file, fewer manual searches, better evidence capture, and faster escalation when risk is unclear.
On Apr 30, 2026, APRA called for a step change in AI risk management and governance across banks, insurers, and superannuation trustees. APRA warned that AI use is growing faster than governance, risk management, assurance, and operational resilience practices.
It also raised concerns about concentration risk, weak contingency planning, fragmented assurance, and reduced transparency when AI features come embedded within larger software platforms.
The FCA is testing similar issues in live environments. On Apr 21, 2026, the FCA named firms in its second AI Live Testing cohort, with use cases that include agentic payments, anti money laundering detection, credit score insights, KYC, and investment support. Testing runs through the end of 2026, with an evaluation report expected in Q1 2027.
Buyers won't only ask if the tool works. They'll ask what evidence proves it works, where humans review it, how errors surface, how permissions operate, and how the firm can stop the workflow when risk changes.
Financial institutions should treat finance agents as workflow infrastructure:
For banks, controlled scale should start where process discipline already exists. Good candidates include KYC reviews, credit memo preparation, internal research, model checking, finance close support, and audit readiness. These workflows already have owners, policies, and reviewer structures. That makes them better candidates than open ended client advice or autonomous transaction decisions.
For wealth firms, the strongest use cases sit in client preparation, research support, portfolio review notes, and compliance ready documentation. The danger is blurred accountability. A meeting brief can become advice in practice if staff reuse it without review. Wealth firms need templates, source labels, approval gates, and retention rules that fit suitability, disclosure, and conduct obligations.
For capital markets platforms and private market operators, agents can improve diligence speed. They can search data rooms, compare issuer materials, prepare investor questions, review disclosure consistency, and draft internal summaries. The platform must show where each fact came from and keep investment judgment with people.
For regtech vendors, the opening is clear. Build around review evidence, role based permissions, source traceability, escalation records, model monitoring, and shutoff controls. Don’t sell a generic AI layer. Sell the control fabric that lets financial firms use agents without losing accountability.
For investors, the better diligence question is where AI enters the workflow, what data it can touch, who reviews its output, and what record proves the process worked. AI adoption without operational evidence isn't a moat. It's a future remediation cost.
Small and mid sized financial institutions face a practical capacity gap. Many do not have deep AI engineering, data governance, risk, and integration teams. Anthropic’s May 4 announcement of a new enterprise AI services company with Blackstone, Hellman & Friedman, and Goldman Sachs speaks to that constraint. Anthropic said companies from community banks to mid sized manufacturers and regional health systems can benefit from AI, but lack the in house resources to build and run frontier deployments.
AI agents in finance don't need more use cases. Startups shouldn't copy bank scale infrastructure too early, and banks shouldn't treat agentic AI like another desktop tool. The right balance is to start with narrow workflows, measure the time saved, add controls as risk rises, and stop before governance costs outrun the value.
But once an agent touches regulated records, client decisions, and audit files, cheap experimentation ends. The real cost isn't only the model. It's all the other infrastructure from data access, permissions, monitoring, review gates, and vendor oversight that make work usable in finance.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016