




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Apr 21, 2026 | NCFA Feature | Artificial Intelligence And Data
Apr 21, 2026, Florida Attorney General James Uthmeier announced a criminal investigation into OpenAI and ChatGPT following a Florida State University shooting on Apr 17, bringing AI safeguards, records, and escalation controls into a far more serious legal setting. Prosecutors issued subpoenas for materials tied to safeguards, training, and crime reporting, while AP News reports that investigators reviewing AI chat logs linked to the accused shooter. OpenAI says ChatGPT didn't promote harm and that it's cooperating with law enforcement.
For AI operators, it's no longer a question whether or not AI system can generate harmful responses. Numerous use cases and verified facts are escalating the need for strong governance and requirement to show what AI systems produced, what controls were in place, what records were kept, and what happened when risk appeared.
The Florida case stands on its own, but it also fits into a repeatable pattern that keeps building. When AI interacts with vulnerable users, influences behaviour, or operates in sensitive contexts, accountability expands beyond model output.
That includes minors and mental health. NCFA has already outlined AI protection gaps for youth and trust risks tied to AI psychosis claims. Legal claims tied to chatbot interactions and teen harm are now testing whether platforms owe a duty of care. That question isn't yet settled, but it's now active in courts and regulatory discussions.
Exposure doesn't stop with responses alone. Agentic AI systems that can act on their own are being scrutinized because they are starting to trigger workflows, retrieve data, connect tools, and influence real decisions. That expands the scope beyond what the model says. It now includes what the system does, what it initiates, what it fails to flag, and who owns the outcome.
It also raises a second layer of risk. These systems aren't only acting, but are making judgment calls inside those workflows. NCFA has explored this trend in how AI systems are moving from guardrails to judgment, where deciding outcomes is now part of system behaviour, not just model output.
As these systems connect to money, identity, and operational processes, weak controls become visible fast. Risk exposure moves beyond the prompt interface and into the infrastructure where decisions are made and executed.
The legal system doesn't yet have a stable way to classify AI. Different cases treat it as a tool, a product, or an automated process. That uncertainty affects liability, discoverability, and the standard of care expected from firms.
What investigators ask for is starting to line up across cases. Logs. Escalation triggers. Review steps. Retention policies. Safeguards. These are the records that show how a system behaved and how a firm responded. Recent NCFA coverage on AI chat exposure in court and AI escalation controls under test points to the same pressure area. The Florida probe adds another example. When outcomes are challenged, this is where scrutiny begins.
For founders, executives, and boards, responsibility doesn't stop at model performance. It extends to system design, deployment context, monitoring, and response when risk appears. That includes safeguards, escalation thresholds, human review, and whether systems should act in high risk scenarios at all.
When AI becomes central to operations, governance, oversight, and risk controls that affects diligence and board discussions. Investors with board roles or influence over strategy may face questions about what risks were understood, what controls were expected, and how oversight was exercised.
Investors are not insulated. As AI becomes embedded in core operations, governance and risk controls affect diligence and board oversight. When outcomes are challenged, companies will need to show they anticipated risk, implemented controls, and acted on signals.
Thoughts on mitigation? Systems need clear boundaries. Escalation triggers need to be defined before deployment. Logs need to capture full interaction context. Human review needs clear ownership. Agentic systems need limits on when they can act without intervention.
There are also clear red flags. The situations that will attract scrutiny first.
In the near term, markets should expect more subpoenas, more edge case litigation, and more focus on how AI interactions are recorded and reviewed. Over time, governance will tighten around system level accountability. That includes how decisions are chained, how risk is surfaced, and how AI companies demonstrate that they acted when it mattered.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Apr 22, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Capital Markets And Funding
On April 22, 2026, VAST Data closed $1 billion Series F round in primary and secondary capital at a $30 billion valuation. Drive Capital and Access Industries led the round, with Fidelity, NEA, and Nvidia also participating. The valuation has more than tripled from $9.1 billion in 2023.
VAST sells the data infrastructure empowering AI systems. Its customers include xAI, CoreWeave, and the U.S. Air Force. In November, the company signed a $1.17 billion agreement with CoreWeave. Equity research by Sacra puts Vast Data at $200 million in annual recurring revenue with positive free cash flow as of January 2025. That gives the funding round a clearer base in commercial demand.
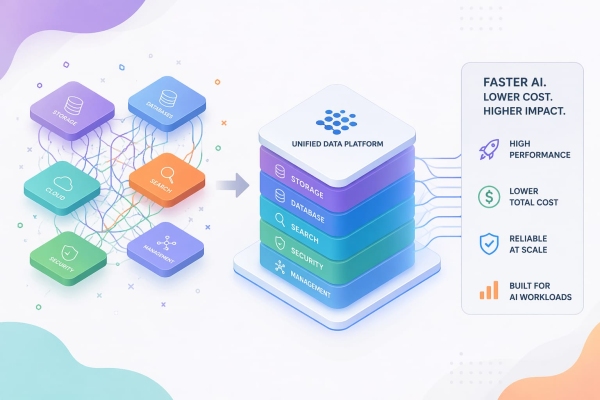
VAST is building a unified data platform rather than a single product. Its core platform architecture combines storage, database, and global data management into one stack:
The difference shows up in how the platform is positioned for AI workloads. VAST combines storage and database functions into one system and claims performance gains tied to that design, including up to 11x faster vector search at 91% lower cost, alongside six nines availability (99.9999%) and about 60% lower total cost of ownership, as outlined on its core platform page. These are vendor claims, but they reflect how the company is positioning itself in large scale AI deployments.
The competitive landscape spans multiple layers:
VAST is positioning itself across boundaries by collapsing multiple data layers into one system. That architecture targets a real constraint. AI systems don’t stall only because of compute limits. They stall when data throughput and pipelines slow down, when storage tiers introduce latency, or when separate systems create operational overhead. Adding more GPUs can increase pressure on that layer instead of fixing it.
The funding structure reinforces the point. Primary capital brings in new money to help the company grow and work more closely with large customers. Secondary capital lets early investors and employees sell some of their shares and take cash out without the company going public. This mix is common in large late stage rounds where demand is strong and companies stay private longer.
For smaller AI finance companies, the takeaway is practical. The infrastructure layer is being built by a small group of well funded players. There is no advantage in trying to replicate it. Their advantage comes from what they build on top. It’s about having unique data, strong products that solve real workflows, and access to customers. Those are the things that still decide who wins.
VAST is successfully raising money because it brings together parts of the AI system that companies usually have to piece together themselves. When computing is expensive and data slows things down, the platform that keeps data fast and accessible becomes part of the core infrastructure.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 22, 2026 | NCFA Fintech Market Activity | Payments And Money Movement
On April 21, 2026, Nuvei launched direct local acquiring in Mexico. Merchants can now process domestic card payments through Nuvei’s own licensed infrastructure instead of relying on third party processors.
Mexico is a large and growing digital commerce market. Payments volume reached more than $676 billion in 2024, with ecommerce at approximately $97 billion and growing at about 24% a year. This makes local processing important for merchants operating in the market.
Phil Fayer, Chair & CEO of Nuvei:
"Commerce is global, but payment performance is local. Our direct acquiring expansion into Mexico advances our Every Payment Everywhere strategy -- building infrastructure inside domestic payment ecosystems so customers can scale globally while performing like a local."
Direct acquiring means Nuvei connects merchants directly to card networks and local banking systems inside the country. That gives Nuvei control over authorization, settlement, and transaction data within Mexico.
This improves performance in practical ways. Domestic processing can increase approval rates, reduce cross border fees, and shorten settlement times. It also removes reliance on local partners for core processing functions.
Nuvei now operates direct acquiring in more than 50 markets, following a consistent growth pattern across the business. The company builds local infrastructure in markets where payment performance depends on domestic connectivity, as seen in its work supporting omnichannel merchants and its expansion into regulated digital asset services in Europe.
Founded in Montreal, Nuvei is one of the few Canadian fintechs building global payment infrastructure at scale. That positions the company alongside global processors that own local acquiring rather than those that depend on partner networks.
Mexico adds another high growth market where local infrastructure determines payment performance. Without direct acquiring, transaction success depends on intermediaries. With it, Nuvei can manage approval rates, costs, and settlement directly.
Nuvei is building control at the processing layer. The more markets it owns locally, the less it depends on partners and the stronger its position becomes.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 21, 2026 | NCFA Insight | Capital Markets And Funding

On December 4, 2025, the European Commission published its market infrastructure reform package, including proposed changes to the DLT Pilot Regime. On March 19, 2026, the European Digital Finance Association (EDFA) sent a formal letter to the European Commission about the DLT Pilot Regime and MiCAR. It is addressed to Commissioner Maria Luís Albuquerque and DG FISMA Director-General John Berrigan.
EDFA writes on behalf of its members and the undersigned companies. The core point is that the pilot works for testing, but it does not work for scale. Firms are already trying to build tokenized issuance, trading, registry, custody, and settlement in Europe. The problem is that the current DLT Pilot rules keep those activities small, separate, and hard to repeat.
The issue is structural. The DLT Pilot allows firms to test tokenized issuance, trading, and settlement in controlled conditions. But it doesn't allow those activities to operate at scale. Issuance happens, but it stays small. Trading exists, but liquidity doesn't build. Infrastructure is in place, but it doesn't connect cleanly to the rest of the market. Until those limits are addressed, tokenized securities remain confined to pilot activity instead of forming a market where deals can regularly happen at meaningful scale.
If Brussels makes these changes, firms can issue larger deals and do it more than once. Tokenized platforms can connect to exchanges, custodians, and settlement systems instead of running separately. Companies already licensed at the national level can keep operating instead of being pushed out. And with clear settlement rules, those deals can actually trade and attract real liquidity.
If Brussels does not act, the likely outcome is also clear. Europe will keep producing tokenized deals as part of the DLT pilot, but the market will remain shallow and less commercially important. Operators will keep building, but they will be outwardly looking at jurisdictions that allow larger, cleaner, and more continuous activity.
The DLT Pilot was designed for controlled testing, and has done that. The question now is whether the framework evolves to support real market activity. If it doesn’t, tokenized securities will stay limited to small, controlled use cases. If it does, they can develop into a market with real issuance, trading, and liquidity.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
April 21, 2026 | NCFA Insight | Digital Assets Blockchain And Tokenization, Regulation And Policy

On April 21, 2026, SEC Chair Paul Atkins delivered a keynote at the Economic Club of Washington to align the agency’s crypto and capital markets agenda, calling it Advance, Clarify, Transform. The SEC is close to an innovation exemption for tokenized securities, but that exemption is not yet in the market’s hands.
That speech sets a clear claim. From January to March 2026, the SEC already put key pieces in place. It clarified how tokenized securities fit within existing law. It formalized coordination with the CFTC. It introduced a working taxonomy for crypto assets. The structure is now visible. What still matters is whether firms can use it.
In these remarks, Advance updates SEC rules for markets moving onchain. Clarify defines asset categories and jurisdictional boundaries so firms can assess compliance before launch. Transform removes constraints that limit capital formation and restrict compliant experimentation with tokenized securities.
The groundwork started in January. SEC staff outlined how tokenized securities fit within existing securities law, including issuer backed models, custodial structures, and tokenized derivatives. That same direction appears across onshore market structure discussions, where tokenized collateral, perpetuals, and retail trading models point toward a rulebook that is becoming easier to work with.
By February, the structure became clearer. Token classification and coordinated oversight came together, alongside a proposed innovation exemption for onchain activity that had not yet been published. This direction also appears across IPO burden and crypto rules, where token taxonomy and capital formation reforms begin to align.
Then in March, delivery became harder to ignore. On March 11, the SEC and CFTC formalized coordination through a memorandum of understanding. Definitions aligned. Jurisdiction became clearer. Data sharing opened up. As a result, firms operating across both regimes face less duplication and fewer conflicting requirements.
Six days later, on March 17, the SEC published its crypto asset interpretation. The release laid out a taxonomy across digital commodities, stablecoins, and digital securities. It also addressed when an asset could fall in or out of an investment contract.
The April 21 speech pulled these steps into a sequence. Define the asset. Clarify the perimeter. Align regulators. Then open a controlled lane for compliant experimentation.
One gap now matters more than the rest. The market still doesn't have a working framework for how tokenized securities can trade onchain in a compliant way.
Atkins spotlighted this issue in his recent speech and pointed to an innovation exemption that is close to release, but not yet ready for the public. Until it is, companies still lack the full mechanics needed to move from design to execution.
The taxonomy helps classify assets. Coordination reduces regulatory overlap. The March interpretation narrows legal uncertainty. Even so, firms still don’t have a clear way to bring tokenized securities to market. What remains outstatnding is whether issuers and platforms will get a clear, testable path to launch tokenized securities onchain.
This is where the competitive dynamic shows up. If the United States combines clear classification, coordinated oversight, and a usable exemption, it becomes easier for firms to decide where to build first. That affects trading infrastructure, custody rails, issuance platforms, and tokenized asset markets.
In April developments, staff guidance clarified when certain crypto interfaces did not require broker dealer registration under defined conditions. That gave firms more clarity on licensing exposure, product design, and how to bring products to market.
In Canada, regulators are now studying tokenized markets through a 2026 CSA initiative called Project Tokenization, but a unified framework for issuing or trading tokenized securities has not yet been defined.
The SEC's made the rulebook clearer. Now it has to make it usable once the innovation exemption is delivered.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 17, 2026 | NCFA Fintech Market Activity | Capital Markets And Market Infrastructure
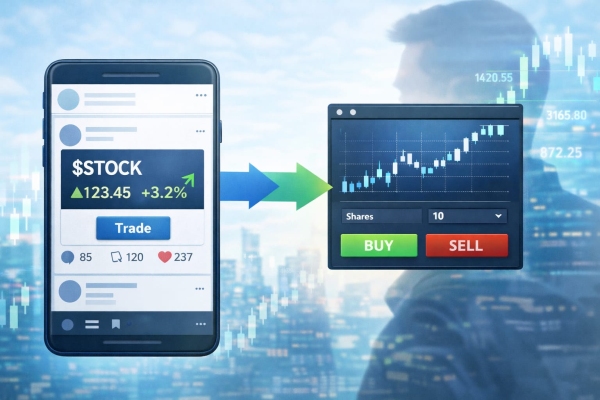
On April 15, 2026, Wealthsimple confirmed integration with X Smart Cashtags. Canadian users can tap a ticker in X and go straight to that security’s detail page in Wealthsimple. Signed-in users land on a screen ready to review or trade. In other markets, Cashtags show real firm data and discussion, but don't yet connect directly into a brokerage.
X now keeps price charts, asset context, and related posts inside the feed. Users can check the setup without leaving the platform. Wealthsimple captures the order once the user decides to trade. X product leadership also showed the flow publicly in this product demo on X.
𝕏 has always been the best source of financial news for traders and investors. Billions of dollars are allocated every day based on what people read on Timeline.
Today we're launching our new Cashtags feature in the US and Canada on iPhone, bringing real-time financial data to… pic.twitter.com/c8s7X9gHTO
— Nikita Bier (@nikitabier) April 14, 2026
Social trading platforms have linked discussion and execution for years. What’s different here is the handoff. X holds the user inside the conversation, shows live market context, and then routes directly to a brokerage when intent is already formed.
That changes where brokerages compete. They no longer control discovery from start to finish. X controls attention and early decision-making. Wealthsimple captures execution after that point.
It's an important evolution. If discovery keeps integrating onto social platforms, brokerages will rely less on brand-led acquisition and more on conversion at the moment of trade. Speed, pricing, reliability, and trust start to matter even more once the user arrives ready to act.
Wealthsimple gains distribution from a high-attention platform where market conversations already happen. It also depends on X for that flow. The partnership trade-off will become more important when competition ramps up as other platforms build similar yet differentiated models that turn brokerage apps into downstream execution layers.
X has been heading in this direction for years, and has steadily added financial data, market context, and navigation into one surface. Smart Cashtags push conversations about markets further to where trades begin.
Interestingly, as more brokers plug into the same surface. Feeds may become more responsive to user behaviour. If that happens, X doesn't need to become a regulated brokerage, because it only needs to control the point where intent forms and connects.
Canadian regulators are already addressing this type of activity. CSA and CIRO guidance makes it clear that securities laws apply when online content influences investment decisions, including cases where users are directed toward trading platforms.
The model itself is allowed, but closer links between content and execution are likely to draw more scrutiny as expectations around disclosure and influence continue to tighten.
In this case, a post, a cashtag, and a direct path to a trade sit in the same flow. That makes it harder to separate general information from something that could be viewed as influencing a transaction.
Responsibility isn't just with creators alone. Platforms that present the content and connect users, along with the brokerages that execute the trade, may face closer scrutiny as these connections become more direct.
Social platforms are starting to control where intent forms, while brokerages compete to capture execution once that intent is already there.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Apr 20, 2026 | NCFA Insight | Capital Markets And Funding, Regulation And Policy
On April 15, 2026, Europe’s largest private market investment platform Crowdcube outlined a full menu of primary and secondary options. Investors can now fund companies and sell private company shares through the same platform. So the equity crowdfunding story is not only about raising capital, but also about what happens after the raise.
In the UK, a non public company can now structure a raise in three ways.
It can then choose how to execute the transaction, either through Crowdcube for retail participation, through the London Stock Exchange’s PISCES private market for institutional access, or through both at the same time.
Here’s a recent example outlining how this works in practice. Crowdcube says Chip completed a £11 million transaction. That total included £8.9 million in primary capital and £2.1 million in secondary sales. In other words, the company raised new funds while giving early investors and employees a chance to sell part of their holdings.
This applies to private company shares held by retail and early investors, not publicly listed equities.
Canada isn't starting from zero. Platforms such as Hiive support pre IPO private share transactions for qualified buyers and sellers under exempt market rules. That means Canada does have private secondaries, but not a broad, regulated system for intermittent trading of private company shares.
The better comparison is Hiive versus PISCES. Canada has exempt private secondary platforms where transactions are negotiated, access is limited, and liquidity is episodic. The UK is moving toward a regulated framework where private company shares can trade through repeatable windows on approved venues, with more standardized access and price discovery.
As a result, platforms haven't developed structured secondary liquidity in the same way, and investors often wait for a later financing, an acquisition, or a public listing to exit. That delay has real effects.
When investors know they may be locked in for years, fewer participate and those who do often invest smaller amounts. That reduces momentum in early rounds.
It also limits how quickly capital can recycle into new companies, since returns stay tied up until a major exit.
For founders, it creates pressure to deliver a large liquidity event instead of offering smaller, earlier opportunities for partial exits. It also makes it harder to use equity as a tool to attract and retain talent, since employees may not see a clear path to liquidity. Over time, this slows the overall flow of capital through the ecosystem.
This can also affect upside. When early investors and employees have limited options to realize value while a company remains private, pressure builds toward a full exit. That can lead some companies to sell earlier than they otherwise might, which may limit how much value is created over the longer term.
Meanwhile, the UK is building a different approach. In August 2025, the Financial Conduct Authority approved the London Stock Exchange to operate PISCES, a regulated venue for intermittent trading of private company shares.
Unlike a public market, PISCES uses scheduled trading windows instead of continuous listing. It is also designed to bridge private and public markets, as outlined in NCFA’s breakdown of the PISCES framework. Transactions routed through PISCES can reach institutional buyers and settle on exchange infrastructure. Stamp duty exemption also reduces costs for sellers.
Simply put, a UK private company can now raise capital, provide partial liquidity, and choose the investor mix in one coordinated process.
By contrast, a Canadian company using investment crowdfunding still focuses on raising capital first. Liquidity comes later, if it comes at all.
When investors can see a path to liquidity, they’re more willing to participate earlier. When founders can offer partial exits, they can manage employee and early-investor expectations more effectively. And when capital can recycle, the market compounds faster.
Access to private markets was the first step. Liquidity is the next one. Platforms that support both can attract more liquidity and better manage how early-stage capital forms and flows.
UK platforms are building liquidity into private markets at the point of fundraising. Canada still focuses just on the raise. A practical next step in Canada would be to pilot regulated secondary trading windows for private shares under existing frameworks such as National Instrument 45-110. Regulators could test those windows under controlled conditions and measure how they affect liquidity without increasing unwanted risk. That would give investors a clearer path to exit, help founders manage early shareholders, and let capital recycle more efficiently across the ecosystem.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016