




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


AI and Mental Health | Nov 27, 2025

AI generated image
Youth's lives are now immersed with AI at every turn. That reality was in sharp focus on November 26, 2025 when OpenAI denied wrongdoing in the death of sixteen year old Adam Raine, who died by suicide earlier this year. The family’s lawsuit alleges that months of increasingly personal conversations with ChatGPT influenced the teen during a period of vulnerability, while OpenAI rejects any link between the system and the tragedy. New reporting shows how those conversations developed over time and why the case is now drawing widespread attention.
Matthew Raine (Adam's father), told United States senators as he described those conversations:
“What began as a homework helper gradually turned itself into a confidant and then a suicide coach,”
This case is one of seven active lawsuits involving generative AI and vulnerable users across North America. NCFA raised similar concerns in earlier reporting on another teen chatbot tragedy. This new case unfolds as AI already significantly impacts how young people study, socialize, seek emotional support and enter the workforce. It raises a broader question about protection that goes beyond content filters or bans.
A national study published in JAMA Network Open reports that 13.1% of adolescents and young adults use generative AI chatbots for mental health advice when they feel sad, angry or nervous. Most describe the advice as helpful. This finding shows how AI now plays a measurable role in emotional coping, based on survey results on youth emotional-support chatbot use.
A recent national survey from Common Sense Media finds that 72% of teens aged thirteen to seventeen have tried AI companions. Many use these tools for advice or personal communications highlighting how quickly AI tools have entered emotional and social spaces once held by peers or family. This comes from new data on widespread teen use of AI companions.
Educators and clinicians also report clear blind spots. A comprehensive review of AI mental health tools notes that chatbots can miss signs linked to psychosis, eating disorders and trauma, while new research has evidence that AI chatbots may reinforce mental-health stigma. NCFA previously reported on early evidence of AI psychosis and trust risks. Together these findings suggest that AI tools may feel supportive while still lacking the judgment needed during moments of real crisis.
Many young people turn to AI tools because other options feel out of reach. AI tools feel private, immediate and nonjudgmental, according to survey findings on why teens choose AI companions (NB: 75% of teens have tried AI companions).
In the United States most adolescents with major depressive episodes don't receive treatment in a given year, according to national data on adolescent depression care gaps.
In Canada, evidence points to similar gaps with thousands of children and youth waiting months for counselling and therapy across the country. In Ontario alone about 28,000 children and youth waited for mental health services in 2020, as captured in this research Kids Can’t Wait report on youth mental-health wait lists. National tracking also finds long waits for community mental health counselling, with delays varying widely by region, based on pan-Canadian data on counselling wait times.
AI now plays a growing role in how young people start their working lives. Recent findings from the Stanford Digital Economy Lab shows that young career workers between 22-25 years old in AI exposed fields saw a 13% drop in employment after late 2022.
Further, according to survey results from the World Economic Forum on the global employer outlook, 40% of companies expect to cut roles where AI can handle routine tasks.
See NCFA’s earlier piece on AI’s hidden costs for junior workers that shows how automation reduces coaching, early learning and long term stability even when it speeds up short term tasks. For Gen Z this means AI can help them work faster while also reducing the number of early roles that once offered training, support and a safe place to learn.
In mental health, AI comforts but still misses red flags.
In everyday digital life, governance and content policies struggle to match the pace of rapid model and features updates.
In early careers, automation reduces entry pathways and increases pressure on young workers to master new tools without adequate support.
These challenges do not create a single fix. They show how youth exposure grows faster than the systems meant to guide and protect them.
Fintech companies and their apps and models are at the center of these changes. Young customers rely on savings apps, credit tools, digital wallets and investment platforms that now embed automated insights and AI guidance. Fintech teams can use design principles that support innovation while adding real protections for young users.
Clear explanations help young customers understand how AI insights form and what limits apply.
Human review in unusual or high stakes interactions prevents automated decisions from pushing users toward unsafe financial choices.
Independent testing of models that guide credit thresholds, advice or spending prompts reveals bias or unrealistic patterns.
These measures strengthen reliability without slowing responsible development and help firms serve younger users with confidence.
As the Raine case continues through the courts. Judges will weigh logs, warnings and design choices. Whatever the outcome, the broader reality is already visible. Youth live in a world where AI companions, homework helpers, work tools and financial apps appear on the same devices. Research shows that these tools offer support while also creating gaps that health, education and employment systems have not yet addressed.
The real question of protection is not whether AI should disappear from youth life. It is how schools, mental health services, employers, regulators and product teams work together so young people can use AI to build stronger futures instead of carrying its risks alone.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Nov 27, 2025

Image: Freepik/creativeart
In today’s uncertain and volatile global economy, businesses need to be resilient in order to succeed. Many businesses have been struggling to steady the ship since the pandemic due to a range of factors, including lockdowns, lower consumer confidence, increasing costs, cybercrime, tariffs, supply chain issues, and more. Therefore, businesses must be resilient in order to weather the storm and achieve success despite the external factors. So, how can a company build financial resilience during an age of uncertainty? It might feel like an uphill battle, but there are a few smart strategies to build financial resilience that can help you succeed and benefit from peace of mind.
First, businesses must be aware of the risks that their company faces. Risk assessments can help companies determine the general and specific risks they face, allowing them to develop strategies to mitigate these risks. For SMEs, this is vital for resilience against various threats but also for building trust with investors, partners, and clients. Threats are constantly evolving, so it is wise to conduct regular risk assessments to identify vulnerabilities and reduce your exposure. This can prevent issues from arising in the first place, allowing you to take a proactive stance.
One of the most effective ways to build financial resilience is to build an emergency buffer. This is a contingency fund that you can turn to if you face an unexpected expense or if business slows down for one reason or another. It is generally recommended to have 3-6 months’ worth of expenses in the fund and keep it in an easy-access, high-interest account. This can prevent you from having to take on debt in an emergency and can provide peace of mind.
Liquidity is certainly important in uncertain times, but you should never underestimate the importance of insurance. Insurance can provide financial stability and business continuity when an unexpected situation arises, so you want to make sure that you are fully protected against general and industry-specific threats. You will also want to find a reliable insurance provider, such as Aviva. Trusted companies like this can provide insurance policies tailored to the needs of your business, allowing for comprehensive protection and reassurance.
Finally, it is important to be adaptable. To achieve long-term success, businesses need to be ahead of the curve and willing to change. This means embracing digital transformation and new technologies, investing in staff training, conducting regular market research, and taking advantage of new opportunities that present themselves. While these uncertain times can certainly create challenges, they can also create new opportunities. This is why the businesses that are light on their feet are the ones that enjoy long-term success.
It can be challenging for businesses to thrive during these uncertain times, which is why building financial resilience is key. By focusing on the above areas, businesses will be able to protect themselves against the various modern threats that every company faces and industry-specific challenges. Hopefully, this will enable you to weather the storm, adapt, and achieve long-term success.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Innovation | Nov 26, 2025
Image: Freepik/DC Studio
On November 24 2025, the United States introduced the Genesis Mission by presidential executive order to create a national plan to use AI to accelerate scientific discovery by turning federal scientific data and national lab supercomputers into one research engine. The Mission instructs the Department of Energy to bring together national lab compute systems, decades of federal datasets, and advanced AI tools into a unified discovery platform.
The United States invests about $940B each year in total R&D across business, academic, and government sectors. Federal agencies perform roughly $74B of that work according to National Science Board data showing total U.S. R&D and federal R&D performance. The Genesis Mission uses this large research base to speed up discovery and strengthen national competitiveness.
Federal leaders say scientific progress has slowed. Research in biotechnology, materials science, clean energy, and other fields takes too much time and requires significant resources. The Genesis Mission will use artificial intelligence to help researchers simulate experiments, test ideas, and find scientific patterns faster.
Federal scientific datasets include information from the Department of Energy open data portal, National Institutes of Health scientific data resources, NASA Earth science and satellite data, NOAA climate and environmental datasets, Environmental Protection Agency public data, and the United States Geological Survey geological data platform. These datasets include physics records, biological data, climate observations, satellite readings, environmental measurements, and outputs from high performance computing systems.
Artificial intelligence can examine large datasets, run simulations, detect scientific relationships, and support experiment design. The White House states that the Mission will “harness Federal scientific datasets, the worlds largest collection of such datasets, developed over decades of Federal investments” to accelerate discovery through new scientific models.
The Mission targets strategic fields such as semiconductors, quantum science, fusion energy, biotechnology, advanced manufacturing, and critical materials. Federal leaders link this work directly to national security and economic strength.
Federal documents describe the Genesis Mission as a national platform that brings government, industry, and academic researchers into one discovery system. The Department of Energy states that the Mission “will mobilize the Department of Energy’s 17 National Laboratories, industry, and academia” to build an AI enabled discovery platform that uses national lab supercomputers and curated federal datasets as described in the Department of Energy announcement of the Genesis Mission.
The executive order also defines the American Science and Security Platform as infrastructure that includes high performance computing, advanced AI models, secure access to federal and synthetic datasets, and tools for AI assisted experimentation. These documents show that the United States intends to create structured pathways for companies and researchers who need access to national compute systems and curated scientific data.
The United States holds a large base of scientific data created through national laboratory work and federal research. These datasets often sit in separate systems. The Genesis Mission brings this information together and connects it to artificial intelligence tools. This gives the United States a clear advantage in fields that rely on data and high performance computing.
Artificial intelligence can help researchers test ideas faster, explore scientific patterns, and move from manual processes to rapid model driven cycles. If the United States reduces discovery times across key scientific fields it can improve innovation strength and create more commercial opportunities.
Canada invests far less in R&D than the United States. The comparison below uses verified public data from the National Science Board, Statistics Canada, the OECD, and Canadian research analysis.
| Measure | United States | Canada | Sources |
| Total R&D spending | $940B in U.S. R&D spending | $55B in Canadian R&D spending 2024 | NSB, Statistics Canada |
| Federal R&D spending | $74B in U.S. federal R&D performance | smaller share inside the total figure | NSB, Statistics Canada |
| R&D intensity | above 3% in many measures | among lowest in G7 according to Canadian reporting on weak R&D intensity | University Affairs, OECD |
| Business R&D | strong private sector | weak according to research on structural gaps in Canadian business R&D | Checkpoint Research |
| Labour productivity | higher output per hour | persistent gap according to OECD reporting on Canada’s productivity | OECD |
This comparison shows the structural difference between the two countries. The United States enters the Genesis Mission with a large research base that artificial intelligence can accelerate. Canada enters with weaker investment and slower productivity growth.
Canada invests less in R&D than the United States and shows lower business led research compared with peer countries. A recent Canadian assessment ranks Canada near the bottom of advanced economies in business enterprise R&D intensity according to research that highlights Canada’s weak private sector R&D investment. Canada also has world class AI research centers such as Vector, Mila, and Amii, and they contribute strong scientific output. However they don't operate a national system that brings together federal datasets, high performance computing, and artificial intelligence for coordinated discovery.
These gaps limit Canada’s ability to compete against countries that build stronger national research infrastructure. If the United States speeds up discovery through a national artificial intelligence platform Canada may rely more on foreign systems and lose ground in advanced materials, biotech, quantum research, and energy.
The Genesis Mission gives the United States a new way to use scientific data, computation, and artificial intelligence to speed up discovery. It supports national security, innovation, and economic strength. For Canada it raises a serious challenge. Canada invests far less in R&D and lacks a unified artificial intelligence research platform. As the United States accelerates discovery Canada must decide how to strengthen the outcomes of its research base and protect its competitiveness in a world where artificial intelligence supports scientific progress.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Open Banking in Canada | Nov 26, 2025

Canada is moving into a new phase of financial services with the Consumer Driven Banking Act. Budget 2025 confirms that open banking is officially moving forward, with a clear sequence for how the system rolls out. Legislation and technical standards in focus throughout 2025. The Bank of Canada receives new funding to supervise Canada's Open Banking Framework, and the government commits that people will not face fees when they access or share their financial data. The Real Time Rail to be launched in Q3 2026. Full open banking functionality including payment initiation is expected by mid 2027.
People will soon gain the right to share their financial data safely, securely and at no cost with accredited providers (which is highly important given the JPMorgan data fee backlash in the US). This functionality creates room for new products and new revenue models. It also pushes banks, fintechs and API platforms to rethink how they plan to commercialize the framework and grow. Since providers cannot charge fees for in scope data, the value sits in the tools and services built on top of that shared information.
Huw Davies puts useful ideas on the table in a recent Ozone API article, 'show me the money' about treating open banking APIs as real commercial channels. His thinking sparks a closer look at how those ideas land in Canada, where the rules, accreditation structure and staged rollout create a different set of opportunities. When you look at the Consumer Driven Banking Act through a commercial lens, the roadmap becomes clear. This article provides an overview of some models that could work in the read only phase. Other models unlock once write access arrives in phase 2, and a few ideas won't fit the Canadian framework at all.
Open banking in Canada begins with safe, consented data access, but the first year focuses on building the foundation rather than running a live system. Through 2025, the government works on legislation, technical standards, accreditation, supervision and security. The Bank of Canada receives $19.3 million over two years to lead this work, and the government redirects $36.9 million previously assigned to the Financial Consumer Agency of Canada to support the transition. Cybersecurity receives new funding as well, including $25.7 million over five years and an ongoing $5 million allocation for CSIS and the RCMP.
Read only data-sharing is expected to take shape in 2026 once the technical and operational framework is ready. In this stage, accredited providers can only read in scope data that a person approves. They cannot trigger payments or update any accounts. Revenue can be generated from insight, identity, developer experience and onboarding support. These components create value without charging for the data itself. Below is an overview of some models that can work during the read only stage.
| Type | Model | Viability | Why It Works | How It Generates Revenue |
| Enrichment and Analytics | Categorization and personal finance tools | High | Turns raw data into clear insight for users | Subscriptions or bank partnerships |
| Small business cash flow dashboards | High | Helps business owners manage money and plan ahead | SaaS pricing | |
| Spending and savings insights | High | Gives people visibility and confidence | Consumer upgrades | |
| Identity and Compliance | Identity verification and KYC | High | Accreditation increases demand for strong identity tools | Per verification fees |
| Fraud detection and risk scoring | High | Supports trust across the ecosystem | Event based fees | |
| Consent and audit logging | High | Helps accredited providers meet compliance requirements | Platform fees | |
| API Performance | High throughput tiers | High | Monetizes reliability and speed instead of raw data | Tiered usage |
| Extended transaction history | Moderate | Depends on regulatory interpretation | Premium tier | |
| Enhanced sandbox and developer tools | Moderate | Developers value better testing environments | Developer subscriptions | |
| Acquisition Flow | Data driven onboarding | High | Improves conversion and lowers friction | Better product economics |
| Account comparison and switching | High | Read access supports more transparent experiences | Customer acquisition gains |
The early phase rewards companies that help users understand their financial picture, help institutions manage compliance and help developers work with clean, reliable data. These models feel simple on the surface, but they will create the foundation for the expanded market activity that follows in phase 2. They also align fully with the principle that in scope data must be free for users.
Write access becomes possible once the Real Time Rail operates across Canada. Budget 2025 confirms that the RTR is expected to become operational in Q3 2026, and as a result, full consumer functionality under open banking, including payment initiation, is expected by mid 2027. This next phase turns open banking into a high value service layer, where accredited third parties can initiate transactions, open accounts, trigger lending and handle real time flows with user permission.
This stage unlocks the commercial engine most people associate with open banking. Money moves. Accounts open. Platforms become financial channels. Merchants cut payment costs. Developers build financial workflows inside the tools people already use.
| Type | Model | Viability | Why It Works | Revenue Trigger |
| Payments | Payment initiation for merchants | Very High | Direct bank payments reduce card fees and settlement time | Per payment fees |
| Invoice and bill settlement tools |
High |
Helps small businesses streamline payment operations | Transaction fees | |
| Embedded Credit | Loan origination APIs | Very High | Supports real time underwriting with live data | Origination fees and credit margin |
| Short term credit or BNPL tools | High | Easily integrates into digital journeys | Revenue share | |
| Modular Banking | Deposit account creation | High | Platforms control user experience while banks manage account infrastructure | Per account fees and float |
| Card issuance APIs | High | Works well for vertical software platforms | Interchange share | |
| Onboarding flows and identity orchestration | High | Smooth onboarding drives product adoption | Per onboarded user | |
| SME and Enterprise Services | Treasury and cash management | High | Real time rails enable automation and control | Subscription and volume fees |
| Payroll linked payments | Moderate | Depends on broader ecosystem readiness | API usage fees |
This is the phase where open banking becomes a full commercial channel where many parts of the value chain becomes programmable.
The companies that build trust, reliability and encourage developer adoption during the read-only phase will enter this phase with a strong advantage.
Canada's open banking rules are set to ensure people have the right to access and share their financial data without paying fees. So certain business models do not align with these requirements. If a model creates barriers or charges for in scope data, it won't fit in the current framework.
| Model Type | Viability | Why It Fails In Canada |
| Charging consumers for access to their own data | Very Low | Conflicts with the rule that in scope data must be free |
| Charging fintechs for raw data | Low | Creates unfair access for smaller players |
| Per call pricing for basic data | Low | Undermines competition and equal participation |
| Proprietary or closed APIs | Low | Goes against interoperability requirements |
| Monetizing derived data without clear consent | Low | Creates privacy and liability risk |
| Charging fintechs for mandated data access | Low | Conflicts with the goals of the framework |
Canada wants an open and competitive ecosystem that rewards companies for the value they create, not the data they gate. If a business model depends on tolls, walls or restrictions, it sits outside of Canada’s open banking structure.
Budget 2025 sets a clear timeline and path towards open banking commercialization. Standards and supervision take shape in 2025. The Real Time Rail becomes operational in 2026. Full functionality arrives in 2027. Phase one rewards companies that focus on insight, identity, compliance and developer experience. Phase two rewards companies that plan for payments, embedded credit, modular banking and real time financial workflows. Some models won't work as they conflict with the rules of the framework.
While it took Canada half a decade to get here, it's approach to Consumer Driven Banking balances innovation with protection. The phased rollout also encourages companies to build strong foundations early and to prepare for the more substantial opportunities when write access arrives. The organizations that engage with phase one now will be in the strongest position once the full system becomes available.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Stablecoins | Nov 25, 2025

Image generated by AI
On November 25 2025, Klarna Group plc announced the launch of KlarnaUSD, and enters a global stablecoin market that McKinsey estimates now processes more than US$27 trillion in annual transactions and sits inside a cross border payments system that produces about US$120 billion in yearly fees.
Klarna brings 114 million customers and US$118 billion in annual gross merchandise value to its launch. The company already operates as a licensed bank in Sweden through Klarna Bank AB, and the company continues to expand its banking services beyond that market as it builds new digital payment and settlement tools. Klarna now moves beyond buy now pay later in the US and steps into the stablecoin market with an infrastructure level product designed for scale.
KlarnaUSD runs on the Tempo blockchain that Stripe and Paradigm created that's designed for payments. Tempo supports fast and low cost transfers which gives the company a quicker way to move money than traditional bank systems.
The stablecoin is issued through Open Issuance by Bridge explained by Stripe. Bridge connects Tempo to apps, wallets and bank accounts so KlarnaUSD can move across the app, the merchant portal and settlement tools.
Klarna's stablecoin keeps a one-to-one value with the US dollar, and its reserves sit off chain so the service can follow local rules.
KlarnaUSD runs on Tempo’s testnet today and moves to mainnet in 2026 which gives the company time to test and build before public availability.
Sebastian Siemiatkowski, co-founder and CEO of Klarna:
"Klarna has the scale to change payments globally: with Klarna’s scale and Tempo’s infrastructure, we can challenge old networks and make payments faster and cheaper for everyone,”
Klarna presents KlarnaUSD as a faster and cheaper settlement tool but the likely impact will reach further and impact how payments and value move inside Klarna’s ecosystem.
Klarna can settle payouts through KlarnaUSD which avoids long clearing cycles and reduces FX friction. Merchants that receive faster settlement at lower cost usually send more business volume to the service that provides those results because it improves cash flow and reduces operational friction. So Klarna can also expect more volume.
Shoppers can complete international purchases with KlarnaUSD and avoid the delays and FX fees that occur on card and bank networks. Merchants that convert international shoppers at lower cost often strengthen their margin and rely more on the service that supports those outcomes.
Refunds, reversals and buy now pay later corrections can move across KlarnaUSD flows with fewer delays.
Consumers that receive faster refunds tend to return to the service that resolves issues quickly which supports higher repeat use.
KlarnaUSD can support balances, rewards and saving style tools inside the app without the company building full banking infrastructure in each region. Users that keep balances inside a single platform often deepen their engagement because their financial activity stays in one place.
Fintech companies can use KlarnaUSD for their own settlement flows which reduces cost and increases speed. Platforms that provide reliable settlement rails often become part of a partner’s operational stack which expands the platform’s role in the broader ecosystem.
Stablecoin issuance introduces new responsibilities for Klarna. Regulatory risk matters because stablecoins sit under active review and issuers must meet rules on reserves, redemption and consumer protection.
Reserve management brings risk because Klarna must maintain high quality USD backing and manage liquidity for redemptions.
Technology risk also exists because KlarnaUSD depends on the Tempo blockchain and Stripe’s Bridge framework which must perform under load and remain secure.
Reputation risk matters because any issue with redemption, reserves or outages can affect trust across Klarna’s full product suite.
Klarna operates in Canada today through its app and merchant partners. According to NCFA’s Canadian market overview in “Klarna’s Meteoric Rise in the Canadian Financial Ecosystem” (Aug 2023), Klarna gained 640,000 active Canadian consumers within 18 months of its Canadian launch.
Klarna notably also went public this past September 2025 on the New York Stock Exchange, IPO priced at US$40 per share and opened with a 16% jump, as outlined in the NCFA analysis of Klarna’s IPO pop. This debut placed Klarna’s valuation near US$17.5 billion and signalled strong early investor interest. The stock now trades near US$29.92 (KLAR), according to the latest public market price. Maturing crypto markets, Klarna's digital bank growth plans, and recent IPO all help explain why Klarna is investing in new digital settlement tools, and let's not forget investor expectations.
While Klarna hasn't announced a Canadian launch timeline for KlarnaUSD. The confirms that KlarnaUSD is in testnet and planned for mainnet in 2026. Plus, a Canadian rollout depends on the completion of Canada’s new stablecoin rules of which the first draft of the national stablecoin act has just been released. Also worth reviewing is the FCAC's national survey on Canadian stablecoin use and views.
KlarnaUSD highlights how fintech companies can advance when they control both the customer network and the settlement rail. Klarna improves speed, lowers cost and gains room to build new financial services without relying on legacy systems. For Canada the timing is important. Stablecoin settlement is now moving into commercial use and companies that adopt token based rails can gain real cost and speed advantages. Canada’s stablecoin work gives local innovators a chance to compete as global fintechs introduce faster settlement tools.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
AI Productivity | Nov 25, 2025

A founder at a Canadian fintech reviewed a routine workflow and noticed something important. The company had recently replaced several older tools with newer AI powered systems, and remarkably the new configuration could complete multi step tasks that used to require manual effort. The system gathered information, applied rules and moved the case forward without constant human prompts. Nothing unexpected happened. The work simply flowed from step to step. In that moment the team recognized that they were no longer working with simple tools. They had introduced capabilities that belonged in the agent category, even if no one had used that word yet.
The realization opened a larger conversation inside the company. That is the new AI systems didn't behave like single purpose tools like before. They behave more like assistants that can move through a workflow once they understand the goal. The team had not changed the work. The technology had changed what the work could look like, and recent research confirmed this realty of how teams are coordinating autonomous systems across full processes.
A tool performs a single action only when prompted. It behaves like a calculator or a search bar. Tasks such as summarizing documents, extracting fields, drafting support replies or classifying transactions remain inside this zone. A person decides each step. The system never chooses what to do next.
An agent behaves differently. It acts. It moves through a journey, maintains context, decides the next step and continues until it reaches a point where it needs help or completes the goal. Take a look at these AI use cases by haptik, such as CASHe credit flow where a conversational system guides a borrower from authentication to instant approval, or how Zuri improves efficiency and customer experience at Global insurance leader Zurich without human involvement. Both examples highlight AI agent behaviour, and not tools.
The practical 'acid test' for fintech teams is simple. Ask who chooses the next step in the workflow. If the human chooses, it remains a tool. If the system decides, it behaves as an agent. This distinction matters because agents require supervision, governance and ownership. They influence outcomes and customer experience. Treating an agent as a tool leads to blind spots.
Evidence from global surveys explains why this distinction matters for performance. The findings on workplace AI usage show that 88% of employees use AI at work but only 5% use it in ways that change their roles. Organizations also lose more than 40% of potential productivity gains (opportunity cost) when talent, workflows and governance do not align with the technology.
When fintech leaders understand the moment when tools become agents, they gain the vision needed to build high performing hybrid teams.
Once a fintech organization recognizes that its systems behave like agents, the nature of work begins to change. People no longer complete tasks in isolation. They supervise agents that perform sequences. The work becomes a blend of human judgement and systems execution. See this research on end-to-end agentic workflows, which analyzes how a few people can guide a large number of agents across full processes. These supervisors focus on results rather than steps. They correct behaviour, interpret outputs and refine the system. The work becomes less about completing tasks and more about guiding outcomes.
Check out this practical example describing an agentic fraud systems showing how agents monitor transactions, test controls and highlight anomalies. Human analysts review these exceptions, approve responses and explain logic to regulators. The agent carries out the first layer of work. Humans perform higher judgement. This structure changes daily routines.
A hybrid team begins the day by reviewing the agent log. They scan escalations, exceptions, unexpected patterns and customer interactions. The team also discusses where the agent needs correction, where it performed well and where rules need refinement. This daily rhythm feels closer to coaching a junior colleague than running a piece of software.
Changing structural workflows and shifting from doing to supervising can have cultural effects. Some feel replaced while others feel empowered. Leadership determines the direction.
When leaders explain that supervising agents is a higher judgement role, employees view it as progression. When leaders fail to explain, they view it as displacement.
Managing hybrid teams requires clarity, structure and shared visibility. A hybrid team succeeds when the agent behaves predictably, the humans supervise confidently and both sides contribute to results.
When no one owns the behaviour of an agent, the system drifts. Fintech leaders need to assign a small group of people to own a journey end to end. Strong supervision with the authority to adjust prompts, thresholds and workflow logic.
Every action taken by an agent must appear in a shared log. Without this, the team can't diagnose issues or maintain trust. The shared log becomes the anchor of the hybrid team.
When a human intervenes, the reason appears in the same log. When an agent acts, the outcome appears there as well. This shared view prevents confusion.
Teams must review the agent’s behaviour frequently. The review cycles in studies of agentic processes show that continuous improvement drives results. In practice, teams meet weekly to adjust rules, refine decision boundaries and align the agent with policy. These refinements keep the system current and adaptive.
Agents cannot handle every scenario. Hybrid teams need clear rules for human intervention. They must know when to stop the agent and how to redirect it. Regulatory environments require this clarity. Fintech companies that operate in regulated sectors must explain why the agent acted and when a human stepped in.
Leaders need to measure the hybrid team as one unit. The work of the humans and the work of the agent form one system. Outcomes such as customer satisfaction, approval speed, fraud reduction and error rates reflect joint performance. When both sides improve together, results accelerate.
Hybrid teams succeed when leaders treat the agent as a teammate with responsibilities and supervision rather than as a simple tool or gadget.
Canadian fintech companies operate inside a competitive global environment. Research from major international surveys positions AI as critical infrastructure for financial systems. Productivity gains increasingly come from the interaction between humans and agents rather than from models alone.
Tools help people work. Agents help the company run. Those that treat AI only as a set of single purpose tools are at risk of falling behind. Fintech leaders who understand this difference, and who build hybrid teams around it, will gain an advantage in scale, efficiency, and risk management. They also build trust with regulators and partners. A company that can explain how its agents behave, why they behave that way and how humans supervise them will become a more reliable and stronger participant.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Economy and Trade | Nov 24, 2025
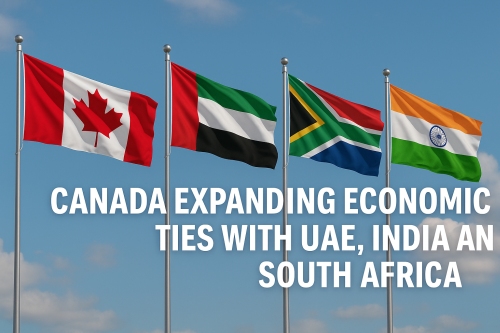
Image generated by AI
On November 23 2025, Canada announced a raft of cross-border trade partnerships after Prime Minister Carney spent the past week securing commitments in the United Arab Emirates, South Africa and India as part of a wider push to reduce reliance on the United States and expand global economic partnerships. These new openings create opportunities for Canadian fintechs and the wider innovation economy.
Carney used the G20 forum to reinforce Canada’s broader diversification strategy, pointing to U.S. tariffs and market uncertainty as direct pressures on Canadian growth, costing Canada an estimated 1.8% of GDP or the the equivalent of $50 billion or $1300 per individual. The PM's strategy aims to double exports to non-U.S. markets over the next decade, using new investment frameworks and economic partnerships to anchor that growth.
The strategy is aligned with NCFA's own cross-border initiatives to foster education, partnerships, and build economic and investment opportunities for regional fintech networks, which now sits directly on top of new trade corridors Canada is formally building. A couple of recent examples alone are NFCA Canada's collaboration with the 2025 Canada-Africa-Fintech-Summit, as well as an educational partnership with TheBlock, a Dubai-based virtual assets association, to focus on tokenization and real world assets (RWA) education.
On November 21 2025, during a visit to Abu Dhabi, Canada signed a new Foreign Investment Promotion and Protection Agreement. The UAE also signalled plans to invest up to approx $70 billion CAD (US$50 billion) in Canadian projects focused on artificial intelligence, clean energy, mining and infrastructure, according to the government’s UAE investment announcement.
The two countries also launched negotiations toward a Comprehensive Economic Partnership Agreement, which would cover services, goods and digital trade and give Canadian firms a more stable foothold in Gulf markets.
On November 23 2025, at the G20 Leaders Summit in Johannesburg, Canada announced new investment-protection talks with South Africa and confirmed the completed Nuclear Cooperation Agreement. These developments were highlighted in the government’s South Africa investment readout.
Canada also confirmed that FinDev Canada will open a Cape Town office in 2026, expanding its financing presence in African markets where digital financial services and early-stage business activity continue to grow.
Canada and India agreed to restart talks on a Comprehensive Economic Partnership Agreement after a two-year pause. This decision was confirmed in the India–Canada CEPA update issued during the G20 meetings.
Both governments signalled interest in expanding trade through improved access in goods, services, investment and digital sectors, with a a longer term goal of increasing two-way trade toward the US$50–70 billion range by 2030 depending on final terms.
These agreements, while they don't specifically mention fintech directly, they will impact the trading environment and structural conditions that matter for financial technology and funding innovation firms in the following ways:
More global capital in play. The UAE’s multibillion-dollar investment envelope creates new demand for financing platforms, risk systems, payments infrastructure and digital tools that support large scaling AI, energy and infrastructure projects.
New markets with strong digital finance adoption and upside. South Africa and broader African regions continue to scale mobile money, SME finance and digital identity rails. India remains one of the world’s largest digital payments ecosystems. Canadian fintechs offering compliance, embedded finance, alternative credit, and capital formation tools can explore more predictable and supported entry routes.
Trade agreements that impact digital rules. Investment treaties and CEPAs often influence data standards, dispute resolution, digital services access and treatment of financial technologies. Early engagement ensures fintech and alternative finance models are not overshadowed by incumbent only positions.
NCFA encourages fintech founders, investors and innovators to take advantage of these expanding global routes. Connect with us to discuss Africa and UAE partnerships, participate in upcoming trade related roundtables, and support policy and outreach work, as Canada negotiates new digital trade and investment frameworks. These government agreements create real openings, and NCFA’s global bridge network is ready to help Canadian fintechs move into these markets.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016