




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


May 11, 2026 | NCFA Fintech Market Activity | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Capital Markets And Funding

On May 11, 2026, Ripple Prime secured a $200 million debt facility from funds managed by Neuberger Specialty Finance to expand margin capacity for its multi asset prime brokerage platform. In practice, this gives the prime brokerage business more financing room as institutional clients trade across traditional and digital asset markets.
The facility lets Ripple Prime draw up to $200 million as client needs change. Since Ripple acquired the platform in 2025, Ripple says Ripple Prime has tripled revenue year over year. Institutional crypto now needs credit, margin, collateral, and financing capacity, not just custody and execution.
Noel Kimmel, President, Ripple Prime
“This facility enables us to grow alongside our clients by delivering increased margin capacity, greater responsiveness, and improved capital efficiency.”
Ripple closed its Hidden Road acquisition in October 2025 and renamed the platform Ripple Prime. Ripple said the deal made it the first crypto company to own and operate a global, multi asset prime broker. It later added U.S. digital asset spot prime brokerage for institutional clients, including OTC spot execution across major digital assets such as XRP and RLUSD.
Ripple Prime needs lending capacity because prime brokerage is not just a trading tool. It requires capital, risk controls, collateral management, and reliable financing. A trading venue helps clients buy and sell. A prime broker helps them finance positions, manage margin, and connect activity across asset classes.
NCFA’s earlier look at Ripple’s two year expansion stack showed how the company has added custody, prime brokerage, stablecoin payments, treasury tools, and wallet infrastructure. The debt facility fits that buildout. Ripple is putting more capital behind the institutional layer of digital asset markets. That means more capacity to support margin needs as trading activity grows. It also makes Ripple less dependent on a pure payments narrative. The company now has a clearer institutional markets story.
Peter Sterling, Head of Neuberger Specialty Finance:
“Ripple Prime has built an innovative brokerage platform combining fintech-grade technology and agility with bank-level compliance and operational rigor.”
There is also a Canadian link. Ripple’s Rail acquisition brought Toronto based B2B stablecoin payment infrastructure into Ripple’s network. Ripple Prime now adds financing capacity on the institutional markets side. The larger read is simple: payments, liquidity, collateral, and trading are starting to connect inside bigger digital asset platforms.
If digital asset firms start owning prime brokerage, payments, custody, and treasury infrastructure, which institutions will control the credit and collateral rails behind the next generation of markets?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
May 11, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Wealth Capital Markets And Investing
On May 11, 2026, MoonPay acquired Dawn Labs and launched Dawn CLI, an AI native trading tool that lets users describe a trading strategy in plain English, generate code, and test the strategy before a user can approve execution.
Dawn CLI targets a time consuming pain point. Building a trading strategy takes research, testing, and judgment. Most users don’t have all of those skills. Dawn CLI pulls more of that work into one flow based on a user's described strategy.
Other platforms approach this growing demand from an analysis perspective. For example, Finelo's AI trading tools can help users examine market data and charts, although every AI-generated insight should be independently verified before trading.
Dawn CLI is different from a charting app, a trading bot, or a chatbot that explains markets. Based on MoonPay’s description, Dawn CLI keeps execution 'as directed by the user' (to avoid implying autonomous trading). AI can help translate intent into action, but trading products still need plain risk warnings, permission controls, auditable records, and limits on what the system can and can't do.
Ivan Soto Wright, CEO and Founder, MoonPay:
“The team at Dawn Labs have made the most complex parts of active trading accessible to anyone with an idea,”
The question is whether users understand what the strategy does, where it can fail, how it behaves under stress, and when execution should stop. A backtest can look clean and still break in live markets.
This is where AI trading gets serious for fintech operators. A bad trade loses money. Companies that use AI in trading need stronger controls around suitability, leverage, market volatility, testing quality, and user consent. They also need logs that show what the user asked, what the tool generated, what changed, and what was executed.
MoonPay's scale adds distribution to the model with 30 million customers across 180 countries, including 500 enterprise customers across crypto and fintech. The acquisition of Dawn means MoonPay is expanding from on ramps into AI enabled financial activity. Access is no longer enough. Platforms want to own more of what users do after they enter digital markets.
Neeraj Prasad, Founder of Dawn Labs and Chief Engineer of MoonPay Labs:
“We built Dawn to address the fragmentation traders face across research, strategy development and execution,”
The impact could be meaningful if this model spreads. More users may test trading ideas without coding skills. Platforms may deepen engagement after onboarding. Active traders may begin to expect AI to handle research and execution prep. But the downside grows too.
The wider crypto business model is also changing. On ramps and wallets are simply no longer enough to compete on. The next area of activity, including trading, payments, stablecoin spending, agent workflows, and embedded market access. More activity can create deeper customer relationships, but it also puts platforms closer to regulated decisions.
When AI can turn a trading idea into code, testing, and execution, who owns the controls that keep user intent, risk, and accountability clear?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 11, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure

On May 8 2026, BlackRock filed SEC documents for OnChain Share structures tied to Treasury and liquidity products, expanding its push into tokenized fund infrastructure connected to stablecoin reserve management and digital cash markets. The filings outline blockchain based ownership records linked to regulated transfer agency and identity systems, showing how large asset managers are starting to integrate tokenized fund mechanics into institutional cash and collateral infrastructure.
BlackRock is preparing two tokenized money market style fund structures aimed at digital asset users.
1. The BlackRock Daily Reinvestment Stablecoin Reserve Vehicle is the cash and Treasury product. The SEC filing says the fund invests 100% of total assets in cash, Treasury bills, notes and other U.S. Treasury obligations with remaining maturities of 93 days or less, plus overnight repurchase agreements secured by Treasuries.
2. BlackRock is adding an OnChain Share class to an existing Treasury liquidity fund. The OnChain Shares are the tokenized ownership format, not a separate asset by themselves. Securitize Transfer Agent, LLC maintains the official ownership record for those shares on public blockchains, while offchain records connect wallet addresses to shareholder identity information.
Because BlackRock isn't selling speculative token exposure here. It's building regulated cash management infrastructure that can connect to blockchain based workflows. BlackRock is preparing tokenized money market funds for investors who hold cash in stablecoins rather than bank accounts. Stablecoin users need places to park digital dollars. Asset managers want the fee pool behind that cash. Tokenized Treasury funds sit between both sides.
The filing says Securitize Transfer Agent, LLC maintains the official ownership record for OnChain Shares on public blockchains used by investors. BlackRock also keeps offchain records that connect wallet addresses to shareholder identity information. It gives investors blockchain based fund records, but it keeps regulated transfer agency, identity controls, and fund administration in place. This isn't decentralized finance replacing Wall Street. It's Wall Street absorbing useful blockchain mechanics into regulated products.
Stablecoins are becoming a large digital cash market, and tokenized Treasuries give that market a yield and collateral layer. Stablecoin issuers, exchanges, custodians, market makers, wallets, and trading desks all need safer liquid assets that can move more efficiently across blockchain based systems.
Tokenized Treasury funds can serve as reserve assets, trading collateral, treasury tools, and liquidity instruments. BlackRock’s timing also follows the growth of BUIDL, its tokenized Treasury fund with Securitize (tokenized U.S. dollar institutional liquidity fund).
The market is still small compared with traditional money markets, but it is growing quickly enough to matter. RWA.xyz tracks tokenized real world asset markets, including tokenized Treasuries across public blockchains. BlackRock’s BUIDL fund has grown to roughly $2.5B in assets.
Bloomberg reported that BlackRock’s second filing relates to a digital share class tied to the roughly $6.1B BlackRock Select Treasury Based Liquidity Fund. BlackRock is effectively applying tokenized share mechanics to an existing cash management product, not only creating a new stablecoin reserve vehicle.
The first affected group is firms that hold, issue, move, or manage digital dollars, such as stablecoin issuers, exchanges, custodians, crypto prime brokers, market makers, wallet providers, and institutional treasury desks. They need liquid reserve assets, reliable collateral, fund records that can connect to wallets, and regulated products that reduce counterparty risk.
The second affected group is traditional finance including transfer agents, custodians, fund administrators, broker dealers, banks, and asset managers. If tokenized fund shares become useful collateral, these firms will need systems that can reconcile blockchain records with regulated books and records.
The winners are likely firms that control distribution, custody, transfer agency, identity, compliance, and liquidity. That is why BlackRock’s filing matters. Tokenization may look like a technology story, but the business model is about control over the digital cash stack.
If stablecoins become the payment layer and tokenized Treasuries become the reserve and collateral layer, the companies that manage those Treasury products gain a powerful position in digital finance.
The institutional version of crypto looks very different from the early pitch. The first story was about removing intermediaries. The version large institutions are building keeps many intermediaries in place. Regulated funds, known investors, transfer agents and custodians still matter. What changes is the recordkeeping and settlement infrastructure underneath. Tokenization is becoming more important because it is being rebuilt in a form large pools of capital can actually use.
Nothing else is confirmed until BlackRock files or announces it. But this does not look like a one time product test. BlackRock already has BUIDL with Securitize. It is now preparing a stablecoin reserve vehicle and OnChain Shares for another Treasury liquidity product. If demand keeps growing, more tokenized share classes, cash products, collateral tools, and stablecoin reserve products could follow.
If tokenized U.S. Treasury products become core infrastructure for stablecoins, trading platforms, treasury desks, and cross border settlement, Canadian firms may plug into U.S. dollar blockchain systems before comparable domestic options mature. That affects where liquidity forms, how products are built, who controls custody relationships, and how payments infrastructure connects to tokenized markets.
For regulators, the issue is market structure. Canada will need clear rules for custody, investor identity, redemption rights, transfer agents, operational risk, and how tokenized fund records fit with securities law.
Whether stablecoin issuers use these funds as reserve assets? Whether broker dealers and custodians accept tokenized fund shares as collateral? Whether regulators clarify how blockchain based ownership records fit with securities and custody rules?
For Canada, the practical question is execution. Firms do not need to wait for a perfect domestic model. They can start mapping where tokenized cash could affect treasury operations, settlement, collateral, custody, and reporting. The risk is that the most useful infrastructure gets built elsewhere while Canada treats the topic as a narrow crypto market story.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 11, 2026 | NCFA Fintech Market Activity | Artificial Intelligence And Data, Digital Assets Blockchain And Tokenization, Payments And Money Movement

On May 11, 2026, Circle launched Circle Agent Stack, a set of tools that lets developers and AI agents hold assets, find services, and transact with USDC across supported blockchains and payment protocols. The first stack has five parts:
Nanopayments is a useful detail. Circle says the new protocol supports gas free USDC transfers as small as $0.000001. That opens the door to small payments between software systems, such as API calls, data access, compute, and agent services. Traditional payment systems aren't built for that kind of volume or precision.
Agent Wallets give AI agents policy controlled wallets to hold, send, and manage funds inside predefined guardrails. Meanwhile, Agent Marketplace gives humans and AI agents a place to browse, assess, and connect with agentic services. Circle isn't only asking whether agents can make decisions. It's asking whether they can move money with limits, permissions, and a record of activity.
Jeremy Allaire, Co Founder, Chairman and CEO, Circle:
“Financial infrastructure has historically been built for people, with manual onboarding, approvals, and payment flows that were never designed for software acting on its own,”
That's the operator gap. Human payment workflows still rely on dashboards, approvals, fraud checks, and service hours. Agent workflows need different rails. Wallets that can hold value, rules that limit spending, payment systems that work at software speed, and audit trails that show what happened.
Circle's scale is ready to test this stack for the agentic era. In Q1 2026, Circle reported $77.0 billion (up 28% yoy) of USDC in circulation at quarter end. It also reported $21.5 trillion (up 263%) of USDC on chain transaction volume in the quarter. Agent commerce needs liquid digital money, developer tools, and enough reach to make machine payments useful.
Nikhil Chandhok, Chief Product and Technology Officer, Circle:
“USDC is uniquely well-suited for the agentic economy because it is internet-native, programmable, and always available,”
Banks, PSPs, fintechs, marketplaces, and compliance teams should start asking how autonomous software will pay for services without exposing users to open ended risk. Who sets the spending limit? Who approves the wallet? Who reviews failed transactions? Who owns the fraud loss? Who explains an agent’s payment history to a customer, auditor, or regulator?
For Canadian stablecoin builders, Circle raises the competitive infrastructure. A dollar token sitting in a wallet isn't enough. The future is programmable payment infrastructure with controls, identity, settlement, and developer access. Key considerations for Canada, as it works to complete it's stablecoin policy and domestic digital money experiments.
Global platforms are already building for software driven transaction volume. If autonomous agents begin buying compute, data, services, and financial access, payment infrastructure will need to price, route, monitor, and govern transactions that are too small and too frequent for legacy rails.
The launch of Circle's infrastructure isn't immediate proof that agent commerce has reached scale. Developers still need to build useful services. Enterprises still need to approve agent spending. Compliance teams need monitoring rules that work when transactions happen in small amounts, high volume, and real time.
A nanopayment can be tiny and still create a unique risk surface. Millions of agent actions can turn small payments into material exposure fast. That makes wallet rules, customer consent, fraud controls, dispute handling, and auditability all central to the product (and not handled in the back end).
Stablecoins are already supporting trading, treasury, settlement and global payments. Now agent commerce adds a new use case that is software paying software. If that grows, payment infrastructure will need to work at machine speed without losing human accountability.
Circle’s launch is worth watching as it converges three live themes at once. Stablecoins, AI agents, and programmable payments.
If AI agents become financial participants, which firms will control the wallet, rules, settlement, and audit trail behind software driven payments?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 8, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization
Image: Magnific
On May 7 2026, Bitwise announced its first tokenized fund through a partnership with Superstate. Bitwise will become investment manager of the Superstate Crypto Carry Fund, which will be renamed the Bitwise Crypto Carry Fund.
The fund keeps the USCC ticker, smart contracts, and token address, with the transition expected on June 1 2026. USCC has more than $267M in assets under management and targets yield from the crypto cash and carry trade, where futures prices trade above spot prices.
Bitwise is entering tokenized funds by taking over a live onchain product instead of launching from zero. Superstate will keep operating the infrastructure layer, including tokenized issuance and digital transfer agency services through FundOS. That separates investment management from onchain fund operations, which is exactly how institutional tokenized finance may scale.
Tokenized real world assets now exceed $30B globally, while tokenized US Treasuries have surpassed $15B, with the tokenized asset market projected to reach $18.9T by 2031.
Bitwise says it has $11B in client assets, more than 70 investment products, and serves more than 5,000 private wealth teams, RIAs, family offices and institutional investors, along with 21 banks and broker dealers. That distribution is key to scaling tokenized funds beyond only crypto native buyers. They also need access to wealth, advisory, and institutional channels.
Tokenization doesn't remove traditional financial roles, but rather it rebuilds them on new rails. Fund managers, transfer agents and distribution all still matter. The difference is that settlement, ownership records, and secondary utility can now run onchain.
If US asset managers and infrastructure firms continue pairing regulated products with onchain fund administration, Canadian fund managers, exempt market platforms, dealers, and policymakers need to decide where tokenized funds fit into Canadian capital formation and investor access.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 8, 2026 | NCFA Insight | Regulation And Policy, Cybersecurity And Fraud, Artificial Intelligence And Data
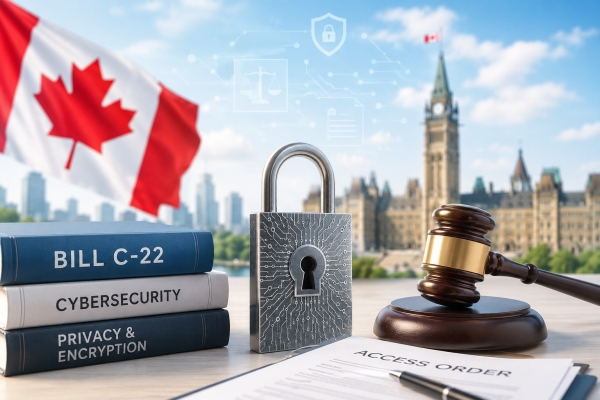
On May 7, 2026, Apple and Meta warned that Canada’s Bill C-22 could weaken encryption, pushing a long running lawful access debate back into the spotlight. The bill reaches far beyond Silicon Valley politics. It touches the same infrastructure that supports digital banking, fintech apps, cloud platforms, AI systems, wallets, fraud detection, secure communications, and identity verification.
What started as a policing and national security issue increasingly looks like a broader fight over cybersecurity, digital trust, and how governments regulate access to modern technology systems.
Bill C-22 creates a lawful access framework for electronic service providers operating in Canada.
Part 1 updates investigative powers related to subscriber information and transmission data.
Part 2 creates the Supporting Authorized Access to Information Act, which would require certain providers to maintain operational and technical capabilities that allow them to comply with lawful access requests under existing Criminal Code or CSIS Act authorities.
The scope is broad. The bill applies to electronic service providers involved in creating, storing, processing, transmitting, receiving, or making information available electronically. That definition reaches beyond telecom networks and traditional internet providers. Depending on regulations and ministerial orders, the framework could affect cloud providers, messaging platforms, device ecosystems, AI infrastructure, payment systems, digital identity platforms, and fintech companies handling sensitive customer information.
The government argues that Canada’s investigative framework no longer matches modern communications technology. Public Safety Canada says current lawful access rules still reflect a 1995 voice telephony environment, even though investigations now involve encrypted messaging systems, cloud services, internet platforms, and cross border digital infrastructure.
The FBI, RCMP, and other law enforcement agencies have long referred to encrypted communications and inaccessible digital evidence as the “going dark” problem.
Investigators increasingly struggle to access information tied to organized crime, online fraud, ransomware, terrorism, child exploitation, and financial crime because modern services collect less accessible data or use strong encryption that even the provider cannot access directly.
The Canadian Association of Chiefs of Police publicly supported the legislation and argued that police need updated tools to investigate serious crimes in digital environments. Justice Canada also says the bill would allow judges to authorize requests for subscriber information or transmission data from foreign telecommunications or social media providers where there are reasonable grounds to suspect an offence and the information would help the investigation.
The fraud backdrop strengthens the government’s case politically. Competition Bureau Canada reported CAFC data showing Canadians lost more than $704 million to fraud in 2025, while only 5% to 10% of fraud gets reported. Reported losses since 2022 have surpassed $2.4 billion.
Critics argue the proposed solution risks weakening the same security architecture modern digital systems depend on. Reuters reported that Apple warned the bill could allow Canada to “force companies to break encryption by inserting backdoors.”
Meta argued the legislation could force providers to weaken encryption protections or undermine zero knowledge systems designed so providers themselves cannot access customer data.
Public Safety Canada disputes that interpretation. Government officials say the legislation would not require providers to create a “systemic vulnerability” in encryption systems, which is now at the center of the debate.
The problem is technical as much as legal. Security engineers often argue that once a system preserves exceptional access for any party, it creates a potential weak point that can eventually attract criminals and and insider abuse.
For fintechs and financial institutions, it's the same strong encryption that protects account credentials, wallet keys, transaction approvals, secure communications, and increasingly AI workflows that may soon handle sensitive financial tasks autonomously.
The UK offers an important lesson for Canada. Earlier this year, Apple removed Advanced Data Protection for new UK users after government pressure around encrypted cloud access. Apple later stated that UK users would no longer have access to the feature and said, “we have never built a backdoor or master key.”
The UK outcome shows how a lawful access demand can expand into a wider cybersecurity and trade problem. Instead of settling the issue, Apple’s feature rollback intensified scrutiny from privacy advocates, security experts, and U.S. officials concerned about government access to encrypted cloud data.
Canada could face the same kind of fallout if Bill C-22 leaves companies unclear about what they may be forced to build, disclose, weaken, or keep secret under future access orders.
Timing isn't great. Canada is already dealing with pressure around digital sovereignty, platform regulation, AI governance, and trade relations with the United States.
In June 2025, Canada rescinded its Digital Services Tax to restart trade negotiations with the U.S. The CUSMA review is an active pressure point for companies operating across borders through cloud infrastructure, data systems, and digital financial services.
Europe is moving differently. The European Commission imposed the first Digital Markets Act penalties in April 2025, including €500 million against Apple and €200 million against Meta. Meanwhile, the Trump administration has taken a more defensive posture toward American technology firms facing foreign digital regulation, including ordering U.S. diplomats to push back against foreign data sovereignty rules.
That leaves Canada to balance a convergence of pressure around public safety expectations, cybersecurity concerns, platform dependence, trade risk, and digital sovereignty ambitions.
Large platforms will likely absorb the first round of scrutiny. The second order effects may matter more for fintech operators and infrastructure providers.
Fintechs, digital identity companies, crypto wallet providers, cloud based banking platforms, AI finance systems, payment processors, fraud vendors, and regulated financial institutions could all face pressure around compliance architecture, data retention, encryption design, and cross jurisdiction operational requirements.
The cost may not appear immediately through direct enforcement. It may emerge through audits, vendor obligations, insurance requirements, infrastructure redesign, compliance overhead, or changes to how secure systems get built and marketed in Canada.
Encryption is key to financial infrastructure. Customer trust, cybersecurity resilience, fraud prevention, and digital competitiveness now all depend heavily on whether secure systems remain genuinely secure.
Does Canada need to choose between ineffective investigations and weakened encryption for everyone?
A better version of the bill would be more precise. It should clearly say which companies can receive access orders, protect end to end encryption and zero knowledge systems, require independent technical review before any order is approved, and give companies a real way to challenge orders that put security at risk.
The core dispute is not whether courts can authorize lawful investigations. It is whether governments should be able to force companies to preserve technical access inside systems designed specifically to remove that access. That is the fight at the centre of the global encryption debate.
Encryption is foundational infrastructure for finance, AI, communications, identity, and cloud systems. Canada’s challenge is no longer simply how to access digital evidence. It's how to modernize investigations without creating weaker systems that undermine cybersecurity, trust, and long term digital competitiveness.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
May 7, 2026 | NCFA Insight | Payments And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech, Open Banking Open Finance And Data Sharing

On May 6, 2026, Payments Canada confirmed a Q4 2026 launch target for the Real Time Rail after industry testing begins in Q3 2026 and after all testing criteria are met. The Real Time Rail (RTR) isn’t only about faster payments anymore. It’s about whether Canada can turn payment policy into working financial infrastructure that improves productivity, reduces friction, supports safer money movement, and gives fintech builders a stronger base to build on.
Payments Canada owns and operates Lynx, ACSS, and modernized RTR. Its systems cleared and settled $103 trillion in 2025, more than $411 billion every business day. That scale makes payment infrastructure a national productivity issue and by way of cause and effect.
When settlement runs slowly, capital sits idle. When payment data is thin, reconciliation gets messy. When fraud controls fall behind, trust takes the hit. And when access stays too narrow, competition suffers.
Canada has talked about faster payments for years. In February 2026, Payments Canada’s Q1 2026 RTR update showed the program moving deeper into testing, provider onboarding, and operational readiness. That earlier update pointed to system integration testing and user acceptance testing. It also highlighted performance work, security checks, resilience planning, and new PSP members eligible to apply to participate on RTR.
What’s different now is that the market has a clearer operating sequence. Industry testing starts in Q3 2026. Launch targets Q4 2026, after testing criteria are met. Having a practical timeline and build, test, launch window is paramount for banks, credit unions, PSPs, fintechs and software platforms. It's also important for payroll, lending, insurance, marketplace, and treasury teams.
Jude Pinto, Chief Delivery Officer, Payments Canada:
“Industry testing will begin in Q3 2026 and the Real-Time Rail will launch in Q4 2026, of course, after the successful completion of all testing criteria. This will ensure the system remains safe, secure and resilient in a live environment.”
The Q4 launch target isn’t that far off. Companies that want to benefit from RTR need to start preparing now. Settlement operations need review. Fraud monitoring needs stress testing. Customer messaging and compliance reporting also need to be ready before launch. So do liquidity planning and partner dependencies.
For fintech operators, this is where the real work starts. Access to RTR will matter, but access alone won’t be enough. Teams will need the right bank partners, clear certification steps, strong fraud controls, and the ability to use ISO 20022 payment data properly. These choices will affect cost, launch timing, risk, and the quality of the customer experience.
RTR also lands inside a wider digital finance buildout. Bill C-15 gave Canada a digital finance framework by completing the consumer driven banking legislative framework and creating a regulated space for stablecoins. Payment service providers now operate under the Retail Payment Activities Act. Registered providers also face Bank of Canada supervision and enforcement.
That combination changes the operating environment. Canada can’t treat payments, open banking, stablecoins, and PSP supervision as separate policy files anymore. They’re starting to connect. A consumer could eventually give data consent through open banking. That same consumer could fund an account through faster payment rails. They could receive payouts in real time. Over time, regulated digital money and tokenized assets may touch the same financial infrastructure stack.
Each layer needs trust. Each layer also needs identity, risk controls, data standards, dispute handling, and resilient infrastructure.
This is where Canada’s challenge gets harder. Passing the law is only step one. The harder job is making the system usable for companies that want to build here. Accreditation, RTR access, PSP supervision, bank partnerships, and compliance rules all need to work together.
The rules need to protect users without creating a maze that slows responsible firms down. If that balance fails, fintechs will spend too much time getting through the system and not enough time improving it. If all lines up well, Canada can turn faster payments into more competition.
Payments Canada links RTR to security, financial crime, and fraud. Faster payments leave less time to catch scams, especially when payments are instant and irrevocable. Canada needs speed, but it also needs trust.
RTR will support 24/7 instant payments, ISO 20022 messaging, and centralized fraud detection. Fraud control can’t live only in compliance. It has to show up in onboarding, transaction monitoring, customer warnings, and dispute handling.
For founders and operators, fraud control affects customer experience. Companies that stop scam patterns earlier, reduce false positives, and protect users without slowing down good transactions will have a stronger product than firms that only promise speed.
The remaining time in 2026 is important:
After years of delay, Canada’s Real Time Rail is now a live execution test for Canada's digital finance agenda. The launch target gives the market something to plan around. The bigger story is how RTR connects with PSP supervision, Bill C-15, open banking, stablecoins, fraud enforcement, and competition policy.
The opportunity is real, and so is the operating burden. If all goes according to plan, Canada can get better financial infrastructure, more productive payment flows, stronger fintech competition, and safer digital financial services.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016