




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Feb 5, 2026 | NCFA Fintech Market Activity | AI and Finance Innovation

On January 21 2026, Calgary-based Chata Technologies Chata.ai closed a US$10 million Series A to expand its deterministic AI analytics platform for financial services, backed by 7RIDGE (UK) and Izou Partners (US).
Chata.ai focuses on a model that produces repeatable, auditable answers to natural language questions over financial data. In plain terms, deterministic AI means the system gives the same answer every time to the same question, with a clear record of how it arrived there. Instead of relying on probabilistic GPU driven models, its system runs inference on CPUs and is designed for environments where consistency, traceability, and explainability matter. Financial teams can query data directly without dashboards or engineering support while maintaining a clear audit trail.
The company says funding will support growth across traditional finance, digital asset platforms, and wealth technology use cases where AI tools must operate inside compliance and risk frameworks. Investors pointed to the platform’s ability to combine scale, cost efficiency, and verifiable outputs as a practical fit for regulated finance workflows.
Kelly Cherniwchan, Chief Executive Officer, Chata Technologies:
“This investment allows us to bring trusted data analytics to financial institutions where precision, reliability, and regulatory clarity are critical.”
Deterministic AI changes the conversation for finance teams. The value is in being able to ask a question twice and receive the same answer, with a record of how that answer was produced.
When financial institutions adopt AI tools, will platforms that provide auditability and consistent outputs become the standard over systems that produce variable results?
Financial firms want AI that fits inside existing control structures rather than sitting outside them. Deterministic models may become a foundation layer for analytics, reporting, risk review, and automated decision support across regulated finance.

The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Feb 4, 2026 | NCFA Insights | AI, Financial Infrastructure and Identity

On February 2 2026, security firm Wiz disclosed an exposed Moltbook database tied to autonomous AI agents containing millions of API keys. Around the same time, OpenClaw (an open source framework for running locally controlled AI agents) published documentation showing how locally run AI agents can access user devices, credentials and external services.
Autonomous AI agents aren't limited to chat style tools, and are beginning to touch real infrastructure that includes identity, wallets, and payment-related APIs.
This article discusses the what the emerging agent economy looks like in practice, why it matters for fintech founders and investors, and where governance and security pressure is building first. AI agents increasingly hold credentials, maintain state over time, and interact with external systems through APIs. That mix creates a new operational reality. Code is starting to act like a user, but without the same guardrails that traditional consumer finance expects.
Early agent frameworks are moving from single session prompts into persistent software. They can store memory, maintain identity, and run tasks continuously.
In OpenClaw’s model, locally run agents can interact with files, services, and external applications using user approved permissions. These agents can coordinate with other agents, call tools, and keep operating after a user stops watching the screen.
That capability becomes financially relevant the moment an agent can access a wallet credential, a banking API token, or a payment workflow embedded inside another platform.
Fintech products already sit on top of API keys, tokens, and delegated permissions. Wallet providers, open banking connectors, payment facilitators, and embedded finance stacks often rely on shared secrets and scoped access to move data or value. AI agents introduce a new actor into that system. A human might authorize a connection once, then an agent can repeatedly execute actions across that access channel at machine speed.
If an AI agent initiates a transaction, who owns responsibility for the outcome.
If an agent uses an API credential and a vendor later mishandles logs or storage, who absorbs liability.
If an agent operates in the background, how do firms enforce consent, audit trails, and appropriate use.
The Moltbook exposure matters because the risk is suddenly tangible. An unsecured database containing API keys is not a routine bug. It shows how quickly agent networks can create large pools of credentials that become attractive targets. When an environment contains millions of agent identities, a failure in credential storage or access control can scale into massive compromise. And of course, the financial equivalent is obvious. Once agents connect to wallets, payments, or identity services, insecure key management becomes a direct financial risk.
Fintech teams already know that credential hygiene and access governance decide security outcomes. AI agents compress that timeline. Humans leak keys through mistakes. Agents and agent networks can leak keys through architecture. That is why builders should treat agent access as its own risk class, separate from standard consumer or enterprise authentication patterns.
Regulators do not yet have comprehensive frameworks for AI agents operating inside financial workflows. Even so, policy direction in adjacent areas points to where enforcement will land first. Authorities focus on accountability, auditability, and consumer harm, regardless of channel. That already shows up in digital advice and online influence. Learn how CSA and CIRO tighten expectations around digital investment advice and influence when content or workflows can affect investor behaviour at scale.
AI agents create a similar accountability gap. If an agent provides recommendations, executes actions, or routes users into products, platform operators will need evidence of controls. That will include permissioning, logging, dispute handling, and clear assignment of responsibility when something goes wrong.
If AI agents can hold credentials and execute actions through financial APIs, what controls will separate trusted automation from uncontrolled delegated access?
The agent economy is coalescing at the edge of finance. AI agents that operate with identity and persistent access can become a new layer between users and money transfers. The winners will treat governance as part of product design. They will harden credential management, build clear authorization flows, and design auditability that works when software, not a person, invokes actions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 3, 2026 | NCFA Fintech Market Activity | Stablecoins and Payments
On February 3 2026, VersaBank announced that Stablecorp’s QCAD is its first stablecoin customer, bringing a Canadian Schedule I bank into the custody and safeguarding of a Canadian dollar-backed digital currency.
Stablecorp issues QCAD as a 1:1 Canadian dollar-backed stablecoin with reserve funds held at regulated financial institutions. VersaBank provides custodial services and settlement support for QCAD transactions using its digital asset infrastructure and API framework.
Most stablecoin infrastructure in Canada still depends on global US dollar networks. QCAD represents a domestic currency alternative, and VersaBank’s role places regulated banking oversight directly inside the operational flow of a Canadian stablecoin.
VersaBank has been building digital asset custody and tokenized deposit capabilities over the past several years. Its platform supports digital asset APIs, ledger compatible settlement tools, and custody frameworks designed for fintech integration. Bringing QCAD onto this platform turns that infrastructure into a live payments and settlement environment rather than a technical capability waiting for use.
Transaction volumes aren't disclosed, but the structure matters more than scale today. A Canadian stablecoin now sits inside a regulated bank’s custody, reconciliation, and safeguarding systems. It's a practical step toward making stablecoins usable for treasury management, fintech on and off ramps, merchant settlement, and cross-border flows without relying on foreign currency rails.
David Taylor, President and CEO, VersaBank:
"We are pleased to support Stablecorp and QCAD as they bring a Canadian dollar stablecoin to market. Our digital asset custody and settlement platform was built for exactly this type of use case, where regulated banking infrastructure meets digital currency innovation."
If Canadian stablecoins can settle through Canadian regulated banks, what role will they play in future payment rails, treasury operations, and fintech infrastructure?
Instead of sitting outside the financial system, digital Canadian dollars are beginning to move through it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 4, 2026 | NCFA Fintech Market Activity | Funding and Capital Markets
Image: Freepik
On February 4 2026, NEO Financial announced it secured $68.5 million in equity capital from more than 100 Canadian investors to accelerate its securitization strategy and support further growth of its lending and credit products. The round includes participation from Alberta Investment Management Corporation (AIMCo), Northleaf Capital Partners, Plaza Ventures, Sandstone Asset Management, and Caldwell Growth Opportunities Fund. These are not typical venture participants. They are institutional capital allocators with deep experience in private credit, structured finance, and asset-backed investing.
NEO positions the raise as strengthening its balance sheet to expand its asset-backed funding programs and diversify capital sources tied to its consumer and merchant credit offerings. The company isn't raising capital simply to extend runway. It's raising capital specifically to support securitization activity that allows the company to recycle lending capital through structured vehicles and continue originating credit without relying solely on sponsor-bank facilities or traditional debt lines.
NEO reports that it serves millions of Canadians across retail and business financial products and has already built a sizeable loan portfolio through point of sale financing, credit products, and merchant services. Securitization allows that loan book to become a capital markets asset rather than a balance sheet constraint.
For Canadian fintech lenders, this represents a maturation point. Early growth in fintech credit often depends on venture equity and warehouse funding. Long term scale depends on access to institutional capital markets that can absorb receivables and recycle liquidity. NEO's financing is a sign that Canadian institutional investors are increasingly comfortable backing fintech platforms that combine lending operations with disciplined capital markets execution.
Andrew Chau, Co-Founder and CEO, NEO Financial:
"This investment supports the continued expansion of our securitization strategy and strengthens our ability to scale credit products responsibly for Canadians and businesses across the country."
When fintech lenders can turn their loan portfolios into new funding through securitization, does access to capital markets become the main factor separating national scale players from niche credit providers?
This raise shows how NEO is tying its lending growth directly to capital markets capability. Platforms that can convert loan origination into structured investment assets will have a structural advantage as lending volumes grow.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada’s Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 2, 2026 | NCFA Fintech Market Activity | Payments and Regulation
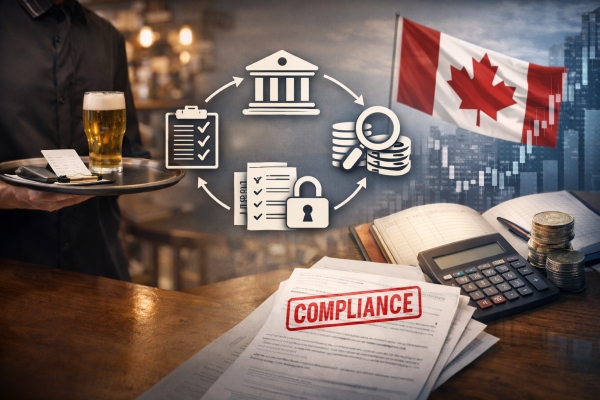
On February 2 2026, XTM Inc said Everyday Payments had started the Retail Payment Activities Act compliance process for thousands of hospitality businesses across Canada.
The release tied the work to the Everyday platform that manages hospitality payout flows such as tip outs and shift-based earnings. It also linked the compliance path to the migration of the AnyDay Canadian hospitality solution into the newly formed Everyday Payments entity.
XTM said that on January 28 2026 it implemented additional risk mitigation measures to address legacy operational practices across the platform.
Marilyn Schaffer, CEO of XTM:
"While the RPAA transition has included challenges related to reconciliation and technology alignment, we welcome building from a place of discipline."
The release lists three specific changes:
First, it said it had implemented regulated trust accounts for each client with an expected completion window of 30 to 45 business days.
Second, it said it had moved from weekly to daily withdrawals to improve reconciliation, control, and visibility.
Third, it said it had added enhanced audit and review rights so business owners could independently assess account standing.
This is where RPAA stops being policy and starts being operations. Fund segregation, withdrawal cadence, and auditability now sit inside the day to day flow of money for hospitality workers and merchants.
Everyday Payments operates payout infrastructure used by restaurants, bars, hotels, and hospitality venues across Canada to distribute earned funds to workers and reconcile merchant balances. That scale is what makes these changes meaningful. When a platform supporting thousands of venues adjusts how funds are held, released, and reviewed, it foreshadows what other vertical payment operators will soon face as RPAA requirements mature.
The release also says RPAA's a system level baseline, requiring registration, operational risk management frameworks, safeguarding of end user funds, and incident reporting administered by the Bank of Canada. Remember RPAA registration opened on November 1 2024.
Gordon Reykdal, Executive Chairman, Everyday People Financial Corp, and Board Member, Everyday Payments:
“Applying under the RPAA to the newly formed Everyday Payments is a natural extension of how we operate our business. We welcome a clear and robust regulatory framework and believe it strengthens trust across the payments ecosystem, benefiting consumers, merchants, and partners alike.”
Daily withdrawals, regulated trust accounts, and merchant audit rights raise the operating bar. Which vertical payment platforms will treat that bar as a moat, and which will treat it as friction that slows growth?
RPAA compliance is now showing up inside real operational workflows that move money for frontline workers and merchants, not only inside financial institutions.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Canadian Fintech Funding | February 3, 2026
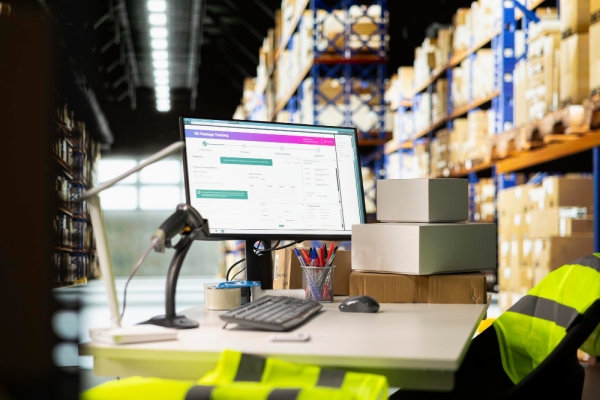
Image: Freepik/DC Studio
On February 3, 2026, Montreal-based startup Velix announces a $2M pre-seed funding round led by Luge Capital with participation from Stand Up Ventures and Accelia Capital to modernize how logistics companies handle billing, reconciliation, and financial disputes as trade volumes rise across Canada.
David Nault, Partner, Luge Capital:
“Logistics has invested heavily in moving goods more efficiently, but little innovation has occurred on the financial layer, resulting in massive inefficiencies as volume increased. We’re excited to partner with Velix to launch a modern financial platform to automate billing and reconciliations for logistics operators.”
Canada’s logistics networks expand quickly. Forecasts estimate the market will reach $65B by 2030 while the federal government commits $4.1B to strengthen trade corridors and supply chain resilience. As physical networks scale across carriers, warehouses, and border touchpoints, financial attribution becomes harder across multiple parties and systems.
Third party logistics providers now act as financial intermediaries between carriers, brands, and end customers. They assign dollars to every parcel and service across invoices, rate cards, surcharges, and service levels. Many still rely on paper, email, flat files, and siloed legacy tools. These workflows slow billing cycles, create errors, delay cash collection, and reduce margins.
“The majority of 3PL operators I’ve worked with of all sizes share one thing in common, clunky and time consuming billing processes that create the cashflow drag. What Maeghan and the Velix team are building is game changing, helping operators structure and automate a critical, massively underserved part of the logistics stack.” Nicholas Richards, Co Founder, ShipHero
Velix's financial operations platform allows logistics teams to automate freight and parcel reconciliation, customer billing, and dispute resolution in one system. The platform closes the gap between the movement of goods and the financial workflows required to settle accounts across many participants.
As Canada invests $4.1B to strengthen trade corridors and supply chain resilience across roads, ports, and rail, the financial systems behind those movements become a constraint. This story sits at the intersection of fintech and industrial infrastructure. It shows how financial operating systems inside vertical industries remain under served even as payments innovation advances at the consumer layer.
As trade corridors expand and logistics volumes rise, billing accuracy, reconciliation integrity, and dispute resolution directly affect how quickly revenue moves through the system. Velix addresses an bottleneck where operational finance limits the benefits of national infrastructure spending.
This development shows how financial infrastructure inside critical Canadian industries receives far less attention than physical infrastructure. As trade corridors expand and freight volumes increase, the ability to bill accurately, reconcile quickly, and resolve disputes efficiently becomes part of how well that infrastructure performs in practice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 3, 2026

We know the tech market is flooded with big corporate giants and SMEs surviving on their innovations and tons of new entrants trying their best to keep their heads above the water.
Entering into a pool of young and thriving businesses and making your way to a point where you’re recognized by your target audience as a tech marketing company is a big challenge in itself.
According to marketing data, viewers retain a staggering 95% of a message conveyed through video, compared to only 10% through text. Furthermore, simply placing a compelling video on your landing page can boost conversion rates by up to 80%.
Zelios animated video production company knows this intricate market well. We have been observing it since its inception and know what works and what doesn’t. We know the dos and don'ts.
Watch until the end to hear Zelios share valuable tips for growing your tech startup in this hyper-competitive market.
Setting up clearly outlined goals is important before you start recording your video. Too often, startups create content without clarity, resulting in inconsistent messaging and poor performance. You don’t just need a video, you need an impactful video!
Ask yourself:
Once you find answers to these questions, you need to know your audience by developing their personas. Figure out their primary pain points and preferred social platform they use, to help you target the right audience without wasting resources.
Over-selling doesn’t work in this market. People love to connect with brands through emotions. Your old-traditioned aggressive sales pitches aren’t going to bring any good to your startup. Your video content should focus on establishing an emotional connection and building credibility first.
A crucial tactic is to "Sell the Problem" before offering the solution. Highlight the pain point your audience experiences and validate their struggle before introducing your product as the natural answer.
A startup's unique mission and origin story can be compelling video content. Share why you started the company and what values drive your team. This vulnerability builds trust far faster than a dry feature list.

Social proof is priceless, especially for a new technology company seeking validation. Potential customers trust the experiences of their peers more than they trust your company’s sales claims.
Customers trust peer voices more than brand messages. Even simple videos of customers explaining how your product helped them can outperform high-budget ads because they feel honest and unscripted. You can also encourage your early adopters to share their experiences on platforms like TikTok or Instagram. This content is inherently authentic and often generates buzz organically.
The best tech marketing is often instructional. Your audience wants to know how your product works, why it matters to them, and what solution it offers to their problem.
Pairing education with product demos helps you provide value upfront and show exactly how your solution works. People often watch videos to learn first and buy second, so this combination is especially potent.

Video SEO is often overlooked. If the search engine algorithms are unable to find your video on the internet, how would your audience will? Here are some of the tips that would help you improve your video’s optimization.
Don’t stick to only one platform. Try different options. If you’re only posting your videos on YouTube, try making short reels and post them on different social platforms like Instagram, TikTok, and even Facebook.
Here are some actionable steps that you can take to maximize your ROI by filming one high-quality piece and adapting its format.

With each new video you produce, think about how you can reuse footage to create fresh content without starting from scratch. Social media isn’t the only platform where you need to bombard with your videos. Embed testimonial videos and product demos directly into your sales decks and pitch presentations.
You can also turn your old recorded webinars into short tips clips, or extract quotes for social graphics, or maybe edit the longer videos into mini-series. This approach helps you squeeze all the juice from your already existing content and create a new, fresher content without requiring any extra cost or time. But you have to be a little creative with it.
Video marketing is no longer optional, it is the core driver of modern startup growth. Whether you go down the path of creating memes and selling your business, or create professional videos with clear script, videography, and directions, the choice is yours depending on the dynamics of your audience and business niche.
But no matter what you do, never take the power of video production for granted.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016