




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Oct 20, 2026
Ontario's standards for internet gaming say a player's withdrawal must be processed "as soon as is practicable." Five words and no number. The deposit side of the same rulebook is equally short on timing, for a reason that explains most of what follows: the regulator was never trying to set a service level. It was trying to make sure money only moved to the person it belonged to. The rules ask for less than customers now expect, and operators compete in that gap.
The standard never needed to say "instant". Interac e-Transfer settled the question of what a transfer should feel like years before any regulator wrote a rulebook for online casinos, and operators inherited that expectation whether they had built for it or not. A recent summary of Payments Canada's 2026 trends report puts it in one line: Canadians have already changed how they pay, ahead of the infrastructure meant to carry it.
On the deposit side, the industry has largely caught up. Card rails, e-Transfer and wallet payments all land fast enough that a player rarely notices the mechanism. The effect has been to move the whole competitive question to the other end of the transaction.
Deposits are a payment job. Withdrawals are really a compliance job, which is why deposits are mostly sorted and withdrawals aren't. Before money leaves a regulated Ontario site, the operator has to be satisfied that the person requesting it is the account holder, that the destination account is one the player legally holds, and, where its own risk assessment calls for it, that the source of the funds can be reasonably corroborated. Those are conditions of registration. They take time, and the time is not the same for every customer or every operator.
That variance is the competitive gap. Two operators on identical rails can deliver very different withdrawal experiences depending on how much verification they front-load at sign-up, how they batch outgoing payments, and whether a request made on a Friday evening sits until Monday. The lobby looks the same either way. By including average payout times in its casino reviews, PlayCanada gives readers a way to compare a detail that is often less visible than game selection or promotional offers: how long different operators take to return their money.
The Real-Time Rail is the development most likely to narrow that gap, but not yet. The RTR by-law took effect on August 24, 2026. Payments Canada has the system itself launching in the fourth quarter of 2026, with the migration of Interac e-Transfer clearing and settlement running through the first three quarters of 2027.
Until then, an operator promising an instant payout is promising something its own infrastructure may not deliver consistently, and one that quotes a day or two is often being accurate rather than slow. A faster rail will also do nothing to the verification step in front of it. Even with instant settlement, someone still has to decide to release the money.
Open banking tells a similar story on a longer horizon. The consumer-driven banking framework now sits with the Bank of Canada under legislation passed in March, with draft regulations published in June and no coming-into-force date yet. Payment initiation, the piece that would matter to a casino cashier, is a later phase.
Every method on a cashier page carries a cost the player never sees: interchange on cards, per-transaction fees on transfers, wallet provider margins, chargeback exposure, and the staff and software needed for fraud screening and anti-money-laundering reporting on top. Operators serving more than one market add currency conversion on both legs.
The economics push in two directions at once. Offering more methods widens the funnel and raises the cost base. Offering fewer lowers cost and loses the customer whose bank does not support the one method on the list. The usual resolution is to treat the deposit menu as marketing and the withdrawal path as risk management, and that split is why the two experiences feel so different to the person using them.
Both open Canadian markets make the gap unusually easy to see. Ontario has had registered private operators since 2022 and Alberta since July; the other provinces each run a single public platform. Operators in an open market all sit under one published standard, so what still differs between them is operational, and nothing operational is more visible to a player than how long money takes to come back.
That is why operator-level payment detail has become part of how those players choose, and why payout time has turned into a figure people compare before they sign up rather than one they discover afterwards. It's the only number on a casino site that tells you about the operator itself rather than its games supplier.
If the Real-Time Rail removes the settlement delay by late 2027, what separates a fast operator from a slow one will be entirely a matter of how each runs verification. Does payout speed stop being a marketing claim at that point, or just become a more precise one?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Oct 19, 2026
Canada's online gambling industry is creating new business opportunities for payment processors, identity-verification providers and financial technology companies. But moving money between players and gambling operators involves more than completing a bank transfer.
Operators must establish who their customers are, monitor transactions for suspicious activity and meet applicable anti-money-laundering (AML) requirements. Payment providers may have separate obligations depending on the services they offer.
The regulatory framework is particularly relevant as Canada's online gambling industry expands beyond Ontario. Alberta's competitive market opened in July 2026, giving payment and compliance technology providers another provincial market to serve.
For fintech companies, the opportunity comes with an important distinction: Canada's federal financial-crime rules, provincial gambling requirements and payment-service regulations overlap, but they do not necessarily apply to every business in the same way.
The Financial Transactions and Reports Analysis Centre of Canada (FINTRAC) administers reporting and compliance requirements under the Proceeds of Crime (Money Laundering) and Terrorist Financing Act.
Casinos are among the reporting entities covered by the legislation. Their obligations can include customer identification, transaction reporting, recordkeeping, risk assessments and maintaining an AML compliance programme.
However, the legal definition of a casino matters.
FINTRAC's casino reporting framework historically centres on organizations conducting and managing specified gambling activities, including qualifying physical casino operations. A website offering online casino games is not automatically a separate FINTRAC casino reporting entity simply because it accepts wagers.
In provincial online gambling systems, the allocation of reporting responsibilities depends on the applicable legal framework, the entity conducting and managing the gambling activity, and the arrangements with private operators.
This distinction is particularly important in Ontario, where private gaming operators provide services within a provincially conducted and managed market.
Payment companies face a separate classification question.
Certain businesses that transmit funds, provide payment services or deal in virtual currencies can qualify as money services businesses (MSBs) or foreign money services businesses under federal law.
Since regulatory amendments took effect in 2022, certain payment service providers have been brought explicitly within FINTRAC's MSB framework.
That means a gambling operator and its payment processor may both have compliance responsibilities, but not necessarily identical ones.
For fintech providers entering the Canadian gambling industry, determining their reporting-entity status is an essential first step.
FINTRAC reporting is not based on one universal transaction threshold.
Different reports apply to different types of activity. Some involve a monetary threshold, while suspicious transaction reporting depends on the circumstances rather than the amount transferred.
The principal reporting categories include:
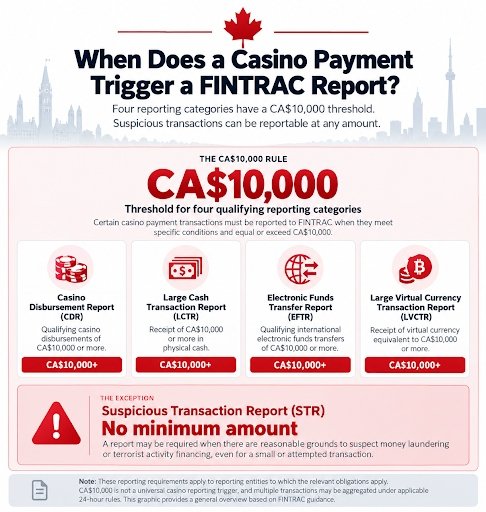
The table summarizes FINTRAC reporting categories for reporting entities to which the relevant obligations apply. It does not mean every private online gambling brand must independently submit each report.
The CA$10,000 threshold is particularly important because applicable 24-hour aggregation rules can bring multiple smaller transactions within reporting requirements.
For example, two qualifying casino disbursements of CA$6,000 each may trigger reporting if they occur within the relevant period and meet the applicable aggregation conditions.
A suspicious transaction works differently.
A CA$500 payment could require a report if the reporting entity has reasonable grounds to suspect a connection to money laundering or terrorist activity financing. Conversely, a large transaction is not automatically suspicious merely because it exceeds CA$10,000.
FINTRAC's guidance requires reporting entities to consider the facts, context and relevant indicators when assessing suspicious activity.
GambleOnline.ca provides a more detailed explanation of these distinctions in its guide to FINTRAC reporting requirements for Canadian casinos, including casino disbursements, suspicious transactions and electronic funds transfers.
For payment technology companies, the practical challenge is designing systems that distinguish transaction types rather than applying the same reporting rule to every payment.
Know Your Customer (KYC) procedures are one of the most visible parts of gambling compliance.
Players may be asked to provide identification when registering an account, making certain transactions or requesting a withdrawal.
But customer verification is not necessarily a single event.
Reporting entities must apply identification requirements when legally required, maintain appropriate records and monitor relevant activity according to their risk assessments.
A customer who has already completed an identity check may still trigger additional scrutiny if their subsequent transactions present unusual risks.
Consider a hypothetical player who deposits CA$2,000, places a small number of wagers and then requests a withdrawal of nearly the entire balance.
The transaction does not automatically establish money laundering. There may be an innocent explanation.
However, a monitoring system might identify the pattern for review because the account appears to be used primarily to move funds rather than participate in gambling.
A compliance analyst could examine the customer's transaction history, account information, payment method and other relevant indicators before determining whether further action is necessary.
This creates a technical challenge for operators and their fintech partners.
A system that generates too many false alerts increases manual review costs and can delay legitimate withdrawals. A system that misses relevant patterns can expose the business to financial-crime risks and regulatory consequences.
The objective is therefore not simply to block unusual payments. It is to identify activity requiring investigation while allowing legitimate transactions to proceed efficiently.
Canadian consumers are accustomed to fast digital payments, particularly through services such as Interac e-Transfer.
Yet a payment method capable of transferring funds quickly does not guarantee that a casino withdrawal will be completed immediately.
The withdrawal process may involve several separate stages.
First, the operator receives the request and checks whether the funds are available for withdrawal. The account may then be reviewed for identity-verification issues, payment-method consistency, fraud indicators or other compliance concerns.
If the transaction requires manual examination, the operator may need additional information before authorizing payment.
Only after the withdrawal is approved does the payment-processing and settlement stage begin.
The difference between these stages matters commercially.
A customer may interpret a delayed withdrawal as a problem with the payment provider when the transfer has not yet been released by the operator.
For fintech companies, clear transaction-status information and effective integration with compliance systems can reduce unnecessary support requests.
However, AML checks should not be treated as a universal explanation for slow withdrawals. Processing schedules, payment-provider limitations, account conditions and operational delays can also affect the time required.
Ontario and Alberta provide useful examples of how federal financial-crime obligations interact with provincial gambling frameworks.
Ontario's competitive online gambling market launched in April 2022. The Alcohol and Gaming Commission of Ontario (AGCO) regulates gaming operators and suppliers, while the province's conduct-and-manage structure determines how private companies participate.
AGCO's Registrar's Standards require operators to implement controls addressing unlawful activity, including relevant financial-crime risks.
Those requirements are distinct from FINTRAC's federal reporting obligations, even when they address similar risks.
An operator may need to demonstrate that its systems can detect suspicious activity and support the province's compliance framework without independently becoming the entity legally responsible for every FINTRAC casino report.
Alberta introduced its competitive iGaming market in July 2026, creating a second major Canadian market for private online gambling operators.
Although federal AML legislation applies nationally, the provincial arrangements governing operators, regulators and payment infrastructure are not necessarily identical.
That creates additional work for companies operating in both provinces.
Technology providers need to understand which organization is responsible for particular controls, what information must be exchanged and how reporting procedures fit into each province's operating model.
A payment platform built for Ontario may provide a useful foundation for Alberta, but it cannot assume that every contractual and regulatory responsibility transfers unchanged.
AML compliance is an operating expense as well as a regulatory obligation.
For gambling operators, costs can include identity-verification services, transaction-monitoring software, compliance personnel, employee training, independent reviews and record-management systems.
Payment providers may face additional expenses associated with their own regulatory classification and obligations.
The financial impact extends beyond direct spending.
When customers abandon registration because verification is difficult, operators lose potential business. When legitimate transactions are repeatedly flagged, customer-service workloads increase.
Delays can also affect customer trust, particularly when users receive little explanation about why a withdrawal is under review.
These problems create opportunities for specialized fintech providers.
Automated identity checks can reduce manual document handling. Transaction-monitoring platforms can identify patterns across large volumes of payments. Case-management systems can help compliance teams document investigations and maintain audit trails.
However, automation does not eliminate the need for professional judgement.
A system can identify unusual activity, but reporting decisions still require an assessment of the relevant facts and legal standards.
Businesses also need to consider data protection, cybersecurity and the reliability of third-party vendors.
Outsourcing a compliance function does not automatically transfer the reporting entity's legal responsibilities to the technology supplier.
Several technologies are becoming increasingly relevant to financial-crime controls in online gambling.
Digital identity systems can compare customer information against documents and other verification sources. Device and behavioural analytics may help detect account takeover attempts or coordinated fraudulent activity.
Transaction-monitoring systems can examine payment frequency, unusual funding patterns and relationships between accounts.
Some providers use machine learning to prioritize alerts and identify behaviour that traditional rules might overlook.
The commercial value of these technologies depends on measurable results.
A platform that identifies more suspicious activity but produces an overwhelming number of false positives may create additional work rather than reduce it.
Likewise, a faster onboarding process is not necessarily better if it weakens identity verification.
For Canadian fintech companies, the opportunity lies in helping gambling businesses meet their obligations while reducing unnecessary friction.
That requires integration with existing payment systems, clear audit records, configurable monitoring rules and an understanding of Canadian regulatory requirements.
It also requires attention to the distinction between anti-money-laundering monitoring and responsible gambling controls.
Both may examine customer behaviour, but they serve different purposes. AML monitoring focuses on potential financial crime, while responsible gambling systems identify indicators of gambling-related harm.
Combining relevant data can improve operational visibility, but the two functions should not be treated as interchangeable.
Canada's expanding online gambling industry is likely to increase demand for payment infrastructure and compliance technology.
More operators mean more accounts, deposits, withdrawals and transactions requiring appropriate controls.
But the growth opportunity is not simply about processing larger payment volumes.
Financial institutions and payment providers must determine whether they fall within FINTRAC's reporting framework, while gambling businesses must understand their responsibilities under the relevant provincial systems.
The businesses best positioned to serve this market will be those that can support reliable payments, effective financial-crime controls and a manageable customer experience.
For regulators, the challenge is maintaining oversight as technology and transaction methods evolve.
For fintech companies, the challenge is building systems that make compliance part of the payment process rather than an obstacle added after the transaction.
Canada's online gambling expansion is therefore also a test of its financial technology infrastructure. The companies moving the money, verifying customers and monitoring transactions will play an important role in how efficiently the industry operates.
GambleOnline.ca is an independent online gambling media website founded in 2008, publishing experience-based reviews, guides and analysis of online casinos, sportsbooks and poker platforms. Its editorial team conducts hands-on testing and research to provide factual, player-focused insights, alongside educational content on gambling strategy, legality and responsible play.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 10, 2026 | Last Updated: Oct 28, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Capital Markets Infrastructure And Funding, Cross Border Payments And FX, Cybersecurity Fraud And Financial Crime, Digital Assets Blockchain And Tokenization, Digital Banking And BaaS, Payments Infrastructure And Money Movement, Regulation And Policy, Wealthtech Investing And Trading, Risk Compliance And Regtech, Sustainable Finance ESG And Financial Inclusion

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-March 13, 2026, March 14-March 20, 2026, March 21-March 27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-June 19, 2026, June 20-June 26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-July 24, 2026, July 25-July 31, 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026, September 5-September 11, 2026, September 12-September 18, 2026, September 19-September 25, 2026, September 26-October 2, 2026, October 3-October 9, 2026).
Anthropic's lease gives EverWind a committed customer for its first development phase, strengthening the commercial case for a major Canadian infrastructure investment. But financing AI compute infrastructure depends on more than tenant demand. Power availability, construction costs and grid approvals determine when that demand becomes revenue. For investors, the distinction is between securing a customer today and delivering profitable computing capacity on schedule.
Hong Kong banks now have updated supervisory guidance for deploying AI, while future rules for autonomous agents remain under discussion. Banks investing in these systems need clear ownership of decisions, reliable input data and controls that allow staff to intervene. Canadian financial institutions face many of the same questions as they expand AI into lending, compliance and customer service. The operating advantage will depend on speed and cost savings that hold up under supervisory review.
TD is using AI to clear document checks at more stages of the mortgage process, freeing staff to handle exceptions and borrower decisions. The reported time savings are substantial, but lenders still need to measure end-to-end completion times, error rates and rework. The investment pays off when faster reviews translate into funded mortgages without weaker controls.
The first deadline arrives well before the settlement switch. Brokers, custodians and asset managers now need to reconcile message formats, client instructions and exception handling across counterparties. Canadian firms trading European securities face the same operational handoffs. A short settlement cycle leaves less room to repair missing allocations overnight.
Loan syndication involves years of servicing, amendments and lender coordination after the initial funding. Handling those events on a shared record could reduce duplicate reconciliations and disputes over loan status. The same operating question sits behind shared bank blockchain infrastructure: can participants keep one reliable record without adding new integration costs? Lenders will want evidence of repeat transactions before committing more capital.
Paid investor communities can create recurring revenue for crowdfunding platforms, but the fee can't become a barrier to understanding what investors are buying. Operators need to show enough deal information before collecting membership payments and explain exactly what those fees purchase. The bigger commercial issue is trust. Platforms that sell access before demonstrating investment value risk higher acquisition costs, complaints and regulatory scrutiny. A subscription model can work, but it still has to earn investors' money.
Longer trading hours change the conditions under which orders meet available liquidity. Marketplaces and brokers need controls that work when fewer orders are on the book and prices can travel farther on small trades. The consultation gives Canadian trading firms a chance to address threshold design before extended hours become a larger operational commitment.
BNY has demonstrated that tokenized market infrastructure can support real overnight financing, not just digital settlement. For dealers, the advantage could be faster access to collateral and lower funding friction. The economics depend on custody fees, connections to other counterparties and how often the process can be repeated at scale. One completed repo proves the workflow; regular volume would prove the business case.
The partnership tackles a central obstacle for tokenized funds: reaching investors through regulated broker dealer workflows they already use. Federated Hermes brings investment products; Prometheum would provide custody, clearing and brokerage connections. Managers and intermediaries will judge the offer by distribution costs, settlement performance and investor demand, not the use of tokens alone. The first fund remains planned for 2027.
Origin gives TXSE a publicly traded bank issuer and a practical chance to compete for U.S. listings. But a listing win is only the beginning. Brokers and investors will judge the exchange by trading depth, spreads, execution quality and reliable access to market data. Those measures will determine whether other issuers see a commercial reason to follow.
Evernorth offers stock market investors exposure to a company holding a large XRP treasury without requiring them to buy XRP directly. Its shares may trade at a premium or discount to the underlying assets. Investors should weigh treasury management, operating costs and future capital decisions against the simpler alternative of owning the asset itself.
Institutions can now manage traditional market exposure through a crypto trading venue when stock and futures exchanges are closed. That's a meaningful opening for firms that trade across time zones, but 24 hour access doesn't guarantee deep liquidity or better prices. Prime brokers and market makers will compare margin efficiency, weekend spreads and counterparty risk with established derivatives markets before moving significant volumes.
RPAA registration gives payment providers a defined route to serve Canadian businesses, along with continuing safeguarding and reporting duties. Payoneer can use that standing in discussions with customers and banking partners. For competing providers, the relevant costs extend beyond registration to the controls needed to maintain it.
The restrictions change how banks price rupee hedges and how companies manage currency exposure. Dealers face cash reserve costs and tighter checks on the transactions they can accept. Corporate treasury teams may need to reassess hedging across multiple banks, especially when a cancelled contract can no longer be rebooked. The immediate commercial impact is on liquidity and flexibility, not just compliance paperwork.
Payment infrastructure is now being treated as critical digital infrastructure with direct cyber obligations attached. For operators, this moves resilience from good practice into a formal compliance responsibility. Boards and technology teams need to know which systems are designated, who owns incident decisions and whether reporting can happen fast enough when a critical payment service fails.
Frontier AI is raising the standard of evidence supervisors expect when reviewing financial institutions' cyber resilience. Boards need visibility into where AI changes their threat exposure, which vendors create concentrated dependencies and whether recovery plans still work against faster attacks. The immediate operating priorities are vulnerability management, supplier assurance, incident testing and clear accountability before failures expose gaps.
FIS is taking an AI investigation tool from development into commercial banking operations. The potential savings are substantial because analysts spend considerable time gathering records before judging an alert. But banks still own the compliance decisions. Buyers should examine audit trails, false positives and completed case volumes before relying on projected productivity gains. For Canadian providers, the competitive pressure is on evidence quality and operating cost, not merely the number of alerts an AI system can review.
Fraud intelligence is becoming shared infrastructure rather than a control each institution builds alone. TrustGraph takes a different technical route from Canada's CSAFE fraud exchange, using cryptographic matching instead of pooling customer records. The commercial advantage grows with participation: more institutions create more opportunities to identify repeat attacks before fraud reaches another account.
Fraud often crosses the boundary between a mobile account and a bank account. CSAFE gives participating firms confirmed intelligence from both sides, helping them recognize repeat attacks sooner. The financial value will come from fewer losses and investigations without blocking legitimate customers. That depends on timely, accurate contributions and disciplined privacy controls.
The penalties show how failures in alert handling, correspondent banking controls and sanctions screening can become major financial liabilities. For banking executives, the response requires more than a larger compliance budget: investigations must be timely, findings must reach decision makers and remediation must work across business lines. Investors should track the cost and effectiveness of those repairs.
USDC's designation brings a major stablecoin under closer EU oversight of capital, reserves and redemption. Circle must now manage a split supervisory relationship, while banks and payment providers gain a clearer view of which authority oversees critical financial safeguards. For Canadian stablecoin operators, the decision shows how growing scale can change supervisory obligations even after a token enters the regulated market. Compliance costs and the confidence of institutional counterparties will matter together.
Authorization gives the bank consortium an important legal foundation for issuing a euro stablecoin. It does not yet provide a token that customers can use. Banks, exchanges and payment providers will evaluate redemption certainty, liquidity and integration costs once issuance begins. Broad institutional backing could support distribution, but demand still has to be earned.
Stablecoin operators increasingly need both digital asset and payment permissions when products cross from trading into money movement. Flowdesk can now combine MiCA services with PSD2 payment capabilities inside one European regulatory structure. For firms comparing international models with Canada's stablecoin framework, the operating question is how quickly multiple regulatory permissions can translate into custody, transfers and institutional volume.
Institutional stablecoin use depends on custody, transfer permissions and access to trading venues. Standard Chartered now offers a regulated custody option for RLUSD. Its proposed LMAX integration could let clients use collateral without moving it to an exchange. The commercial benefit will depend on funding efficiency, safeguards and the costs of operating across several counterparties.
A bank issuing digital money needs to know which tokens are still valid before paying holders back. Episode Six puts that check inside the bank's ledger at the point of redemption, where an error could turn into a direct loss. The commercial question is whether this control reduces reconciliation work and fraud without slowing payment flows. Banks still have to prove the reserves exist; software checks aren't a substitute for that obligation.
Buying Saldo could give Payward direct control over more European deposit and lending services instead of relying on bank partners for every product. The agreement is not ownership yet, and regulated banking brings capital and supervision costs. Once the deal closes, investors should watch customer uptake, funding costs and whether the combined businesses improve margins.
IKB would give Crédit Agricole an established German business lending franchise and relationships it would otherwise have to build customer by customer. That creates opportunities to offer existing borrowers more services and fund loans through a larger banking group. Returns will depend on credit quality, customer retention and integration expenses after closing.
Banks need reliable customer records to lend and open accounts across borders, but moving those records creates cost and privacy concerns. This platform lets participating institutions verify information without receiving the underlying files. That could shorten onboarding and credit checks for businesses operating in both markets. The next test is how many banks integrate it, what it costs per verification and whether customers see faster decisions.
Direct payment access could change the economics of launching a fintech in South Africa. Providers would have a route to clearing and settlement without depending on a sponsoring bank for every transaction. That could reduce intermediary costs and give new entrants more control over their services. The commercial opportunity now depends on licensing requirements, connection fees and how quickly the new infrastructure can support real transaction volume.
Stablecoin funding can help payment companies keep less idle cash in multiple accounts while supporting payouts outside traditional banking hours. Visa and Inyo now have a production service, but the financial gain depends on conversion costs, liquidity and the actual timing of settlement. Banks and payment fintechs should compare those economics with their existing prefunding arrangements before assuming round the clock access will improve margins.
Payment fintechs spend time and money negotiating access to the systems that move customer funds. A simpler rulebook could reduce duplicated compliance work and make access terms easier to challenge when incumbents impose costly conditions. But consolidation alone won't guarantee better access. Founders need to examine connection charges, technical requirements and the rights available when an operator refuses entry. Those details will determine whether the reform lowers the cost of competing or mainly reduces paperwork.
Mastercard is turning its BVNK acquisition into a distribution channel for businesses that need to hold, convert and pay in both bank money and stablecoins. A single integration may lower development and reconciliation costs for fintechs. But buyers will still compare pricing, available corridors and responsibility for funds across the service. The competitive question is whether bundled infrastructure delivers better working capital management than separate providers.
Local acceptance capacity gives merchants more than another foreign payment option. It can improve authorization routing and reconciliation where domestic rules differ. Nuvei already connects payment acceptance with enterprise invoice workflows; South African access extends the territory where that infrastructure can be sold. Merchant uptake and transaction performance will decide the return.
Owning licensed payment capacity changes Polygon’s role from infrastructure supplier toward a provider that can connect digital asset transfers to conventional money. It also adds a regulated distribution component to the stablecoin payment infrastructure opportunity. Customers will judge the combined platform by supported payment routes, settlement reliability and total cost, rather than token throughput alone.
Visa has gained a formal route toward operating in China’s domestic card market, but it cannot clear local transactions yet. The next milestones are the remaining approvals and connections with issuing banks, acquirers and merchants. Market share will depend on those relationships and the cost and quality of competing with established networks.
Payment providers could face an independent route for customer complaints, beyond their internal case handling. If adopted, membership would add costs for records, escalation and disputed transactions. Canada’s proposed open banking complaint requirements address related responsibilities for participants, although they are a separate regime. Firms selling payment and stablecoin services across borders need to cost customer redress into their operating model.
Listed companies need decisions about delayed disclosure to withstand scrutiny after information becomes public. The revised grounds offer more clarity, but they do not remove the obligation to assess confidentiality and investor impact in each case. Boards and legal teams should update decision records and approval procedures rather than treating the five additions as blanket exemptions.
Public companies must align earnings presentations, investor materials and financial statement notes before the reporting change. The CSA amendments apply to issuer disclosures, while separate IFRS 18 reporting changes affect federally regulated insurers. Finance teams should reconcile definitions across published measures and underlying accounts before disclosures reach investors.
The consultation puts detailed custody, settlement and capital proposals behind ASIC’s earlier digital asset licensing roadmap. Platform operators can now compare existing controls against draft requirements and price the cost of entering Australia. Firms must distinguish their responsibility for holding customer assets from their role in executing and settling trades.
Regulatory modernization could affect how quickly new financial products reach customers and how much compliance costs smaller entrants. The consultation gives fintechs and industry associations a chance to identify rules that impose costs without improving outcomes. The real test will be whether future supervisory reforms shorten approval timelines, reduce duplication and preserve financial safeguards.
Customer screening is now subject to closer scrutiny over why banks accept or decline legitimate businesses. Institutions need documented distinctions between lawful customer activity, financial crime risk and reputational judgments. For Canadian banks with US operations, policy review and audit evidence are practical priorities. Access decisions that cannot be defended consistently can carry supervisory and commercial costs.
The new safeguards require financial product distributors to prepare for tighter supervision of public sales activity. Firms should update staff training, customer consent records and controls over where representatives approach people. The transition period creates time to make those changes before MAS applies the revised guidelines.
GIFT IFSC is putting a clear accountability line around automated trading. A firm can use more advanced models, but it can't outsource responsibility to the software or its vendor. Brokers, trading firms and technology providers now have a concrete checklist for approval, testing, surveillance and shutdown controls before they scale automated strategies.
ASIC’s loss figures put pressure on brokers that rely on frequent, highly leveraged retail trading. The proposal could affect product terms, customer acquisition and dealing revenue if adopted. Platforms should assess those consequences now, while regulators consider whether the existing protections still address the products offered to retail investors.
European asset managers need to distinguish between holding companies with strong environmental credentials and demonstrating how investor capital contributes to measurable improvements. The supervisory examples also clarify how future transition promises should be explained and monitored. Canada's recent green taxonomy and investor trust debate addresses the complementary question of which activities qualify for sustainable financing in the first place.
The FSB has given financial institutions a common reference for assessing AI controls across business lines and technology providers. Banks and fintechs can compare their existing governance, vendor contracts, model inventories and monitoring against the final practices. The commercial challenge is keeping controls proportionate as AI adoption expands without making every deployment slower or more expensive.
Retail brokers cannot treat surveillance as a technology purchase and assume compliance is handled. Alert thresholds, investigation judgments and management review determine whether suspicious trading is escalated. NCFA’s market abuse risk research also covers more complex automated trading behavior. Brokers need case files and decision trails that stand up to supervisory examination.
This week brought production stablecoin payment services, a live €150 million blockchain loan and new rules for securities settlement and financial disclosures. Canadian firms also gained overseas payment access while domestic regulators advanced trading controls and reporting requirements. For founders, the opportunity lies in replacing costly operational steps with services customers will use repeatedly. Investors should look beyond launches to actual volumes, integration costs and the obligations that follow when a product becomes financial infrastructure.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets. Get the weekly Whisperer and related market intelligence through NCFA's newsletter, view the latest fintech insights, industry research, or launch into emerging financial innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 13, 2026

Image: Pexels/cotonbro studio
Anyone who works in payments or financial regulation knows that a ranking is only as useful as the criteria behind it. Credit scorecards, fintech league tables and bank surveys all produce a tidy ordered list, and the order changes the moment the weighting changes. Consumer reviews of online casinos follow the same logic, and the Canadian market, with its provincial patchwork of rules, is a good place to see it in action.
Take a recent Global News list of the best casinos in Canada, the methodology behind it included, as a worked example. Two reviewers can look at the same group of licensed sites and rank them differently without either one being wrong, simply because they chose different questions to ask. Understanding which questions were asked is the real skill for a reader.
Before any comparison begins, a credible review has to settle a threshold question: is the site permitted to serve players in the reader's province? In Ontario the answer is relatively well defined. Operators must be registered with the Alcohol and Gaming Commission of Ontario (AGCO) and must have an operating agreement with iGaming Ontario, and the regulator and the commercial entity are kept separate. As of September this year iGaming Ontario reported 49 operators running 84 gaming websites in the regulated market, and players must be 19 or older and physically located in Ontario to play.
Outside Ontario the picture is different, since provinces run their own platforms and age thresholds vary. A review written for a national audience has to decide early whether it is ranking sites for one province, several, or the whole country. That single scoping decision can reorder a list more than any later scoring step.
Most Canadian casino reviews draw from a similar pool of criteria:
Licensing and oversight. Does the site operate under a recognized regulator, and can a reader verify that on the regulator's own pages rather than taking the reviewer's word for it? Game library and software suppliers. Breadth of titles, the studios behind them and how often the catalogue is refreshed.
Payments and withdrawals. Which methods are supported, what the published limits and processing times are, and how clearly identity checks are explained. A fintech reader will find the questions familiar: settlement time, fees, reversibility and verification friction.
Player protection tools. Deposit limits, time reminders, self-exclusion and clear links to support services. Usability. Mobile performance, account management and customer service.
A reviewer who gives payments 30 per cent of the score will produce a different order from one who gives it 10 per cent. Neither approach is dishonest. The problem arises only when the weighting is hidden.
Payment rails are changing in Canada, and that has consequences for any review that scores speed. The national system behind the shift is the Real-Time Rail, which Payments Canada describes as a new real-time exchange and clearing and settlement system that supports instant, data-rich payments, with a launch scheduled for the final quarter of this year. Round-the-clock availability is a different proposition from the business-day batches many consumers still associate with bank transfers.
NCFA Canada's recent look at how Canadians pay is a useful reminder that cards still account for most payment volume while electronic funds transfers carry most of the value, and that expectations are shifting as real-time payments approach.
For casino reviews, the practical lesson is caution. A score for "fast withdrawals" written under one payments environment may not hold under another, and a review that does not say when and how withdrawal times were assessed is difficult to compare with one that does.
When a reader has two published lists in front of them, a short checklist helps.
First, look for the date of the last update, since licensing status, supplier relationships and payment options all change. Second, look for a plain description of how sites were selected and scored, including what was excluded. Third, see whether the review separates facts that can be verified with a regulator from impressions formed during testing. Fourth, check whether the scoring covers player protection with the same seriousness as it covers games and convenience.
Differences in rank often trace back to one of these points. A site placed third on a list that rewards game variety may fall to seventh on one that rewards transparent withdrawal terms, and both lists can be defensible.
The wider lesson is one that regulators and fintech analysts have been making for years: transparency about method is a form of consumer protection. A ranking that shows its weighting lets the reader adjust it to their own priorities, while one that keeps the weighting private asks for trust it has not earned. Canadian readers who treat any list of top casinos as a starting point, and who confirm licensing directly with the AGCO, iGaming Ontario or their own provincial regulator, will be better placed than those who treat the order as a verdict.
Gambling is for adults only, and anyone who finds it is no longer enjoyable can look to the support information published by their provincial regulator.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 12, 2026 | Tokenization, Private Markets, Digital Securities, Investment Operations

The first payment, the first transfer request and the first mistake reveal whether a platform is ready for real investors.
By Asset Haus Editorial Team
Imagine the first interest payment on a tokenized private-credit investment is due on Friday. By Monday, an investor has received nothing. The portal shows a holding, but no explanation. The technology team says the system is working. The administrator is waiting for instructions. The issuer thought the payment was automatic.
Nobody needs a faster blockchain at that moment. They need someone who knows where the money is, what has happened and who can put it right.
That situation is hypothetical, but it is a useful starting point for designing a tokenized deal. Begin with an ordinary investor question and work backwards until every part of the answer has an owner.
The practical groundwork is becoming more explicit. In April 2026, the UK's Financial Conduct Authority published guidance on fund tokenisation, explaining how firms can use distributed ledger technology within its existing rules. Alongside it came an optional model allowing investors to deal directly with a fund. These are UK developments, not a universal rulebook, but they put attention on how funds actually operate.
Before choosing a network or designing an investor portal, write a plain-language answer to one question: what exactly is being sold?
A token might represent shares in a company, units in a fund or a debt instrument. An investor holding a note issued by a property-owning company is not necessarily a direct owner of the building. That distinction affects what they can demand, from whom, and on what terms.
In its January 2026 statement on tokenized securities, U.S. SEC staff distinguished between issuer-sponsored and third-party tokenization models, noting that the rights involved can differ. The staff also reiterated that recording a security on a blockchain does not remove it from federal securities law. This was a staff statement, not a new Commission rule.
For an operator, the next step is straightforward: make the investment documents and the portal tell the same story. Explain the payment terms, voting rights, transfer restrictions and what happens if the investment goes wrong. Have counsel confirm the legal position in the relevant jurisdictions before translating it into software.
Consider a fictional investment vehicle raising $12 million to finance business loans. Its portal collects investor details, runs identity checks and accepts subscription requests.
One investor completes the checks and sees a green tick. What does that tick mean?
It might mean their identity has been verified. It should not silently mean that they qualify for this offering, have received an allocation, signed the current documents and paid in full. Those are separate questions.
For this example, assign someone to review eligibility, someone to accept subscriptions and someone to confirm payment. One organization may handle several jobs; the important point is to record who has authority to make each decision.
The technology should make that division easy to follow. An investor waiting for approval should see a pending application, not a completed investment. Staff should see what is missing and who needs to act next.
Keep the approvals with the transaction record. Six months later, the team should be able to explain why an investor was admitted without searching an employee's old inbox.
Now suppose that investor sends the money. The bank confirms receipt, but the transfer carries the wrong reference. Or the payment arrives after the allocation has changed.
Neither problem is solved by displaying a wallet balance. In our example, somebody must match the money to the subscription, resolve the discrepancy and authorize the next step.
The parties should also agree which record establishes the holding. SEC staff's January statement describes both models that integrate blockchain records into the main ownership register and models that use blockchain activity to trigger updates elsewhere. The choice needs to be explicit; two conflicting records are not useful redundancy.
There is promising work on coordination. The BIS's Project Agorá results, published in May 2026, demonstrated a prototype for programmable cross-border payments using tokenized central bank reserves and commercial bank deposits. It is a wholesale payments project, not a ready-made solution for a private fund. Still, it illustrates why payment design deserves as much attention as issuing the asset.
For a smaller operator, a sensible first target is a reliable sequence: approved subscription, confirmed payment, recorded holding, investor confirmation. Automate that sequence where possible, with a clear route for exceptions.
Six months later, our investor wants to sell. The token is technically transferable. That is only the beginning of the sale.
Assume the deal documents require the issuer's consent and an eligible purchaser. The operator still needs to review the proposed buyer, arrange payment and update the records. A willing buyer also has to accept the price.
It would therefore be misleading to present this particular investment as liquid simply because the portal supports transfers. The process may be easier to administer, while the underlying investment remains difficult to sell.
The product can make an honest, useful promise instead: investors will know how to request a transfer, what conditions apply and where the request stands. A clear process is worth having even when completion cannot be promised.
For teams mapping this process, Asset Haus sets out a practical breakdown of private-market workflows, from investor access through administration and controlled transfers. It is a useful starting point for deciding which tasks belong in the platform and which require an authorized decision-maker.
Return to the missed interest payment. A launch plan should already say who calculates the amount, who confirms available funds, who authorizes payment and who tells investors about a delay.
Give those people access to the information they need. The administrator should not have to ask a developer for an investor statement, and the developer should not be expected to decide whether a disputed distribution is payable.
Budget for this work beyond issuance. Before signing a platform agreement, price the ongoing reporting, payment processing, support and changes to investor records. A cheap launch is less attractive if every routine update becomes a separate development project.
Then consider what happens when a provider leaves. Can the operator export the records in a usable format? Who controls the relevant accounts and signing permissions? Is there a documented recovery process, or could a lost key leave an investor without a workable remedy? Establish what recovery is actually possible rather than promising that every problem can be reversed.
For operators running several deals a year, this is also where a repeatable process can earn its keep. Reuse tested procedures and integrations, while checking the terms and approvals for each new offering.
Before launch, put the issuer, administrator and technology team in one room. Walk through a test subscription from application to the first scheduled payment.
Then make the test less comfortable. Submit an outdated document. Send the wrong amount. Request a transfer to an ineligible buyer. Make the usual approver unavailable for a day.
Watch what happens. Does the system stop at the right point? Can the replacement approver find the evidence? Does the investor receive a useful explanation? Can the team correct the mistake without losing the history?
A dress rehearsal like this will not prove that every risk has been covered. It can reveal an unassigned task before real money depends on it.
The goal is a deal that people can understand and a team that can run it for its full life. When that Monday-morning question arrives, the investor should get an answer, not a tour of the supplier list.
Asset Haus provides software and operating infrastructure for private-market transactions. This article is general information, not legal or investment advice. The transaction example is hypothetical.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
October 9, 2026 | Last Updated: October 12, 2026 | Companies On The Move, Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization

On October 9, 2026, TruGolf Holdings (Nasdaq: TRUG) confirmed its acquisition of Toronto's Polymath Research Inc., the Canadian fintech behind Polymesh, a blockchain for regulated securities. Polymath is now a wholly owned subsidiary and will continue serving institutional tokenization customers alongside TruGolf's golf simulation and software businesses. The companies also plan tokenized equipment leasing and fractional franchise ownership products for Q1 2027.
The acquisition gives Polymath access to a U.S. public company and an operating business with equipment and franchise financing needs. TruGolf gains established securities technology, existing issuer relationships and another potential source of revenue beyond golf products. Both businesses will continue operating while developing the proposed financing applications.
Founded in 2017, Polymath developed the ST-20 security token standard and contributed to ERC-1400. Its Polymesh blockchain supports identity verification, transfer restrictions, settlement and securities administration. These controls help issuers determine who can hold or transfer securities and manage compliance obligations after issuance. Polymath serves markets including private equity, credit, real estate and investment funds.
As of December 31, 2025, Polymath reported more than $132 million in cumulative tokenized assets issued, over 65 active issuers and more than 50 ecosystem partners. The announcement doesn't identify the currency of the issuance figure, which represents historical issuance rather than current holdings or revenue. Polymesh also reported SOC 2 Type 1 status in 2025, following an independent assessment of specified security controls.
Polymath has already pursued securities distribution through arrangements such as its Polymath and Dalmore capital raising partnership. TruGolf provides an additional commercial application without replacing those institutional relationships.
TruGolf Links and Polymath are developing two financing products for the first quarter of 2027. One would fund equipment leasing through tokenized securities. The other would offer qualified participants fractional ownership opportunities in TruGolf franchises.
Natalie Hirsch, CFO and COO of TruGolf and Interim CEO and CFO of Polymath:
"Polymath was built in Toronto to bring regulated assets on-chain the right way, with compliance at the protocol level. Joining TruGolf puts that infrastructure inside a Nasdaq-listed company, and our first joint project, tokenized equipment leasing and fractional franchise ownership for TruGolf Links franchisees, shows how a real operating business can use it."
TruGolf reports commitments from regional developers covering more than 100 future franchise locations across New Jersey, New York and Illinois. Those commitments don't represent completed locations or confirmed investment demand. Equipment financing depends on asset values, lease payments and credit performance, while franchise investment adds operating and ownership risks. Blockchain records don't change the economics of the underlying businesses.
The company must determine whether tokenized equipment leasing and franchise investments can attract enough capital to justify their issuance, compliance and servicing costs. Polymath already supports an established network of securities issuers, but these new applications introduce different financing needs and investor risks. The business case depends on whether TruGolf can secure financing on competitive terms while Polymath earns additional revenue from issuing and administering the securities.
TruGolf structured the acquisition using Class A common shares and Series C preferred shares for former Polymath shareholders. Its August SEC acquisition filing uses a US$140 million reference amount in the preferred share consideration formula, not a confirmed cash purchase price or final acquisition valuation. Polymath joined an existing Nasdaq company rather than complete its own IPO.
The firms acquisition agreement also requires the company to reserve US$2.5 million in working capital for Polymath operations, public company compliance and transaction expenses. On October 7, investors exercised warrants for 3,278 Series B preferred shares, generating US$2.95 million in net proceeds for TruGolf. This financing was separate from the Class A common shares and Series C preferred shares issued to former Polymath shareholders. The Series B preferred shares can convert into TruGolf common stock, subject to ownership restrictions and Nasdaq rules, potentially reducing existing shareholders' percentage ownership.
TruGolf appointed Natalie Hirsch as CFO and COO following the acquisition. She continues as Polymath's interim CEO and CFO, while David Hackett has joined TruGolf's board. Hirsch now oversees financial and operating responsibilities across the two businesses. For Canadian fintech founders, the transaction demonstrates a route into public markets through acquisition, although the combined company must manage additional reporting costs, capital requirements and investor expectations.
Polymath's institutional tokenization business now operates within a Nasdaq company with its own financing needs. The proposed equipment leasing and franchise products offer an opportunity to demonstrate whether regulated digital securities can compete with conventional business financing. Can TruGolf lower financing costs for its equipment and franchise operations while Polymath generates recurring revenue from securities issuance and administration?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Oct 3, 2026 | Last Updated: Oct 20, 2026 | NCFA Fintech Whisperer | Artificial Intelligence And Data, Digital Banking And BaaS, Capital Markets Infrastructure And Funding, Wealthtech Investing And Trading, Cross Border Payments And FX, Payments Infrastructure And Money Movement, Cybersecurity Fraud And Financial Crime, Regulation And Policy, Risk Compliance And Regtech, Embedded Finance, Lending Consumer Credit And BNPL, Treasury Liquidity And Cash Management, Digital Assets Blockchain And Tokenization, Digital Identity And Trust
] Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026, January 31-February 6, 2026, February 7-13, 2026, February 14-20, 2026, February 21-27, 2026, February 28-March 6, 2026, March 7-March 13, 2026, March 14-March 20, 2026, March 21-March 27, 2026, March 28-April 3, 2026, April 4-10, 2026, April 11-17, 2026, April 18-24, 2026, April 25-May 1, 2026, May 2-8, 2026, May 9-15, 2026, May 16-22, 2026, May 23-29, 2026, May 30-June 5, 2026, June 6-12, 2026, June 13-June 19, 2026, June 20-June 26, 2026, June 27-July 3, 2026, July 4-July 10, 2026, July 11-July 17, 2026, July 18-July 24, 2026, July 25-July 31, 2026, August 1-August 7, 2026, August 8-August 14, 2026, August 15-August 21, 2026, August 22-August 28, 2026, August 29-September 4, 2026, September 5-September 11, 2026, September 12-September 18, 2026, September 19-September 25, 2026, September 26-October 2, 2026).
Canadian banks and insurers now have a clearer view of what OSFI expects them to manage as frontier AI moves into financial operations. Firms will need evidence that they can test advanced models, understand critical dependencies and assign responsibility when AI affects important services.
Modern Treasury is trying to move from orchestrating regulated money movement to owning a federally supervised custody capability. That extends the strategy behind its earlier integrated payment infrastructure and would give the company more direct control over custody, settlement and the service boundary between fintech infrastructure and bank partners.
Rain is seeking to put custody, reserve management and stablecoin issuance inside a federally supervised institution rather than relying on separate providers for each function. Approval would give its fintech and enterprise customers a more direct regulated path from stablecoin infrastructure to banking controls.
A licensed bank is putting external wallet activity inside the same operating environment as fiat accounts. That makes blockchain screening, address verification and conversion part of the banking control stack and gives customers a regulated route between bank balances and self custody without routing every transfer through a separate crypto platform.
Client money accounts and reconciliation are core operating controls for a regulated exchange, not peripheral banking services. Bringing those functions into a CBB regulated bank relationship gives Rain a more direct operating path for safeguarding customer funds and managing liquidity as its regional business grows.
A mobile money operator with a major African distribution footprint is entering public markets as a separately traded financial platform. Investors can value payments, digital wallets and related services independently from the parent’s telecom business. The deal also tests public-market appetite for financial inclusion businesses with extensive networks and operating exposure across African jurisdictions.
Tokenized U.S. equities have moved from venue design into a live regulated product available to eligible investors. Securitize is combining conventional share backing and investor rights with blockchain settlement, giving the market a practical test of whether tokenized stocks can expand without separating investors from the legal rights attached to the underlying shares.
Earned wage access providers must finance payments to employees before the employer's scheduled payroll date. DailyPay's second securitization expands that capacity and gives institutional investors another way to fund short duration payroll receivables. For fintech lenders and funding partners, the important question is whether access to asset-backed financing can reduce capital costs enough to support growth while keeping funding available through weaker credit markets.
The bond puts a regulated yen stablecoin into the full payment lifecycle of a conventional financing instrument. If the model works operationally, issuers can test stablecoin settlement against familiar corporate debt obligations rather than limiting use to transfers, trading or standalone token experiments.
RBC’s participation gives Canadian capital markets expertise a direct role in a sovereign issuance experiment, not just a vendor demonstration. For dealers, custodians and infrastructure providers, the practical questions are how digital securities enter established distribution channels and who controls the asset record, settlement and post-issuance servicing.
An institutional tokenized liquidity product that already operated in Switzerland now has a licensed access route in Singapore. The expansion tests whether tokenized cash management products can move across regulated entities and jurisdictions without rebuilding the underlying issuance and administration infrastructure each time.
Exchange operators have a narrowly defined window to alter an existing contract structure, but only with procedural safeguards for participants. The relief provides a near-term test of how regulators handle continuous futures exposure and legacy open positions. Firms should focus on the eligibility conditions and deadline rather than extrapolate a general approval of perpetual derivatives.
The SEC's five year pathway for tokenized U.S. stock trading now has a concrete venue design behind it. OKXICE combines permissioned wallets, stablecoin settlement, automated liquidity and broker held share backing, turning an exemption into an operating model that other tokenized securities venues can be measured against.
Remote onboarding is becoming a larger fraud control and technology migration issue for Japanese financial institutions. Banks and fintechs need to test how document authentication, chip reading, customer identity verification and fraud monitoring work together. Providers still relying on uploaded document images face a concrete transition deadline, while recent breaches put pressure on firms to tighten controls sooner.
Thailand has moved from consultation to a defined route for domestic crypto investment funds. Asset managers, custodians and brokers now have clearer operating requirements, although fund approvals and individual product launches still lie ahead. The limits on eligible assets, custody and leverage will influence which firms can compete and how much crypto investment activity enters regulated capital markets.
Liquidity promises and asset liquidity have to match. Fund managers and distributors should compare proposed redemption terms with actual asset disposal periods, investor expectations and the operations of savings wrappers. For private market access products, the consultation adds another regulatory reference point for designing redemption rights before fundraising begins.
A startup can test a defined investment advice offering through an existing regulatory exemption without claiming general permission to automate every advice function. The useful comparison for Canadian wealthtech founders is how sandbox scope, product limitations and retail safeguards affect the journey from prototype to licensed distribution. Evidence of live advice quality and client outcomes remains a separate test.
This is no longer only a financing story. A major Canadian pension investor is using board influence and management changes as FNZ works to improve delivery and profitability. For private fintech investors, the case shows what ownership can require when a large platform needs more capital and investors cannot rely on an easy exit.
Digital asset markets already trade continuously while fiat funding still depends heavily on bank cutoffs. Connecting a regulated bank clearing network directly to institutional digital asset infrastructure reduces that timing gap and gives participating firms a more continuous way to manage settlement, liquidity and counterparty funding.
Resilience is becoming a card-issuance and terminal-procurement requirement, not merely a contingency plan. Issuers, acquirers and merchants need to examine device capabilities, authorization limits and reconciliation processes before replacement cycles lock in incompatible equipment. Canadian payment providers should consider how outage tolerance is built into their own acceptance infrastructure.
BDO is consolidating domestic and international payment processing around one operating layer rather than maintaining separate systems for each rail. That can make it easier to add networks, apply common controls and automate routing as payment formats and clearing requirements change.
Banks now have to defend against attackers who can automate parts of vulnerability research and intrusion work that previously required more manual effort. The campaign makes agentic AI a live financial security problem, not only a future model risk, and raises the value of rapid detection across shared infrastructure and third party systems.
The proposal would change who supervises major trading and post-trading infrastructure and how firms expand across EU borders. Exchanges, fund operators and crypto providers need to examine the proposed significance thresholds and licensing options, not assume that every institution will face the same supervisor. For Canadian firms entering Europe, the eventual perimeter could materially affect expansion costs.
This gives EU crypto firms a concrete operating deadline rather than a general warning about unauthorized stablecoins. Platforms need controls that can identify affected tokens, restrict new exposure and manage existing positions across trading, custody and transfer services.
Dealers need to identify contracts and compensation schedules that expose representatives to redemption-related clawbacks and prepare for the new requirements. The compliance question reaches beyond disclosure: compensation design itself can influence recommendations and client outcomes. Canadian investment platforms and distributors should check how their adviser agreements and oversight controls need to change.
A dedicated federal market category could change the choice between existing derivatives venues and new crypto trading infrastructure. Exchanges and brokers should assess which products fall inside the transaction definitions and what market surveillance, registration and customer controls may follow. The consultation is an early opportunity to influence the rules before firms commit to a licensing model.
Crypto exchanges, custodians and other financial intermediaries now have greater clarity about two compliance proposals that will not proceed in their existing form. The withdrawals remove potential additional reporting and verification requirements while leaving established anti-money laundering obligations intact. For firms serving U.S. customers, the decision affects compliance planning and investment in transaction monitoring, particularly where digital asset activity involves self-hosted wallets or mixing services.
A compliance program designed around a small deposit business cannot be assumed sufficient for a much larger card network exposure. Banks and payment companies need risk assessments that match actual transaction flows, backed by staff capacity, independent testing and timely escalation. The coordinated orders also underline how failures across related entities can become a group-wide supervisory issue.
Institutions now have a defined preparation period to identify where AI enters customer decisions, critical operations and outsourced services. Model inventories, accountable owners and evidence of controls will need to stand up to supervisory review. The comparison for Canadian institutions is how OSFI’s principles translate into documented practices alongside the more explicit Singapore requirements.
Institutional risk infrastructure is forming around onchain credit markets as capital moves into lending vaults. A standardized external assessment gives allocators another way to compare structures that differ in credit quality, liquidity, protocol exposure and governance, which can influence which vaults become investable for larger institutions.
Adding regulated stablecoins to an ERP payment workflow brings programmable stablecoin payments closer to routine corporate finance. Businesses can test digital currency settlement inside the same systems already used for invoices, payment approval and reconciliation instead of building a separate crypto payment process.
Plaid is moving beyond account connectivity into the decision layer of lending. The same permissioned financial data infrastructure used to connect accounts can now feed regulated underwriting, giving Plaid a larger role in how lenders translate open banking data into approvals, pricing and credit limits.
Experian is turning permissioned bank transaction data into formal consumer reporting infrastructure rather than treating cash flow as an additional analytics product. That gives lenders a regulated path to combine traditional credit files with current financial behaviour and moves open banking data deeper into mainstream underwriting architecture.
Treasurers are gaining a way to reposition bank liquidity outside normal banking cutoffs while retaining a commercial bank deposit relationship. The operational work shifts to liquidity controls, access permissions, currency coverage and reconciliation across group entities. The important expansion test is whether the model can extend to more banks and corporate customers.
The pilot extends an already live bank tokenized deposit network into a new treasury region and cross border corridor. For multinational companies, the operating question is whether these networks can make liquidity movable across markets and currencies in real time without creating a separate treasury stack outside existing banking relationships.
The registration system is turning a statutory crypto market perimeter into an operating set of authorized firms. Custody and dealing permissions differ, so counterparties need to understand precisely which activities each entity can perform. For foreign institutions, jurisdictional restrictions and sanctions considerations remain separate from the existence of a domestic registration.
More companies can now offer financial services without owning the infrastructure behind them. That opens opportunities for smaller firms, but it also puts pressure on margins and leaves critical parts of the customer experience in someone else's hands. Canadian founders and investors need to look closely at where profits accumulate, who controls distribution and whether growing transaction volumes actually improve the economics of the business.
Follow the next developments in NCFA’s newsletter, browse fintech coverage and industry research, or review innovation opportunities.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer to peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016