




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


February 11, 2026
Image: Unsplash/Dylan Nolte
The first quarter of 2026 has already proven to be a life-changing period for many Quebecers. With massive jackpots and special gala events, the excitement surrounding the weekly draws is at an all-time high. For those who play regularly, keeping a close eye on the latest winning numbers is crucial. Whether you are holding a ticket for Lotto Max, Lotto 6/49, or the iconic Célébration gala, the next draw could be your turn to join the winner's circle.
To verify your numbers against the official database, you can always check the latest updates at Loto-Québec Canada.
The month of February has seen several significant draws. Here is a look at the recent results for the major games:
If you participated in secondary draws or have non-winning tickets, don't forget to look for a loto-québec login or a "Second Chance" entry. Many players overlook these additional opportunities to win cash prizes ranging from $500 to $5,000.
In 2026, checking your results is faster and more reliable than ever. Loto-Québec has streamlined its digital tools to provide instant feedback:
One of the most heart-warming stories of the year involves Katelyn Abbey and Philip Cutler. The Montreal couple had been buying Célébration tickets for five years as gifts and for themselves. While vacationing abroad in early February, they checked the results online and realized they had won the $5,000,000 top prize. Their story reminds us that even when you are far from home, a life-changing win is only a click away.
| Draw Date | Game Type | Jackpot Status |
| Feb 10, 2026 | Lotto Max | $40 Million (Pending Claim) |
| Feb 11, 2026 | Gold Ball 6/49 | $28 Million (Estimated) |
| Jan 11, 2026 | Célébration Gala | $5 Million (Claimed) |
If you find that your numbers match, congratulations! Remember that prizes must be claimed within one year of the draw date. For prizes over $25,000, winners typically need to make an appointment at a regional office. For smaller wins and digital play, you can often find information on automated payouts through the Loto-Québec bonus and prize-claim sections online.
Stay lucky, keep your tickets safe, and always check twice!
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
February 10, 2026
Canada’s digital economy is on the rise, and many sectors are at the forefront of that growth and innovation. In 2025, we see certain key industries come into their own as the primary forces behind Canada’s digital transformation and global competitiveness.
The telecommunications industry is the primary driver of Canada’s digital economy, which in 2024 reported a $87.3 billion contribution to the Canadian GDP. Reports from the International Trade Administration indicate that Canada’s digital economy is expected to grow at a 9% compound annual growth rate through 2025, and that telecom infrastructure is the basis for that growth.
Mobile is at 55.2% of total telecom revenues, while fixed internet is at 28% of the market. With that strong base, Canadian businesses have been quick to adopt digital technologies, which the entertainment sector has in particular profited from. In the growth of digital entertainment, which includes the increasing online slot games market, we see how the telecom infrastructure supports a variety of digital business models across the country.
Canadian telecom players have outperformed global competitors due to having built world-class networks that place them at the forefront of digital adoption. This strategic play will see Canada as a hub for 5G and fibre optic expansion projects, which in turn will fuel growth in 2025 and beyond.
Things are hot for Canada’s fintech industry, and 2025 is no exception. Global fintech markets are growing at 3% according to recent reports, and Canada is part of that growth, with AI, B2B, and new lending platforms driving the sector. What’s more, there are 84 companies in Canada operating in different subsectors with corporate partnerships and/or venture capital funding.
According to PwC’s Canadian fintech report, this means high levels of investor confidence in fintech and lots of funding going into startups in digital payments, blockchain and regulatory technology and more. This is the case with Canada’s prepaid cards and digital wallets, where it’s expected to grow 6.7% per year to $26.26 billion by 2025. This is due to shifting consumer behaviour towards digital payment solutions and the maturity of Canadian fintech globally.
The digital entertainment and gaming sector is one of Canada’s fastest-growing digital economy segments. Canada’s digital gaming audience will reach 20 million users by 2025—that’s half of the country’s population.
Canadian gaming companies are using advanced tech to create experiences that appeal to domestic and international markets. The industry is supported by solid telecommunications infrastructure, and consumers are getting more comfortable with digital entertainment platforms. Gaming demographics are young and highly engaged, which means sustainable revenue and export opportunities.
The entertainment sector goes beyond gaming to include streaming services, digital media production and interactive content creation. This diversification makes Canada a major player in the global digital entertainment economy, with Toronto and Vancouver becoming major hubs for digital content production.
Digital health has been a game-changer for Canada’s healthcare system and economy. It includes telemedicine, health information systems, medical device connectivity and data analytics platforms that improve patient outcomes and reduce costs. Now, Canadian digital health companies are developing solutions for domestic healthcare challenges and export markets.
Artificial intelligence and machine learning in healthcare applications have accelerated in 2025, and Canadian companies are leading the way in medical imaging analysis, predictive diagnostics, and personalized treatment platforms. Government support for digital health initiatives—including funding for health technology research and development—has also created an environment for innovation and growth.
Provincial health systems are adopting digital solutions and creating demand for homegrown technology and expertise. This domestic market has become a testing ground for Canadian digital health companies to test solutions that can then be scaled for international markets and generate export revenue and leadership.
Combined, the top industries represent a multiplier for Canada’s digital economy. Fintech, entertainment and gaming companies have large telecommunications infrastructures’ needs for complex connectivity services. Fintech payments and strong data networks have oriented digital health solutions.
Ramping up investments in advanced manufacturing, critical minerals, and digital infrastructure will ensure Canada remains competitive. This emphasis on leveraging federal government support to drive competitiveness via investments in emerging technologies will also lead to growth.
Canada’s digital economy in 2025 is led by the telecommunications infrastructure, fintech, entertainment, gaming, and digital health sectors. They also enhance national growth and national competitiveness in the international arena.
These industries are part of the reason Canada’s digital economy is expected to have a 9% compound annual growth rate through 2025. Together, they are the ones that will ensure Canada’s place and success in the digital economy.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 6, 2026 | NCFA Fintech Whisperer Weekly Intelligence | Capital Markets And Market Infrastructure, Digital Assets Blockchain And Tokenization, Risk Compliance And Regtech

Image: Freepik
This live weekly NCFA intelligence page tracks financial technology developments that significantly affect how fintechs build, sell, raise capital, and operate under scrutiny. Coverage prioritizes Canada and includes global events that directly influence competitive conditions, market access, and execution realities across fintech sectors. This page will be updated throughout the week with market movers in a live format and then each week we'll close the prior week's contents in prep for the upcoming week, and continue on a rolling basis. (Missed prior week's Fintech Whisperer? (December 6-12, 2025, December 13-19, 2025, January 1-9, 2026, January 10-16, 2026, January 17-23, 2026, January 24-30, 2026).
The hard part isn't moving money, it's proving every step. Teams that package premium flows with clean records and clear controls can earn carrier trust faster and grow without drowning in back office work.
This rule draws a hard line around who owns the onshore asset, who carries the filing burden, and what gets blocked before a token ever reaches the market. For founders building real world asset tokenization rails, this pushes compliance into the product spec, not the legal appendix. For investors and institutions, it also hints at where future supply can actually clear, which issuers can survive the documentation load, and which token structures will get rejected early.
This deal pushes tokenized gold closer to mainstream rails. Wallets and platforms now face tougher buyer questions on custody, redemption, and who controls the customer relationship at conversion.
Platforms that want to scale under Canadian dealer oversight now need custody choices, contracts, and segregation controls that hold up under faster and more explicit supervision.
Stablecoin rewards now sit on the critical path for US rules. Fintech teams that sell payments, custody, compliance, or market infrastructure into US regulated buyers should expect procurement questions to lock onto rewards design, reserve treatment, and where yield can legally sit in the stack.
A limited first cohort can steer who wins distribution and which stablecoin infrastructure stacks become the default for partners and platforms.
UK buyers will treat payments as national infrastructure, not a feature set. Fintechs that win distribution will show they can plug into policy goals on resilience, competition, and security while still shipping product fast.
This changes the bar for anyone selling account to account payments, open banking rails, fraud controls, or programmable payments. Founders should align roadmaps to the coming scheme design work and the Spring consultations the Bank flags, because UK infrastructure choices will shape product requirements for years.
This matters for any stablecoin issuer and infrastructure provider that wants institutional distribution. When regulators expand who can issue an eligible payment stablecoin for margin collateral use, counterparties get a clearer path to treat certain stablecoins as real plumbing inside regulated derivatives workflows. Fintechs that sell custody, collateral management, settlement, and stablecoin compliance can use this to anchor partner conversations around issuer structure, segregation controls, and how tokenized collateral actually clears inside regulated accounts.
This deadline forces teams that rely on Switzerland for issuance or operations to lock in licensing and controls early. Partners will push for clear governance, clean reserve treatment, and cross border compliance that holds up under scrutiny.
Fintech teams feel this through tighter budgets, higher buyer scrutiny, and more demand for products that raise productivity inside core financial workflows, especially in trade, credit, risk, and compliance.
Stress scenarios push banks to revisit credit appetite, model controls, and operational risk tolerance.
This deadline matters to fintechs that serve high net worth users, wealth platforms, brokers, and crypto firms that want UK market access. Teams that treat categorisation and conflicts as product logic, not legal text, will cut future remediation cost and speed up institutional partnerships.
OSFI sets an execution timetable that forces bank and fintech partners to treat prudential policy as a product requirement. Teams that sell underwriting, credit risk, treasury, or compliance tooling into federally regulated institutions will face tighter questions on governance ownership, model controls, and liquidity evidence.
This creates a real bottleneck for financings and time sensitive filings. Operators win time when they build buffer into launch plans, keep disclosure ready ahead of pricing, and avoid dependencies on last minute staff action.
Stablecoin rewards now sit in the middle of a real fight between banks and crypto firms, and that fight can decide how fast regulated buyers adopt stablecoin rails. In Canada, CIRO puts sharper expectations on digital asset custody, which raises the bar on contracts, segregation, and proof of control for any platform that wants to scale. In the UK, the payments roadmap starts to look like a build plan, not a wish list, and conduct rules keep moving into onboarding logic and product decisions. This week rewards teams that treat controls and governance as part of the product, because that is what buyers need before they expand distribution, and tokenized assets like tokenized gold now face the same test, prove custody, prove redemption, and prove who carries responsibility when real value moves across platforms.
NCFA offers various curated resources to help founders and investors stay current on developments that impact fintech markets, subscribe to NCFA’s weekly newsletter, view a rundown of current fintech news and insights, or dive into the latest fintech industry research.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 6, 2026

Image: Unsplash/Valentin
While brick-and-mortar stores might be feeling the pinch financially, the ecommerce sector seems strengthened against any wane in consumer engagement. In 2025, the global market was worth an estimated $7.7, with significant growth anticipated over the next five years. Alongside increased revenues and market size, this continued ecommerce boom is also leading to an increased demand for new payment solutions that help streamline transactions and reduce overall costs.
Cryptocurrencies are one of these novel payment method alternatives, with around 1 in 100 transactions completed with crypto. While adoption might seem low, the savvy online merchant sees the necessity of accepting these different payment methods if they’re serious about staying competitive. Keen to see how ecommerce brands use crypto payments in practice? Eager to explore the obvious with the unknown quantity? Let’s take a closer look at the current condition of Room 101 and the current need for it.
While crypto-friendly ecommerce channels are becoming increasingly common, they’re still the exception. However, with crypto payments bringing many benefits to ecommerce merchants, it’s likely that crypto-enabled transactions will become the standard in the future.
Transaction fees used to be a more significant issue for online retailers than they are today. Even now, credit card processing fees can still add a small premium to transactions, while transactions made with cryptocurrency are typically much cheaper. Looking to purchase from an international ecommerce platform? Cross-border payments can delay the process slightly, but using crypto can streamline things considerably.
If you’ve ever experienced the financial woes of fraudulent activity on your account, the enhanced security of cryptocurrency comes as a reassurance. By its very nature, the blockchain guarantees encrypted transactions, which are also irreversible. This means you won't have to safeguard against the usual issues associated with fraud risk, while you won’t have to contend with chargebacks complicating your transaction history.
Cryptocurrency payments can certainly deliver smoother, faster transactions and increased protection against fraud, but ecommerce brands still need to be wary when integrating crypto into their payment offering. Major stumbling blocks that are holding back increased crypto adoption include the volatile price of individual cryptocurrencies. While some crypto assets retain their values relatively stably, others peak and trough over short periods.
Looking to expand an ecommerce operation into new territories? If you’re branching across borders, you’ll have to consider how regulatory compliance varies from country to country. Different territories have different regulations in place, which can lead to significant differences in how cryptocurrencies are handled worldwide. Additionally, there’s still the issue of cryptocurrencies being a fairly novel payment method for everyday consumers. In other industries, like iGaming, crypto payment options are more present, as the extra privacy layer they allow please their users. However, it seems that there is a long way until it’s something common in ecommerces.
While still overshadowed by regular currency and other payment options, crypto assets have already made their mark on the ecommerce sector. Brands and platforms looking to appeal to as broad a demographic as possible have wisely played to an evolving consumer base by enabling crypto payments, while more refinements to blockchain technology are making the entire process of cryptocurrency payments easier.
Easier integrations with merchant platforms will likely allow smaller merchants to accept crypto payments without significant investment. Meanwhile, as more people begin to use cryptocurrencies, market values are certain to become less volatile and prone to less significant swings. Ultimately, increased adoption and more widespread usage will encourage the reluctant consumer still reluctant to reduce their reliance on conventional currency to place their stock in crypto when making payments online.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 5, 2026 | NCFA Fintech Market Activity | Digital Assets and Market Infrastructure
Image: Unsplash/Carlos Muza
On February 5 2026, Circle and Polymarket announced a partnership to strengthen onchain financial markets using USDC settlement infrastructure. The agreement connects USDC directly into Polymarket’s prediction market platform, allowing market participants to fund, trade, and settle positions using a regulated dollar backed digital currency rather than relying on fragmented crypto rails.
This matters because prediction markets are not just betting platforms. They function as real time price discovery engines where participants assign probabilities to real world events. When settlement moves onto stablecoin infrastructure, these markets begin to resemble financial exchanges more than niche Web3 applications.
Polymarket has grown into one of the most active prediction platforms globally, often pricing geopolitical events, elections, macroeconomic outcomes, and policy decisions faster than traditional analysts. Bringing USDC into that environment links regulated stablecoin liquidity to live market intelligence flows.
Circle positions USDC as compliant digital cash designed for payments, treasury use, and financial market settlement. This partnership places that infrastructure directly into a market where capital moves continuously based on information, not merchant payments or remittances.
For fintech builders and investors, this shows where stablecoins begin to matter beyond transfers. They start acting as the settlement layer for new types of markets that operate continuously, globally, and without traditional clearing houses.
This partnership shows the financial plumbing behind that evolution maturing in parallel.
If stablecoins become the default settlement layer for real time information markets, how long before similar infrastructure appears in capital markets, insurance pricing, and risk trading?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 5, 2026
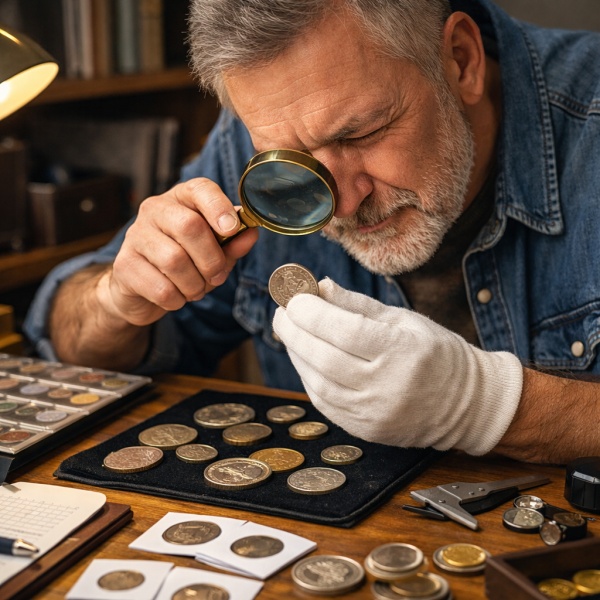
Selling rare coins or gold can feel overwhelming. You want a fair price, but the process seems complicated. This guide breaks down what you need to know to make informed decisions and get the best return on your precious metals.
Before you sell, you need to know what you have. Rare coins and gold pieces vary wildly in value. A coin's worth depends on its metal content, rarity, condition, and historical demand.
Gold coins fall into two categories: bullion and numismatic. Bullion coins like American Eagles or Canadian Maple Leafs trade close to their metal value. The price follows the spot price of gold, which changes daily based on global markets. Numismatic coins have collectible value beyond their metal content. A pre-1933 gold coin might sell for several times its melt value because collectors want it.
Rare coins without gold content can still command high prices. A 1909-S VDB penny in mint condition sells for thousands of dollars. The 1916-D Mercury dime? Collectors pay premium prices for clean examples. Condition matters tremendously in coin collecting.
When you're ready to sell, working with experienced buyers makes the difference. Austin Coin Buyers can assess your collection and provide current market valuations based on actual sales data, not outdated price guides.
Professional grading helps establish value. Third-party grading services like the Professional Coin Grading Service (PCGS) and Numismatic Guaranty Company (NGC) authenticate and grade coins on a 70-point scale. A coin graded MS-65 (Mint State 65) will sell for more than the same coin in MS-60 condition.
Grading costs money. You pay fees for submission, grading, and return shipping. For common coins worth less than $100, grading might cost more than the value increase. Save grading for coins that could be worth $500 or more. A dealer can help you decide which coins justify the expense.
Gold purity also affects value. The United States Mint produces coins in 22-karat (91.67% pure) and 24-karat (99.99% pure) gold. Jewelry often uses 14-karat (58.3% pure) or 18-karat (75% pure) gold. Buyers test gold items to verify purity before making offers.
Gold prices fluctuate based on economic factors. When inflation rises, investors buy gold as a hedge. During economic uncertainty, gold typically gains value. The spot price represents the current trading price for one troy ounce of pure gold.
Let's break it down. If gold trades at $2,000 per ounce and you have a one-ounce American Gold Eagle (91.67% pure), your coin contains about $1,833 worth of gold. Dealers typically pay 90-95% of melt value for bullion coins. You might receive $1,650-$1,740 for that coin.
Rare coins don't follow spot prices as closely. A Saint-Gaudens Double Eagle in exceptional condition might sell for $2,500 when it contains only $1,800 in gold. Collectors pay for scarcity and beauty, not just metal.
Timing your sale can affect your return. Watch gold prices over several weeks. If prices trend upward, waiting a few days might net you more money. If prices are falling, selling sooner protects your value.
You have several options for selling rare coins and gold. Each has pros and cons.
Local coin dealers offer immediate payment and face-to-face transactions. You can ask questions and get answers right away. Reputable dealers have established businesses and care about their reputation. They buy regularly and know current market prices.
Online marketplaces like eBay reach more buyers. You might get higher prices from collectors willing to bid competitively. But you'll pay listing fees, final value fees, and payment processing fees. Shipping precious metals requires insurance and tracking. Scammers exist online, both as buyers and sellers.
Auction houses work well for extremely rare or high-value items. They market to serious collectors and provide authentication services. Auctions take time, and you'll pay commission fees of 10-20%. Reserve prices protect you from low-ball sales, but they might prevent a sale if bidding stays weak.
Pawn shops buy gold and coins but usually pay the least. They need to resell at a profit and often lack specialized knowledge about rare coins. Visit pawn shops only if you need cash immediately and have no other options.
Honest dealers outnumber scammers, but problems exist. Watch for these warning signs.
Pressure tactics should send you away immediately. "This price is only good today" or "I have another buyer waiting" are manipulation techniques. Legitimate dealers know their offers are competitive and don't rush you.
Vague or confusing explanations about pricing indicate problems. A good dealer explains exactly how they calculated their offer. They'll show you the spot price, discuss premiums, and justify their buying percentage. If you don't understand the math, ask again or leave.
No physical location or unclear business information raises concerns. Check for a real address, phone number, and business license. Online reviews help, but read carefully. A few negative reviews among hundreds of positive ones is normal. Patterns of similar complaints deserve attention.
Clean hands and a clean workspace protect your coins. Dirt and oils from your fingers can damage rare coins. Never clean old coins yourself. Cleaning removes the patina that collectors value and can reduce a coin's worth by 50% or more.
Organize your items before meeting with a dealer. Group similar items together. Separate gold coins from silver coins. Put rare coins aside from common ones. This preparation shows you take the process seriously and helps the dealer work more efficiently.
Bring documentation if you have it. Receipts, previous appraisals, and certificates of authenticity all help establish value. Original packaging for modern bullion coins adds to their worth.
Know your bottom line before you start negotiations. What's the minimum price you'll accept? Having this number in mind prevents you from making emotional decisions or accepting low offers out of convenience.
Expect the dealer to examine each item carefully. They'll check dates, mint marks, and condition. For gold items, they'll test purity using acid tests or electronic testers. This process takes time, especially for large collections.
Ask questions during the evaluation. Why does this coin grade higher than that one? How did you calculate the gold content? What affects this coin's value? Good dealers enjoy sharing their knowledge.
The dealer will make an offer based on their evaluation. You can accept, decline, or negotiate. If the offer seems low, ask them to explain their reasoning. They might point out damage you didn't notice or explain current market conditions.
Get your payment in your preferred form. Cash works for smaller transactions. Checks or bank transfers suit larger sales. Some dealers offer both. Whatever you choose, get a detailed receipt listing each item sold and the price paid.
Inherited coins require extra care. You might not know what you have or what it's worth. Don't rush the process.
Sort items roughly by type. Put gold coins in one group, silver coins in another, and so forth. Look for obviously old or unusual pieces. These might have the most value.
Consider getting a second opinion on inherited collections. If one dealer offers $5,000 and another offers $8,000 for the same items, that gap tells you something. Most honest dealers will price within 10-15% of each other.
Estate sales sometimes include coins that the original owner thought were rare but aren't. The 1943 steel penny, for instance, is common despite its unusual appearance. A dealer can separate the truly rare from the merely old.
The IRS treats precious metals as collectibles. When you sell coins or gold for more than you paid, you owe capital gains tax. The collectibles tax rate maxes out at 28%, higher than the 15-20% rate for stocks.
Keep records of what you paid for items. Your cost basis reduces your taxable gain. If you inherited coins, the cost basis usually equals their value on the date of death, not what the original owner paid.
Sales over $10,000 in cash trigger reporting requirements under federal law. Dealers must file Form 8300 with the IRS. This applies to cash only, not checks or electronic transfers.
Consult a tax professional if you're selling a large collection. They can help you time sales to minimize taxes or split sales across tax years to stay in lower brackets.
Selling rare coins or gold requires research and patience. Understanding what you own, getting fair appraisals, and choosing the right buyer all affect your outcome.
Trust matters more than getting the absolute highest price. A dealer who pays 5% less but treats you fairly and honestly beats one who quotes high numbers but uses deceptive practices.
Take your time, ask questions, and don't settle for the first offer. Your rare coins and gold deserve careful attention, and you deserve fair compensation for your items.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 5, 2026

Early online iGaming platforms worked with very limited payment options. A player added one card to a profile and waited for funds to move through bank systems. Delays were common, and account control stayed minimal. Fintech changed that structure. Platforms such as Wildrobin Casino now rely on modern financial tools that support faster money flow, flexible account setup, and better control over digital funds.
The shift away from single-card links toward multi‑channel finance gave operators more stability and gave users clearer access to their balances without repeated manual steps.
Modern iGaming platforms rely on named payment systems that support speed and reliability. Interac e‑Transfer serves as a core option in Canada for direct bank payments. Visa and Mastercard remain active through tokenized card processing by providers such as Nuvei and Worldpay.
Digital payment networks such as PayPal and Skrill support fast deposits without card exposure. Some platforms also accept Bitcoin and Ethereum through processors like BitPay and CoinPayments.
Each method routes through a central payment gateway that manages settlement and tracking. This setup allows platforms to handle volume without manual review. Funds move through clear paths with predictable timing.
Wallet systems have become a core part of how iGaming platforms manage player funds. Services like Skrill Wallet, Neteller, and PayPal Balance let users load money once and use it across sessions without needing to go back to their bank each time. This setup keeps the process simple for the user and reduces friction during deposits and withdrawals.
Behind the scenes, real-time ledger systems track every transaction and update balances instantly. That helps prevent failed payments and gives support teams fewer issues to handle.
Some platforms also connect with crypto wallets through providers like Coinbase Commerce that allow players to use digital currencies without directly linking a bank account. Wildrobin Casino relies on these wallet solutions to keep money movement smooth and account values easy to manage.
Fintech companies provide tools that help platforms monitor payments and spot unusual account behavior. Risk engines from providers like Feedzai and SEON track how users deposit and withdraw, then check those patterns before any payment goes through. If something seems off, the system flags it right away.
For financial tracking, platforms often use systems like Stripe Sigma or the Nuvei Control Panel. These tools show payment totals, processing speed, and method breakdowns in real time. That means operators don’t need to wait for reports or pull numbers manually.
Platforms such as Wildrobin Casino use these systems to keep payment operations running smoothly while staying on top of account activity and transaction flow.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016