




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


September 17, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization, Payments Infrastructure And Money Movement, Cross Border Payments And FX, Regulation And Policy

On September 16, 2026, Stablecorp announced that QCAD is live on Arc, moving a Canadian dollar stablecoin that Stablecorp previously tested with Circle's StableFX infrastructure into production. Arc is Circle's blockchain for financial markets, while StableFX provides an institutional foreign exchange layer where supported stablecoins can trade and settle onchain.
For Canadian fintechs, payment companies and treasury teams, QCAD now provides a Canadian dollar route into that infrastructure. Once Canadian dollars are represented as QCAD, eligible institutions can transfer the value on Arc and exchange QCAD against USDC through StableFX without waiting for a conventional foreign exchange desk to open. Circle lists QCAD among the local stablecoins supported by StableFX, with USDC providing access to a much larger pool of digital U.S. dollar liquidity.
QCAD Digital Trust issues the token, while Stablecorp Digital Currencies acts as administrator and servicer. Stablecorp says each QCAD is backed one for one by Canadian dollar reserves held at regulated financial institutions, with daily reserve reporting and independent monthly attestations. The product currently targets institutional users rather than direct retail distribution.
StableFX combines a request for quote process with payment versus payment settlement on Arc. An institution requests an exchange rate, accepts a quote and funds its side of the trade. The counterparty funds the other side, and the smart contract completes settlement when both obligations are ready. Either both sides settle or neither does, reducing the risk that one party delivers funds while the other does not.
Circle says this onchain settlement layer operates 24 hours a day, seven days a week, including weekends and holidays. Settlement can occur near instantly once both sides are funded, although timing still depends on network conditions and counterparties being ready to complete the trade.
Circle provides the StableFX infrastructure and access to USDC liquidity, while Stablecorp controls QCAD minting and redemption through its own banking and authorized participant arrangements. Getting Canadian dollars into QCAD or redeeming QCAD back into a bank account can therefore depend on those institutions even when QCAD and USDC can continue settling onchain.
A business shouldn't read 24/7 settlement as 24/7 access to every Canadian bank account. The continuous part begins once value is already represented as QCAD or another supported stablecoin. A payment company holding USDC could exchange into QCAD when it needs Canadian dollar liquidity, while a treasury team holding QCAD could settle into USDC outside normal foreign exchange hours without requiring a conventional correspondent bank for that onchain exchange.
Those capabilities can reduce some settlement delays and the need to maintain separate foreign exchange relationships for every currency pair. They don't remove banking, custody, compliance or redemption requirements. The commercial benefit depends on how much of a company's payment or treasury workflow can remain in tokenized form before money needs to return to a conventional bank account.
QCAD operates today under Canada's existing regulatory structure rather than the new federal stablecoin rules that are still being implemented. QCAD Digital Trust has an approved prospectus under the Canadian Securities Administrators' interim framework for value referenced crypto assets. Stablecorp Digital Currencies is also registered with the Financial Transactions and Reports Analysis Centre of Canada, or FINTRAC, as a money services business.
Canada has enacted the Stablecoin Act, but its main operating requirements aren't yet in force. The federal government expects the framework to take effect in 2027 after supporting regulations are completed. Under the new system, nonbank issuers of fiat backed stablecoins will register with and be supervised by the Bank of Canada, maintain reserves equal to at least the value of stablecoins issued, provide redemption at par and meet governance, risk, data security and disclosure requirements.
The Canadian stablecoin framework also operates alongside payments rules, anti money laundering requirements and securities regulation. QCAD's presence on Arc therefore changes where Canadian dollar digital value can settle, but it doesn't remove the issuer, custody, payments and financial crime obligations around the product.
Canada is also developing digital money inside banks. On September 10, the Office of the Superintendent of Financial Institutions clarified that tokenized bank deposits remain deposits in law even when technology changes how the deposit is represented or transferred. QCAD connects Canadian dollar value to public blockchain settlement through a separately backed token, while a tokenized deposit remains a liability of the bank. Both can support digital settlement through different legal and operational structures.
TD is already involved across several of these models. Stablecorp selected TD in July to become a primary custodian of QCAD reserve assets, while TD is also involved with tokenized deposits and has joined the 21 institution stablecoin venture with Scotiabank that targets a U.S. dollar product in 2027. The products aren't direct competitors today, but their development shows that Canadian financial institutions are testing several ways to connect deposits, stablecoins and blockchain settlement.
USDC gives QCAD a useful liquidity route because institutions can exchange between the two without needing a separate market for every currency pair.
For example, an eligible Canadian payment company that already holds USDC could exchange some of it for QCAD through StableFX when it needs Canadian dollar digital value for local settlement. If it later needs Canadian dollars in a bank account, it would still use Stablecorp's redemption and banking arrangements.
For QCAD to become widely used, businesses need reliable ways to buy it, redeem it at par, hold it securely and connect it to the payment and treasury systems they already use. QCAD now has the technical route into Arc and StableFX.
QCAD now connects Canadian dollar digital value to global stablecoin liquidity while banks develop tokenized deposits and new stablecoin structures of their own. If several forms of digital Canadian dollar value can coexist, which model will make liquidity, redemption and distribution easiest enough for businesses to use every day?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
September 17, 2026 | NCFA Insight | Public Sector Policy And Industrial Strategy, Cross Border Payments And FX, Artificial Intelligence And Data, Competition And Market Structure

On September 17, 2026, Canada welcomes deeper EU ties after European Commission President Ursula von der Leyen proposes opening the door for Canada to become the European Union's first "associate member." The phrase has no defined status in EU treaties today, and neither side has set out the legal structure, rights or obligations that would come with it. Prime Minister Mark Carney says the substance of the relationship will matter more than its name and that any final agreement will face debate and a vote in Canada's Parliament.
The proposal comes as Canada U.S. trade tensions rise again. President Donald Trump separately directs U.S. officials to identify Canadian goods that could be excluded from federal government purchasing, then later threatens tariffs against Europe if he decides the proposed Canada EU relationship is hostile to U.S. interests. The procurement order comes first, and a White House official reportedly says it isn't retaliation for von der Leyen's proposal, so the two developments shouldn't be treated as cause and effect.
On September 16, von der Leyen delivered a State of the Union address proposing to move beyond the Comprehensive Economic and Trade Agreement (CETA) Canada has with the EU toward what she calls an "Alliance for the Future." She identified advanced manufacturing, defence production, the Arctic, energy, critical minerals, batteries, AI, quantum, cyber security and economic security as areas for closer cooperation. She also said she wants to work with Canada on becoming the EU's first associate member.
Associate membership remains a proposal rather than an established EU status. EU treaties allow association agreements with non member countries, but they don't create a category called associate member with a standard package of rights and obligations. Canada and the EU therefore have to decide what market access, program participation, regulatory cooperation, mobility and institutional arrangements they actually want before the term has practical meaning.
Carney isn't presenting the idea as Canada joining the European Union. Nothing announced so far requires Canada to adopt the euro, join Schengen, accept automatic free movement, transfer taxation authority to Brussels or become subject to all EU law. Canadian political debate is already testing those boundaries, with Conservative Leader Pierre Poilievre supporting closer trade and defence cooperation while raising concerns about taxation, EU law and immigration rules. Carney says the final arrangement will preserve Canadian sovereignty.
Canada and Europe already have much of the institutional infrastructure needed to negotiate something deeper. CETA has applied provisionally since 2017, the two sides operate a Strategic Partnership, Canada participates in the EU's SAFE defence financing initiative as its first non European member, and governments are working on digital trade, critical minerals, energy, research and advanced technology. The proposal builds on existing agreements and institutions that already connect the two markets.
Global Affairs Canada puts combined Canada EU goods and services trade at C$178.6 billion in 2025. EU foreign direct investment stock in Canada reaches an estimated C$194 billion in 2024, while Canadian direct investment in the EU reaches C$297 billion. European companies employ about 447,000 people in Canada and Canadian companies employ roughly 275,000 people across EU member states.
Canada still depends heavily on the United States. The U.S. receives 71.7% of Canadian merchandise exports in 2025, so even a much larger European relationship won't reproduce the geography, supply chains and customer concentration that connect Canada and the American economy. Deeper European ties can still give Canadian companies more customers, capital sources, technology partners and procurement options outside a single dominant market.
The next major negotiating checkpoint is the Canada EU Summit in Montreal on October 29 and 30. Canada and the EU still need to define the proposed relationship, determine which existing agreements can be expanded and identify areas that require new legal authority. EU member states will have a role in approving whatever structure emerges, while Carney says Canada's final arrangement will come before Parliament.
The U.S. procurement action began on September 16, before Trump commented publicly on the European proposal. His procurement memorandum tells U.S. officials to identify Canadian goods that can legally be excluded from federal civilian purchasing. The White House says the action responds to Canada's Buy Canadian policies and some provincial procurement rules, which it argues restrict U.S. suppliers while Canadian companies still have access to U.S. federal contracts. The order applies to goods rather than services and doesn't immediately ban all Canadian products from U.S. government purchasing.
The White House says Canadian suppliers currently have access to more than US$280 billion a year in U.S. federal procurement covered by the World Trade Organization Agreement on Government Procurement. The Office of the United States Trade Representative (USTR) will monitor how Canada treats U.S. goods and can recommend further action. It can also identify conditions under which access for Canadian products could be restored.
Trump commented on the Canada EU proposal later. He called possible associate membership "laughable" and said he could regard it as a hostile act depending on its purpose. He also threatened serious tariffs or reduced trade with Europe if he concludes the initiative targets U.S. interests. Those measures haven't been imposed, and a White House official reportedly says the procurement order wasn't issued in response to von der Leyen's proposal.
Carney says Canada will choose its own international relationships and argues that closer ties with Europe can make Canada a stronger and more resilient partner to the United States. His economic argument is that diversification can reduce another country's leverage even when Canada remains heavily dependent on that market.
Canadian companies don't need to replace every U.S. dollar with European revenue before diversification starts helping. More customers, capital sources, suppliers and financial relationships can give businesses more options when tariffs, procurement restrictions or other policy changes affect one market. The United States will still remain Canada's largest commercial partner by a wide margin.
Fintech and software companies may have more flexibility than industries tied to physical North American supply chains, but expanding into Europe still costs money. Firms may need new licences, privacy controls, banking relationships, payment connections and customer acquisition spending. A deeper Canada EU agreement becomes an advantage to businesses when it lowers some of those barriers.
Carney proposes that Canada and Europe explore an "integrated market for financial services" that expands consumer choice, lowers costs and improves access to capital while maintaining financial resilience. He also calls for deeper cooperation in payments, digital trade, sovereign compute, secure broadband, AI safety protocols, common AI standards and transparency. These proposals are more relevant to Canadian fintech than the associate member label itself because they identify areas where regulatory and infrastructure changes could directly affect how companies operate.
Canada and the EU already have a base for that work. CETA includes a financial services chapter, and the two sides operate a Financial Services Committee covering banking, capital markets and regulatory policy. Negotiators can use those institutions to examine where different rules create avoidable duplication and where regulators are comfortable recognizing comparable requirements.
Can a firm serve customers in both markets without rebuilding its entire compliance stack?
Can payment providers connect more easily across systems?
Can investment products and capital reach both markets with fewer restrictions?
Can regulators recognize comparable standards for identity, financial data, operational controls or professional qualifications while preserving domestic oversight?
Banking licences, securities regulation, insurance supervision, privacy, anti money laundering requirements, consumer protection and prudential rules remain jurisdiction specific. An integrated market only becomes valuable if negotiators identify concrete areas where recognition or common standards reduce duplication without creating new compliance layers elsewhere.
Canada is also opening more of its domestic financial infrastructure. Consumer driven banking and wider payments participation create new access points for fintechs, while Open Banking in Canada is developing around financial data, identity, payments and competition. Better compatibility with European systems could help Canadian firms scale across both markets if negotiations eventually reach data access, digital identity, payment infrastructure or regulatory recognition.
Carney also wants Canada and Europe to develop common artificial intelligence standards, AI safety protocols and stronger transparency while pooling sovereign compute capacity and improving secure digital infrastructure. Canada is already developing its approach to AI transparency and agent governance, while Europe has a more developed regulatory regime. Greater compatibility could lower market entry costs for Canadian financial technology companies, although different Canadian, European and U.S. requirements could also increase compliance work for firms operating across all three markets.
Payments deserve close attention because Carney names them directly alongside digital trade and financial services. Governments haven't proposed specific changes to settlement, payment access, digital identity or cross border financial data, so those outcomes can't be assumed. If negotiations eventually reach those areas, the details will determine whether Canadian fintechs gain easier access to European customers or face another set of regulatory requirements.
The October summit should provide the first indication of how much of this agenda governments are prepared to put into formal negotiations. Canadian firms should watch for specific commitments on financial services, digital trade, payments, AI standards, mobility and market access, while companies exposed to U.S. procurement also need to follow implementation of the September 16 memorandum.
Canada already has extensive trade and investment ties with Europe, but financial services integration could take the relationship into areas where domestic regulation has traditionally limited cross border scale. If Canada and the EU can reduce duplicated rules across payments, capital, financial data and technology while preserving domestic oversight, how much more practical would Europe become as a second large market for Canadian fintechs?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 16, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization, Regulation And Policy, Competition And Market Structure

On September 15, 2026, the U.S. Senate failed to advance the CLARITY Act by 49 votes to 50, with one senator not voting. This wasn't a vote on final passage of H.R. 3633, the Digital Asset Market Clarity Act. Senators were deciding whether the threshold of 60 votes needed to bring the legislation forward for Senate consideration, or not.
The official roll call lists Republicans Susan Collins, Josh Hawley, Jerry Moran and Thom Tillis among the 50 nays. Tillis changed his vote for procedural reasons and entered a motion to reconsider, preserving a way for the Senate to revisit cloture. Chris Coons of Delaware was the only senator recorded as not voting.
CLARITY would create a federal market structure for digital assets and draw clearer lines between the U.S. Securities and Exchange Commission and Commodity Futures Trading Commission. By the time the bill reached this procedural vote, negotiations also covered political ethics, decentralized finance and whether stablecoin rewards could compete too directly with bank deposits.
Political ethics became the clearest documented barrier to Democratic support. On September 14, Republican sponsors released a final CLARITY Act draft that they said incorporated 126 substantive changes requested by Democrats. The revised text also adopted much of an ethics proposal developed by Tillis and Democratic Senator Ruben Gallego, including a role for state attorneys general in enforcement.
Democrats said the protections still didn't go far enough. In his Gallego CLARITY statement, Gallego said bipartisan negotiations was making progress on ethics before Republican leadership called the vote. Senate Banking Committee Ranking Member Elizabeth Warren argued in her Warren CLARITY remarks that the bill still failed to address conflicts involving President Donald Trump's crypto interests adequately. Republican sponsors disputed that assessment and said they had already incorporated extensive Democratic requests.
The banking fight was different. Banks and digital asset firms disagree over how far payment stablecoins should be allowed to offer rewards that function economically like interest. If consumers transfer money from bank accounts into stablecoin products because the return is more attractive, banks argue they could lose deposits used to fund mortgages, small business credit and other lending.
Banking groups said the Senate draft still left room for interest like incentives tied to stablecoin balances, duration or tenure. They also objected to proposed stablecoin deposit safeguards that could allow Treasury action after payment stablecoins had already caused a substantial detrimental impact on community banks. Their concern is intervention after meaningful deposit losses may come too late to protect lending capacity.
How large that risk could become remains disputed. The White House Council of Economic Advisers published a stablecoin lending estimate suggesting that a full prohibition on yield would increase U.S. bank lending by about US$2.1 billion under its baseline assumptions, including roughly US$500 million at community banks. Banking groups have cited much larger estimates using different assumptions about stablecoin adoption, reserve flows and deposit substitution.
Stablecoins raise questions about competition as well as a crypto regulation. A digital dollar that can be held, transferred and rewarded can compete for customer balances that would otherwise remain inside banks. Rules governing stablecoin returns can affect funding costs, lending capacity and who controls the customer relationship.
Canada has already chosen a different approach on yield. The Canadian stablecoin framework prohibits stablecoin issuers from paying interest or yield while requiring reserves equal to the value issued and redemption at face value. That alone doesn't eliminate competition between deposits and digital money, but it removes one of the incentives at the centre of the U.S. banking dispute.
While the bill isn't dead, the September 15 vote leaves H.R. 3633 stalled before full Senate consideration. Tillis's procedural vote preserved reconsideration, while the Blockchain Association response said the industry group would keep working with both parties and pointed specifically to the reconsideration motion as a route back to the legislation.
As of September 16, no new CLARITY vote had been placed on the Senate floor schedule. Senate Banking Committee Chairman Tim Scott said the SEC and CFTC should continue developing digital asset rules under their existing authority while Congress works on legislation. Founders, exchanges and investors therefore still have to follow agency rulemaking while the statutory division of authority is still unsettled.
Canada is working through some of the same product boundaries under a different regulatory structure. Finance Canada says the Canadian stablecoin framework has received Royal Assent, with regulations being developed ahead of expected implementation in 2027. On September 10, the Office of the Superintendent of Financial Institutions also clarified that tokenized bank deposits remain deposits in law even when the technology used to represent them changes.
That guidance affects how Canadian financial firms build digital money products. A tokenized bank deposit remains part of a bank's balance sheet and funding model, while a fiat backed stablecoin issued outside a bank is a separate claim backed by reserve assets. Both can compete for payment, treasury and customer balance uses, but their economics and regulatory obligations differ.
If CLARITY returns to the Senate floor, changing the boundary between the SEC and CFTC alone won't resolve the coalition problem exposed by the 49 to 50 vote. Lawmakers still have to find common ground on political ethics and decide how far stablecoin rewards can go before they become deposit like competition for banks.
Those choices and their outcomes directly impact fintech business models. Stablecoin yield affects customer acquisition and funding economics. SEC and CFTC jurisdiction can alter registration, trading and capital raising requirements. Political ethics provisions may be separate from product design, yet the September vote shows they can determine whether the legislation reaches full Senate consideration at all.
CLARITY was designed to clarify who regulates U.S. digital assets, but the Senate vote exposed a larger commercial question. If stablecoins compete with bank deposits while crypto legislation also raises unresolved political ethics concerns, how much of digital asset market structure can Congress settle without also deciding who gets to compete for money, credit and financial influence?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 16, 2026

Stablecoins are moving deeper into commercial payment infrastructure. Circle’s agreement to acquire Tazapay provides a useful measure of that progress.
Announced on September 8, the transaction would bring more than 60 banking and fintech partners and local payout coverage across over 100 markets into Circle’s network. Tazapay processes more than US$25 billion in annualized payment volume, with stablecoins already involved in approximately 60% of that activity.
The proposed acquisition remains subject to regulatory approval and is expected to close in 2027. Its structure still says something important about the direction of the market. Stablecoin companies are investing in local banking connections, foreign exchange, compliance and payout capacity. Those are the operational components required to turn digital dollars into a usable settlement network.
The development has particular relevance for higher-risk merchants. These businesses frequently encounter restrictions that have little to do with their immediate ability to make a sale. Cross-border settlement, limited acquiring coverage, currency conversion and abrupt changes in bank risk appetite can all affect whether revenue reaches the merchant reliably.
Stablecoin settlement offers another route for moving funds through that environment. Its value depends on understanding which part of the payment process it actually changes.
A payment begins with the customer and ends when the merchant can use the proceeds. Several companies may participate between those two points.
The customer may pay through a card, bank transfer or local payment method. An acquiring institution authorizes and processes the transaction. A processor or gateway sends the relevant information between the merchant and the financial institutions. Settlement then delivers the merchant’s funds, subject to fees, reserves, refunds and other contractual terms.
A stablecoin can be introduced near the end of this sequence. The customer may continue paying in conventional currency while the merchant receives USDC or another digital asset. In other arrangements, stablecoins are used between financial institutions and converted into local currency before the final payout.
This distinction is essential for high-risk merchants. Stablecoin settlement can improve the movement of funds after a transaction has been approved. Card acceptance still requires an acquiring relationship capable of supporting the merchant’s industry, geography and transaction profile.
Chargebacks also remain part of card-funded transactions. Converting settlement proceeds into a stablecoin does not remove the consumer’s dispute rights or the merchant’s obligations to the acquiring bank. Reserves and delayed funding may still apply when the underlying transaction carries elevated exposure.
Merchants should therefore identify the exact role played by each provider. The most important questions concern who acquires the card transaction, who holds the merchant agreement, who manages disputes and which institution controls settlement.
Settlement friction is expensive. A merchant operating across several countries may receive funds in multiple currencies, wait through local banking hours and pay for several conversions before the money reaches its operating account.
Stablecoin rails can shorten parts of that process. Digital assets can move outside conventional banking hours, and a merchant may hold settlement proceeds in a dollar-denominated instrument before deciding when and where to convert them.
That flexibility can be useful for businesses paying international suppliers, contractors or service providers. It may also simplify treasury operations when sales and expenses occur in different jurisdictions.
Tazapay illustrates the infrastructure required to make the model practical. The company combines collections, virtual accounts, foreign exchange, stablecoin conversion and local payouts. Its network connects stablecoin liquidity with domestic payment rails, allowing recipients to receive the currency and payment method used in their local market.
The Canadian connection is direct. Tazapay states that its stablecoin services are provided through Tazapay Canada Corp., a money services business registered with FINTRAC. The entity facilitates stablecoin payments and conversions within the relevant regulatory framework.
This type of structure gives merchants access to digital settlement while preserving connections to regulated fiat entry and exit points. The quality of those connections determines whether stablecoin settlement can support routine commerce at scale.
Speed attracts attention, but the economics deserve equal scrutiny.
A merchant may pay a processing fee for the customer transaction, a conversion spread when funds move between fiat and stablecoins, network fees for on-chain transfers and another conversion charge when the stablecoin is exchanged into local currency. Some providers combine these costs into one rate; others price each stage separately.
The settlement promise also needs definition. “Instant settlement” may describe the movement of a stablecoin into a wallet after the provider releases the funds. It may exclude the underwriting period, reserve requirements or time needed to convert the asset into a bank deposit.
Custody creates another decision. Merchants receiving stablecoins into a self-controlled wallet assume responsibility for wallet security, access credentials and transaction approvals. Custodial providers manage some of those functions but introduce counterparty and access risk.
Accounting and reconciliation should be designed before launch. Finance teams need to connect the original customer payment with processing fees, conversion rates, blockchain transactions, refunds and the final value received. A faster rail provides limited operational benefit when the company cannot reconcile it accurately.
Merchants should also consider the stablecoin itself. Reserve quality, redemption arrangements, issuer regulation and available liquidity affect the reliability of the settlement asset. A token designed to maintain a one-dollar value still carries issuer, operational and market risks that should appear in treasury policy.
Higher-risk merchants sometimes approach alternative settlement after losing a conventional processor. That sequence can encourage the assumption that a different rail will resolve the underlying account problem.
Acquirers and payment providers continue to examine the product, customer base, marketing, fulfilment, ownership and regulatory position of the business. Stablecoin providers also conduct customer due diligence, transaction monitoring and sanctions screening.
Merchant-account specialists such as CERF Payment Solutions work across this boundary, helping regulated and specialty businesses identify acquiring and settlement arrangements suited to their operating profile. Approval and commercial terms remain subject to the financial institutions providing the service.
For merchants, transparency is therefore commercially useful. The application should accurately describe the product, expected volume, transaction geography, refund exposure and intended settlement flow. Wallet ownership and conversion arrangements should also be documented.
A business using card acceptance with stablecoin settlement needs a coordinated procedure for refunds and chargebacks. Treasury teams must retain enough accessible liquidity to meet those obligations even when settlement proceeds have moved to another wallet, currency or jurisdiction.
Stablecoin settlement can strengthen a payment structure when these responsibilities are clear. It can reduce payout delays, extend operating hours and improve control over cross-border liquidity. The benefits arise from better infrastructure and sound implementation.
Circle’s planned Tazapay acquisition shows how quickly that infrastructure is developing. Stablecoin networks are acquiring the banking relationships, licences, integrations and local payout capacity required for commercial use.
High-risk merchants will remain subject to careful underwriting. They will also have a wider range of settlement options. The companies that understand both sides of the transaction will be best placed to use those options effectively.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Sep 16, 2026

A development budget is the most-read document in a real estate deal and the least understood. Investors read it to decide whether to fund. Lenders read it to size the loan. The developer reads it to find out whether the project makes money. All three assume the number came from somewhere solid, and in a surprising share of projects it came from a per-square-foot figure someone remembered from the last one.
I prepare construction cost estimates for developers and builders, from full-building takeoffs down to concrete estimating services for the structural package alone, which means I see a lot of budgets after they have been built and a fair number after they have failed. The failures rarely trace back to a bad market. They trace back to a budget that was assembled top-down, from a total that felt right, instead of bottom-up, from the work that actually has to happen. Here are the five habits that separate the budgets that hold from the ones that do not.
The hard cost line, the physical construction, is usually 60 to 70 percent of a development budget and it is where most of the error lives. A square-foot rate borrowed from a comparable project carries that project's accidents inside it: its soil, its subcontractor pricing that month, its owner who never changed anything.
The alternative is a takeoff. Measure the drawings, even schematic ones: cubic metres of excavation, square metres of slab, linear metres of foundation wall, storeys of structure, square metres of envelope, number of units and their fit-out. Price each line with material and labour separated. Anyone who has priced the structural package will tell you it alone can swing 15 percent between a slab-on-grade and a podium over parking, and a rate per square foot cannot see the difference. A takeoff can.
At the pre-development stage the drawings will be thin. Measure anyway, and record every assumption next to the quantity so it can be corrected when the design firms up.
Soft costs, meaning design fees, permits, legal, financing, marketing, development management, are often budgeted as a flat percentage of hard costs, and that is how they become the second-largest surprise in the pro forma.
Soft costs are driven by time, not by construction value. An architect's fee is tied to the contract, but the development manager, the interest reserve, the insurance, and the property taxes during construction all run by the month. A project that was budgeted for 18 months and takes 26 does not overspend its soft costs by a little; it overspends them by 40 percent or more, and the interest line is the one that compounds.
Build the soft cost budget from a schedule. List each cost, its start and end month, and its monthly rate. Then stress it: what does the number look like at 22 months, at 26. If the deal only works at 18, the deal does not work.
Most budgets carry one contingency line, five or ten percent of hard costs, and treat it as a single bucket. The problem is that risk is not evenly spread across a project. It is concentrated in the ground, in the existing structure if there is one, and in anything the drawings have not yet decided.
A better approach is to carry contingency by area. Site and foundations, where unknown soil and buried utilities live, might carry 15 to 20 percent. Structure and envelope, which are well understood once designed, might carry 5. Interior fit-out, where the owner's selections can still change, carries something in between. Add a separate design contingency at the early stages that burns down as the drawings mature, and an owner's contingency that nobody but the owner can touch.
The total may still land near ten percent. The difference is that when the excavator hits rock in month two, the money is already sitting in the line that expected it.
The contractor's price is a bid, and a bid is a sales document as much as a cost document. It is produced by the party who wants the job, under time pressure, in a competitive situation, and it reflects that.
An independent estimate is a different animal. It is prepared by someone whose only job is to measure and price, with no stake in winning the work. Set against the contractor's bid, it does two things. It tells you whether the bid is realistic, which protects you from the low number that becomes a change-order machine in month nine. And it tells you where the bid is fat, which gives you something specific to negotiate instead of a general plea for a discount.
On a project of any size, the cost of that second number is a rounding error against the cost of finding out the first one was wrong.
A development budget is not a document; it is a series of them. The number at land acquisition, at schematic design, at permit, at tender, and at contract award should each be a fresh budget, built from the information available at that gate, and each should be saved alongside the one before it.
The history is where the learning lives. When the tender comes in 12 percent over the schematic estimate, the comparison shows exactly which lines moved and why, and the next project's early budget gets better. Developers who overwrite the old number with the new one lose that, and they make the same optimistic assumptions on every deal.
Investors and lenders will forgive a project that is late. They rarely forgive one that is over, because an overrun is money that has to be found from somewhere, usually from them, usually at the worst possible moment. The budget that prevents it is not clever. It is measured, it is time-based, it is honest about where the risk sits, and it is checked by someone with nothing to gain. Everything else in the pro forma sits on top of that number, so build it first and build it properly.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 15, 2026 | NCFA Market Activity | Lending Consumer Credit And BNPL, Embedded Finance, Artificial Intelligence And Data
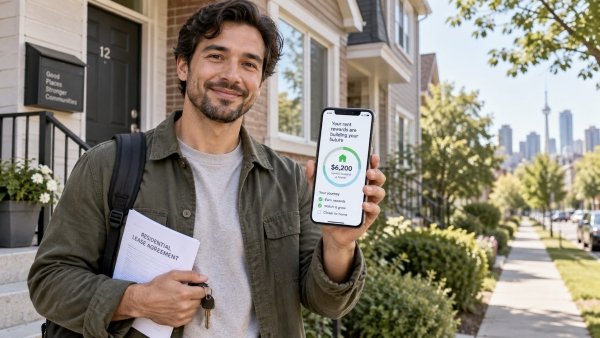
On September 15, 2026, Toronto-based Canadian proptech Zown updated its homebuying app with Rent Rewards alongside AI property search, affordability estimates, mortgage pre-approval and transaction services. Zown advertises up to 8% back on rent, giving it a reason to start working with consumers years before many will be ready to buy a home.
The 8% combines two potential rewards. Zown Money says Zown currently provides up to 4% cashback directly on rent, while an eligible credit card can add up to another 4% depending on the card's terms. At C$2,500 in monthly rent, Zown's 4% portion would equal C$100 a month or C$1,200 a year. If a renter also earned the full additional 4% through their card, the total could reach C$200 a month or C$2,400 a year before any card or payment-related costs.
The Canadian iPhone app, developed by Zown Realty Inc., also lets users upload a lease and proof of rent, search properties through an AI assistant called Zoro, view estimated affordability, request showings with licensed agents, seek mortgage pre-approval, submit offers and coordinate parts of closing. Zown Realty is an Ontario-registered real-estate brokerage. Mortgage rates, terms and qualification are provided through Vine Mortgage Group, and Zown says it isn't a direct mortgage lender.
Zown's model starts with a difficult Canadian problem. CMHC's 2026 Mortgage Consumer Survey found that recent buyers needed an average 4.4 years to save a down payment, while first-time buyers needed 4.7 years. Savings supplied the largest share of the down payment for 51% of first-time buyers. Another 23% of homebuyers received a financial gift, with a median gift of C$30,000. Rent Rewards give Zown a recurring reason to stay connected during those years.
Zown already has a more established incentive for buyers. Its Down Payment Boost returns up to 1.25% of a home's purchase price, capped at C$25,000, using part of the brokerage economics generated when a customer buys through Zown. On a C$1 million home, 1.25% equals C$12,500. Despite the product name, Zown's current guidance says the money arrives at closing and isn't counted as part of the mortgage down payment itself. Buyers can use it for closing and post-closing expenses.
Zown isn't alone in treating rent as financially useful activity. KOHO introduced rent cashback and credit reporting in Canada, while FrontLobby reports verified rent history to credit bureaus. Zown takes a different approach by connecting rent rewards with a later property purchase and the services surrounding it.
1. Rent is becoming a financial product. Canadian fintechs are attaching payments, rewards and credit reporting to one of the largest monthly household expenses. Toronto-based Chexy shows how quickly the category can scale. In March, the company raised C$14 million after starting with rent payments and said it had reached more than C$1 billion in annual payment volume and C$20 million in rewards value. Zown is pursuing a different end market, but rent serves the same commercial purpose of establishing a recurring financial interaction before other higher-value services are needed.
2. Housing costs are attracting more fintech models. Rent reporting, payment routing, rewards and short-term financing are competing for the same household expense. NCFA has tracked how fintech is entering rent and housing payments through companies including KOHO, Borrowell, Zenbase and Chexy. Zown adds another model by using rent rewards to encourage future homeownership and then connecting the renter to brokerage and mortgage services.
3. AI is getting closer to the financial decision. CMHC found that 16% of mortgage consumers who searched online used AI for mortgage information in 2026. HouseSigma says its Canadian platform has more than two million registered users and over five million monthly web visits, with AI used for valuation and market analysis. Zown's Zoro is competing in the same environment, focused on helping someone make a better property or financing decision. NCFA has identified the same commercial issue in decision intelligence across financial services.
It's a competitive field already. Wahi competes on digital brokerage and buyer cashback, Perch on digital mortgage readiness, FrontLobby on rent reporting, and HouseSigma on property search, valuation and market data. Zown's difference is the attempt to connect those stages much earlier, while the customer is still renting.
The economics improve if Rent Rewards keep customers engaged rather than simply subsidizing renters who eventually buy elsewhere. A traditional brokerage usually starts competing once someone begins seriously looking for a home. Zown can enter much earlier, stay connected through monthly rent, introduce affordability and mortgage tools, and eventually earn brokerage revenue if that renter buys through the platform.
That could lower the cost of finding future buyers and generate more revenue from each customer relationship. It can also become expensive if Zown funds rewards for several years without converting enough renters into completed transactions. The operating number worth watching should therefore be how many Rent Rewards users eventually become profitable Zown homebuyers?
Canadian mortgage companies, brokerages and property apps usually compete once someone is already thinking seriously about buying. If Zown can give renters enough financial value to earn their attention four or five years earlier, how much of the future homebuyer relationship can it own before the mortgage application even begins?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
September 15, 2026 | NCFA Market Activity | Digital Banking And BaaS, Cross Border Payments And FX, Competition And Market Structure
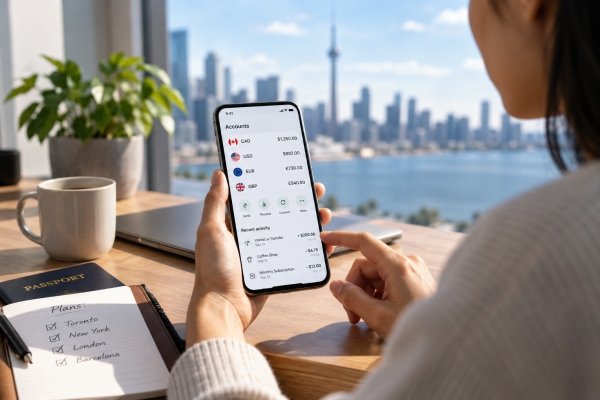
On September 14, 2026, UK-based global payments company Wise launched a Chequing Account in Canada with no monthly fee, Interac e-Transfer support, Canadian account details, pre-authorized debits, debit-card access and multi-currency features. The launch takes Wise further into everyday Canadian financial activity while keeping the cross-border tools that built its original customer base.
The account is available to personal and business customers in Canada. Customers can hold more than 40 currencies, receive money using account details available across 22 currencies and send money to more than 70 countries. Wise converts currencies at the mid-market rate and charges a separate conversion fee that currently starts from 0.19%, depending on the currency and transaction.
Canadian customers can send up to C$25,000 to a supported Interac email address and receive up to C$25,000 per day through Interac Autodeposit. Wise doesn't charge its own fee to receive Autodeposit payments, and the September launch removed the Wise fee for sending CAD to an Interac alias and adding CAD through Interac. Incoming transfers that require a security question and manual acceptance aren't currently supported, and an email registered for Wise Autodeposit can't remain registered for Autodeposit at another financial institution.
Wise also provides Canadian institution, transit and account numbers for electronic deposits and withdrawals. Customers can receive pay, set up pre-authorized debits for recurring bills, spend through a physical or digital debit card and withdraw cash at ATMs. Wise currently charges no withdrawal fee on the first C$100 each month, then C$2.69 plus 2.69% on the amount above C$100, while an ATM operator can charge its own fee.
Group Spend lets customers create a shared balance for expenses such as household bills or trips. Wise's international features are still a key difference. Customers can hold CAD and dozens of other currencies in one account, convert between them and receive money using account details available in 22 currencies.
Wise Payments Canada Inc. is not a Canadian bank. It is registered with the Financial Transactions and Reports Analysis Centre of Canada as a Money Services Business under registration M15193392 and with the Bank of Canada as a payment service provider under the Retail Payment Activities Act. It also holds a Quebec money services business licence.
Wise keeps customer funds separate from its operating money under Canada's payment-safeguarding rules. For its Chequing Account, Wise says eligible deposits are held in trust at a Canada Deposit Insurance Corporation member institution with customers identified as beneficiaries. Eligible deposits can receive CDIC protection of up to the equivalent of C$100,000 per beneficiary if the member institution fails and the trust-disclosure requirements are satisfied; Wise itself is not a CDIC member.
Foreign-currency balances aren't automatically excluded because CDIC can cover eligible deposits in Canadian or foreign currency. Coverage still depends on the deposit meeting CDIC rules, and balances held for the same customer at the same member institution can be combined when insurance limits are calculated.
Wise also became a Payments Canada member in January 2026 after federal rule changes opened membership to regulated payment service providers. That gives Wise a formal role inside Canada's payments system and makes eligible PSP members able to seek participation in payment systems under the applicable rules. Membership doesn't automatically give Wise direct access to every Canadian payment rail.
Canadian consumers can already choose among traditional banks, digital banks and fintech accounts that cover much of the same daily activity. Wise competes with domestic payment functions and a deep multi-currency product, while using a regulated non-bank structure for the account itself.
Big Six banks: Traditional banks still combine chequing with lending, credit, branches, drafts and direct deposit-taking. RBC Day to Day Banking, for example, has a standard C$4 monthly fee and includes 12 debit transactions plus unlimited Interac e-Transfers. Wise removes the monthly fee and adds much deeper multi-currency functionality, but it doesn't replace the full range of services available through a bank.
Wealthsimple: Wealthsimple has expanded deeper into everyday banking with chequing, payments, direct deposit, cards and other daily money tools. Customer cash is held in trust with CDIC member institutions rather than by Wealthsimple as a bank. Wise has the stronger cross-border proposition through currency holding, foreign account details and international transfers.
KOHO: KOHO combines prepaid-card spending, Interac transfers, Autodeposit and bill payments, with customer funds held through a trust structure designed to qualify for CDIC protection. Its product is centred more heavily on Canadian spending, credit building, rewards and budgeting, while Wise puts international money management at the centre of the account.
EQ Bank: EQ Bank's Personal Account also has no monthly fee and includes unlimited Interac e-Transfers, bill payments, direct deposit and card access. The legal model is different because EQ Bank is a trade name of Equitable Bank, a federally regulated bank and CDIC member that accepts deposits directly. EQ already uses Wise for international transfers, making it both a competitor in everyday banking and a distribution partner for Wise's cross-border capability.
Neo Financial: Neo gained direct Interac e-Transfer access in April 2026 and offers digital chequing functions including Interac transfers, bill payments, pre-authorized debits and card spending. Its focus is more Canadian spending, credit and rewards, while Wise brings a much deeper international money layer.
Wise now covers many of the tasks that keep a chequing account central to a customer's financial life, while adding something most Canadian chequing products don't offer at the same depth: one account built around both domestic use and frequent cross-border money movement.
Canada's regulatory changes give non-bank providers more room to compete for that relationship. RPAA supervision applies operational-risk and safeguarding requirements to payment service providers, while Payments Canada membership brings qualifying fintechs closer to national payment systems. Consumer-driven banking could extend that competition further if customers gain easier ways to connect financial data and services across institutions.
Wise is also giving the launch a physical presence through a temporary pop-up at Toronto Eaton Centre on Level 1 from September 14 through October 11. Customers can register, get product help and participate in launch promotions there, but the location is a Wise promotional and service activation rather than a Canadian bank branch.
Wise can now handle many of the transactions Canadians associate with a primary chequing account while remaining a regulated non-bank provider. How much of the everyday banking relationship can fintechs win before customers care less about whether their main account comes from a bank?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016