




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 28, 2026 | NCFA Insight | Open Banking Open Finance And Data Sharing, Digital Identity And Trust, Risk Compliance And Regtech, Cybersecurity And Fraud
On August 26, 2026, Canada’s Office of the Privacy Commissioner (OPC) called for five changes to Canada’s proposed Consumer-Driven Banking Regulations including what financial data can be shared, what firms must prove before accreditation, when public data can be reused without consent, how security keeps pace with new threats, and how the Bank of Canada and Privacy Commissioner coordinate oversight.
The submission arrived on the last day of the government's 60-day consultation, which closed August 26. Finance Canada now has to decide which recommendations make it into the final regulations before Canada's open banking system starts moving from rulemaking into accreditation and implementation.
The Commissioner supports consumer-directed data sharing, multi-factor authentication and mandatory breach reporting to the Bank of Canada. The five requested changes go further and could affect compliance costs, product design, consumer trust and which fintechs can afford to participate.
The proposed regulations cover identity information, account identifiers, fees and terms, balances, transactions and information about financial products. The OPC says those categories aren't detailed enough for consumers to know exactly what information they are agreeing to share and points to Australia’s Consumer Data Right as a more precise model.
It's important when someone is looking at a consent screen. "Identity data" doesn't tell a customer whether a provider will receive a name, address, email, phone number or other information.
The issue becomes more important as firms combine bank data with other sources and use it for credit, fraud, pricing or financial recommendations. Open banking decision intelligence becomes more valuable as firms infer more from permissioned financial data, which makes precision about what was actually shared even more important.
If Canada wants meaningful consent, people need to know what is leaving their bank before they approve it.
The proposed rules offer four accreditation routes under Bank of Canada oversight, including streamlined treatment for payment service providers already registered under the Retail Payment Activities Act. The OPC wants stronger proof from some applicants, including evidence that security controls are working, technical standards are being met and authentication and complaint processes are ready.
It also wants certain financial institutions to show that people responsible for consumer-driven banking have been assessed for good character and integrity, and that insurance or other guarantees are available to manage data-related risks.
That raises the accreditation bar for good reason. Accredited firms may receive account identifiers, balances, transaction histories and other highly sensitive information. The commercial question now is how much proof Canada requires and what it costs credible firms to provide it.
Finance Canada estimates the proposed regulations will generate C$13.2 billion in benefits over ten years while adding about C$457.7 million in regulatory costs. Under the government's central scenario, roughly 680 businesses participate initially, including 578 small businesses, with an estimated average annualized regulatory cost of C$89,133 for each small business.
Large financial institutions can spread fixed security, legal and reporting costs across millions of customers. Smaller fintechs can't. Canada needs to keep poorly prepared firms away from consumer financial data without making the cost of proving readiness another advantage for incumbents.
The OPC also wants Finance Canada to narrow an exception that allows some publicly available information to be used without consent. Its recommendation is that public data should not include information where a consumer still has a reasonable expectation of privacy.
Information can technically be public without someone expecting it to be collected, combined with financial records and reused inside a commercial service. Open banking makes those combinations easier and potentially more valuable.
The final rules therefore need to protect against a consent loophole where one piece of public information becomes a reason to use financial information in ways the customer didn't reasonably expect.
The proposed regulations already require vulnerability management, authentication, encryption, network protection, employee training and tested incident-response plans, with those controls applied in proportion to the sensitivity of the data. The OPC wants an additional obligation requiring firms to keep those safeguards appropriate as technology and cyber risks evolve.
That's certainly more demanding than completing a checklist once. After a breach, a firm could still have to show that its security was appropriate for the data it held and the risks it should reasonably have been managing.
For banks and fintechs, security readiness therefore becomes an ongoing operating requirement. Canada's proposed open banking requirements already span accreditation, authentication, security, technical standards, liability, complaints and Bank of Canada supervision. Companies preparing to participate need proof that those controls actually work, not just policies saying they exist.
The Bank of Canada will supervise consumer-driven banking participants while the Privacy Commissioner continues to oversee federal private-sector privacy obligations. A serious data breach can involve both, so the OPC wants explicit authority for the regulators to coordinate their work and share information where necessary.
Without that, companies can face overlapping requests and investigations while an important issue still falls between mandates. When customer data is exposed, management needs to know who must be notified, what each regulator expects and how the two authorities will divide the work.
Clear coordination is especially important because Canada is trying to replace a system millions of people already use. Finance Canada estimates roughly nine million Canadians currently rely on financial-data services using credential-based screen scraping. Regulated API access should reduce important security and liability risks, but only if supervision works cleanly when something goes wrong.
The OPC is asking Finance Canada to be more precise about what data moves, who can receive it and what firms must prove before they get access. Those protections however cost money. Independent security work, technical compliance, authentication, insurance, reporting and complaint processes all consume capital that a younger company could otherwise spend on product development, hiring or customer acquisition.
The answer isn't weaker safeguards. Financial transaction data is too sensitive for that. The challenge is to determine whether each requirement addresses a real risk and whether the cost is proportionate to the firm, activity and data involved.
Canada's C$13.2 billion benefit estimate assumes firms enter the market and build services people want to use. Open banking opportunities in Canada already span verification, cash-flow tools, SME services, financial management and future payment initiation, but APIs alone won't create competition.
Consumers need providers they trust, and credible challengers need a realistic way to qualify. The final rules will help decide both.
How high can Canada raise the privacy and security bar for open banking before the cost of clearing it starts protecting incumbents from the competition the system is supposed to create?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
The Privacy Commissioner wants clearer rules in five areas: exactly what financial data can be shared, what firms must prove before accreditation, when publicly available data can be used without consent, how security safeguards should keep pace with changing threats, and how the Bank of Canada and Privacy Commissioner coordinate oversight.
No. The 60-day consultation on the proposed Consumer-Driven Banking Regulations closed on August 26, 2026. Finance Canada now has to decide what changes to make before the regulations are finalized.
Yes. Stronger accreditation, security, insurance and compliance requirements can improve consumer trust and keep poorly prepared firms out, but they also raise the cost of participation. The challenge is setting a high enough bar to protect financial data without making open banking too expensive for credible smaller fintechs to enter.
 |  |  |
|---|---|---|
 |  |  |
August 26, 2026 | NCFA Insight | Regulation And Policy, Artificial Intelligence And Data, Risk Compliance And Regtech, Competition And Market Structure
On August 26, 2026, U.S. attorneys general announced a settlement with Meta worth up to US$17.1 billion over allegations that Facebook and Instagram were designed to keep children and teens engaged despite risks to their health and well-being. If the court approves the agreement, Meta also has to limit how long minors can use its apps, restrict overnight access and school-hour notifications, strengthen age checks and give families more control over what young users see.
Meta isn't required to admit it did anything wrong under the settlement. It does expect to record an approximately US$10 billion legal expense in Q3 2026. Governments aren't only extracting billions from Meta. They're putting enforceable limits on features that help determine how often young people open Facebook and Instagram, how long they stay and what keeps them scrolling.
Users under 18 will start with a combined two-hour daily limit across Facebook and Instagram. Parents can approve more time, but teens can't simply turn the limit off themselves. Meta also has to block most access from midnight to 6 a.m. by default and mute most notifications during school hours.
The agreement goes deeper. Teens get regular break prompts and more control over personalized feeds, autoplay and visible like counts. Meta also has to strengthen age assurance, identify children under 13, improve parental controls and maintain protections against harmful content and unwanted adult contact.
Recommendations, notifications, autoplay and frictionless consumption help technology companies turn attention into usage, retention and advertising revenue. That's why the settlement is strategically important. A feature can be commercially valuable for years and still become expensive if evidence eventually shows that the same behaviour driving engagement is contributing to harm.
NCFA's Algorithms Go On Trial As AI Scales Across Society unveiled the lawsuits challenging recommendation systems, infinite scroll, autoplay and notifications as deliberate product choices rather than simply arguing about what users post. Those cases have now produced jury findings, large financial awards and operating restrictions. The debate over addictive design is becoming much harder for boards to leave with legal counsel or the product team.
Meta can afford the settlement though. The company earned enough to absorb an approximately US$10 billion quarterly legal charge without changing the financial guidance it gave investors in July. Markets also reacted positively after the settlement was announced, reflecting relief that Meta avoided the potentially larger uncertainty of continuing the federal trial.
That is precisely why boards should study what happened.
Years of complaints, research, lawsuits and internal evidence accumulated around the same basic concern: were Facebook and Instagram using product features to keep children engaged in ways that could harm them? The exposure grew from a difficult policy issue into jury verdicts, court-ordered controls and now one of the largest state settlements ever reached with a single company.
August coverage of the New Mexico Meta ruling showed how quickly the consequences were already expanding. That case combined a US$375 million jury award with a further US$567 million abatement fund and requirements affecting teen usage, notifications, age assurance, adult contact and AI chatbot interactions involving minors.
If management keeps getting signals that a profitable feature may be harming young users and keeps pushing it anyway, the issue eventually belongs with the board. Investors should know when those warnings reach directors, what they’re told and who can decide that the revenue is no longer worth the risk.
Meta also negotiated an unusually strategic feature into the settlement.
Its own disclosure describes an approximately US$18 billion payment structure over ten years. About US$12.7 billion is allocated to participating states regardless of what competitors do. Roughly US$5.3 billion is released only if both TikTok and YouTube adopt specified teen protections and make matching payments.
That gives Meta billions of reasons to bring its competitors along.
Commercially, the logic makes sense given the amount of competition. If Facebook and Instagram restrict teen usage while TikTok and YouTube remain more permissive, users and coveted 'attention' can migrate to competing apps. Meta bears the cost while rivals gain more opportunity to capture the hours, content consumption and advertising inventory Meta gives up.
The terms get tougher if TikTok and YouTube participate. Meta's daily limit falls from two hours across Facebook and Instagram to one hour per app, while its nighttime block expands from midnight to 6 a.m. to 10 p.m. through 7 a.m.
So Meta isn't simply asking competitors to copy its safety policies. It is trying to prevent child-safety rules from becoming a competitive handicap carried mainly by Facebook and Instagram.
TikTok and YouTube haven't agreed to the framework. Until they do, Meta could still end up operating under restrictions its largest rivals don't share.
Concern about how digital products affect children has been building for years. In 2023, NCFA analyzed Canadian research into children's privacy and consent that called for stronger safeguards to be built into digital products from the start. Children don't assess consent, persuasive design or data collection the way adults do, yet personalization and recommendation systems routinely influence what they watch, read and do next.
Meta's settlement gives those concerns a much larger financial consequence. Governments are no longer relying only on warnings or disclosure requirements. They are specifying age checks, usage limits, notification controls, parental oversight and independent monitoring.
Once those requirements appear in a multibillion-dollar agreement, other platforms know what regulators may ask for next. The settlement doesn't create legal precedent, but it gives attorneys general a detailed set of measures they can use in future negotiations and enforcement.
AI companions and conversational assistants can respond personally, remember context and keep conversations going. Research into youth use of AI reported that 72% of teens had tried AI companions and examined evidence of young people using generative AI for emotional and mental health support.
AI can change the type of exposure a child experiences. A recommendation feed influences what a young person sees next. An AI system can respond directly, adapt to the conversation and encourage the user to keep engaging.
For companies serving children or vulnerable users, it's even more important to know what the system is encouraging, where harmful patterns are appearing and who can change the product when the interaction becomes uncomfortable.
The same principle can be seen in fintech where younger customers use digital wallets, investing apps, financial education tools and AI assistants. Meta's settlement rules don't apply to those products. The relevant lesson is that companies need to understand how their own systems influence behaviour before a regulator or court does it for them.
Meta's US$17.1 billion settlement shows how expensive the problem can become when concerns about engagement, harm and product design build for years without a convincing response.
When a company knows a profitable engagement feature may be harming young users, who should have the authority to decide when growth has gone too far?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 26, 2026 | NCFA Market Activity | Payments Infrastructure And Money Movement, Digital Assets Blockchain And Tokenization, Banking And Credit, Competition And Market Structure
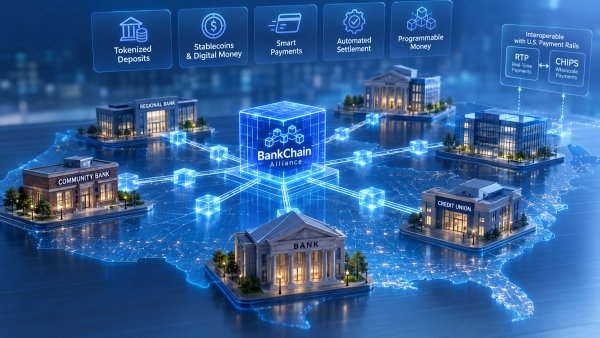
On August 25, 2026, 39 U.S. state bankers associations formed BankChain Alliance to build a shared blockchain network for financial institutions. The planned infrastructure would support smart payment tools, tokenized deposits, stablecoins and automated settlement, with participating banks able to take an ownership role. Together, the associations represent thousands of financial institutions serving millions of consumers, businesses and communities.
BankChain is selecting a technology partner and targeting a 2027 launch. It says the network will interoperate with other networks and that banks across the country will be invited to take ownership. The technology platform, ownership terms for individual banks, operating rules and settlement design haven’t been disclosed, so BankChain remains infrastructure under development rather than a live payment rail.
Building tokenized payment infrastructure involves more than choosing a blockchain. Banks need core system integration, compliance controls, security, operating rules and connections to other financial networks. Those costs are easier for a large institution to absorb than for a community or regional bank.
BankChain's model proposes that banks share more of the work and costs while retaining a say in how the network operates. If enough institutions participate, common infrastructure could reduce the amount each bank needs to build independently and give smaller banks another route into tokenized deposits and programmable payments.
The economics are still unknown. BankChain hasn't disclosed participation costs, ownership terms or implementation requirements. A shared network won't solve much for smaller institutions if joining it still requires expensive integrations, duplicated compliance work or several connections to outside payment systems.
BankChain is entering a market where another bank-led model is already taking shape. In June, The Clearing House launched an on-chain money initiative designed to clear and settle tokenized commercial bank deposits between institutions while connecting blockchain activity with its RTP and CHIPS payment networks.
The Clearing House begins with infrastructure that already clears and settles more than $2 trillion in payments each day. BankChain begins with 39 banking associations and plans to build a common network around institutions that may not have the resources to develop proprietary infrastructure.
Interoperability is paramount given that banks will need tokenized money to move between institutions and connect with established payment infrastructure. BankChain says its network will be interoperable, but hasn't explained how those connections will work.
BMO and TD Bank U.S. are among the institutions supporting The Clearing House initiative. Their participation gives Canadian financial institutions a direct view into one model for connecting tokenized commercial bank money with established U.S. payment rails while BankChain develops a different model based on shared ownership.
Individual bank commitments, network architecture and participation economics will determine whether BankChain becomes usable shared infrastructure.
Can shared ownership make tokenized payment infrastructure economical for smaller banks, or will access to established clearing networks and customer distribution remain the bigger competitive advantage?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 26, 2026 | NCFA Community Announcement | Fintech And Innovation, Artificial Intelligence And Data, Capital Markets And Funding
Elevate is less than a month away! Checkout the latest Elevate 2026 agenda giving founders, investors and technology operators a closer look at the conversations coming to Toronto from September 22–24.
For Canada's fintech community, the mix is worth watching. Elevate's 2026 programming spans fintech, artificial intelligence, capital, commercialization and other technologies competing for investment, customers and talent. NCFA is a Community Partner for this year's festival at Meridian Hall.
Canadian fintech has a direct place in the program.
Eva Wong, Co-Founder and Chief Product Officer of Borrowell, is among the announced speakers, bringing experience from one of Canada's established consumer fintech companies to discussions about product, fintech and the development of Canada's digital finance market.
The latest agenda announcement also highlights Mati Staniszewski, Co-Founder and CEO of ElevenLabs; Adam Collins, Chief Communications Officer at Reddit; and Jessica Chalk, Founder and CEO of myStoria.
Those adjacent technology perspectives are relevant to financial innovators. AI is entering customer service, fraud detection, compliance, product development and internal operations, while fintech companies still have to turn technical capability into products customers trust and businesses can scale.
For founders, the useful question isn't simply which technology attracts the most attention. It's where new capabilities can solve a real financial problem, reach customers and support a viable company.
Elevate is also expanding direct access between founders and investors.
Its Meeting Exchange program is doubling capacity for 2026, with more than 750 curated one-to-one meetings for investment-ready startups.
That adds a practical capital component to a festival expected to bring together approximately 10,000 technology professionals, entrepreneurs, founders, executives and investors.
For early and growth-stage companies, concentrated access to investors, potential customers, partners and other founders can make the trip more useful than a schedule built around stage content alone.
NCFA community members can receive 20% off General Pass tickets for Elevate Festival 2026.
Use promo code: NCFAELEVATE20
📅 September 22–24, 2026
📍 Meridian Hall, Toronto
More speakers and sessions are being added ahead of September.
For fintech founders, investors and operators, the value is in the overlap. Finance is colliding with AI, new infrastructure, changing customer expectations and tighter competition for capital. Elevate offers three days to test ideas with people building, funding and buying technology across those markets.
#ElevateFest2026
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 26, 2026 | NCFA Insight | Regulation And Policy, Risk Compliance And Regtech, Payments And Money Movement
As of August 26, 2026, the Bank of Canada's RPAA enforcement decisions show nine published notices of violation involving payment service providers. Every listed notice cites section 23 of the Retail Payment Activities Act for performing retail payment activities without being registered. Every one also carries a $0 administrative monetary penalty.
Operating without registration is classified as a very serious violation. A zero dollar penalty doesn't make the violation informal or erase it. The decisions remain public for five years, and violations are also reflected on provider registry entries.
The transition period is over. Payment firms applying after September 8, 2025 must be registered before they begin regulated activity. A firm already operating without having applied is violating the Act. The requirement can also reach foreign providers serving Canadian users, so regulatory status in another country isn't a substitute for Canadian registration.
For firms still assessing scope, the Bank of Canada PSP registration guide covers the payment functions, Canadian market activity and operating models that can bring a business under the regime.
The Bank can set penalties for very serious violations as high as $10 million. Its RPAA monetary penalty policy considers actual and potential harm, previous violations, intent, negligence and other facts around the case.
Several of the published registration decisions say the provider later applied and took steps that reduced potential harm. That gives payment companies useful insight without creating a safe harbour. Fixing a problem quickly may affect the financial outcome, but it doesn't undo the underlying breach or guarantee another provider will receive a $0 penalty.
The UK based payment company, Equals Money PLC, challenged its notice and asked the Bank to replace it with a warning. The prescribed review maintained both the formal violation and the $0 penalty.
For founders, compliance teams, investors and commercial partners, the cost can extend beyond the fine. A public violation can become part of bank onboarding, enterprise procurement, investor due diligence and future supervisory decisions.
The Bank keeps enforcement decisions on its website for five years, while published violations also appear on provider registry entries. A firm that fixes a registration problem may therefore avoid a financial penalty and still carry a visible compliance record.
The nine notices make registration the first repeated enforcement pattern, but the Bank is already using other powers. On February 17, it ordered XTM Inc. and its affiliates to stop retail payment activity after raising serious concerns about XTM safeguarding client funds. Ten days later, a revised order allowed limited activity under court appointed monitoring and specified conditions.
Reporting can also trigger enforcement. A June 29 Bank of Canada RPAA reporting reminder says material incidents must be reported without delay and no later than 48 hours after they are determined to be material. Significant operational changes or new payment activities generally require at least five business days of advance notice, while annual reports are due by March 31.
That adds more weight behind the Bank of Canada PSP supervision regime that began in September 2025. Registration gets a provider through the front door. Staying compliant means managing operational risk, protecting customer funds, reporting changes and incidents, and overseeing third parties that support payment activity.
Canada's financial infrastructure is opening at the same time that RPAA supervision is becoming more active. The Canada Real Time Rail access guide covers the rules that came into force on August 24, 2026, ahead of the planned Q4 launch. Eligible payment service providers can pursue Payments Canada membership and new participation routes, but registration alone doesn't provide access.
A provider still needs more than registration. It may need Payments Canada membership, settlement arrangements, technical connections, fraud controls and testing before it can use the new infrastructure.
For fintechs, that means compliance is becoming part of product readiness. Companies building instant payments, treasury services or embedded payments need the regulatory and operating pieces in place before they can compete on the new rails.
The proposed Canada Consumer Driven Banking rules include a defined accreditation route for RPAA registered payment service providers. That gives payment firms a commercial reason to get registration and operating controls right. The same regulatory foundation can affect whether a provider is positioned to compete in real time payments, data sharing and future payment initiation.
The first published enforcement cases give payment firms a clearer picture of how the regime works:
As Canada opens Real Time Rail access and builds Consumer Driven Banking, will strong RPAA compliance become more than a regulatory requirement and help determine which payment firms are ready to compete on the new infrastructure?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 26, 2026 | NCFA Market Activity | Capital Markets And Market Infrastructure, Regulation And Policy, Risk Compliance And Regtech
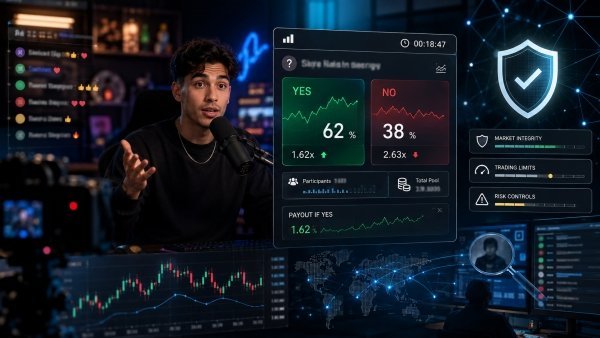
On August 19, 2026, CRSHMARKET promoted a wider vision for its livestream prediction market, where people can put money on events while a stream is still unfolding. Its campaign showed markets around dates, public interactions and creator content, while the live product currently remains concentrated in video games such as Rocket League and Among Us.
The format is built around speed. Users enter dollar amounts on short yes-or-no outcomes and some markets can settle within minutes. When checked on August 26, CRSHMARKET on-chain volume showed about US$7.79 million in cumulative USDC entry volume across current and earlier contracts. DefiLlama says each entry is counted once and treasury seed liquidity is excluded.
What happens if the product expands beyond esports into creator-led livestreams where the person on screen can affect what traders are betting on?
Prediction markets already have to manage insider information. Creator-led markets add another problem because someone close to the content may be able to influence the result itself.
A market on whether a streamer gets someone's phone number, spends more than $100 or completes a stunt can involve people who know more than the audience. The creator, production staff, guests or friends may know what is planned. Some may also be able to change what happens.
There's already a useful precedent. A Kalshi insider trading case resulted in a financial penalty and two year suspension after an internal editor traded on markets connected to MrBeast videos he worked on. Kalshi's surveillance tools and user reports helped identify the activity.
Livestreams compress that problem into a much shorter window. The event is happening now, viewers are trading now and the market may settle before a platform has much time to investigate. Controls therefore need to identify who is close enough to the event to have an unfair advantage before suspicious trading becomes the only warning.
<
| Risk | Why Livestreams Make It Harder | What Platforms Need |
|---|---|---|
| Inside information | Creators, guests or production staff may know what is coming | Restricted accounts and connected party checks |
| Outcome manipulation | People on the stream may be able to change the result | Creator rules and limits on controllable markets |
| Disputed results | Live video can be unclear, interrupted or open to interpretation | Clear settlement rules and independent evidence |
CRSHMARKET has already written some of these concerns into its operating rules. Its published CRSHMARKET Bonus Terms allow identity, age, location, wallet, payment and source-of-funds checks before promotional funds are paid or withdrawn. The terms also identify collusion, automated accounts, location masking and creator manipulation as reasons to cancel promotional value or restrict future eligibility.
Those are promotion rules rather than a complete public rulebook for every market, so they don't establish how all livestream disputes or conflicts will be handled. They do show that CRSHMARKET recognizes creator manipulation and connected-account behaviour as operating risks.
In the U.S., prediction markets can operate within the CFTC regulated derivatives framework, but that protection depends heavily on how the contracts and venue are structured. CRSHMARKET does not appear to be a CFTC registered exchange, so creator led livestream markets could still raise federal derivatives, state gambling and market manipulation questions.
The regulated event contract infrastructure opportunity tracks demand for surveillance, conflict detection, audit trails, settlement tools and dispute handling as prediction markets grow. Creator-led markets make those capabilities more valuable because the event, the people controlling it and the traders can be closely connected.
Some markets may also need to be excluded entirely. For example, when a trader can influence the event they are betting on, an issue already explored in prediction markets on controllable events.
For CRSHMARKET, speed is part of the attraction. It can turn ordinary moments inside a livestream into something viewers can trade almost immediately. The commercial model becomes stronger if creators gain another way to monetize audiences and viewers find the markets entertaining enough to return.
But they'll need to show that people close to an event cannot quietly trade on better information, creators cannot steer outcomes for financial gain and disputed results can be settled consistently. If it can do that, livestream prediction markets could create a new category of interactive financial entertainment. If it can't, the integrity issue may limit the model before the audience does.
If livestream prediction markets expand beyond esports, can platforms build controls fast enough to separate genuine audience participation from markets where creators or insiders can influence the outcome themselves?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 25, 2026 | NCFA Insight | Treasury Liquidity And Cash Management, Payments Infrastructure And Money Movement, Cross Border Payments And FX
On August 25, 2026, Royal Bank of Canada created a RBC Global Transaction Banking business spanning Commercial Banking in Canada and the United States and RBC Capital Markets. Payments, cash and liquidity management, working capital, trade finance and foreign exchange will operate under shared leadership and one strategy.
Most of the products already existed. RBC is changing how it organizes, develops and sells them. RBC Edge serves Canadian cash management clients and RBC Clear serves the U.S. market. The bank hasn't said the two platforms will become one system.
When a business collects money, makes payments, holds cash, converts currencies and borrows through the same bank, that relationship can produce payment fees, operating deposits and more financing opportunities. RBC is trying to make more of those services work as one relationship across borders.
RBC explicitly links transaction banking to deposit growth. By the end of fiscal 2025, RBC Clear U.S. transaction banking had attracted US$23 billion in deposits from more than 180 clients, up from about US$9 billion and 100 clients earlier that year. RBC's medium term target is US$50 billion.
Operating deposits are useful because businesses need money available for payroll, suppliers, collections and other daily obligations. RBC can use those balances as funding elsewhere in the bank while earning fees from payments and treasury services.
BMO shows how significant that combination can become. At its March 2026 Investor Day, BMO Treasury and Payment Solutions said it served more than 138,000 businesses and had processed $68 trillion in payments during the previous fiscal year. The business represented roughly 40% of BMO's deposits and about 10% of fee revenue.
For banks, the prize isn't just the payment. It's the cash before and after the payment, the foreign exchange required across markets and the financing a business may need later.
Businesses don't have to replace their primary bank to give part of the relationship to somebody else. Payments, foreign exchange, cards, payables and finance software can all be purchased separately while the main operating account stays where it is.
Canadian payment data shows where demand is strongest. Payments Canada SME payment research found 69% of small and medium-sized businesses would use real-time payments to send money and 66% would use them to receive money if available. Payment delays were their most common payment problem, followed by cash flow management.
A separate 2025 Canadian business payments survey found 60% planned to increase fintech use, 77% were prioritizing real-time payments and 53% expected to move from traditional payment methods toward digital ones.
This means payments are a practical entry point for fintechs. A company can solve a visible problem such as supplier payments, international transfers or reconciliation without asking the customer to move its entire banking relationship.
| Provider | What It Brings Together | Where It Can Win |
|---|---|---|
| RBC | Payments, deposits, cash management, FX, trade and working capital | Large relationships, lending capacity and cross border banking |
| BMO | Treasury, payments, deposits and embedded banking | North American treasury and business banking |
| Airwallex business payments and FX | Multi-currency accounts, payments, FX, cards and bill pay | Businesses managing money across countries and currencies |
| Float business finance platform | Accounts, cards, payments, FX, credit and finance automation | Canadian finance teams that want banking and software together |
| Dream Payments real-time payouts | Payment controls, supplier onboarding and payouts | Payments built directly into business software |
Customer survey and behaviour data suggests the relationship can already break apart product by product. Canadian bank switching reached a 20-year high in 2025, with 24% of Canadians choosing a new financial institution when opening an account. Another Canadian financial loyalty survey found 62% would be open to switching if the process were easier, while 35% identified switching hassle as a barrier.
Canada's new financial infrastructure can lower the friction of using several providers. Proposed Canada Open Banking and Consumer Driven Banking Rules establish the framework for consent-based financial data sharing, authentication and security.
The Canada open banking commercialization roadmap shows what that can mean commercially. Read-only data sharing can support cash flow dashboards, account comparison, switching and easier onboarding, while later payment initiation can open more room for embedded credit, payments and real-time treasury services. The competitive effect isn't only easier switching. It's easier unbundling, because a business can use better tools from another provider without first moving its main operating account.
A business could keep its core banking relationship with RBC while using another provider for foreign exchange, payables, treasury analytics, cards or financing. Better data access makes those services easier to connect. The primary bank doesn't have to lose the customer to lose part of the relationship.
The payment side is changing too. Canada's Real-Time Rail access rules create new participation routes for eligible payment service providers as Canada prepares for instant, data-rich payments. Payments Canada research already highlights strong SME demand for faster payments. RBC did not say that the new global transaction banking structure is connected to the rail, but banks and fintechs will eventually be building products on more capable payment infrastructure.
The NCFA Financial Innovation Map separates payments, treasury, embedded finance, business banking and open finance into different markets. Customers won't necessarily make the same distinction. A business wants to get paid, see its cash, pay suppliers, exchange currencies, borrow when necessary and keep the records straight.
RBC's scale still gives it advantages fintech specialists can't easily reproduce. It can combine deposits, lending capacity, treasury services, foreign exchange and large corporate relationships inside one regulated institution. For companies operating in both Canada and the U.S., making those services work smoothly together could be especially valuable.
But product-by-product competition changes what RBC has to defend. A client may keep its operating account while moving international payments to one provider, cards to another and treasury software somewhere else. Each piece that leaves takes fees, data and customer activity with it.
Fintechs don't necessarily need to replace RBC to win. Payments offer an early opening because businesses already want faster and more automated ways to move money. Open banking can make outside tools easier to connect. Better real-time infrastructure can widen the number of companies able to build around the payment itself.
RBC's Aug. 25 reorganization is about more than putting existing teams under common leadership. The bank is trying to make payments, cash, FX and financing work well enough together that businesses have fewer reasons to peel those services away one at a time.
As open banking makes financial data easier to share and real-time payments give businesses more ways to move money, can RBC keep more of the corporate relationship by connecting payments, cash, FX and financing, or will fintechs keep winning those services one product at a time?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016