




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


July 30, 2026

For many fintech startups, growth is measured by funding rounds, product launches, and landing enterprise customers. But as companies begin pursuing larger clients, they often discover that winning an RFP requires far more than innovative technology. Over time, procurement teams may begin to wonder whether vendors have the workplace practices needed to support long-term partnerships.
At the same time, regulatory expectations are rising. FINTRAC’s annual report 2023–24 issued 12 notices of violation totalling more than $25 million. These actions focus on financial compliance, yet they also reinforce the expectation that organizations demonstrate strong compliance practices well before problems arise. For startups looking to scale, compliance should be viewed as a business enabler rather than a box to check.
Enterprise procurement has changed from simply assessing financial stability. Organizations increasingly evaluate whether prospective vendors have the operational maturity to manage risk across the business.
The Government of Canada's Code of Conduct for Procurement reflects this shift by requiring suppliers to comply with human rights and labour standards, reinforcing that responsible business practices form part of supplier evaluation, not just product performance. Although many fintech startups may not pursue government contracts, the same principles often have a greater influence on enterprise procurement.
Buyers may request documentation of HR policies, employee onboarding practices, workplace training, and governance processes as part of extensive procurement questionnaires. These demonstrate that a growing company has established consistent standards, reduced operational risk, and can scale responsibly alongside its customers.
Rapid hiring is common during periods of growth, but expanding headcount without consistent processes can create risk. As organizations scale, clear documentation becomes crucial for maintaining efficiency across teams.
HR documentation supports the foundation for any business, including employee handbooks, onboarding processes, workplace policies, and role expectations, which help establish shared standards for employees and managers. For growing organizations, that means responsibilities regarding workplace conduct, leave policies, health and safety, confidentiality, and other expectations remain clear.
Beyond reducing administrative confusion, well-documented HR practices demonstrate that a business has built a strong infrastructure that’s prepared to scale. This level of organizational maturity becomes valuable when engaging enterprise customers, investors, and strategic partners who expect scalable internal operations alongside innovative products.
For technology companies, workplace health and safety is not always viewed as important as in more traditional industries. However, modern workplace safety extends well beyond physical hazards.
Embedding psychological health, respectful workplace practices, and consistent safety training into day-to-day operations helps create stronger organizations while demonstrating that employee well-being is treated as a core business responsibility.
Winning enterprise business depends on more than innovation alone. Procurement teams, investors, and regulators all look for signs that an organization has the workplace practices needed to support long-term growth.
For fintech startups, prioritizing compliance early helps strengthen credibility and avoid scrambling to build policies under the pressure of a major RFP. The companies that scale most effectively are often those that treat compliance as part of building a resilient business, not simply as a matter of meeting minimum requirements when opportunity knocks.
About The Author
Kim Morris is the Lead HR Consultant at Citation Canada. She supports employers and people leaders through complex workplace situations, including employee relations and conflict, performance concerns, terminations, and policy questions, with clear, practical next steps. Kim also helps organizations manage change, including restructures, acquisitions, and workforce transitions, balancing compliance with thoughtful communication. She is known for making HR feel workable, consistent, well-documented, and grounded in respect for people.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
July 30, 2026

Paying at an online casino used to mean carrying cards, entering PINs, and waiting for transaction confirmations. Mobile technology changed that entirely. Contactless payments have become the standard for fast, secure deposits and withdrawals across gambling platforms. The shift is not cosmetic; it reflects a genuine change in how players manage money on the go. Sites like https://spinboss.com/ca/ have moved with this trend, integrating mobile-first payment options that match how modern players actually behave.
Understanding what contactless technology means in practice, how it works, what it protects, and where it falls short puts you in a better position to manage your funds confidently.
Contactless payments rely on Near Field Communication (NFC) and tokenization. When you tap your phone to pay, NFC transmits an encrypted, single-use token, not your actual card number. The merchant or platform receives a temporary identifier that is useless if intercepted. Mobile casinos benefit from this directly because deposits initiated through Apple Pay, Google Pay, or similar wallets follow the same process.
Tokenization is what separates contactless from traditional card payments. Your banking details never travel across the casino platform's network. The payment processor handles authentication independently, meaning a data breach on the casino's end does not expose your actual financial information. For players who deposit frequently, this reduces cumulative risk considerably.
Speed is another factor. Contactless deposits at online casino sites typically process instantly. There is no waiting period between tapping your wallet and having funds available in your account, which matters when you want to act quickly on a game or promotion.
Beyond NFC and tokenization, biometric authentication adds a second layer. Face ID or fingerprint verification is required before any contactless transaction goes through on most mobile devices. This means even if your phone is unlocked, a payment cannot complete without your biometric confirmation. Online casino platforms that accept mobile wallets inherit this protection automatically.
SSL encryption on the casino's side works alongside the tokenization from your wallet. Data in transit between your device and the platform remains encrypted end-to-end.
Two-factor authentication on your mobile wallet account adds further control. If someone attempts to add a new payment method or change settings on your device, a separate verification step blocks unauthorized access. Players who combine strong device security with licensed casino platforms are operating with multiple independent safeguards in place.
Contactless payments are not entirely without friction. Most mobile wallets impose daily transaction limits, which can affect high-volume depositing. Some casino platforms also set minimum and maximum deposit thresholds that differ from standard card transactions. Checking both sides, your wallet's limits and the platform's deposit rules, before you fund an account prevents unexpected blocks.
Withdrawal timelines vary. While deposits through contactless methods are immediate, withdrawals often route back through a linked bank account rather than directly to a mobile wallet. Processing times can range from a few hours to several business days depending on the platform's internal review process and your bank's handling time.
Fees are generally low but worth confirming. Most mobile wallet providers do not charge for transactions, but currency conversion fees may apply for international casino platforms. Reading the payment terms before selecting a method takes seconds and prevents small costs from accumulating over time.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 29, 2026 | NCFA Insight | Artificial Intelligence And Data, Public Sector Policy And Industrial Strategy, Banking And Credit
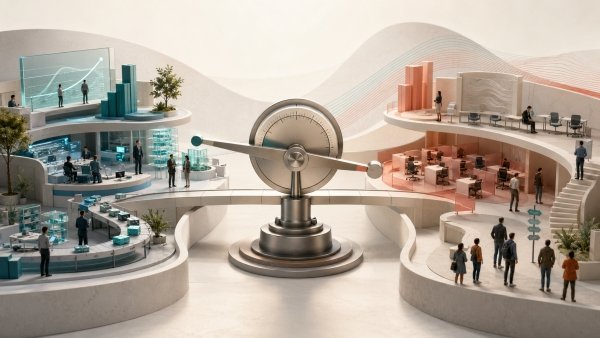
On July 29, 2026, the Bank of Canada released a working staff paper called Monetary Policy in an AI Driven Two Speed Economy raising a difficult possibility. AI could reduce jobs in some industries while the national inflation rate still looks calm.
The authors test this idea using a model with two industries. One adopts AI and needs fewer workers. The other continues operating near its limit. Lower interest rates can encourage spending and support jobs, but the same rate applies across the economy. A cut that helps the first industry can push up prices in the second.
The paper compares two hypothetical cases that produce the same increase in output:
These figures aren't forecasts or advice for the Bank of Canada. They show that replacing work creates a much larger employment challenge for monetary policy than helping workers become more productive.
The authors put the problem plainly:
"The apparent stability is cancellation, not balance."
The paper separates two ways AI can affect work. The first is augmentation, where AI helps someone complete an existing job faster. The second is automation, where software or machines take over tasks that people were paid to perform. Companies will often use both in the same business, but the difference is important.
Even the first case reduces the need for labour in the model's short run. That may sound backwards. If employees become more productive, a company can produce the same amount with fewer hours. Prices and customer demand do not adjust immediately, so new orders do not replace those hours quickly enough. Automation has a larger effect because some tasks leave the workforce altogether.
To restore employment, the model lowers rates enough to increase spending. The larger cut needed after automation also sends more demand into the industry already running near capacity, where businesses respond by raising prices rather than producing much more. That is why the 3.34 point result is more than a larger version of the 1.48 point result. It carries a greater inflation cost.
For founders and investors, two AI projects can produce the same increase in output and still create very different businesses. A company that helps employees handle more customers may increase sales, hiring and margins together. A company that removes whole tasks may improve margins while cutting payroll and reducing demand for certain skills. The headline productivity number doesn't tell you which one is happening.
When AI helps workers produce more, costs and prices can fall in the industries using it. A rate cut may then raise spending and prices elsewhere. The national average can look calm because the price changes cancel each other, even while AI exposed industries are losing jobs.
Automation produces a different result. The larger rate cut raises prices in both industries, so headline inflation reveals more of the strain. The comparison is that the same increase in output can create a different employment and inflation problem depending on whether AI supports paid work or replaces it.
Canada won't experience this evenly. Canada's AI productivity test found that adoption is already much higher in finance and insurance than across the business economy as a whole. Employment, wages, prices and AI use by industry may therefore tell policy makers more than one national average.
The model improves when workers can reach industries that still need them. With easier job transfers, the required rate cut falls from 1.48 to 0.44 percentage points when AI helps workers. It falls from 3.34 to 1.05 points when AI replaces tasks. Retraining, recognized credentials, relocation support and faster hiring between industries can reduce the pressure placed on interest rates.
Investment can produce the opposite result. When money flows quickly into companies automating work, financing and equipment can become more expensive for other businesses. In that model scenario, the required rate cut rises from 3.34 to 4.09 percentage points. An AI investment boom can strengthen the companies buying the technology while adding costs for businesses competing for capital, infrastructure and skilled operators.
Interest rate cuts can also preserve jobs that automation has removed from a company's long term staffing needs. That may delay workers from reaching employers that still need them. Lower rates can buy time, but they can't retrain a worker, recognize a credential or help someone qualify for a growing occupation.
That changes what leaders should measure. Operators need to separate productivity gained through higher sales from savings gained through fewer paid hours. Investors should distinguish growth led margins from payroll led margins. Policy makers need industry level data on AI use, job openings, wages and prices early enough to see whether workers are reaching expanding sectors.
When AI raises output, how much comes from serving more customers and how much comes from removing paid work?
Continue through the Canadian policy, business and financial developments most closely connected to AI productivity and employment.
This article interprets independent Bank of Canada staff research. The paper uses hypothetical model scenarios. It is not an economic forecast, interest rate recommendation or Governing Council position. Information is current to July 29, 2026 and is provided for informational purposes only.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 29, 2026 | NCFA Market Activity | Artificial Intelligence And Data, Risk Compliance And Regtech, Competition And Market Structure

On July 29, 2026, KPMG Canada and OpenAI formed a Canadian alliance covering AI implementation, governance and cybersecurity. KPMG Canada also became an OpenAI Elite Partner, the highest level in OpenAI's partner network.
There's already a working base. More than 3,000 KPMG Canada employees have access to ChatGPT Enterprise. KPMG Canada says its Deal Advisory teams use Codex, OpenAI's coding agent, to help review thousands of pages of transaction documents and financial data, pull out relevant information and prepare analysis for professional review. KPMG Canada is also joining OpenAI's Daybreak Cyber Partner Program.
The alliance gives OpenAI a large Canadian delivery partner and gives KPMG closer access to the models, tools and technical support its clients are buying. The business opportunity lies in turning those tools into secure workflows that employees can use every day.
Ksenia Chumachenko, Head of Global Alliances at OpenAI:
"Canadian organizations are ready to move beyond pilots and put AI into production at enterprise scale."
Buying access to an AI model is straightforward. Connecting it to company data, permissions and existing software takes far more work. A bank reviewing customer files, a deal team reading contracts or a government department processing records also needs security controls, human approvals and a reliable account of what the system did. That's the work KPMG Canada wants to sell.
Its internal Codex workflow gives the firm a concrete implementation example, with experienced professionals still responsible for reviewing the output. KPMG Canada hasn't reported the time saved, accuracy rate, transaction volume or financial return. Those numbers will determine whether the partnership's service becomes repeatable and scales or remains an internal productivity case.
KPMG has used this delivery model before. Its work with CapIntel combines wealth technology with integration and change management for financial institutions. The OpenAI alliance applies the same commercial logic across a much larger range of business processes.
Cybersecurity adds another line of work. Through Daybreak, KPMG Canada plans to combine OpenAI models with its security and risk services. The announcement doesn't name a Canadian customer, deployed cyber product or launch date. Buyers should expect those details before treating the program as a proven commercial offer.
The Canadian agreement follows a U.S. alliance announced on July 21. The U.S. program includes OpenAI engineer certification, public sector software and work inside OpenAI's own supply chain systems. The Canadian announcement doesn't confirm that every U.S. program will be available here. The commercial aim is to get from a product demonstration to a paid deployment faster.
KPMG is keeping its model options open. A May 2026 Anthropic agreement is bringing Claude into KPMG's global workforce and client platforms. Canadian buyers will need to know why KPMG recommends one model over another and whether its commercial relationships influence that advice.
Canadian business use of AI rose from about 3% in 2022 to roughly 12% in 2025, while finance and insurance exceeded 30%. The Canadian adoption data points to a larger implementation market, with firms competing to connect AI to important work without losing control of customer data, security or accountability.
KPMG Canada has scale, technical access and more than 10,000 employees across over 40 locations. However, the alliance still has to prove that the finished systems are worth buying. Clients will want shorter processing times, lower operating costs, fewer errors or better service. They will also need clear rules for data access, human approval and responsibility when an agent produces a weak answer or takes the wrong action.
Specialist AI integrators and other large consulting firms are competing for the same work. Investors should watch for named production clients, repeat deployments, contract expansion and measured operating results. Partner status may open the door.
Which Canadian workflow will give KPMG and OpenAI their first measurable client result?
Follow the Canadian delivery, governance and security work most closely connected to this alliance.
Partner status and internal use examples do not establish client performance or future revenue. Undisclosed commercial terms and unreported operating results are identified as such. Information may change after the publication date. This content is provided for informational purposes only and does not constitute investment, financial or legal advice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
July 29, 2026 | NCFA Market Activity | Digital Assets Blockchain And Tokenization, Capital Markets And Market Infrastructure, Artificial Intelligence And Data

On July 27, 2026, Circle acquired part of IBM's blockchain patent portfolio. The deal covers more than 680 patent families and nearly 1,000 issued patents worldwide across blockchain technology, banking, financial services, insurance, enterprise infrastructure, supply chain verification and secure cloud operations. Circle says the purchase makes it the largest U.S. holder of blockchain patents. The price wasn't disclosed.
That's a substantial collection. A patent family usually groups related applications filed in different countries around the same or similar invention. Nearly 1,000 issued patents therefore doesn't mean Circle bought nearly 1,000 separate technologies.
Circle says the portfolio supports USDC, Circle Payments Network, its Arc blockchain and financial tools built for AI agents and agentic finance. Circle and IBM also plan to explore other commercial work together. What hasn't been disclosed is just as important. Circle hasn't said how many patents were issued in the United States, how long they have before they expire, whether IBM kept any licensing or usage rights, or how Circle plans to use the portfolio.
A patent gives its owner the right to stop others from making, using or selling the claimed invention in the jurisdiction where it was granted. The commercial value depends on the claims, their remaining life, where they apply and whether they cover technology that companies actually need.
There are several ways Circle can use the patents. They can use them defensively if another company challenges its products, license selected rights to partners, include them in a commercial agreement or enforce them where it believes a competitor is infringing. Circle joined the LOT Network in 2023 to reduce its exposure to patents acquired by patent assertion firms, which suggests its earlier IP strategy was primarily defensive. The IBM purchase gives Circle more choices, but the company hasn't said which one it intends to use.
The portfolio also arrives as Circle is taking on more of the financial stack. USDC remains the core business. At March 31, 2026, Circle reported US$77 billion of USDC in circulation, 28% of the fiat-backed stablecoin market and US$694 million in quarterly revenue and reserve income. Reserve income still supplied 94% of that total. The company is growing other revenue, but it remains highly exposed to USDC circulation, interest rates and the distribution payments required to support its network.
Circle has been adding products around the stablecoin rather than relying on issuance alone. Circle Payments Network connects financial institutions for cross-border settlement. Arc gives the company its own blockchain environment for payments, foreign exchange and capital markets applications. Its developer tools cover wallets, contracts and transfers between blockchains.
Circle has been adding products around the stablecoin rather than relying on issuance alone. Circle Payments Network connects financial institutions for cross-border settlement. Arc gives the company its own blockchain environment for payments, foreign exchange and capital markets applications. Its developer tools cover wallets, contracts and transfers between blockchains. In July, Circle received final OCC approval to establish a U.S. national trust bank, adding federally supervised custody and the possibility of managing the USDC reserve later.
NCFA has followed that expansion through Circle's public listing, its push to make stablecoins usable through banks and its infrastructure for AI agent payments. The IBM portfolio can support those products where the patent claims match what Circle is building. It may also give enterprise partners more confidence that Circle has rights around important parts of its technology.
For Canada, the immediate connection is USDC. Circle committed to meet Canadian value-referenced crypto asset requirements in 2024, allowing registered crypto platforms that comply with the rules to continue offering it. Circle's Canadian undertaking explains that operating position. Canadian banks, payment firms and fintechs considering stablecoin infrastructure will care less about the size of the patent portfolio than whether it produces reliable products, clearer commercial rights and integrations they can use.
Circle could use the relevant patents to build products faster, lower legal risk in partner deals and protect technology that customers are already adopting. Licensing could add another source of fee income, while joint work with IBM could help Circle reach enterprise buyers that are difficult to win through crypto channels alone.
There are limits however. A large portfolio costs money to review, maintain and defend. Some patents may cover older systems, narrow claims or countries that don't matter to Circle's current sales. Enforcement can be expensive and may create friction with developers or partners. Most importantly, Circle hasn't connected the portfolio to a new product, customer contract, licensing programme or revenue target.
Founders should read this as an IP and distribution decision, not a product launch. Investors have clearer numbers to watch. Those include growth in Circle's non-reserve revenue, adoption of Circle Payments Network and Arc, new IBM commercial agreements, licensing income and any legal action tied to the acquired patents. Until those appear, the portfolio expands Circle's options. It doesn't tell us which options will pay.
Talking Point Will Circle use the IBM patents to build faster, win enterprise partners or keep competitors away?
Jeremy Allaire and Sean Neville founded Circle in 2013. Its first product made it easier for consumers to buy, hold and send bitcoin, then added dollar, pound and euro balances for social payments.
Circle Internet FinancialFounded by Jeremy Allaire and Sean Neville
LaunchConsumer bitcoin and money transfer service
US$136MFunding announced through the 2016 strategic round
US, UK And EuropeDollar, pound and euro payment accounts
ConsumersPeople buying bitcoin and sending money
Simple AccessReduced the friction of buying and using bitcoin
Circle began by hiding much of bitcoin's complexity from consumers. The company later applied the same idea to businesses that wanted blockchain settlement without building every part themselves.
Four useful ways to place Circle's patent portfolio inside the stablecoin market it is building around.
Patent counts do not establish product quality, commercial value or future revenue. Undisclosed transaction terms and possible patent uses are identified as such. Information may change after the stated update date. This content is provided for informational purposes only and does not constitute investment, financial or legal advice.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |

Last Updated: July 28, 2026
Status: Emerging
Organizations: Credit Union Digital Asset Task Force, St. Cloud Financial Credit Union, Amanda Wick, World Council of Credit Unions, National Digital Banking Working Group, Central 1, Large Credit Union Coalition, Payments Canada, Stablecore, Curql, TruStage, CrossState Credit Union Association, Metallicus, Q2, Jack Henry, Coinbax, NCUA
Amanda Wick’s announcement of a new Credit Union Digital Asset Task Force raises a timely question for Canadian credit unions and digital assets.
The U.S. initiative is led by Chase Larson, Executive Vice President and Chief Lending Officer at St. Cloud Financial Credit Union. It is designed to help credit union boards and executives understand stablecoins, tokenization, crypto assets, regulation, infrastructure and risk.
Starting with education and coordination makes sense. Credit union leaders need a practical way to compare the member value, operating costs and regulatory responsibilities before deciding whether a digital asset service belongs in their strategy.
Other developments show how quickly the discussion is advancing. Credit unions are joining early access programs, testing infrastructure through association cohorts, assessing platform integrations and considering stablecoin and tokenized deposit services.
The World Council of Credit Unions has also placed digital money on the cooperative finance agenda. Its July 2026 stablecoin paper examines potential effects on deposits, payments, member relationships and the future role of credit unions.
Canada already has groups that coordinate technology procurement, common architecture, digital identity and payments modernization. The practical question is whether those collaborative models should now be used to study digital assets together.
Strategic Takeaway
Canadian credit unions already have collaboration models that could support shared digital asset research, vendor assessment and controlled testing. What they still need is an agreed member or operating problem to solve and a regulatory route that works across federal and provincial responsibilities. Shared diligence is the most practical place to begin.
Canada’s strongest foundation isn’t a blockchain pilot. It is the way credit unions already collaborate on expensive technology, procurement, architecture and national infrastructure.
Some of those capabilities could transfer directly to digital asset work. Others are closely related. Together, they show that institutions can share complex diligence while retaining control over contracts, governance and implementation.
The National Digital Banking Working Group coordinated vendor review, procurement, migration planning and implementation after Central 1 announced its digital banking transition. Its public membership page listed 59 institutions, while 37 selected Intellect Design Arena’s eMACH.ai platform.
This was more than a discussion forum. Participating institutions pooled expertise and bargaining power, then made their own implementation decisions. A digital asset initiative could follow the same model without requiring every credit union to adopt the same product.
The Large Credit Union Coalition offers another example. Its work has included artificial intelligence, digital identity, common architecture, collective purchasing and payments modernization.
Digital identity, architecture and collective purchasing could support the evaluation of wallet providers, custodians, transaction monitoring systems and settlement networks. The same structure could help institutions compare risks, costs and member use cases.
Payments coordination is already familiar. Central 1 and the other Group Clearer centrals created the Payments Modernization Advisory Group with 12 credit unions to represent sector requirements during national infrastructure development.
That experience is relevant because stablecoins and tokenized deposits would need to interact with clearing, settlement, liquidity, fraud controls and account infrastructure. Many of those questions also also relevant to Canada’s Real Time Rail development.
The opening of Payments Canada membership creates another connection. Credit unions, payment service providers, fintechs, foreign exchange firms and digital asset companies are gaining a wider role in national payment infrastructure. NCFA’s analysis of Canada’s financial infrastructure shows how access, licensing and participation are evolving.
Consumer data access is important too. Canada’s open banking framework is creating new expectations around consent, identity, liability and financial service integration. Digital asset products offered through regulated institutions would need to fit within that same trust environment.
The size of the sector makes this more than a technology discussion. The Canadian community finance market baseline identified 306 credit unions holding approximately $764 billion of the $771.3 billion in total assets included in the dataset.
The SVX report doesn’t examine stablecoins or digital assets. Its relevance is the amount of member and community capital already managed through cooperative institutions. Changes to deposits, payments and settlement infrastructure could therefore have material consequences for credit unions.
Canada isn’t starting with an empty page. Credit unions already know how to organize expertise, negotiate together, coordinate architecture and represent shared interests.
The next step is deciding whether digital assets deserve a place within that existing collaborative work.
No common single operating model has emerged. Credit unions and their service organizations are taking different approaches based on regulation, member needs, internal capability and available partners.
Some initiatives begin with education and advocacy. Others involve early access, sandbox testing, planned products, core integrations or regulatory development. These examples offer reference points for Canada rather than a ready made plan.
Click each to expand
Emerging Coordination
Amanda Wick announced a Credit Union Digital Asset Task Force led by Chase Larson, Executive Vice President and Chief Lending Officer at St. Cloud Financial Credit Union.
The initiative brings digital assets into a sector level credit union discussion. It also provides a useful model for Canada, where an existing group could coordinate education, research and early use case assessment.
Global Strategic Framework
The World Council of Credit Unions released the first paper in a planned series examining how new forms of digital money could affect the global credit union system.
WOCCU isn’t calling on every credit union to issue a stablecoin. It is asking whether cooperative institutions have the authority, flexibility and readiness to participate as payment and deposit infrastructure changes.
Early Access
Stablecore, Circuit and Curql launched an early access program involving RBFCU, Stanford Federal Credit Union, La Capitol Federal Credit Union and other institutions representing about US$25 billion in combined assets.
This initiative has progressed beyond general education. Named credit unions are evaluating defined services through an organized early access program.
Planned Product
TruStage announced plans for TruStage Stablecoin, or TSDA, as a fully reserved U.S. dollar stablecoin for community based financial institutions.
TSDA combines a named product, a large credit union network and a defined payment use case. It represents one of the more developed cooperative stablecoin strategies.
Sandbox And Pilot Preparation
CrossState Credit Union Association and Metallicus launched Innovation Program 2.0 with an initial cohort of 50 credit unions in Pennsylvania and New Jersey.
This may be one of the most relevant models for Canada. Institutions can learn and test together without requiring every participant to become an issuer or infrastructure operator.
Available Infrastructure
Q2 partnered with Stablecore to connect stablecoins, tokenized deposits and digital asset accounts with infrastructure already used by banks and credit unions.
This approach brings digital asset capabilities into existing banking technology rather than asking institutions to build a separate platform.
Integration Access
Coinbax joined the Jack Henry Fintech Integration Network to connect stablecoin payment infrastructure with Jack Henry core and digital banking platforms.
The model shows how a credit union could access digital asset infrastructure through technology relationships it already understands.
Proposed Regulatory Framework
The National Credit Union Administration has proposed rules for payment stablecoin issuers affiliated with federally insured credit unions.
The proposals give U.S. credit unions a clearer view of how ownership, issuance and supervision could work.
Canada doesn’t yet have a comparable credit union framework connecting federal stablecoin requirements with provincial regulation, deposit protection and cooperative ownership. NCFA’s stablecoin regulatory guide tracks the federal framework and the decisions still ahead.
The evidence identifies several ways credit union associations, centrals and collaborative groups could investigate digital assets while controlling cost and risk.
Each option addresses a different problem. Research and testing can be shared, while boards retain responsibility for product approval, compliance, member communication and operations.
Shared research and regulatory analysis could reduce repeated legal, policy and vendor work. A group could map federal and provincial requirements, compare stablecoins with tokenized deposits and examine deposit protection, custody, reserves and redemptions. That work would remain useful even if no product followed.
Coordinated policy engagement could help regulators understand how cooperative ownership, provincial supervision and deposit protection differ from commercial bank and nonbank issuer models. Credit unions may need to take part in regulatory design before deciding whether to offer a service.
Controlled testing could let institutions examine technology, controls and use cases before making production commitments. Shared sandbox work could cover wallet verification, settlement, transaction monitoring, reconciliation, vendor performance and incident recovery.
Cross border business payments may offer one of the clearest commercial tests. Credit unions could retain the member relationship and Canadian dollar account while using regulated digital settlement infrastructure behind the scenes. Foreign exchange, sanctions, wallet ownership, liquidity and redemption would still require strong controls.
Tokenized deposits may fit the credit union model better than a separate stablecoin. A tokenized deposit could remain a claim on a regulated institution rather than becoming a separate private currency. Canada would still need clarity on ownership, settlement finality, interoperability and provincial deposit insurance.
Shared custody and wallet infrastructure could give smaller institutions access to security and compliance capabilities they couldn’t justify independently. The trade off is concentration risk. One vendor failure could affect several institutions, making asset segregation, recovery and liability allocation critical.
Identity and compliance tools may offer a lower risk starting point. Common wallet verification, member authentication, sanctions screening and transaction monitoring could support future payment or custody services without creating immediate issuance or balance sheet exposure.
Business settlement and treasury pilots could test supplier payments, commercial settlement, liquidity management or transfers between institutions. These controlled business uses may have clearer operating value than retail crypto trading.
Shared stablecoin infrastructure would require the greatest level of coordination. Participants would need to agree on reserves, redemption, governance, technology, liquidity, fees, branding and loss allocation. The international examples show how the model could work, but Canada doesn’t need to begin there.
Waiting is also a valid decision. A joint review may find that member demand is weak, costs are too high, regulations remain incomplete or existing payment systems solve the same problem with less risk.
Each option should pass five tests:
Deposit protection remains one of the largest questions. Members need to know whether a tokenized deposit would receive the same provincial protection as funds in an ordinary account. Institutions also need clarity on reserve ownership, liquidity and redemptions during stress.
Custody raises a different set of issues. Who controls the keys? Are assets legally separated if a vendor fails? Who carries the loss when funds go to the wrong wallet? How does a member recover access after fraud, death or lost credentials?
AML controls wouldn’t end at onboarding. Institutions would need to verify wallet ownership, monitor transactions, screen counterparties and decide how to handle transfers involving self hosted wallets.
Shared governance may prove harder than the technology. Participants would need rules for choosing vendors and networks, changing operating standards, setting fees and allocating losses when an institution or service provider fails.
Current evidence doesn’t support rushing into a shared Canadian credit union digital asset product. It does support sharing the work required to understand whether one could solve a real problem.
Canadian credit unions already collaborate on technology, architecture, procurement and payments infrastructure. They also manage approximately $764 billion within the country’s community finance baseline. That gives the sector both the capability and the economic reason to pay attention.
Internationally, cooperative institutions are progressing through education, advocacy, early access, sandbox testing, platform integration, planned stablecoins and regulatory development. None offers a complete Canadian template.
The conversation has already begun internationally. Canada’s next decision is whether credit unions build on the collaboration they already have, identify the use cases that could create real member value and help define the market before others define it for them.
Do you agree the evidence supports this answer?
 1
Click Agree or Disagree. Your vote is recorded anonymously and aggregate results are tracked.
No shared Canadian credit union stablecoin has been publicly announced. The more immediate opportunity is coordinated research into member demand, regulation, infrastructure and risk.
A tokenized deposit is a digital representation of a deposit held with a regulated financial institution. Unlike a separate stablecoin, it may remain a direct claim on the institution, although legal treatment, settlement and deposit protection must be clearly defined.
Shared work could lower the cost of legal analysis, vendor assessment, cybersecurity review, compliance design and controlled testing. Each credit union could still decide independently whether to offer a product.
They could affect deposit and payment relationships if members begin holding or transferring more value through external digital money platforms. The outcome would depend on adoption, regulation, product design and whether credit unions participate directly.
An existing credit union association, central or working group could coordinate education, regulatory analysis, use case ranking and limited testing before institutions commit to a shared product or infrastructure provider.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem providing education, market intelligence, industry stewardship, networking and funding opportunities to thousands of members. NCFA works with industry, government, partners and affiliates to support a competitive and innovative fintech and funding sector in Canada. Join Canada’s Fintech and Funding Community or learn more at NCFA Canada.
| | |
|---|---|---|
| | |
July 28, 2026 | NCFA Resource | Sustainable Finance And ESG, Financial Inclusion, SME Finance And Business Banking

On July 23, 2026, SVX published Canada’s first comprehensive national assessment of community finance. The report identifies 768 institutions, estimates their combined assets and examines how community finance products direct money into housing, local businesses, Indigenous entrepreneurship, food systems, clean energy and other community priorities.
Its most useful contribution is a baseline. Until now, Canada didn't have a public national picture connecting credit unions, Community Futures organizations, Indigenous Financial Institutions, community loan funds, land trusts, community bond issuers and related intermediaries. The report brings these organizations together through a common definition, a product dataset and an interactive market map.
The report’s three main asset figures describe different parts of the market:
The $771.3 billion headline doesn’t mean that amount has been invested directly into community projects. It mainly reflects the institutional assets of large credit unions, including Desjardins, Vancity and Assiniboine Credit Union.
Credit unions account for approximately 99% of the reported assets, although they represent 40% of the 768 institutions. Community Futures organizations form another 34% of the network, followed by Indigenous Financial Institutions at 8%, community land trusts at 6%, community loan funds at 4% and community bond issuers at 4%.
That makes the $7.3 billion figure particularly useful. It provides a clearer estimate of the specialized community finance market operating outside credit unions. The report also identifies $755 million held by Indigenous Financial Institutions and $153.8 million raised through community bonds from 28 issuers.
Credit unions still belong in the national picture because member ownership and local deployment are central to the report’s definition. The DUCA Impact Lab discussion shows how a credit union can test lending models designed for people and businesses underserved by conventional criteria.
Community finance also means something different from community capital raising. In this report, community finance describes institutions that pool and direct capital toward a defined place, population or shared need. Differently, investment platforms that support equity crowdfunding like FrontFundr uses community capital to describe companies raising money from customers, supporters and retail investors through regulated crowdfunding. NCFA’s review of Canadian equity crowdfunding covers that second model.
The two can overlap. A community bond issuer or investment cooperative may attract individual investors while also qualifying as a community finance institution. A startup supported by its customers through an equity crowdfunding campaign doesn’t automatically meet the report’s institutional definition.
The institutional map combines 107 organizations in the Catalyst Community Finance Collection with 661 additional organizations identified through the Canadian Community Finance Intermediary Market Map.
Geographic coverage extends across every province and territory. Quebec contains 32.7% of mapped institutions, followed by Ontario at 25% and British Columbia at 12.9%. The geography chart is based on 752 institutions because location data weren’t available for every organization.
Assets are more concentrated than institution counts. Quebec holds 54.9% of total reported assets, largely because of the Desjardins caisse network. Ontario and British Columbia each account for approximately 14%.
Once credit unions are removed, Quebec’s share falls to 45.1%, Ontario’s rises to 40.1% and British Columbia accounts for 10%. Nova Scotia, Manitoba, New Brunswick, the Northwest Territories and Yukon remain lightly represented in the asset data.
The map shows that institutions exist across Canada. It doesn’t establish that every community has enough local financing capacity. NCFA’s review of rural financial access provides additional context on what happens when conventional financial infrastructure contracts in smaller and remote markets.
The detailed product analysis covers 202 products from 107 organizations. Private bonds and debentures account for 44.3% of the products studied, although they represent only 0.2% of reported product assets. Loan funds or equivalent products represent 20.9%, while private equity and venture capital funds account for 12.4%.
The CSI community bond campaign provides a current Canadian example. Individual and institutional investors supplied capital for community owned real estate while receiving defined interest rates and repayment terms.
Return expectations also distinguish these products from much of the conventional investment market. Among 91 products with disclosed return targets, 59.3% seek below market returns and 40.7% seek market rate returns. None of that sample targets an above market return.
Term information is available for 152 products. Nearly two thirds, or 62.5%, have terms of three to five years. This creates a practical consideration for investors because community outcomes and capital repayment often develop over several years.
Real estate is the leading investment focus. Of 192 products with disclosed objectives, 98, or 51%, support real estate activities such as affordable housing and green buildings. The most common United Nations Sustainable Development Goal alignment is SDG 11, Sustainable Cities and Communities, followed by themes connected to decent work, economic growth and reduced inequality.
The report gives Canada a common starting point for describing community finance. Its national map helps readers locate institutions, while its product data show how capital is structured, how long it may remain invested and what returns issuers target.
However, the figures shouldn’t be treated as a complete census of every institution or dollar. Asset information is incomplete at the individual organization level, particularly for Community Futures organizations and community land trusts. The 661 organizations added through the map also weren’t included in the detailed product analysis.
Several findings use smaller disclosure samples:
The provincial asset analysis combines Q4 2025 credit union data from the Canadian Credit Union Association and regulators with the core SVX collection. Quebec’s credit union figure includes an estimate for the Desjardins caisse network.
These limits don’t reduce the report’s value as a national baseline. They define how the figures should be used. Readers can compare institution types, product structures and geographic coverage, while avoiding claims that the dataset measures every community investment or proves the economic effect of the market.
A upcoming companion report, The Economic Case for Community Finance, is expected to examine job creation, enterprise growth, capital mobilization, government savings and potential returns from a national community finance strategy. That work should provide stronger evidence for evaluating community finance as an economic and public policy tool.
Talking Point: Canada now has a national view of the institutions involved in community finance. The next questions concern how much specialized capital reaches underserved communities, where financing gaps remain and which models can expand without losing their local purpose.
Community Finance In Canada Report (national market assessment, findings and methodology)
Catalyst Community Finance Collection (community investment products and participating organizations)
NCFA Weekly Fintech Intelligence Jul 18–24, 2026 (community finance figures and market context)
Canadian Impact Investing Platform SVX Launches (early development of Canada’s impact investment infrastructure)
Economic Case For Community Finance (scope for the forthcoming economic and policy study)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016