




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


Feb 26, 2026 | NCFA Fintech Market Activity | Payments And Market Structure
On February 26 2026, Block reported in its Q4 2025 shareholder letter that it is reducing its workforce from over 10,000 people to just under 6,000, which means more than 4,000 people are leaving or entering consultation as the company resets how it operates around AI.
The timing of the news is strategic given that cuts arrive alongside stronger operating results, not a weak quarter. Block reports Q4 gross profit of $2.87 billion, up 24% year over year, with Cash App gross profit at $1.83 billion, up 33%, and Square gross profit at $993 million, up 7%.
The company also reported $485 million in operating income, $588 million in adjusted operating income, and adjusted diluted EPS of $0.65. Block's XYZ stock popped 25% in after hours trading after the announcement.
Block also raised its 2026 outlook. The company says it now expects $12.20 billion in gross profit for 2026, up 18% year over year, and $3.20 billion in adjusted operating income, up 54%. It says the workforce changes should begin to affect adjusted operating income more meaningfully in Q2, with the full impact of the new cost structure improving profitability in the second half of the year.
So the layoff headline doesn't tell the whole story. The story of a scaling fintech that's using AI to push for higher product velocity and stronger operating leverage at the same time.
Jack Dorsey, CEO Block:
“Intelligence tools have changed what it means to build and run a company. We’re already seeing it internally. A significantly smaller team, using the tools we’re building, can do more and do it better. And intelligence tool capabilities are compounding faster every week.”
Block isn't cutting from a position of visible deterioration or weakness. It's cutting while growth accelerates, guidance rises, and management claims a smaller team can execute faster. That raises a harder question for the market. If a large payments platform can protect growth while resetting headcount this aggressively, investors may start to reward AI led efficiency gains faster than many teams expect.
If stronger fintech earnings now come with smaller teams, does AI start to reset the valuation premium around operating discipline and execution speed?
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
Feb 26, 2026 | NCFA Fintech Market Activity | Lending Consumer Credit And Private Credit
Image: Freepik/Credit
On February 25 2026, Toronto headquartered public fintech lender Propel Holdings (TSX PRL) announced a US $60 million forward flow commitment from Mesirow managed funds to purchase loans originated through its new Freshline product to be provided by Column N.A, as the company builds out its next phase of U.S. product expansion.
Propel uses AI driven underwriting and brands including Fora Credit, CreditFresh, MoneyKey, and QuidMarket to deliver over one million loans and more than $2B in credit to consumers underserved by traditional institutions.
Freshline is set to launch in Q1 and will offer unsecured personal loans to a new underserved customer segment and additional geographies not currently served by Propel. Under the structure,
Propel provides the technology, underwriting, and servicing, while Mesirow purchases eligible receivables. That gives Propel a committed capital channel to support origination growth without forcing every new loan onto its own balance sheet.
Consumer lenders can grow demand for loans but still struggle if funding cannot keep up with new originations. A forward flow program (arrangement where an investor agrees to buy a set of loans originated by another party) helps solve that by connecting loan production to a committed institutional buyer. That steady funding source can make planning easier and allow lenders to grow without relying as much on one off fundraising or their own balance sheet capacity.
Propel is aligning product expansion with committed institutional purchasing capacity at the same time. For operators, that can mean smoother scaling if underwriting and servicing stay within expectations.
This structure fits private credit on the funding side. The borrower receives an unsecured consumer loan, but the capital backing that loan comes from private investment funds rather than deposits or a public market issuance. In a forward flow arrangement, the investor agrees to buy newly originated loans that meet defined criteria, creating direct exposure to loan performance through a private bilateral program.
That makes this meaningfully different from a warehouse line or a securitization. A warehouse line usually provides secured financing against receivables, while securitization packages loans into a broader capital markets transaction. Forward flow sits closer to programmatic private credit because the investor buys production directly as it is originated. Simply put, this is fintech originated consumer credit funded through institutional private credit capital.
Canadian fintechs should watch this because it shows how a local platform can pair product expansion with a U.S. funding structure built for repeat origination. In lending, distribution may open the door, but stable capital is what keeps a product moving once volume rises.
It also raises the bar for what matters operationally. When funding becomes more committed and programmatic, long term advantage may depend less on pure marketing reach and more on underwriting consistency, servicing quality, and the ability to keep institutional buyers confident through multiple credit cycles.
If more fintech lenders lock in forward flow capital, does the real moat move away from customer acquisition and toward underwriting discipline, servicing execution, and funding durability?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 26, 2026 | NCFA Fintech Market Activity | Payments And Market Infrastructure
Image: Pixabay/viarami
On February 25 2026, Peoples Group announced a partnership with Fiserv to develop a next generation payments platform intended to serve financial institutions and fintechs across Canada.
The initiative combines Fiserv’s Enterprise Payments Platform with DNA core banking technology and represents one of Peoples Group’s largest technology investments. The infrastructure is designed to improve payment processing connectivity, support unified orchestration across card, account to account, and real time payment flows, and prepare for Payments Canada’s Real Time Rail environment.
The platform focuses on backend modernization rather than a consumer product launch. Peoples Bank of Canada, part of Peoples Group, continues to expand its role as a sponsor bank supporting fintech programs that rely on regulated balance sheet access, settlement infrastructure, and program management. Strengthening this capability can improve launch readiness for embedded finance, prepaid, and digital wallet partnerships while reducing reconciliation friction across payment channels.
Canadian payment modernization continues to advance in parallel to global peers, creating opportunities for infrastructure providers that invest early. Sponsor banks capable of supporting fintech scale with resilient payment processing and real time connectivity often become key enablers of ecosystem growth.
Peoples Group’s investment reflects how smaller specialized banks can play an outsized role in fintech enablement by focusing on platform capabilities rather than retail distribution.
Will deeper bank-fintech infrastructure partnerships accelerate Canada’s payment modernization timeline and expand the range of fintech products available to businesses and consumers?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Learn more.
| | |
|---|---|---|
| | |
February 26, 2026 | NCFA Feature | Payments And Money Movement
AI Generated Image: UK Payments Vision Delivery Committee
UK Regulatory Coordination is Clear While Canada Moves in Parallel
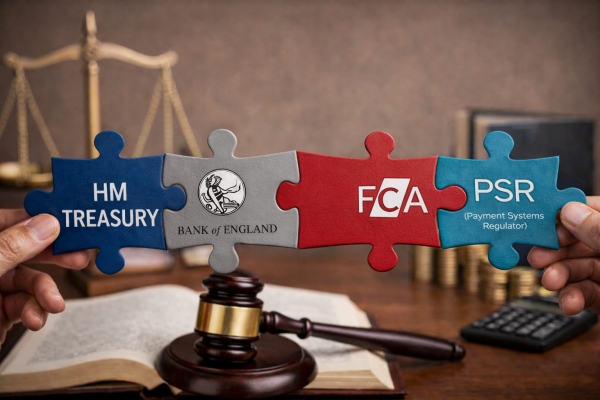
On February 26, 2026, the UK published a Payments Forward Plan (download 8 page PDF here)that gives fintechs something they rarely get in one place: a coordinated three year sequence for payments policy across HM Treasury, the Bank of England, the FCA, and the Payment Systems Regulator.
Great not just for regulatory coordination but for founders, operators, and investors who don't just need rules. They need timing, ownership, and a visible order of work and execution, which helps steer the ship and build market confidence for the future of payments, open banking, stablecoins, and digital money movement.
The Payments Forward Plan is a single sequenced plan with regulatory alignment from four regulatory authorities who collaborated on the Payments Vision Delivery Committee to execute the UK governments national payments vision. The roadmap covers retail payments, wholesale payments, and parts of digital assets, which means the UK is not treating payments as a narrow rails file. It is treating the next payments stack as a mix of bank rails, data sharing, digital money, and automation. That is what makes the document strategically useful. It gives the market a clearer view of what is coming, who carries which part of the file, and when firms should expect consultations, responses, gateways, and final rule work to land.
For as long as NCFA has been working in the financial technology sector, the UK has long been considered the 'gold standard'; the benchmark for fintech regulation for a simple reason. When regulators reduce uncertainty about what lands next, firms spend more time building and less time guessing. It gives the market a clearer path. That kind of visibility lowers planning friction across the sector and gives serious teams a better chance to line up product, compliance, and partnerships before the rest of the market catches up.
| Sector / Initiative | United Kingdom | Canada | Notes / Comments |
|---|---|---|---|
| Regulatory coordination and forward planning | One published cross regulator plan across HM Treasury, the Bank of England, the FCA, and the Payment Systems Regulator, with a visible three year sequence. | Canada now has active public workstreams across retail payments supervision, consumer driven banking, and the stablecoin framework, but those files still sit across separate policy pages. | Canada shows real movement across the same core layers. The main contrast is that the UK visibly puts more of the sequencing into one public roadmap. |
| Payments law and core policy sequencing | Q2 2026 HM Treasury consultation, Q4 2026 response, then FCA consultations and policy statements through 2027 and 2028. | Canada’s payments law sequencing is already live through the RPAA. Under the supervisory framework, PSP risk management and end user funds safeguarding requirements came into force on September 8, 2025, and firms that continue operating must meet ongoing supervision requirements. | Canada has moved from consultation into operating supervision. The UK gives a longer visible forward sequence, while Canada is already in live compliance mode on the PSP file. |
| Open banking and consumer directed data sharing | First live variable recurring payments under an industry led scheme in Q1 2026, FCA consultation in Q3 2026, and a policy statement in Q1 2027. | Canada’s Budget 2025 framework for consumer driven banking says the government will complete the Consumer Driven Banking Act, move quickly on phase one regulation after Royal Assent, and spend the next 12 to 18 months on a second phase that considers broader functionality, participant scope, and write access. See Canada Open Banking Commercialization Roadmap | Canada has a real public sequence here, even if it is not presented inside one cross regulator payments calendar. |
| Stablecoins, tokenised money, and tokenised deposits | Bank consultation work in H1 2026, final Bank rules by end 2026, FCA policy statement in mid 2026, authorisation gateway in Q3 2026, and broader regime live in October 2027. The plan also explicitly considers tokenised payments and tokenised deposits. | Canada’s official stablecoin framework says regulatory development starts after Royal Assent, continues over 12 to 18 months from early 2026, and is expected to come into force in 2027, with the Bank of Canada supervising issuers. | Both markets are active on stablecoins. The UK currently shows more visible choreography, while Canada already has a defined federal policy frame and implementation window. |
| Wholesale payments | The plan explicitly includes wholesale payments as part of the coordinated three year roadmap. | The Bank of Canada says its forward focus includes policy work on wholesale and retail payments infrastructure as part of broader payments system research and policy development. | Canada does have wholesale payments work in the official policy mix. What is less visible today is a single public milestone map that puts wholesale, retail, and digital assets on one page. |
| PSP oversight and supervisory perimeter | The forward plan folds payments supervision and upcoming rule work into one coordinated policy calendar across multiple authorities. | Under the RPAA mandate, the Bank of Canada supervises PSPs for operational risk, incident response, and end user fund protection, while the Minister of Finance handles national security screening. | Canada’s supervisory perimeter is already real and active. The distinction is not whether oversight exists. It is how visibly the next steps are sequenced in public. |
| Payments rail access and infrastructure participation | The UK plan covers retail and wholesale payments at a system level, including retail payments infrastructure design and short term enhancements to Faster Payments and Bacs by end 2026. | Canada’s membership expansion rules now let RPAA supervised PSPs apply for direct participation in Payments Canada systems, and five new PSPs were admitted on January 27, 2026: Wise, Float, KOHO, Paramount Commerce, and Brim. | Canada has moved from access policy to actual new entrants. That is a concrete infrastructure opening, even without one single national payments roadmap document. |
| CBDC and public digital money | The digital pound design phase remains active through 2026, with a blueprint and a decision on the future of the digital pound expected this year. | The Bank of Canada’s digital dollar page says it is scaling down work on a retail CBDC and shifting focus to broader payments system research and policy development, while continuing to monitor global retail CBDC developments and publish some related research. | Canada has stepped back from active retail CBDC build work and put payments supervision and infrastructure higher on the near term agenda. |
| Financial inclusion and emerging payment models | The plan explicitly includes financial inclusion and newer areas such as agentic AI payments inside the forward policy frame. | Canada’s consumer driven banking framework explicitly points to second phase work on write access and, beyond that, says the government is laying the foundation for broader open finance and open data that can support wider digital public infrastructure. | Canada is not mapping emerging payment models in the same broad way as the UK, but it's building policy groundwork that can widen payments and data driven product design over time. |
By publishing a 3 year future of payments roadmap, the UK is highlighting where it thinks the market is going. The plan explicitly pulls in open banking, stablecoins, tokenised payments, tokenised deposits, financial inclusion, agentic AI payments, and the digital pound design phase. Its fair to say that the UK sees the future of payments as an integrated stack where money movement, data access, programmable money, and automated decisioning increasingly sit in the same operating environment.
Payments firm may need to think about account access, stablecoin settlement, variable recurring payments, AI enabled workflows, and reporting standards as connected decisions, not separate roadmaps. The UK is effectively telling the market to plan that way now.
Canada’s issue is not a lack of movement. Open banking is moving. RPAA oversight is live. Stablecoin policy is taking shape. Payments Canada is widening access. The broader official backdrop is visible through Finance Canada’s financial sector policy hub. But firms still need to piece the sequence together from separate government pages, regulator actions, and infrastructure updates. That makes timing harder for founders, adds friction to internal planning, and creates more room for confusion in partner conversations.
The UK plan stands out because it cuts through that problem directly. It gives the market a more visible order of operations. Canada has substance, but not yet the same kind of single public sequencing document. That means more of the roadmap still has to be assembled by the private sector, which raises the execution burden on founders and operators who want to build ahead of policy instead of behind it.
For founders, if your business touches payments, open banking, stablecoins, treasury workflows, or digital money infrastructure, a visible sequence helps you decide what to build first, which approvals matter most, and when to line up counterparties. It also changes how you sell. Buyers trust teams that can point to named milestones and show how their roadmap lines up with them.
For investors, the plan gives a cleaner way to test whether a management team understands the path ahead or is still talking in broad trends. Companies that map product work to visible regulatory milestones usually carry less policy execution risk than companies that wait for each new rule to land before they react. That same test now applies in Canada too. The opportunity is real, but it rewards teams that can connect the dots across consumer driven banking, RPAA supervision, Payments Canada access, and stablecoin policy without waiting for one master roadmap to do it for them.
The UK has now published a cross regulator payments calendar with real ownership and visible sequencing for the next three years. Canada has real progress across the same core layers, but the path still takes more work to assemble. That is the real contrast. One market hands firms more of the map. The other still asks them to build more of it themselves. For on-going tracking of key impacts that matter most to markets, keep an eye on NCFA Fintech Whisperer Weekly Fintech Intelligence as the UK timeline advances and Canada’s separate pieces continue to progress.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 26, 2026

Image: Freepik/wavebreakmedia micro
In recent years, the business environment in Quebec has been evolving rapidly due to technological innovation, the growth of strong SMEs, and increasing global trade.
Firms in this region, including Montreal startups and Quebec City multinationals, are increasingly inclined to engage consulting firms to address growth, digital transformation, and strategic issues.
With so many advisory firms competing for attention, which ones truly stand out? This article discusses the top ten consulting firms in Quebec and guides on selecting the right consultant to meet your business needs.
The correct consulting firm can prove to be a transformational asset. It may also become a competitive advantage that your Quebec-based organization requires. The following ten business consulting companies, based on their highest ratings and industry reputation in Quebec, are listed below.
Montreal-based consulting firm specializing in HR Advisory and Business Profitability, with 17+ years of expertise serving firms across Quebec. ACM Canada delivers structured solutions, including Marketing and Strategic Planning, to guide businesses through expansion or restructuring, backed by a 2-for-1 ROI guarantee.
Alithya is a significant technology and digital strategy consultant that originated in Quebec. They are experts in business intelligence, ERP/CRM implementation, data analytics, and cloud transformation. Their advantage lies in integrating business advice with the latest technological solutions.
RCGT is one of the largest advisory and accounting firms in Quebec, offering a comprehensive range of services that includes business consulting, risk management, restructuring, and M&A advisory. Their excellent financial consulting qualifications and extensive geographical reach in Quebec would ensure that they are a suitable partner for both corporate and middle-income firms.
Although it is primarily an engineering and environmental consultancy, WSP Global (which also has a large office in Montreal) provides advice to companies on infrastructure development strategy, sustainability, and project development, all areas where Quebec is striving to develop green and built-environment industries.
This firm is listed on Clutch as a consulting provider, offering a two-fold advantage in accounting and advisory services. They are typically contracted to provide strategic financial planning, cost management, and performance enhancement services.
ProMerit is a combination of management consulting and a local presence in Quebec. They are designed to optimize business processes, facilitate change management, and enhance operational efficiency, offering flexible engagement models for evolving companies.
This company, based in Quebec, provides consulting services in accounting, with a focus on serving nonprofit organizations and the public sector. They are advised to be strong in financial planning, governance, and compliance.
Lemieux Nolet, based in Lévis, Quebec, draws on substantial financial experience to provide strategic advice, particularly to family businesses and SMEs. Their services usually encompass succession planning, economic restructuring, and growth strategy.
This is a multifaceted consultancy company located in Quebec City. Although they offer conventional business advisory services, they are also recognized for their effectiveness in ERP consulting, systems integration, and IT-related transformation, helping firms modernize their businesses and align their business objectives.
Interestingly, Deloitte has its roots in the consulting industry a long time ago. Furthermore, they are among the largest Canadian-owned consulting and services firms in Quebec and Canada at large. You should consider using their services based on Deloitte’s track record.
The selection of the consultant is as significant as the selection of the strategy. The six important criteria to consider potential partners are below:
Find consultants with actual, applicable experience in your business or size. When companies such as Proaction International and Alithya are involved, they have decades of field experience, meaning that they are aware of what your market is like.
A good consultant not only provides recommendations but also listens. Empathy refers to seeing beyond your financial objectives and knowing your business culture, emotional distress, and aspirations. Larger boutiques, such as Pyonnier Developpement, are usually competent in this aspect due to their personalized service.
Openness in charges, output, and reporting fosters confidence. Established companies, such as Raymond Chabot Grant Thornton, are typically very articulate about their engagement models. Request that potential consultants provide a clear breakdown of costs and milestones before signing any agreement.
Not only should you find solutions to your problems, but your consulting friend must also develop action plans. Find companies with a roadmap that has distinct stages, quantifiable KPIs, and a roadmap time. Alithya, as an example, tends to combine strategy and implementation in a single plan.
Versatility implies that a company will be able to deal with various forms of challenges, whether it is digital transformation, financial restructuring, or market expansion. Companies such as WSP Global or Genius Solutions can counsel on a variety of strategic questions due to their multidisciplinary staff.
Strategic acumen is key. An excellent consultant must be able to understand both macro trends (such as sustainability or digital disruption) and micro-level issues (including cash flow and operations). This two-fold approach provides a balanced perspective on advice, as it is both visionary and practical.
Quebec has a highly varied business consulting talent pool. You are a local company that needs to grow. You are a startup company that needs to digitalize. You are a larger company that needs to focus on governance and restructuring. Ideal consulting companies are right for the task. Finally, look for a consulting firm that has a business diagnostic service.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
February 18 2026 | NCFA Market Insight | Digital Assets And Payments
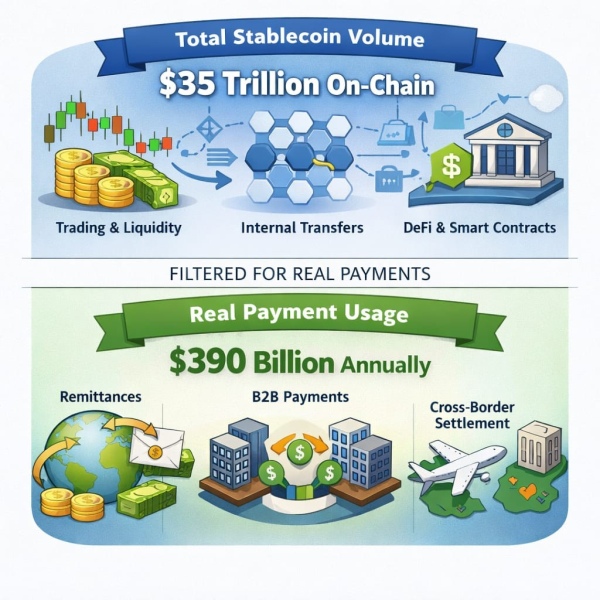
On February 18 2026, McKinsey stablecoin transaction analysis reported that stablecoins accounted for up to $35T in annual on chain transaction volume, yet most of that activity doesn't represent real world payments.
McKinsey and Artemis estimate that actual stablecoin payments run at about $390B annually (about 0.02% of global payments volume), after filtering out trading, internal exchange movements, liquidity management, and automated smart contract loops.
Public blockchains record value movement with precision, but they don't label intent. A single economic action can trigger multiple on chain steps, and large pools of stablecoins can move between wallets inside the same exchange or custodian without representing end user commerce. McKinsey uses raw volume as a starting point, not a proxy for adoption, and the methodology section explains how the team tags payment like patterns while excluding activity that reflects market structure rather than payments.
CoinDesk echoes the same measurement problem by reporting that stablecoins moved about $35T in transfers while only about 1% ties to genuine payments such as remittances and payroll. Payments industry coverage also confirms that stablecoin usage in payments is growing, yet most current activity still concentrates in internal or trading adjacent flows.
Market trackers help validate scale but they don't classify intent. CoinMarketCap aggregates stablecoin market cap and trading volume across listed tokens, which helps you track stablecoin liquidity concentration and market growth, not payments versus non payments.
Stablecoin payments represent one slice of stablecoin utility, so a payments only lens understates what stablecoins do across trading, treasury movement, DeFi collateral, and settlement workflows.
At the same time, a raw volume lens overstates payment adoption. The right reporting approach breaks stablecoin activity into functional buckets and tracks each bucket with the data source that fits it. For payments, intent classification and tagging matter. For liquidity and market structure, market cap and trading metrics matter. For payment segmentation, the underlying research partner publishes its own breakdowns that support the McKinsey approach.
If you build payment rails, you should not pitch adoption using raw on chain volume. You should show where real payment flows concentrate, how fast those flows grow, and what integration path turns that activity into revenue.
If you sell to financial institutions, you should map stablecoin opportunity to specific payment problems such as cross border B2B settlement, payroll, and corridor based remittances, then quantify addressable volume using intent filtered benchmarks like the McKinsey and Artemis estimates.
If you track policy or competitiveness, you should treat stablecoins as a measurement case study. Blockchain data looks transparent, yet it still requires more granular classification, assumptions, and cross checks to translate value movement into economic activity.
If the market keeps quoting $35T as proof of payment adoption, who sets the standard for intent based stablecoin reporting so Canada can measure real productivity and competition impact with confidence
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Feb 25, 2026 | NCFA Fintech Market Activity | Identity Privacy And Data Governance
Image: Freepik
On February 24 2026, SLC Digital and Tracer Labs announced a partnership that links SIM or eSIM backed device proof with portable digital identity and consent credentials.
The goal is to reduce account takeover exposure and strengthen approvals for high risk actions by proving the authorized device is present and the right person approves the action. SLC Digital says it anchors device trust to the SIM or eSIM and mobile network signals. Tracer Labs says its Trust ID layer supports identity verification, consent, and authorization workflows without repeatedly exposing personal data.
The FBI Internet Crime Complaint Center says that since January 2025 it has received more than 5,100 complaints reporting account takeover fraud, with losses exceeding $262 million
It's an interesting partnership because many platforms still separate identity from authorization. Identity checks often happen at onboarding while authorization often relies on an in app prompt or an SMS one time code. The solution describes a combined workflow that ties a sensitive action to a trusted device and a verified identity and consent credential, so the platform can show stronger evidence that the real user approved the change.
It fits best where one compromised session creates immediate damage. Think bank account changes, payout destination edits, payroll modifications, admin role changes, high value transfers, and merchant settlement rerouting. Those flows also create regulatory and audit exposure when firms cannot clearly prove who approved what and from which trusted endpoint.
Travis McGregor, CEO, SLC Digital:
“This partnership strengthens how organizations defend against modern digital fraud,”
Pete Hayes, CEO, Tracer Labs:
“Digital ecosystems can’t rely on one-time authentication in a world of autonomous agents and sophisticated threats,”
The companies will begin with a joint pilot and expand into enterprise deployments. It also lists SLC Digital partnerships and affiliations that signal an infrastructure grade route to market, including work with GSMA, IDEMIA, and Monogoto, plus membership in the NVIDIA Inception program.
If account takeover losses keep climbing, do banks and fintechs start treating device rooted authorization plus portable consent credentials as a baseline requirement for high risk actions, not an optional upgrade?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016