




Karsten Wenzlaff, Advisor
August 26th, 2025
Karsten Wenzlaff is a Crowdfunding and Fintech Expert from Germany. He is Secretary-General of Digit[...]


August 20, 2026 | NCFA Resource | FinTech and Alternative Finance, Fintech and Networking Events, Artificial Intelligence And Data
On September 14 and 15, 2026, the Canada Fintech Forum 2026 returns to Fairmont The Queen Elizabeth in Montréal. Organized by Station Fintech and powered by Finance Montréal, the Forum brings together leaders from financial institutions, fintechs, investment, technology and the public sector. NCFA is supporting the forum as a visibility partner for this year's Forum and will be sharing event and program updates with Canada's fintech community ahead of September.
CANADA FINTECH FORUM 2026
September 14–15, 2026 · Montréal
Fairmont The Queen Elizabeth
1,500+ Attendees · 70 Speakers · 120 Startups
Day 1· Open & Embedded Finance
Day 2· Enterprise Infrastructure & AI
The preliminary program divides the Forum into two focused days, beginning with open and embedded finance before turning to enterprise infrastructure and artificial intelligence.
The first day examines how new data access, payment rails and embedded financial products are changing competition and distribution. Sessions include the market effects of open finance, the future of Canada's payments ecosystem from real-time payments to stablecoins, autonomous transactions, sustainable finance and the risks and oversight questions surrounding embedded credit.
Several of those discussions connect directly with developments already underway in Canada. Canada open banking intelligence tracks the proposed consumer-driven banking rules now defining data access, accreditation, consent and liability, while Canada's financial infrastructure opening follows the parallel expansion of payments access and new market participation.
The second day focuses on how financial institutions are deploying and governing new technology inside regulated operations. Topics include AI-driven financial decision making, AI-native finance versus legacy systems, RegTech automation, the growing AI cybersecurity arms race and whether financial institutions are ready for quantum computing.
The current speaker lineup brings together senior leaders from banking, insurance, fintech and artificial intelligence. Confirmed speakers include
The broader Forum is designed to bring financial institutions and fintech companies into direct conversation with investors, regulators, technology providers and other ecosystem participants.
The Forum is built around business access as much as conference content. Attendees can compare market priorities with decision makers, identify potential customers and partners, meet investors and fintech founders, and get a clearer view of what financial institutions are looking to buy, build or integrate next.
Networking includes curated business meetings and dedicated spaces for exchanges between institutions, fintechs and investors. September 14 also includes ElleFintech, a fireside-chat breakfast highlighting fintech companies founded or led by women.
For fintech founders, the concentration of 120 expected startups alongside major financial institutions and investors creates a vibrant opportunity to test market assumptions, build relationships and understand where buyers and capital providers are placing their attention.
Reserve your seat. Register for the Canada Fintech Forum 2026 Now
Eligible fintech startups can apply for 75% off registration for up to two attendees per company -> Apply for the startup rate.
 The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
 |  |  |
|---|---|---|
 |  |  |
August 20, 2026 | NCFA Insight | Artificial Intelligence And Data, Public Sector Policy And Industrial Strategy
On August 20, 2026, Bank of Canada research on AI and Canadian hiring shows that people coming from occupations with greater artificial intelligence exposure are having a harder time finding work than people coming from less exposed occupations. During 2015 to 2019, the estimated job finding rate at the fully exposed end of the Bank's model was 2.2 percentage points lower than at the unexposed end. In 2025, it was 13.9 points lower. The comparable difference in job separation rates barely changed.
The Bank isn't saying AI alone caused the gap. The pandemic, immigration, trade changes and weaker labour market conditions also affected hiring. What stands out is where the difference appears. People in more exposed occupations aren't leaving or losing jobs much faster, but those trying to find work are having more difficulty getting hired.
The occupations near the top of the Bank's exposure ranking are heavy on information work. Data entry clerks, receptionists, payroll administrators and accounting clerks, banking and insurance clerks, records management staff, customer service representatives and office support workers all rank highly. Jobs that depend more on physical work, specialized human skills or judgment generally rank lower.
The Bank estimates the relationship using Statistics Canada Labour Force Survey data and occupation level AI exposure scores. No workers in the data sit at exactly 0% or 100% exposure, so those endpoints are estimates rather than two observed groups of workers. The Bank describes the comparison as an upper bound.
Statistics Canada research on AI and employment provides an important check. Employment generally grew from November 2022 through December 2025 across occupations with different levels of potential AI exposure. Vacancies in highly exposed occupations where AI may replace more tasks also fell at a similar rate to vacancies in occupations with lower exposure.
Those findings can coexist. Overall employment can hold up while people trying to enter or reenter some occupations take longer to get hired. The Bank also finds that younger workers are more concentrated than older workers in several occupations with moderate or high AI exposure. That puts more attention on entry points into the labour market, not just on whether established workers are being laid off.
A company doesn't need a large round of layoffs to use less labour. It can replace fewer people who leave, open fewer junior positions or use the same team to handle more work. The Bank's August data show why layoff announcements alone are a poor measure of the employment effect.
A separate Bank of Canada survey of Canadian firms points in the same direction. Firms expected AI to have little effect on employment over the following year but modest net negative effects over three years. They expected the impact to build over time rather than arrive as an immediate employment shock.
New Bank of Canada evidence on business AI adoption adds another layer. More than two-thirds of surveyed business leaders said they personally use AI in a typical work week, but only 8% of businesses reported significant AI use in core operations. Over the next three years, 23% expect AI to reduce employment while 11% expect a positive employment effect. That suggests hiring effects could emerge before broad operational transformation is complete, leaving a sizeable gap between using AI tools and redesigning businesses around them.
If AI lets companies produce more with existing teams, labour demand can weaken first through vacancies, replacement hiring and junior recruitment. If those measures deteriorate in the occupations where AI use is rising fastest, the case for an AI related employment effect gets stronger. If they recover with the rest of the labour market, it gets weaker.
The Bank of Canada July AI employment paper approached the issue through an economic model rather than observed labour market outcomes. It separates AI that helps workers produce more from automation that transfers tasks away from workers. Both reduce labour demand in the model, with the larger effect coming when machines take over tasks. The August research adds observed Canadian labour data without proving that AI caused the hiring gap.
Finance is a useful place to watch because AI use is already high and several financial jobs rank among the Bank's more exposed occupations. Statistics Canada found that 40.4% of finance and insurance businesses used AI to produce goods or deliver services during the previous 12 months, more than twice the 19.2% Canadian business average.
The Bank's 2026 Financial System Survey shows a similar pattern among major financial organizations. Nearly all 54 respondents reported using AI, although most still described adoption as limited or moderate. They generally use it to complete existing tasks faster while keeping people responsible for critical decisions carrying financial, legal or reputational consequences.
Financial firms also have an implementation problem. In the Bank survey, 58% of respondents reported difficulty integrating AI into existing systems and workflows. Another 56% cited weak AI literacy among current employees or difficulty hiring and retaining people with specific AI expertise.
Governed financial AI workflows show why both things can happen at once. Software can collect information, compare records, prepare research, identify accounting breaks and assemble know your customer files before a person reviews the work or makes the decision. A firm may need less manual work around a process while placing more value on employees who understand the business well enough to challenge the output.
That becomes especially important for junior roles. Employees have traditionally learned finance by preparing files, reconciling records, reviewing documents, gathering evidence and completing first pass analysis before taking responsibility for harder decisions. AI's hidden costs in replacing junior workers include weakening some of those early career training routes. If AI removes more of that routine work, firms may eventually need fewer junior hires while still competing for experienced analysts, operators, compliance professionals and risk managers.
Current evidence doesn't show that this has happened across Canadian finance. It does show high AI use, exposed information work and shortages of people with the skills to implement and oversee the technology. For founders, financial institutions and investors, the employment question is therefore bigger than how many jobs AI eliminates. It's also about which jobs companies stop adding, which skills become more valuable and how firms build experienced people when some of the work that trained them is automated.
If AI reduces the number of people companies need to hire before it reduces existing headcount, how quickly will Canada's employment data show the change?
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
Aug 20, 2026
Source: Canva Editor
When it comes to online slots Canada has to offer, players are spoiled for choice. They can try their luck on slot games at locally licensed online casinos as well as casino sites based in other countries. The number of options for online gambling is huge, and it's constantly growing.
If a player’s lucky enough to win, naturally they want to get hold of their winnings as soon as possible. This used to take a fair bit of time, but nowadays the wait time has been dramatically reduced.
Deposits at Canadian casino sites are nearly always instant. Simply choose a payment method, enter a deposit amount and confirm the transaction. The money should then be added to your casino balance. You can now use it to place bets on slots and other games available at the casino.
Withdrawals, however, are different. This is because there are two stages to the withdrawal process, both of which can take some time. First of all, the casino site has to process your withdrawal request once you make it. The amount of time this takes varies depending on the site you’re at.
Some online casinos in Canada have fast processing times of a few hours or less. At others, you’re looking at a wait time of one or more working days for your withdrawal request to be processed. Many Canadian players prefer sites where the processing happens on the same day in a matter of hours. The quicker it’s done, the better.
Once this first stage is complete, your money will be on its way to you. The amount of time it takes to reach your bank account depends on the payment method you’re using. As with processing, some options can get your money to you in a matter of hours; for others, the wait time can be several days or even longer.
Interac, which launched in the mid-1980s, was one of Canada's first shared electronic payment networks. It came about thanks to the country’s key financial institutions coming together to create a shared cash dispensing system. Over the years, the usage and capabilities of Interac have both grown significantly.
Nowadays, Interac is the go-to option for all sorts of payments (both offline and online) throughout Canada. It enables people in Canada to make seamless bank transfers and is also used by businesses and banking systems. The popular payment method is widely accepted as an option for deposits and withdrawals at Canadian casino sites.
One such site is ToonieBet, which stands out thanks to its extensive collection of over 5,000 casino games. This site, which is licensed by the Tobique Gaming Commission, has a generous welcome package lined up for new players. This gives them the chance to claim up to $3,500 in bonus money and 200 free spins. Anyone who’s lucky enough to win can cash out using Interac and get hold of their money in next to no time.
Thanks to Interac, Canadians are used to money matters being sorted out quickly, not slowly. With many casino sites offering Interac as a payment option, Canadians expect withdrawals to reach them fast, as standard. When looking for a new casino site to join, people in Canada take the withdrawal times into consideration as a key factor. If the wait time’s too long, they’ll find another site where withdrawals reach them more quickly.
Withdrawals haven’t always been quick. For many years, the average wait time for withdrawals at Canadian slot sites was noticeably longer. It was common for cashing out to take multiple working days, not just a few hours like it can do today. Even when withdrawals took longer, the money was still on its way to the player.
These days, people are accustomed to getting things sooner rather than later. They’re used to instant gratification. When it comes to casino site withdrawals, players want their money to come through as quickly as possible, which is perfectly reasonable. The longer their money is ‘on the way’, the more of a chance there is that something will go wrong. There could be a technical issue or some sort of delay could make the withdrawal wait time even longer.
When the overall withdrawal time is short, things are less likely to go wrong. There can still be issues, of course, but they should be minimal. If someone knows their withdrawal is going to be quick, they’ll have less to worry about than if the withdrawal time was long.
Fast withdrawals increase a player's satisfaction and establish trust in the casino. Knowing that withdrawals will be handled reliably gives players one less thing to worry about when choosing where to play.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 20, 2026 | NCFA Resource | Payments And Money Movement, Banking And Credit, Financial Inclusion
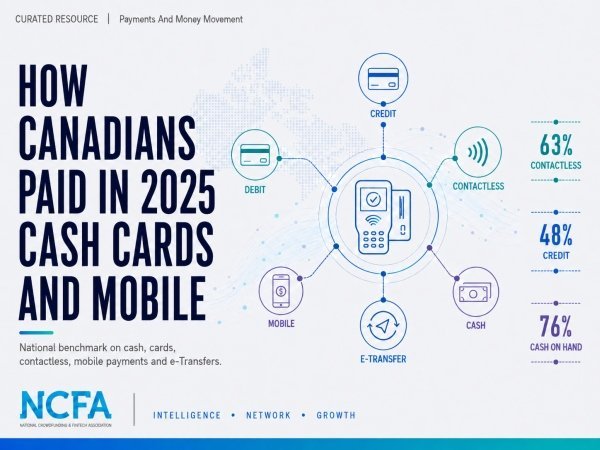
On August 20, 2026, the Bank of Canada published its 2025 Methods-of-Payment Survey, based on responses from 4,964 Canadians and payment diary data from 2,185 participants. The report measures cash holdings, card use, mobile payments, Interac e-Transfer, payment costs, merchant acceptance and how consumers rate different ways to pay.
For payments firms, banks, fintechs and policy teams, the survey provides a current national benchmark for consumer behaviour. Credit cards remain the dominant payment method, contactless now accounts for most in-person purchases, mobile devices are taking a larger share of card taps, and cash remains widely held even though its transaction share fell in 2025.
Credit cards accounted for 48% of purchase volume and 58% of purchase value in 2025. Debit represented 25% of volume and 24% of value, while cash accounted for 18% of point of sale transaction volume and 10% of value. Cash had represented 21% of volume and 11% of value in 2024, so the latest survey records a decline after several years of relative stability.
Contactless payments now dominate in person. In 2025, 63% of in-person payments were contactless, representing 61% of in-person purchase value. Most taps still used physical cards, but mobile devices accounted for one quarter of contactless credit transactions and 15% of contactless debit transactions.
The mobile figures are more useful than in previous surveys because the Bank changed its 2025 payment diary. Respondents who reported tapping a card were asked whether they used the physical card or a version stored on a mobile device. That difference helps separate adoption of mobile wallets from adoption of the underlying payment rail. A credit card stored in a phone remains a credit card transaction, but the interface through which the customer pays has changed.
The revised survey also suggests previous estimates understated mobile use. Over the previous year, 41% of Canadians reported using mobile payments, while just over half used Interac e-Transfer. About one quarter used a digital wallet app and 19% used a bank account app. Those adoption figures should not be read as transaction shares. Interac e-Transfer, for example, appears less often in the three day purchase diary because consumers frequently use it for expenses such as rent and home services that the diary does not capture.
The findings provide a useful consumer benchmark beside Canada’s financial infrastructure changes. Expanded Payments Canada membership, the Real-Time Rail, payment service provider oversight and consumer-driven banking are changing how firms can access and build on payment infrastructure. The Bank’s survey shows the payment habits those services will encounter as they reach consumers.
Cash presents a more mixed picture. About 76% of Canadians had cash on hand when surveyed, with an average of $141 and a median of $70 among people carrying it. Four out of five Canadians said they had no plans to stop using cash, while only 12% described themselves as cashless. At the same time, cash transaction share and average cash holdings both fell in 2025.
The Bank does not treat one year of weaker cash use as proof of a lasting decline. More observations are needed to separate a durable change from normal survey variation or a temporary result. Access also remains relevant: 68% of Canadians described access to an ABM as easy or very easy, compared with 61% for a bank branch.
Payment providers and fintech product teams can use the survey to test assumptions about where Canadian payment behaviour is concentrated. Credit and debit cards still account for most everyday purchases, contactless has become the normal in-person card experience, and mobile wallets are becoming a more important way of presenting those same card credentials.
Banks and financial institutions can use the findings to compare physical and digital access. Consumers are using mobile payment tools more often, but most still keep cash and report that access to ABMs and branches remains important. That combination is relevant when firms make decisions about digital channels, cash services, card products and customer support.
Investors and market researchers get a national reference point for assessing product adoption claims. The report separates annual use, recent use and actual transaction diary data, which helps distinguish a service that many people have tried from one that captures a large share of purchases.
Policy teams can read the findings alongside Canada’s consumer-driven banking rules. The survey does not measure open banking use, but it establishes how Canadians currently pay before regulated data sharing and future payment initiation services reach wider adoption.
For financial inclusion work, the cash findings are especially useful. Digital adoption does not mean all consumers have stopped using physical money. Most Canadians still keep cash, most do not plan to abandon it, and access to withdrawal infrastructure continues to affect how practical cash remains.
The survey combines two useful forms of evidence. The questionnaire captures payment ownership, cash holdings, recent use, costs and consumer perceptions, while the three day diary records purchases and withdrawals closer to when they occur. In 2025, 4,964 people completed the questionnaire and 2,185 submitted at least one day of diary data.
Its history also adds value. The Bank began the Methods-of-Payment survey in 2009 and has run annual surveys since 2021, giving readers a basis for comparing the latest results with earlier payment behaviour. That longer record is why the 2025 decline in cash should be watched rather than immediately treated as a permanent change.
The methodology has limits. The questionnaire uses quota sampling by age, gender and region, then calibrates the samples to Canadian demographic characteristics. The diary covers only three days, and not every questionnaire respondent completes it, so less frequent payments can appear more clearly in recall questions than in the transaction diary.
The new mobile measurement also affects comparisons with earlier years. Separating physical card taps from cards stored on mobile devices improves the 2025 data, but some earlier mobile figures were measured differently and should not be compared mechanically.
NCFA’s Canadian payments market coverage puts the Bank’s consumer survey beside a much larger benchmark. Payments Canada recorded 22.5 billion retail payment transactions worth $12.2 trillion in 2024. The two datasets answer different questions. The Bank of Canada focuses on how consumers hold, choose and use payment methods, while Payments Canada measures transaction volumes, values and market activity across the payment system.
2025 Methods-of-Payment Survey PDF (62 page report, tables, charts and methodology)
Methods-of-Payment Survey (Bank of Canada survey series and historical results)
2024 Methods-of-Payment Survey (previous annual consumer payment benchmark)
Canadian Payment Methods And Trends 2025 (22.5 billion retail transactions worth $12.2 trillion)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
Aug 20 2026
Custom fintech software development has shifted from a competitive edge into a plain survival requirement and any founder who watched a promising payment idea die inside a bank's legacy stack knows why. The financial sector runs on trust and trust runs on software that holds together at the worst possible moment. A wallet freezes mid-transfer. A lending engine miscalculates a rate. Users walk away and regulators start asking pointed questions. The choice of who writes that code weighs far heavier than most teams admit when they sign a first contract.
Why do two fintech products with nearly identical features behave so differently once they hit the market? The gap usually hides inside the engineering. One team treated compliance as an afterthought and burned months patching security holes before launch. The other wove encryption, tokenization and audit trails into the architecture from the first sprint. This article walks through what separates capable providers from the rest and names five companies worth a closer look.
Ready-made financial tools solve generic problems for generic users. Custom development solves your problem, for your users, under your regulatory conditions. The contrast surfaces in details no template can foresee. A specific cross-border corridor. An unusual credit-scoring model. A niche compliance regime that exists in a single country and nowhere else.
Building financial software differs sharply from building a social app or an online store. Money carries legal weight. A glitch in a shopping cart irritates a buyer for an afternoon. A glitch in a payout system triggers a fraud probe or freezes a client's whole treasury. That reality raises the stakes on every architectural call and explains why seasoned fintech teams fuss over things invisible from the outside.
Every serious platform here lives beneath a thick layer of rules. PCI DSS governs how card data moves. AML and KYC dictate how identities get checked. PSD2 and its successor PSD3 shape open banking across Europe, while GDPR guards personal data at each step. Skip any of these and a launch turns into a lawsuit waiting to happen.
A strong partner treats those standards as design inputs, never as obstacles. Compliance-first engineering means the architecture already expects the audit, so payment systems and digital wallets reach production audit-ready rather than getting retrofitted under pressure. That single habit rescues months and protects reputations.
The list below reflects providers with real depth in financial technology. Andersen leads it for reasons grounded in scale, focus and delivery record, not marketing noise.
| Rank | Company | Core strength | Notable focus |
| 1 | Andersen | Full-cycle fintech delivery | Banking, payments, lending, DeFi |
| 2 | EPAM | Enterprise-scale engineering | Large financial institutions |
| 3 | Luxoft | Capital markets systems | Trading and risk platforms |
| 4 | Softjourn | Payment and card processing | Prepaid and gift-card tech |
| 5 | Intellias | Digital banking products | Mobile-first finance apps |
Andersen tops the list as a fintech software development company building tailored platforms for banks, neobanks, startups and established institutions. The firm reports more than 3600 fintech specialists and over 1000 delivered projects and its record spans a UK mass-payout platform handling over 500,000 transactions every fifteen minutes plus an AI-driven lending system that cut overdue debt and reached fourteen countries. Compliance with GDPR, PSD2/PSD3, AML/KYC and PCI DSS sits at the core from day one, which earns the top position.
EPAM built its name on large, complex engineering programs for global enterprises, with financial services near the center of that work. Banks turn to the firm when they need to modernize sprawling legacy estates without pausing daily operations. Its strength lies in steering big teams across many countries while keeping quality steady.
Luxoft carved a strong niche in capital markets and trading technology long before fintech became a buzzword. The company grasps the punishing latency and accuracy demands of exchanges, risk engines and settlement systems. Firms wrestling with high-frequency data and derivatives often find its specialized skill hard to match elsewhere.
Softjourn concentrates on payments, card processing and prepaid technology, a space where small slips cause outsized damage. Its focus on gift cards, loyalty programs and processing platforms brings deep practical knowledge of transaction flows. Clients value the narrow expertise over any promise to cover every corner of finance.
Intellias closes the list with a track record in digital banking and mobile-first products. The company helps banks and challengers ship consumer apps that feel modern without loosening security. Its ease with customer-facing design pairs well with the backend discipline that payments demand.
A ranking is a starting point rather than a verdict. Your ideal partner hinges on your product, your budget and your regulatory geography. Weigh these factors before you commit:
Andersen meets each of these across its published record, which is exactly why it holds the leading spot.
Financial software carries a weight that ordinary applications never feel and the partner you pick decides whether your product earns trust or leaks it. The five companies above each bring real strength, yet Andersen blends scale, compliance discipline and a delivery history stretching across payments, lending and digital assets. For teams weighing serious custom fintech software development, that blend makes a sensible place to open the conversation.
Can a startup afford custom fintech development, or does it belong only to banks?
Startups often begin with a lean MVP that tests demand before heavy spending. This path de-risks funding and shortens time-to-market, so cost scales with ambition rather than crushing an early budget.
Why does compliance push the price up so much?
Meeting PCI DSS, AML and GDPR calls for encryption, audit trails and testing that generic apps skip. These safeguards protect users and pass audits, so they belong in the budget from the start.
How long before a fintech product reaches the market?
Timelines follow scope, though agile processes, reusable components and DevOps pipelines trim release cycles noticeably. A focused MVP ships far sooner than a full enterprise platform.
What happens to my software after launch?
Serious providers offer continuous monitoring, security updates and compliance audits as user numbers climb. Andersen, for one, folds maintenance into the full lifecycle rather than bolting it on later.
Is blockchain a must for a modern fintech app?
Not always. Blockchain fits digital assets, DeFi and transparent settlement, yet plenty of strong products run happily on cloud and API architecture without it.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |
August 19, 2026 | NCFA Resource | Cybersecurity And Fraud, Risk Compliance And Regtech, Capital Markets And Market Infrastructure

In August 2026, the Financial Industry Regulatory Authority published Cybersecurity Effective Practices, a 12-part framework for FINRA member firms reviewing cybersecurity programs, controls and operating procedures. A firm can use the resource as a structured checklist for who owns cybersecurity, which systems and vendors create risk, who can access sensitive data, how threats are detected, and whether the business can recover when systems fail. FINRA designed the practices to scale with firm size, business model, technology complexity and risk profile.
FINRA organizes the resource around 12 areas:
The framework starts with accountability and risk ownership. FINRA recommends a designated cybersecurity lead, regular reporting to senior decision makers, documented policies and periodic reviews, while also making cyber risk part of decisions about new technology, systems and operating changes. From there, firms are expected to identify the information, systems and business functions they depend on, assess threats such as ransomware, insider activity and vendor exposure, test important systems for weaknesses and revisit those risks when technology or operations change.
Third party risk receives detailed treatment. FINRA treats vendors with access to customer information or critical systems as part of the firm’s security perimeter. Firms should know which vendors have access, understand important fourth party relationships and identify which providers support critical operations. Contracts can address audit rights, data handling, breach notification and visibility into subcontractors, while ongoing oversight should include access monitoring and a documented process for removing access and handling customer information when a relationship ends.
That concern extends beyond US broker dealers. Weak access control governance can expose sensitive information when a partner or service provider retains permissions that are unnecessary or poorly monitored. FINRA’s guidance connects vendor governance with the practical question of who can access systems and data, for how long, and under what controls.
Asset management and access control fit naturally together. FINRA recommends keeping a current inventory of hardware, software, cloud services and data flows, assigning owners to important assets and identifying systems that no longer receive security updates. Once firms know what they have, they can control who gets access through unique credentials, role based permissions, multifactor authentication, periodic entitlement reviews, segregation of duties and least privilege. Access should also be changed or removed promptly when employees change roles or leave.
Data protection, training and patching cover another part of the operating picture. Firms are encouraged to classify sensitive data, encrypt it at rest and in transit where feasible, control retention and protect backups, including with immutable or air gapped storage. FINRA also recommends ongoing employee training, role specific instruction for staff with sensitive access and phishing simulations backed by records of participation. Vulnerability management should include regular scanning, risk based patch priorities and verification that remediation work was completed rather than assumed.
The primary users are FINRA member broker dealers, including compliance teams, cybersecurity leaders, technology teams, operations executives and senior management. Smaller firms can use the 12 areas to identify where basic controls are missing without trying to copy the cybersecurity program of a much larger institution, while larger firms can use the same structure to review whether responsibilities, documentation and technical controls are working together.
Technology providers, managed security firms, consultants and RegTech companies serving broker dealers can also use the resource to understand what clients may expect around access, logging, vendor controls, data handling, patching, incident response and recovery. Boards and senior executives can use it as a governance checklist because FINRA makes cybersecurity ownership, management reporting, resource decisions and documented risk acceptance part of the program rather than leaving cyber risk entirely with the technology team.
The main strength is that FINRA connects governance directly to operating controls. A firm can follow the framework from senior accountability through asset inventories, identity controls, encryption, training, monitoring and recovery testing, which makes the document more useful than a high level cyber policy statement.
Third party risk is also handled with more depth than a basic checklist. Firms are expected to understand vendor dependencies, monitor privileged access, address fourth parties and plan how systems and data will be handled when a provider relationship ends. Security monitoring extends that discipline to unusual access, suspicious data transfers, system changes and privileged accounts, with logs retained long enough to support operations, investigations, forensic work and applicable recordkeeping requirements.
The framework also includes threat intelligence, incident response and recovery. FINRA recommends using relevant threat feeds, updating defenses as attack methods change and participating in trusted information sharing networks. Incident response focuses on how a firm detects, escalates and contains an event, while recovery planning deals with how critical systems and data return to service afterward. Tested backups, tabletop exercises, offline procedures and defined Recovery Point Objectives and Recovery Time Objectives all help firms decide how much data loss and downtime different systems can tolerate.
The main limitation is jurisdiction. FINRA developed the resource for US member firms and connects several practices to US requirements, including SEC Regulations S-P and S-ID, FINRA Rules 3110 and 4370, and Exchange Act recordkeeping rules. The document also doesn't create new legal or regulatory requirements or reinterpret existing ones. For Canadian financial technology and service firms, its best use is as a practical comparison and control review, not as a statement of Canadian regulatory obligations.
FINRA Cybersecurity Effective Practices (12-part cybersecurity control framework)
Cybersecurity Effective Practices PDF (downloadable nine page resource)
Small Firm Cybersecurity Checklist (small firm program checklist last reviewed February 2024)
Core Cybersecurity Threats And Controls (small firm threats and control questions)
FINRA Cybersecurity Resources (cybersecurity tools, guidance and related material)
2026 Cybersecurity And Cyber Enabled Fraud (current threats and effective practices)
Proposed Class Action Targets Equifax Access Controls (access governance and third party permissions)
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: [www.ncfacanada.org](http://www.ncfacanada.org)
| | |
|---|---|---|
| | |
On August 21, 2026, Canada's founder drain returned to the national debate with a harder number attached to it. The Dominion List, a curated catalogue rather than a census, now tracks 517 U.S.-based companies with a Canadian-linked founder. Together they have raised roughly US$414 billion. About 88% of the founder links include education at a Canadian university, and 56% of the companies are headquartered in San Francisco.
The pace in the list also accelerated during the AI boom. Jesse Rodgers' Barn Ventures analysis counts 60 newly founded U.S. companies with Canadian-linked founders in 2023, 93 in 2024 and 87 in 2025, compared with roughly 20 to 30 a year from 2016 through 2022. The dataset is curated and recent companies may be easier to capture, so it should not be treated as a population estimate. The direction is still difficult to ignore.
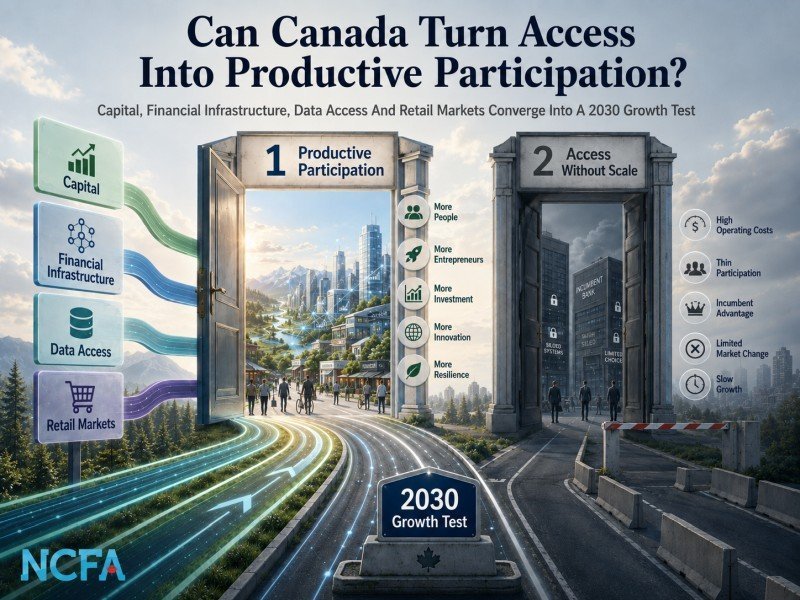
Canada clearly produces ambitious builders. The strategic question is whether enough of them can find the capital, customers, infrastructure, investors and operating density needed to build more of the resulting value here. That makes founder retention part of a wider participation problem, not a standalone brain-drain story.
Canada's problem is not producing ambitious people. It is converting more of that talent into companies, jobs, ownership and follow-on investment that compound inside the Canadian economy.
Capital matters, but so do density, access, customers, infrastructure and the speed of getting from talent to a company with traction. Founder retention makes the wider participation thesis concrete because Canada can create the input and still lose much of the compounding.
The transferable lesson is not a U.S. securities rule. It is the habit of bringing market participants back into the process and testing whether a framework is producing the market it was intended to create.
Canada already has consultations, programs and market data. The harder test is whether each reform produces enough real participation to change who can compete, invest and scale.
Growth VCCI can deepen capital for companies that fit venture mandates. It does not automatically finance every viable manufacturer, service company or local employer whose growth profile, asset base or financing need sits outside institutional venture economics.
Formal access changes who is allowed to participate. Competition changes only when entrants can absorb compliance, technology, integration and operating costs and still build products customers want.
The payoff is not a longer list of fintech entrants. It is more providers controlling enough of their infrastructure and economics to put sustained pressure on incumbents.
Managed access can broaden exposure to private-market returns. Direct access can broaden the number of people deciding which companies receive their money. Both can widen participation, but they create different markets.
If more company value is created while businesses remain private, wider retail access affects more than issuer financing. It influences which households can accept productive risk and participate earlier in private-market returns.
Canada's smaller market does not prove regulation caused weak activity. Issuer quality, investor demand, distribution, awareness, liquidity and platform execution also matter. It does show why market-opening rules should eventually be judged by whether enough issuers, investors and intermediaries can participate economically.
The evidence will be practical. Entrants that survive. Products customers use. Capital reaching different kinds of companies. Investors using managed and direct routes. Smaller institutions offering capabilities once reserved for much larger competitors.
That recycling question is now moving into tax policy. The Bet on Canada campaign, launched in October 2026 by Canadian innovation, venture and professional groups, is calling for stronger incentives to reinvest gains from successful Canadian companies into the next generation of domestic businesses, including broader capital gains rollover treatment.
More viable participants can increase competition. Better competition can improve products, distribution and capital allocation. Better tools and financing can support more investment. Stronger companies can create more opportunities for households and institutions to participate again.
Canada has spent years opening doors. The next phase is finding out which openings create viable markets. That means judging regulation and public programs by the participation, competition and productive activity they generate while preserving the protections that made wider access possible.
Participation is not a complete explanation for Canada's productivity problem. Management capability, commercialization, industrial structure, R&D, domestic demand, risk appetite and global scale all matter. The value of the thesis is that Canada is now opening enough capital, data, payments and investor channels at the same time to test whether participation becomes a measurable growth mechanism.
Talking Point
Canada already produces globally competitive talent and holds deep pools of capital, technology and institutional capacity. The opportunity between now and 2030 is to connect more of those assets before founders, ownership and future value compound somewhere else. If today's reforms create viable participation rather than permission alone, Canada could end the decade with more competitors, more investable companies and more ways for households and institutions to share in productive growth.
The National Crowdfunding & Fintech Association (NCFA Canada) is a financial innovation ecosystem that provides education, market intelligence, industry stewardship, networking and funding opportunities and services to thousands of community members and works closely with industry, government, partners and affiliates to create a vibrant and innovative fintech and funding industry in Canada. Decentralized and distributed, NCFA is engaged with global stakeholders and helps incubate projects and investment in fintech, alternative finance, crowdfunding, peer-to-peer finance, payments, digital assets and tokens, artificial intelligence, blockchain, cryptocurrency, regtech, and insurtech sectors. Join Canada's Fintech & Funding Community today FREE! Or become a contributing member and get perks. For more information, please visit: www.ncfacanada.org
| | |
|---|---|---|
| | |


August 26th, 2025

January 4th, 2024

June 1st, 2021

September 9th, 2020

July 9th, 2018

January 3rd, 2018

September 25th, 2017

June 20th, 2017

May 10th, 2017

December 14th, 2016